
 Methyl Ethyl Ketone (MEK) Market | 2026-2036
Methyl Ethyl Ketone (MEK) Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Ethyl Ketone (MEK) Market Intelligence
Market Context
Capital-intensity divergence between integrated petrochemical giants and regional solvent blenders is bifurcating competitive dynamics in the MEK sector. Sasol leverages its South African coal-to-liquids platform to sustain captive feedstock economics across industrial solvent markets. ExxonMobil Corporation anchors North American supply through integrated refinery operations, while Arkema differentiates via specialty-grade purification for electronics-grade applications.
Technical Definition and Segment Structure
Methyl ethyl ketone is a four-carbon aliphatic ketone with the molecular formula C4H8O, manufactured primarily through the dehydrogenation of secondary butyl alcohol over copper or zinc oxide catalysts at temperatures between 400°C and 500°C. The compound functions as a high-evaporation-rate solvent in coatings, adhesives, and chemical synthesis where fast dry times and strong resin solubility prove critical. Solvents command the largest volume share within product-type segmentation, though coatings applications generate disproportionate margin capture due to specification-grade requirements in automotive OEM finishes. Surface coatings lead application-level demand, while paint strippers represent the fastest-expanding niche as infrastructure refurbishment cycles accelerate in mature industrial economies.
Regulatory Environment
EPA hazardous air pollutant standards and OSHA permissible exposure limits shape workplace handling protocols and ventilation infrastructure investments across US manufacturing facilities. REACH registration requirements in Europe impose full toxicity dossier obligations, while China's MEE enforces provincial VOC emission caps that restrict open-application solvent use in populated zones. Stakeholders must monitor evolving chemical substitution mandates and carbon-border adjustment mechanisms that could reroute cost-competitive supply toward jurisdictions with integrated carbon accounting.
Market Dynamics
China's MEE provincial VOC emission caps are forcing coatings manufacturers to reformulate solvent blends, redirecting procurement toward lower-exposure MEK grades while compressing margins for conventional solvent suppliers.
Growth Catalysts
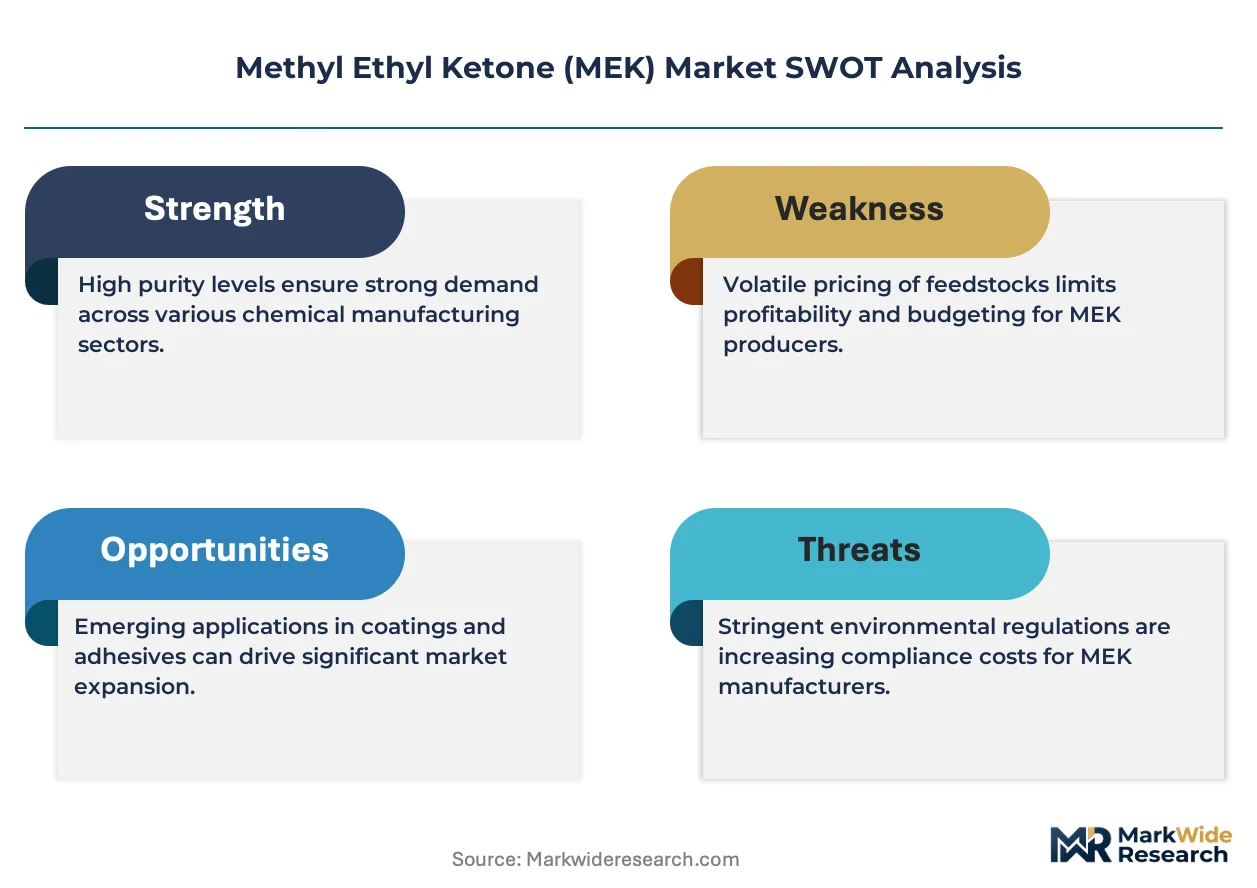
- Marine coatings demand:Shipyard maintenance cycles in South Korea and Japan sustain specification-grade MEK consumption for high-performance anti-corrosive formulations.
- REACH registration completion:Full toxicity dossier acceptance under ECHA enables uninterrupted EU market access for established producers serving adhesives manufacturers.
- Secondary butyl alcohol feedstock expansion:Petrochemical cluster investments in Jiangsu province secure captive dehydrogenation feedstock for integrated MEK-coatings supply chains.
Market Restraints
- Crude oil price volatility:Naphtha-derived feedstock costs swing with Brent crude movements, compressing dehydrogenation unit economics for non-integrated producers.
- Substitution by methyl isobutyl ketone:Paint formulators in automotive OEM finishes increasingly specify MIBK for slower-evaporation lacquer applications.
- EPA hazardous air pollutant standards:Compliance mandates for ventilation infrastructure and emissions monitoring raise fixed costs for US-based coatings operations.
Strategic Opportunities
- Electronics-grade purification:Semiconductor solvent specifications in Taiwan and South Korea create premium pricing tiers for ultra-high-purity MEK distillation capabilities.
- Infrastructure refurbishment cycles:Industrial maintenance spending in Germany and France accelerates paint stripper demand for bridge and machinery recoating programs.
- Direct procurement platforms:Bulk chemical marketplaces are shortening distribution layers between Jiangsu producers and Southeast Asian coatings compounders.
Industry Challenges
- Specialized distillation engineering shortage:Operations teams capable of managing copper-catalyst dehydrogenation at 400-500°C are concentrated among legacy petrochemical workforces.
- Carbon-border adjustment compliance:EU importers must document embedded emissions across secondary butyl alcohol supply chains, complicating procurement from coal-to-liquids sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Ethyl Ketone (MEK) Market |
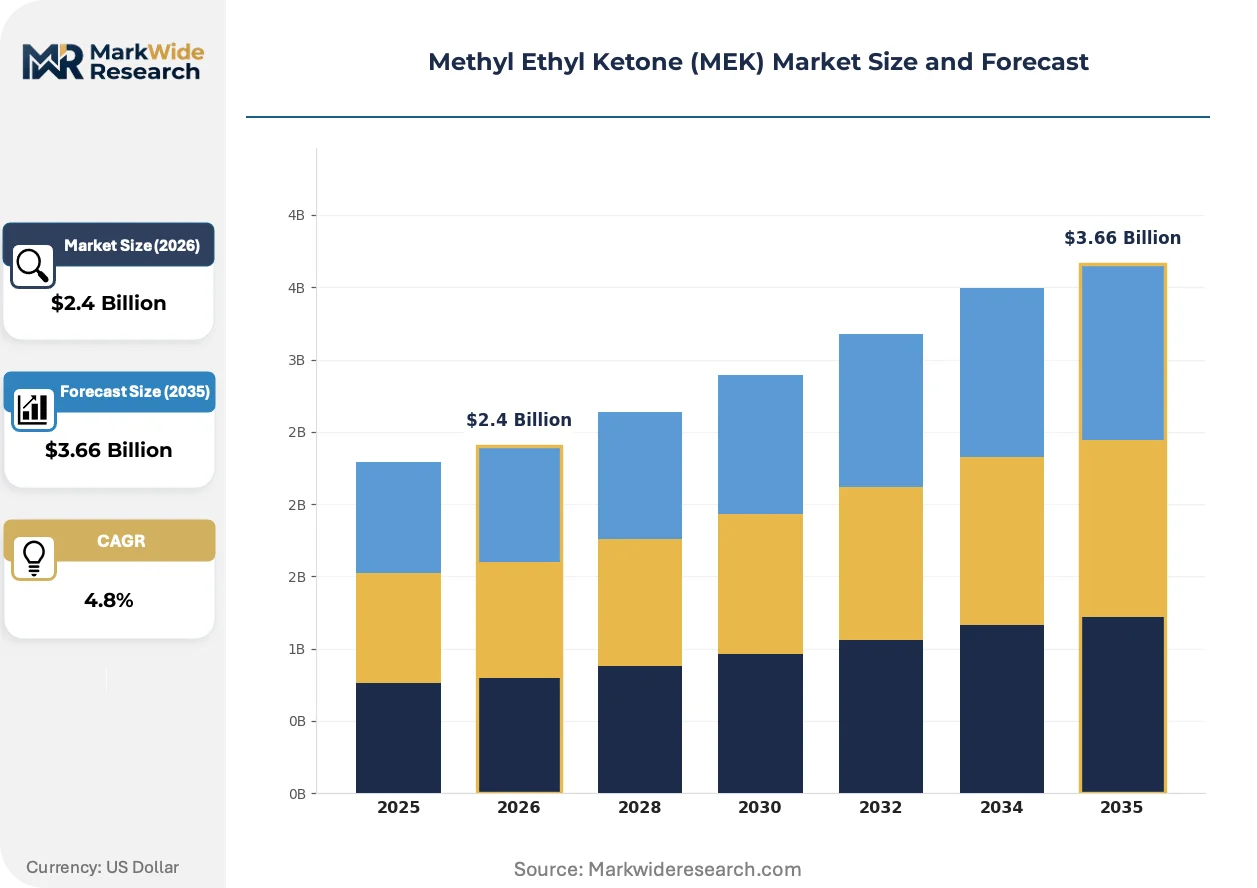
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Adhesives, Coatings, Chemical Intermediates End Use Industry: Automotive, Construction, Electronics, Paints Application: Surface Coatings, Paint Strippers, Printing Inks, Cleaners Packaging Type: Drums, Bulk Containers, Cans, Bottles |
| Companies Covered | Sasol, Idemitsu Kosan Co., Ltd., ExxonMobil Corporation, Nouryon, INEOS, Shell Plc, Maruzen Petrochemical, Celanese, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Ethyl Ketone (MEK) Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are restructuring how MEK is manufactured, purified, and specified across industrial solvent markets.
Membrane separation technology for final-stage MEK purification is displacing conventional azeotropic distillation in electronics-grade production. Semiconductor solvent suppliers in Taiwan and South Korea are retrofitting existing units to capture premium pricing for sub-ppm impurity specifications. This displacement compresses energy consumption per ton while raising technical barriers for commodity producers.
China's MEE enforcement of provincial VOC emission caps is tightening open-application solvent permissions in populated zones. Coatings manufacturers in Shandong and Jiangsu are relocating blending operations to designated chemical industrial parks with centralized treatment infrastructure. Surface coatings applications face the steepest compliance costs, driving consolidation toward integrated petrochemical-coatings complexes.
Long-term supply agreements with fixed volume-price mechanisms are supplanting spot market purchases among large coatings compounders. Procurement teams at marine and industrial maintenance formulators in Japan and South Korea are locking in eighteen to twenty-four month contracts to hedge feedstock volatility. This shift concentrates purchasing power among integrated petrochemical suppliers with captive dehydrogenation capacity.
Methyl Ethyl Ketone (MEK) Market Segmentation
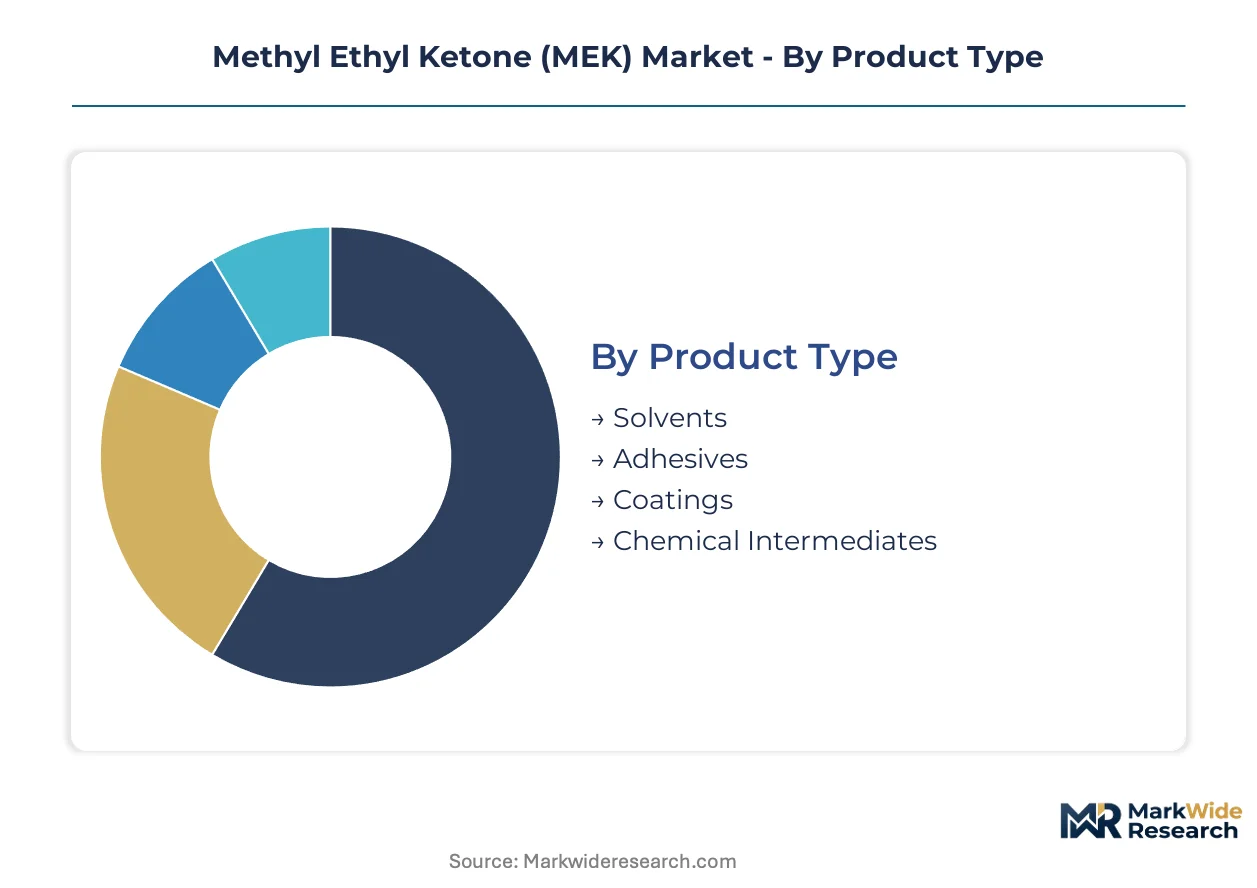
MEK demand fragments across solvent grades, application chemistries, and purity specifications that command divergent margin structures. Substitution pressures from methyl isobutyl ketone and bio-based alternatives concentrate in specific product tiers, reshaping where producers allocate distillation capacity.
Product Type:
Solvent-grade formulations face the sharpest substitution threat as paint formulators reformulate away from high-VOC open applications under tightening emission caps.
- Solvents:Standard-grade MEK serves high-evaporation coating formulations where fast dry times outweigh VOC exposure concerns. Marine maintenance yards in South Korea and Japan sustain specification-grade consumption despite regulatory pressure on open-application use.
- Coatings:Specification-grade solvent systems for automotive OEM finishes command premium pricing through resin compatibility and controlled evaporation profiles. Jiangsu province petrochemical clusters feed integrated supply chains serving marine and industrial anti-corrosive formulations.
- Adhesives:Bonding applications in footwear and flexible packaging rely on MEK's polyurethane solvency for rapid tack development.
- Chemical Intermediates:Synthetic rubber and pharmaceutical precursor manufacturing consumes merchant-grade material with less stringent purity requirements than electronics applications.
Solvents retain volume leadership; Coatings holds the steepest expansion curve.
End Use Industry:
Cost-tier stratification separates specification-grade automotive demand from commodity construction consumption, with electronics purity commanding the widest margin spreads.
- Automotive:OEM lacquer finishes specify slower-evaporation ketone blends, pressuring MEK share in premium coating segments. Tier-1 suppliers in Germany and Japan negotiate long-term supply agreements to lock in dehydrogenation capacity.
- Electronics:Semiconductor solvent specifications in Taiwan and South Korea require sub-ppm impurity thresholds that only membrane-purified grades satisfy. This purity tier captures the widest margin spreads across all end-use categories.
- Construction:Infrastructure refurbishment cycles in France and Germany accelerate paint stripper demand for bridge and machinery recoating programs.
- Paints:Architectural and industrial maintenance formulations concentrate procurement among integrated petrochemical suppliers with captive secondary butyl alcohol feedstock.
Paints commands the largest procurement volumes; Electronics posts the steepest margin expansion.
Application:
Geographic concentration of surface coatings demand in Asia-Pacific chemical industrial parks is restructuring where blending operations locate relative to dehydrogenation capacity.
- Surface Coatings:Marine and industrial maintenance formulations in Shandong province drive specification-grade consumption, though MEE emission caps are forcing relocation to designated chemical parks with centralized treatment infrastructure.
- Paint Strippers:Infrastructure refurbishment in mature industrial economies accelerates demand for high-strength solvent blends that dissolve aged coatings without substrate damage. German bridge maintenance programs represent the most concentrated demand pockets.
- Printing Inks:Flexographic and gravure applications rely on MEK's rapid evaporation for high-speed publication printing.
- Cleaners:Degreasing formulations for metal fabrication and electronics assembly utilize technical-grade material with less stringent purity thresholds than semiconductor solvent specifications.
Surface Coatings dominates procurement tonnage; Paint Strippers is expanding most quickly.
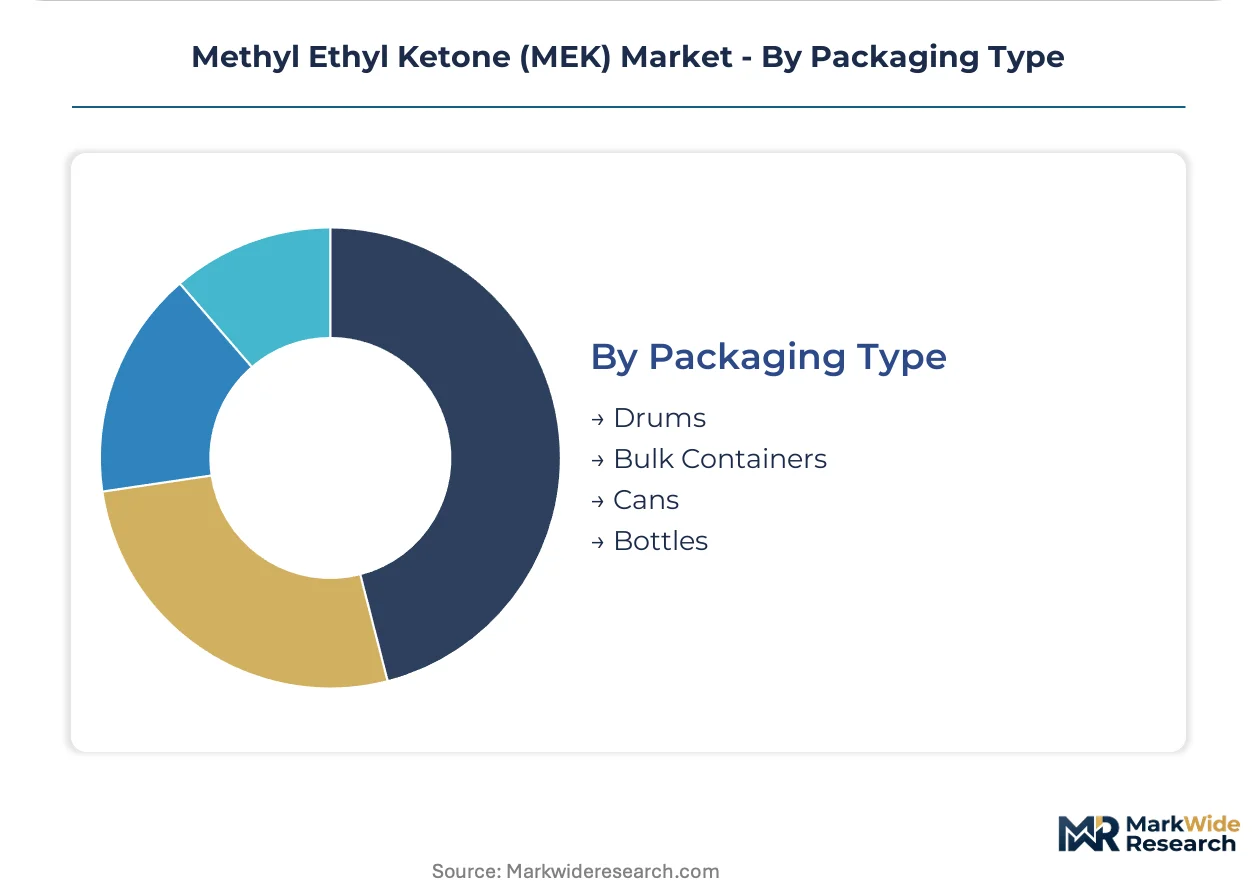
Packaging Type:
Customer-type stratification separates bulk procurement by integrated coatings compounders from drum-scale purchases by regional blenders and maintenance contractors.
- Bulk Containers:Marine coatings manufacturers in Japan and South Korea contract eighteen to twenty-four month supply agreements to hedge feedstock volatility. This packaging tier concentrates purchasing power among producers with captive dehydrogenation capacity.
- Drums:Regional solvent blenders and industrial maintenance contractors procure standard-grade material in intermediate volumes that bypass long-term contract structures.
- Cans:Specialty distributors serve small-scale automotive refinishing and electronics assembly operations with just-in-time replenishment.
- Bottles:Laboratory and pilot-scale chemical synthesis operations require analytical-grade packaging with contamination controls.
Bulk Containers anchors procurement volumes; Drums shows the fastest volume climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward net-import dependence in Western markets while integrated Asian producers capture growing outbound shipment volumes. China's Jiangsu and Shandong petrochemical clusters now supply coating-grade material to Southeast Asian compounders at freight-advantaged rates. European formulators face mounting feedstock cost pressure as dehydrogenation capacity concentrates in coal-to-liquids and naphtha-cracking corridors.
China
Marine coatings demand from South Korean shipyards sustains specification-grade consumption through Jiangsu province export channels. MEE provincial VOC emission caps are forcing Shandong blenders to relocate operations to designated chemical industrial parks with centralized treatment infrastructure. The Yangtze River Delta petrochemical corridor feeds integrated MEK-coatings supply chains serving domestic automotive OEM finish requirements.
South Korea
Semiconductor solvent specifications in Hsinchu and Taichung drive ultra-high-purity procurement from membrane-purification facilities in the Busan-Ulsan corridor. METI-aligned industrial standards shape specification-grade requirements for marine maintenance yards in Geoje and Ulsan. The Daegu-Gyeongbuk region hosts dehydrogenation capacity serving both domestic electronics-grade demand and export shipments to Japanese coatings compounders.
United States
Gulf Coast refinery-integrated producers supply marine coatings manufacturers in Pascagoula and Newport News through captive secondary butyl alcohol feedstock economics. EPA hazardous air pollutant standards mandate ventilation infrastructure investments that raise fixed costs for coatings operations in Ohio and Michigan industrial corridors. The Texas-Louisiana chemical corridor anchors North American dehydrogenation capacity serving automotive OEM finish specifications.
Germany
Infrastructure refurbishment cycles for bridge maintenance programs in North Rhine-Westphalia accelerate paint stripper demand from industrial maintenance contractors. REACH registration requirements under ECHA impose full toxicity dossier obligations that filter commodity suppliers from specification-grade procurement channels. The BASF-Ludwigshafen chemical complex maintains integrated solvent supply relationships with automotive tier-1 suppliers in Baden-Württemberg.
Japan
Long-term supply agreements with fixed volume-price mechanisms dominate procurement at marine coatings formulators in Nagasaki and Kure shipyards. JIS standards for industrial solvent specifications create technical barriers for non-integrated importers serving Kansai region electronics assemblers. The Chubu-Nagoya corridor concentrates polyurethane adhesive manufacturing that relies on MEK's rapid tack development properties.
Methyl Ethyl Ketone (MEK) Market Key Industry Players
Concentration sits with integrated petrochemical conglomerates possessing captive secondary butyl alcohol feedstock and refinery-integrated dehydrogenation assets. Regional solvent blenders without upstream control face margin compression during naphtha price volatility cycles. Two strategic archetypes dominate: coal-to-liquids platforms leveraging synthetic feedstock economics, and refinery-integrated operators capturing scale advantages in commodity solvent markets. Competitive moves center on long-term supply agreement structures and electronics-grade purification capability investments.
Among integrated petrochemical operators, Sasol exemplifies the coal-to-liquids archetype with South African synthetic feedstock integration, while ExxonMobil Corporation anchors refinery-integrated supply positioning in North American markets. Arkema occupies the specialty-grade purification tier, serving semiconductor solvent specifications that command premium pricing tiers. These three entities represent the structural spectrum from commodity scale to specification-grade differentiation.
| Leading Market Players |
|---|
| Sasol |
| Idemitsu Kosan Co., Ltd. |
| ExxonMobil Corporation |
| Nouryon |
| INEOS |
| Shell Plc |
| Maruzen Petrochemical |
| Celanese |
| Arkema |
| Others |
Cost & Logistics Intelligence
Dehydrogenation unit scale economies at Jiangsu and Shandong petrochemical clusters compress per-ton fixed costs and establish price floors that regional blenders cannot match without captive secondary butyl alcohol feedstock. This concentration of integrated capacity concentrates pricing power among coal-to-liquids and refinery-integrated operators while forcing merchant buyers into long-term offtake structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing with eighteen to twenty-four month volume commitments that hedge naphtha feedstock volatility. Price differentiation separates membrane-purified electronics grades from standard solvent formulations based on impurity thresholds and certification compliance. Cost compression in commodity solvent tiers is intensifying because paint formulators reformulate toward methyl isobutyl ketone for automotive lacquer applications. Regional solvent blenders without upstream integration exhibit the highest price sensitivity, while semiconductor solvent procurement in Taiwan and South Korea demonstrates the lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement at marine coatings manufacturers in Japan and South Korea, who maintain buffer inventories against freight disruption from Jiangsu export channels. Supply concentrates in China, South Korea, and the United States, with dehydrogenation capacity tethered to naphtha-cracking and coal-to-liquids corridors. Secondary butyl alcohol, copper catalysts, and zinc oxide feed the manufacturing process, with single-source vulnerability concentrated in catalyst supply chains. Distribution runs through bulk chemical marketplaces that shorten layers between Jiangsu producers and Southeast Asian compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine maintenance cycle recovery in South Korean and Japanese shipyards is restoring specification-grade consumption volumes after period contraction. This cyclical upturn rewards producers with locked-in dehydrogenation capacity and electronics-grade purification capabilities.
For Market Incumbents: Consolidate long-term supply agreement structures with coatings compounders to defend share against methyl isobutyl ketone substitution in automotive OEM finishes. Prioritize backward integration into secondary butyl alcohol production in Jiangsu province to secure captive feedstock economics against naphtha price swings.
For New Entrants and Emerging Players: Lead with electronics-grade membrane purification capabilities targeting semiconductor solvent specifications in Taiwan and South Korea, where sub-ppm impurity thresholds create technical barriers for commodity producers. Establish direct procurement platforms that bypass traditional distribution layers serving Southeast Asian coatings compounders.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated petrochemical operators with coal-to-liquids or refinery-anchored dehydrogenation assets and existing REACH registration dossiers. Monitor carbon-border adjustment mechanism implementation as the inflection indicator that would reroute cost-competitive supply toward jurisdictions with integrated carbon accounting.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Butyl Alcohol | Jiangsu petrochemical clusters secure captive feedstock economics against naphtha volatility. |
| Electronics-Grade Membrane Purification Investment | Taiwan semiconductor foundries demand sub-ppm impurity thresholds unavailable from commodity producers. |
| Long-Term Supply Agreement Restructuring | Marine coatings manufacturers in Japan lock in eighteen-month volume commitments to hedge price swings. |
| REACH Registration Dossier Completion | ECHA acceptance filters commodity suppliers from EU specification-grade procurement channels. |
| Direct Procurement Platform Development | Bulk chemical marketplaces shorten distribution layers between Shandong producers and Southeast Asian compounders. |
Research Approach
Initial hypotheses were tested against primary input from plant managers at dehydrogenation facilities, procurement leads at marine coatings OEMs, distribution channel partners in the Yangtze River Delta, and technical R&D directors specializing in solvent purification, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical operators, and MEE regulatory enforcement records. Bottom-up capacity assessments and top-down demand modeling were triangulated to validate segment-level projections.
Variance decomposition across the projection horizon isolates volume drivers by grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from modeled segment trajectories incorporating secondary butyl alcohol feedstock expansion timelines, MEE provincial VOC cap enforcement schedules, and semiconductor fabrication capacity buildouts in Taiwan and South Korea.
Underlying assumptions cover sustained marine maintenance spending cycles, REACH dossier acceptance continuity, and naphtha-crack spread stability, with deviation risk concentrated in carbon-border adjustment implementation timing and methyl isobutyl ketone substitution acceleration. Revision becomes warranted when MEE enforcement intensity crosses thresholds that force coatings operation relocation beyond designated chemical industrial park capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
North America Toluene Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Global Solvents Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Methyl Undecylenate Market
Solvents
Isoamylene Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Diethanolamide Market
Solvents
Monochlorobenzene Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Acetone Market
Solvents
Global Xylenols Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Butyl Acetate (BAC) Market