
 4-Tert-Amylphenol Market | 2026-2036
4-Tert-Amylphenol Market Size, Share, and Industry Trends Forecast 2026-2036
4-Tert-Amylphenol Market Outlook
Phenolic antioxidants are consolidating their role in stabilizing synthetic rubber and adhesive formulations against thermal degradation. SI Group leverages captive cumene and phenol assets to secure backward integration into alkylation feedstocks. Sasol Limited anchors its position through South African coal-to-chemicals infrastructure that supplies branched olefin precursors. Lanxess AG differentiates via controlled hydrogenation technology that tightens isomer specificity in tert-amyl phenol output.
4-Tert-Amylphenol is an alkylated phenol with a tert-amyl substituent at the para position, typically produced through acid-catalyzed alkylation of phenol with isoamylene and used primarily as an antioxidant intermediate and polymer stabilizer. Industrial grade material dominates volume flows into chemical manufacturing and rubber compounding, where cost sensitivity outweighs purity premiums. Laboratory grade and pharmaceutical grade segments command narrower specifications and higher unit margins, serving analytical reagent and active pharmaceutical ingredient synthesis channels respectively.
EPA oversight of phenolic compound emissions shapes plant siting and abatement investment for US-based producers, while REACH registration requirements in Europe constrain non-compliant import volumes. FDA indirect food additive regulations govern pharmaceutical grade and food grade pathways when downstream applications contact consumables. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as phenolic antioxidant alternatives gain scrutiny in fluoropolymer replacement formulations.
Market Dynamics
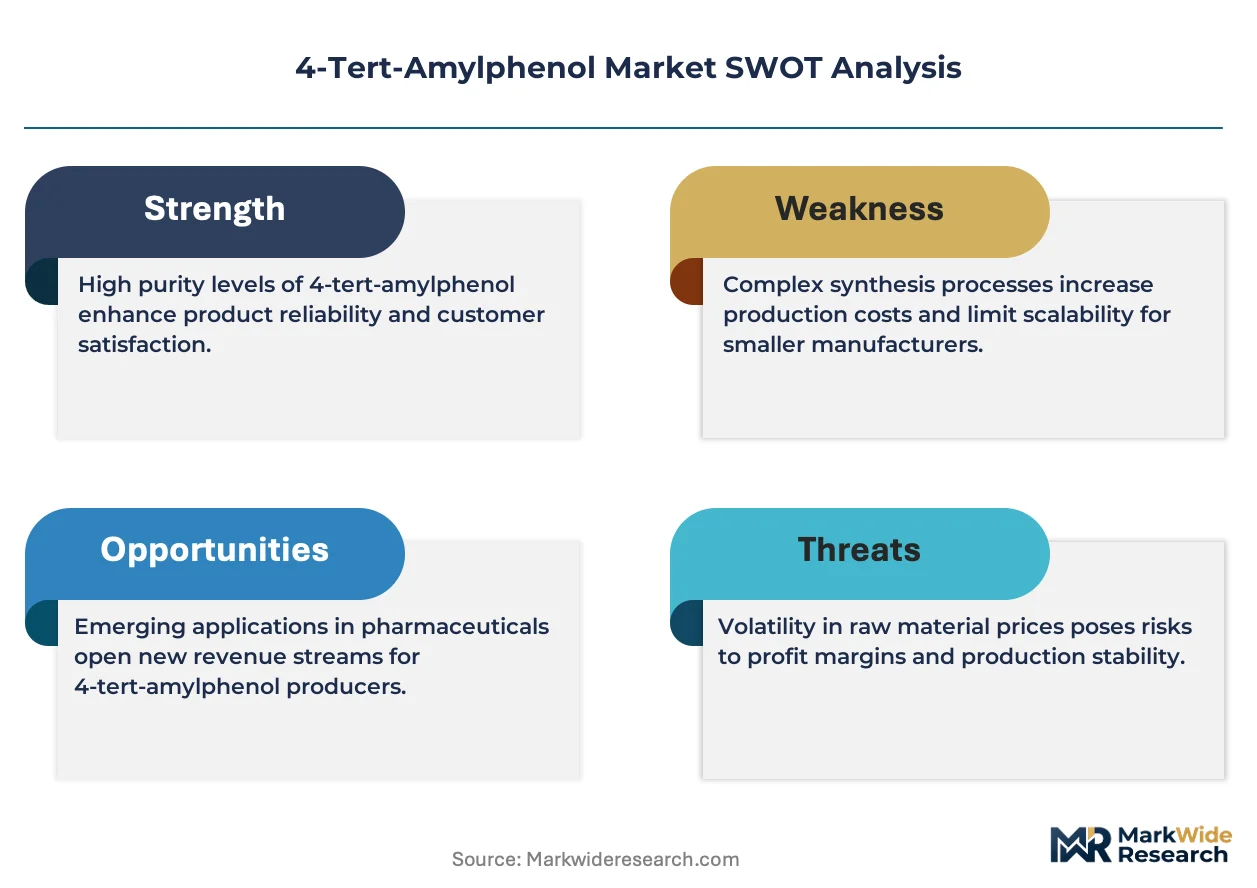
REACH compliance in Europe is tightening purity specifications for chemical intermediates used in consumer-facing products, forcing producers to upgrade hydrogenation controls and isomer separation capabilities. This regulatory compression is reshaping capital allocation across the tert-amylphenol value chain.
Growth Catalysts
- Coatings formulator demand:North American coatings producers are expanding antioxidant purchases for high-performance resin formulations. This end-use pull is absorbing incremental industrial-grade capacity.
- Dual carbon goals:China's domestic alkyl phenol infrastructure supports localized derivatives output, reducing import dependency for polymer stabilizer manufacturers.
- FDA indirect food additive pathways:Pharmaceutical grade certification is opening food-contact applications, creating margin expansion for compliant producers.
Market Restraints
- Isoamylene feedstock volatility:Branched olefin precursor costs fluctuate with coal-to-chemicals output from South African synthetic fuel complexes.
- EPA emissions abatement:Phenolic compound oversight requires scrubber investments that extend payback periods for US-based alkylation assets.
- Fluoropolymer substitution scrutiny:Per- and polyfluoroalkyl substance restrictions are diverting R&D budgets toward unproven antioxidant alternatives.
Strategic Opportunities
- Analytical reagent channel:Laboratory grade specifications remain underpenetrated in India's specialty chemical import market.
- Controlled hydrogenation licensing:Technology convergence between catalytic alkylation and membrane separation is enabling tighter isomer specificity.
- EU Green Deal chemical leasing:Servitization models for antioxidant intermediates are reducing working capital burdens for SME formulators.
Industry Challenges
- Alkylation catalyst expertise:Acid-catalyzed process optimization requires scarce petrochemical engineering talent familiar with phenol handling protocols.
- REACH registration timelines:Extended dossier preparation periods are delaying market entry for non-EU producers seeking consumer-facing product access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Tert-Amylphenol Market |
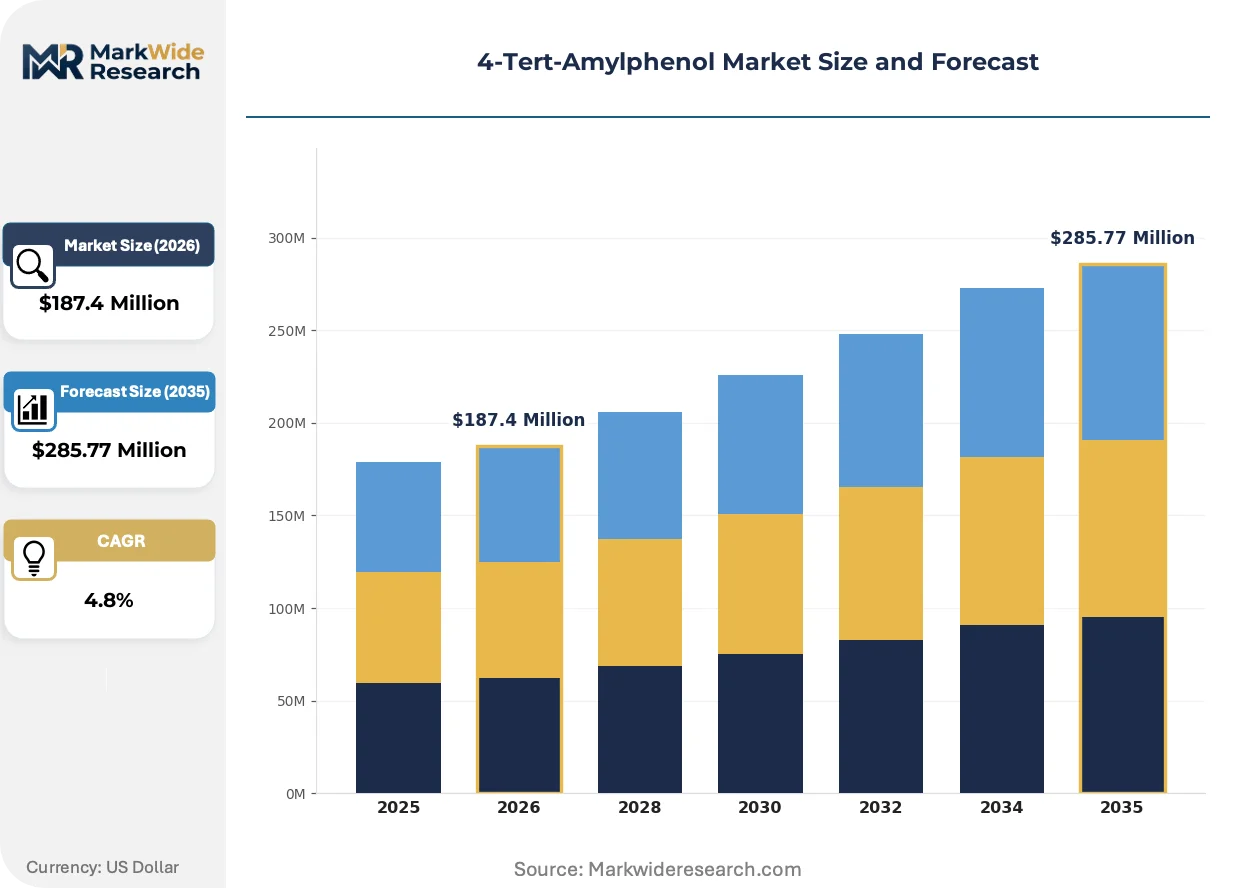
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Pharmaceutical Grade, Food Grade Application: Chemical Manufacturing, Adhesives, Coatings, Additives End User: Chemical Industry, Paints & Coatings, Pharmaceuticals, Food Industry Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | SI Group, Sasol Limited, Lanxess AG, DeLong Chemicals America, Penta Manufacturing Company, Tokyo Chemical Industry Co. Ltd., BOC Sciences, Henan Coreychem Co., Ltd., Santa Cruz Biotechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Tert-Amylphenol Market Strategic Shifts
Process intensification and regulatory precision are converging to reshape how tert-amylphenol producers compete on specification breadth rather than volume scale alone.
Membrane-assisted reactive distillation is expanding into phenol alkylation trains, enabling simultaneous reaction and separation that cuts energy intensity. Specialty chemical producers in Germany and Japan are retrofitting existing cumene-phenol complexes with these hybrid units. The technology is expanding into mid-tier producers who previously lacked capital for standalone hydrogenation investments.
REACH Article 33 disclosure obligations are forcing downstream formulators to document substance-of-very-high-concern content in antioxidant blends. This transparency mandate is compressing supply chains toward certified producers with full registration dossiers. Coatings manufacturers in France and the Netherlands are consolidating purchases with REACH-registered suppliers to avoid downstream liability.
Specification-driven procurement is consolidating buyer pools around pharmaceutical-grade certified producers, displacing spot-market industrial-grade transactions. Large rubber compounders in China are implementing vendor qualification programs that require dual-grade production capability. This preference shift is most visible in tire manufacturing hubs around Shanghai and Qingdao, where OEM supply agreements mandate full certification traceability.
4-Tert-Amylphenol Market Segmentation
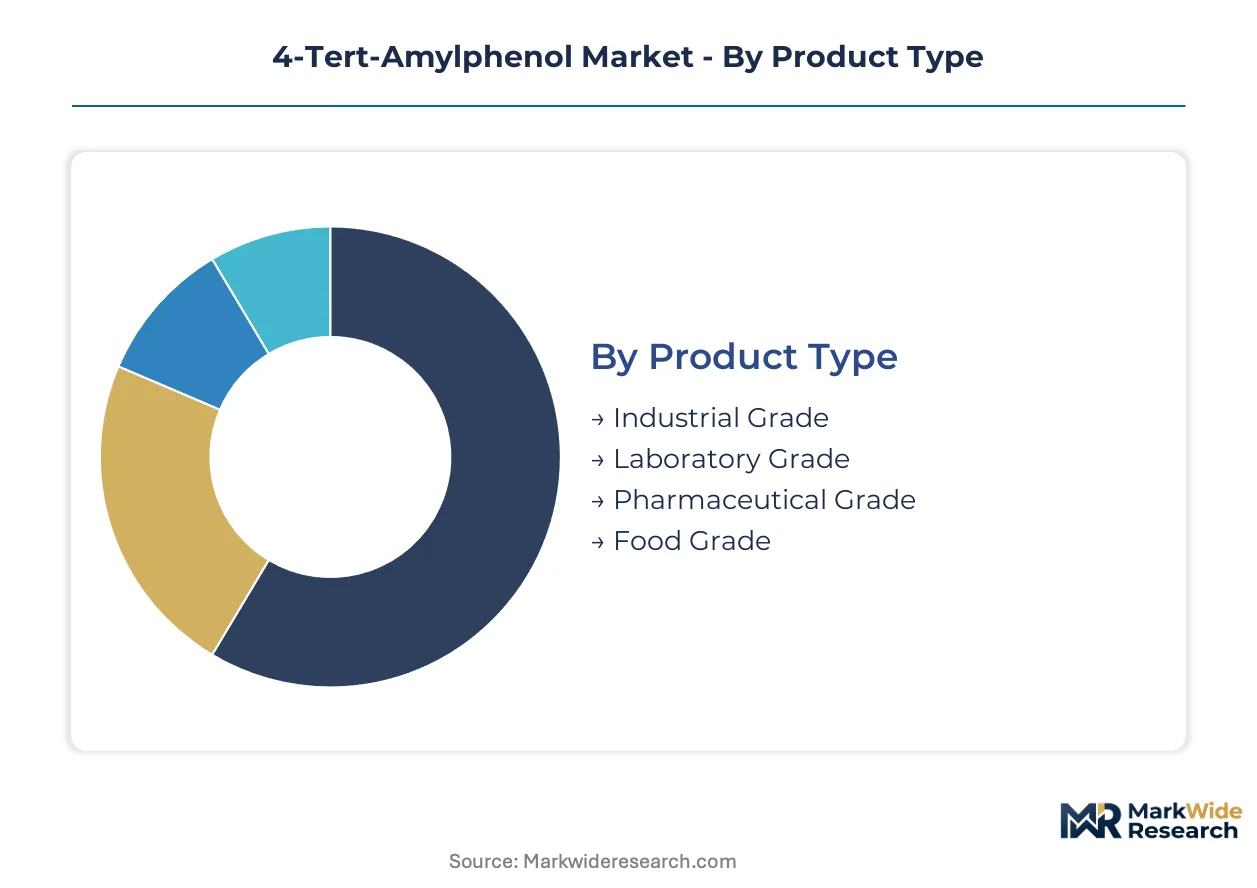
Segmentation in 4-tert-amylphenol markets separates volume-scale commodity flows from specification-driven premium tiers. Producers allocate capital across hydrogenation trains and purification skids based on grade-specific margin structures.
Product Type:
Capital intensity escalates sharply with purity thresholds, as pharmaceutical-grade hydrogenation requires dedicated catalyst beds and isomer separation trains.
- Industrial Grade:Standard alkylation output serves rubber compounding and bulk chemical synthesis where phenol content tolerances remain broad. Chinese tire manufacturers around Qingdao absorb the majority of global volume, prioritizing cost position over isomer specificity.
- Pharmaceutical Grade:Controlled hydrogenation achieves tight para-isomer selectivity for FDA-regulated active pharmaceutical ingredient pathways. Lanxess AG leverages membrane separation technology to secure certification for indirect food additive applications.
- Laboratory Grade:Analytical reagent specifications demand sub-ppm impurity profiles for chromatography standards and reference material production.
- Food Grade:Compliance with FDA indirect food additive regulations governs antioxidant use in packaging and processing equipment contact surfaces.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
End-use pull concentrates in formulations requiring thermal stabilization against oxidative degradation.
- Chemical Manufacturing:Intermediate consumption for phenolic resin synthesis and alkyl phenol derivative production dominates tonnage flows. Sasol Limited supplies branched olefin precursors from coal-to-chemicals infrastructure to polymer stabilizer manufacturers.
- Coatings:High-performance resin formulations in North American automotive and industrial finishes drive antioxidant specification tightening. SI Group integrates captive cumene-phenol assets to secure backward integration into alkylation feedstocks.
- Adhesives:Synthetic rubber stabilization in pressure-sensitive and structural adhesive compounds requires consistent phenolic antioxidant performance.
- Additives:Lubricant and fuel additive applications leverage tert-amylphenol alkoxylation derivatives for detergent and dispersant functionality.
Chemical manufacturing commands the largest share of volume throughput; coatings application is climbing the fastest on specification premium capture.
End User:
Customer concentration patterns reflect downstream industry consolidation and vertical integration strategies.
- Chemical Industry:Bulk intermediate demand from phenolic resin and specialty chemical producers anchors baseline capacity utilization. REACH-registered suppliers in Germany consolidate supply relationships with formulators seeking Article 33 disclosure compliance.
- Paints & Coatings:Automotive OEM qualification programs mandate full certification traceability from antioxidant suppliers. French and Dutch coatings manufacturers are consolidating purchases with REACH-registered suppliers to avoid downstream liability.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and excipient applications require pharmaceutical-grade certification with full dossier documentation.
- Food Industry:Indirect food additive pathways for packaging antioxidants and processing equipment stabilizers operate under FDA regulatory oversight.
Chemical industry end users represent the dominant demand pool; pharmaceuticals segment shows the steepest expansion trajectory on grade premium realization.
Distribution Channel:
Channel selection balances working capital efficiency against technical service requirements for specification-sensitive grades.
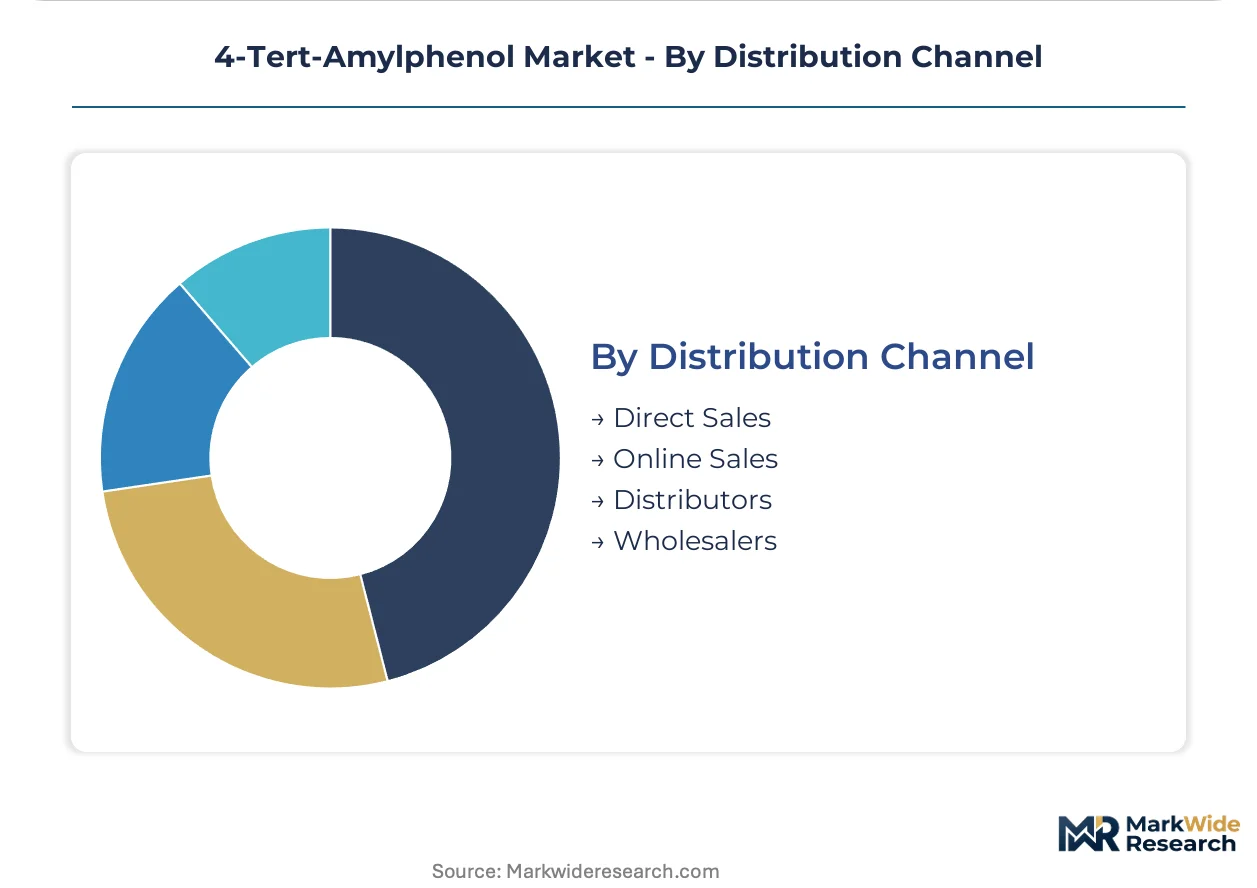
- Direct Sales:Large-volume contracts with rubber compounders and coatings formulators eliminate distributor margins and enable technical collaboration on formulation optimization. Chinese domestic alkyl phenol infrastructure supports localized derivatives output through direct supply relationships.
- Distributors:Specialty chemical distributors in India and Southeast Asia provide market access for laboratory and pharmaceutical grade penetration into underpenetrated import markets.
- Online Sales:E-procurement platforms serve small-laboratory and research-scale customers with standardized industrial and laboratory grade offerings.
- Wholesalers:Bulk commodity flows for industrial grade material leverage wholesaler networks in regions with fragmented end-user bases.
Direct sales channel captures the majority of value throughput; distributor channel is gaining share fastest in emerging import markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's chemical industry parks attract tert-amylphenol producers through preferential tax treatment and streamlined environmental permitting. These zones concentrate alkylation capacity near Qingdao's tire manufacturing clusters.
China
Domestic alkyl phenol infrastructure supports localized derivatives output for polymer stabilizer manufacturers. MIIT's dual carbon goals pressure Shandong producers to retrofit coal-fired boilers with natural gas systems. Qingdao and Shanghai tire hubs implement vendor qualification programs requiring full certification traceability from antioxidant suppliers.
United States
Coatings formulators in Michigan and Ohio expand antioxidant purchases for automotive resin formulations. EPA emissions abatement rules extend payback periods for Gulf Coast alkylation assets requiring scrubber investments. Houston's petrochemical corridor anchors backward integration into cumene-phenol feedstocks for antioxidant intermediate production.
Germany
REACH-registered suppliers consolidate supply relationships with formulators seeking Article 33 disclosure compliance. ECHA's tightening purity specifications force hydrogenation control upgrades at Ludwigshafen and Leverkusen chemical complexes. BASF's neighboring specialty chemical producers leverage membrane separation technology for isomer-specific tert-amylphenol output.
India
Specialty chemical distributors provide market access for laboratory and pharmaceutical grade penetration into underpenetrated import markets. CDSCO's active pharmaceutical ingredient regulations constrain non-compliant antioxidant intermediate volumes. Maharashtra's Mumbai-Pune industrial belt attracts import substitution investments for rubber compounding chemical manufacturing.
South Africa
Coal-to-chemicals infrastructure supplies branched olefin precursors to polymer stabilizer manufacturers across sub-Saharan Africa. SAMR-equivalent industrial chemical standards create export documentation burdens for Secunda synthetic fuel complex output. Sasol's captive isoamylene production anchors regional feedstock security for alkylation derivatives.
4-Tert-Amylphenol Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with industrial-grade volumes concentrating around backward-integrated petrochemical players while pharmaceutical-grade certification favors hydrogenation technology owners. The vendor base organizes into three archetypes: captive feedstock operators controlling cumene-phenol assets, technology licensors monetizing controlled hydrogenation patents, and regional distributors arbitraging import specifications. M&A activity targets REACH registration dossiers as transferable compliance assets, while capacity expansion concentrates in Shandong chemical parks with integrated environmental permitting.
Among integrated petrochemical operators, SI Group exemplifies captive feedstock control through cumene-phenol asset ownership, while Sasol Limited anchors the coal-to-chemicals archetype with branched olefin precursor security. Lanxess AG occupies the technology-differentiated tier, representing hydrogenation specialization for isomer-specific output. These three patterns—backward integration, synfuel feedstock anchoring, and catalytic process licensing—define competitive positioning across industrial and specification-grade market layers.
| Leading Market Players |
|---|
| SI Group |
| Sasol Limited |
| Lanxess AG |
| DeLong Chemicals America |
| Penta Manufacturing Company |
| Tokyo Chemical Industry Co. Ltd. |
| BOC Sciences |
| Henan Coreychem Co., Ltd. |
| Santa Cruz Biotechnology, Inc. |
| Others |
Value Chain & Pricing Dynamics
Isoamylene spot price volatility cascades through tert-amylphenol value chains into three distinct pricing tiers: pharmaceutical-grade contracts indexed to coal-to-chemicals output from South Africa, industrial-grade spot purchases absorbing Shandong alkylation overcapacity, and laboratory-grade imports arbitraging India's distributor markups. Buyers in Qingdao tire clusters leverage direct procurement to compress distributor margins, while REACH-registered European suppliers command certification premiums from coatings formulators seeking Article 33 disclosure compliance.
Pricing Analysis
Short lead-time premiums separate contract pharmaceutical-grade volumes from spot industrial-grade transactions. Three-tier pricing structure across pharmaceutical, industrial, and laboratory levels reflects hydrogenation intensity and isomer specificity thresholds. Cost compression in industrial grade is intensifying because Shandong capacity additions outpace Qingdao rubber compounding absorption. Tire manufacturers demonstrate highest price sensitivity; FDA-certified pharmaceutical buyers exhibit lowest elasticity due to qualification lock-in costs.
Supply Chain Analysis
China's domestic-content mandates under MIIT dual carbon goals are reshaping sourcing patterns for polymer stabilizer manufacturers. Feedstock security draws from South African coal-to-chemicals complexes, US Gulf Coast cumene-phenol infrastructure, and German membrane-separation hydrogenation trains. Single-source vulnerability concentrates in branched olefin precursor flows from Secunda synthetic fuel complexes. Distribution runs through direct sales contracts with large rubber compounders, bypassing distributor layers for industrial-grade tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH-registered producers as extended dossier preparation timelines force non-compliant importers into distributor arbitrage roles. Regulatory compression eliminates marginal alkylation operators lacking hydrogenation control investments.
For Market Incumbents: Anchor feedstock security through captive cumene-phenol assets or long-term isoamylene offtake agreements with South African synthetic fuel producers. Upgrade membrane separation capabilities to tighten para-isomer selectivity ahead of ECHA purity specification tightening. Defend against Chinese domestic alkyl phenol capacity expansion by locking automotive OEM qualification programs with full certification traceability. For New Entrants and Emerging Players: Enter via laboratory-grade distribution partnerships in India's Mumbai-Pune industrial belt, where CDSCO regulatory constraints have suppressed compliant import volumes. Target pharmaceutical-grade certification for indirect food additive pathways, the least penetrated tier with highest margin capture. Pursue technology licensing arrangements with German hydrogenation specialists rather than greenfield alkylation investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor REACH-registered mid-cap producers in Germany with transferable compliance dossiers and idle hydrogenation capacity. Long-term viability hinges on positioning for fluoropolymer substitution demand as phenolic antioxidant alternatives gain formulation trials. Watch for inflection in OEM tire supply agreements mandating dual-grade production capability as the signal for specification-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene-Phenol Feedstocks | SI Group leverages captive assets to secure alkylation input cost position against isoamylene volatility. |
| Controlled Hydrogenation Technology Licensing | Lanxess AG monetizes membrane separation patents for para-isomer specificity in pharmaceutical-grade output. |
| REACH Registration Dossier Acquisition | Transferable compliance assets accelerate market entry for non-EU producers seeking consumer-facing product access. |
| Coal-to-Chemicals Capacity Expansion | Sasol Limited anchors regional feedstock security for branched olefin precursor supply across sub-Saharan Africa. |
| Laboratory-Grade Distribution Partnership | Specialty chemical distributors in India provide market access for analytical reagent specification penetration. |
Study Parameters
Document review covered customs and trade flow databases, ECHA registration dossiers, and SEC filings from listed chemical producers, complemented by interviews with plant managers at Shandong alkylation facilities, procurement leads at Qingdao tire manufacturers, and technical R&D directors at coatings formulators. Secondary validation drew from MIIT dual carbon policy disclosures, EPA emissions enforcement records, and CDSCO active pharmaceutical ingredient regulations. Bottom-up capacity assessments triangulated against top-down end-use consumption estimates across rubber compounding, coatings, and pharmaceutical synthesis channels.
Historical volume trajectories cross-referenced against panel input from industry stakeholders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier (industrial, pharmaceutical, laboratory, food), end-use industry (chemical manufacturing, coatings, adhesives, additives), and regional production hub (China, United States, Germany, India, South Africa). CAGRs derived from weighted average of historical trend extrapolation and demand elasticity estimates for antioxidant intermediate substitution in fluoropolymer replacement formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH specification tightening or sudden isoamylene feedstock disruption from South African synthetic fuel complex operational issues. Forecasts reflect documented assumptions regarding dual carbon policy implementation pace and OEM qualification program adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Aminophenol Market