
 Soy Chemicals Market | 2026-2036
Soy Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Chemicals Market Analysis
Midwestern soybean processing corridors in the United States are restructuring supply chains to serve expanding oleochemical demand. Cargill leverages its crush-and-refine infrastructure to anchor downstream chemical output. Archer Daniels Midland sustains origination density across the Farm Belt, while Bunge Limited competes through port-advantaged export logistics.
Soy chemicals encompass derivatives extracted from Glycine max, including refined oils, protein isolates, lecithin fractions, and hydrogenated waxes, produced via solvent extraction, mechanical pressing, or enzymatic fractionation for industrial formulation. Soybean oil dominates value capture in biodiesel and lubricant applications, while soy lecithin occupies narrower but higher-margin positions in food emulsification and pharmaceutical delivery systems. Soy wax differentiates within personal care and candle manufacturing as petroleum paraffin displacement accelerates.
The EPA Renewable Fuel Standard and EU Renewable Energy Directive II shape feedstock qualification and lifecycle carbon accounting for soy-derived materials. REACH registration requirements in Europe and FDA food-contact regulations in the United States constrain formulation chemistry and import pathways. Stakeholders must monitor evolving bio-based content mandates and carbon-border adjustment mechanisms to align capacity investments with compliance thresholds.
Market Dynamics
Biodiesel offtake contracts are restructuring soybean oil flow patterns, pulling crush capacity toward chemical conversion corridors and compressing traditional food-grade refining margins.
Growth Catalysts
- EU Renewable Energy Directive II:Binding bio-based content thresholds for transport fuels are redirecting European oleochemical investment toward soy-derived feedstocks. Chemical manufacturers in Germany and the Netherlands are expanding hydrogenation capacity to meet certified sustainable supply requirements.
- Petroleum paraffin displacement:Candle and personal care formulators are switching to hydrogenated soy wax as carbon accounting pressures intensify. Midwestern processors are retrofitting refineries to produce technical-grade wax fractions.
- Enzymatic fractionation advances:Novel protease and lipase systems are yielding higher-purity lecithin and protein isolates for pharmaceutical delivery applications. Biotechnology firms are licensing these processes to soybean processors.
Market Restraints
- Crude oil price volatility:Soybean oil competes directly with mineral oil derivatives in lubricant and surfactant markets. Price swings in Brent crude compress bio-based margin premiums unpredictably.
- Argentina-Paraguay supply concentration:South American crushing capacity dominates exportable soy oil volumes. Weather disruptions or export tax shifts in these jurisdictions transmit immediate price shocks.
- REACH registration complexity:Novel soy-derived chemical intermediates face multi-year toxicity dossier requirements. European market entry timelines extend accordingly.
Strategic Opportunities
- India industrial surfactant demand:Local detergent and agrochemical formulators seek domestic oleochemical feedstocks to reduce palm oil import dependence. Soy-based alternatives penetrate this procurement pivot.
- Bioplastics monomer supply:Polyol and polyurethane producers require non-petroleum polyols for automotive interior applications. Soy-based polyols align with OEM sustainability scorecards.
- US Inflation Reduction Act biofuel credits:Section 45Q and clean fuel production incentives expand qualifying feedstock categories. Soybean oil processors capture additional margin through tax credit stacking.
Industry Challenges
- Process chemist scarcity:Oleochemical conversion requires expertise in lipid hydrogenation and epoxidation that conventional food-oil refining does not cultivate. Technical hiring lags capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact, EPA fuel pathway, and REACH chemical registrations demand dedicated regulatory affairs capacity. Smaller processors struggle with compliance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Chemicals Market |
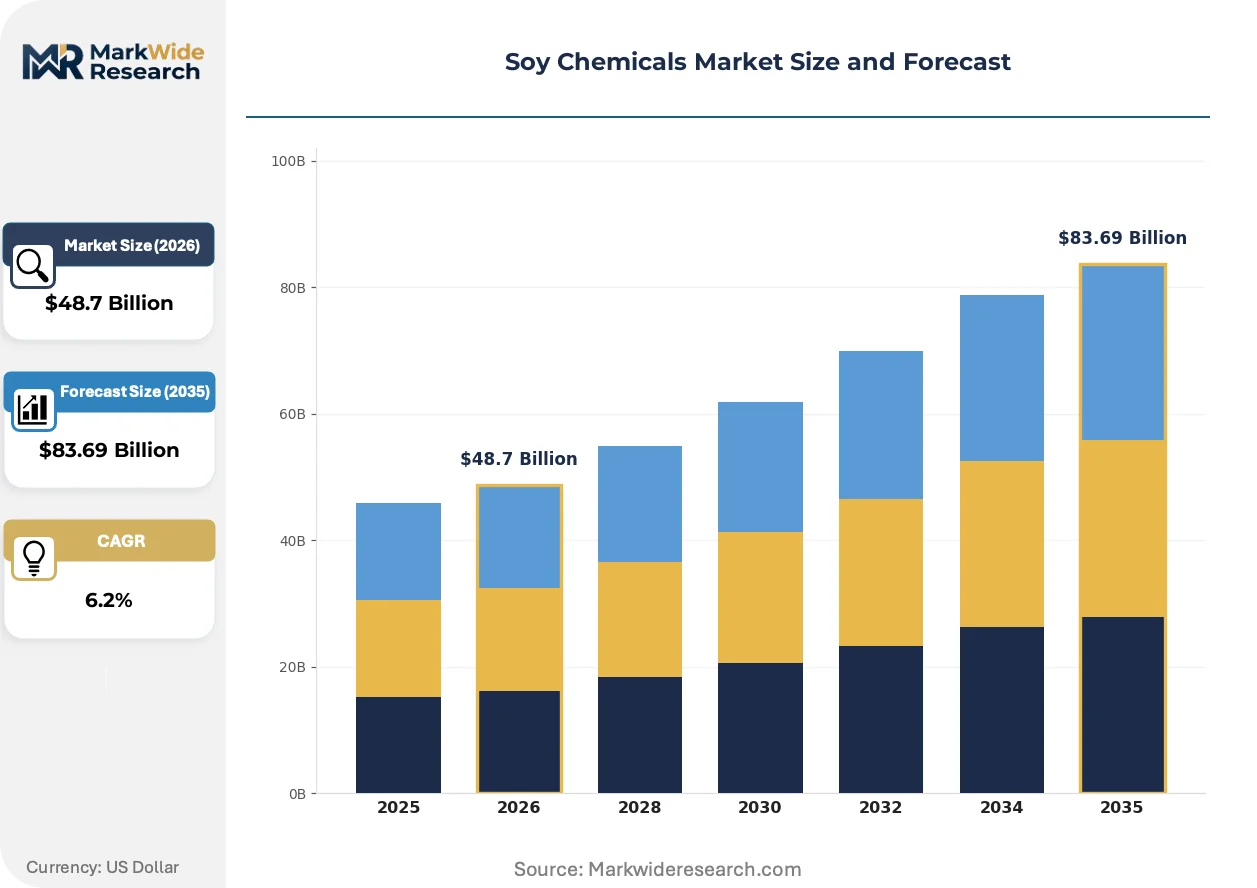
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $83.69 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Soy Protein, Soy Wax, Soy Lecithin Application: Food Additives, Personal Care, Biodiesel, Adhesives End User: Food Industry, Cosmetics, Agriculture, Automotive Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Cargill, Archer Daniels Midland, Dow, LANXESS, Bunge Limited, Elevance Renewable Sciences, Ag Processing Inc., Vertec BioSolvents, BioBased Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Chemicals Market Emerging Trajectories
Enzymatic and mechanical processing advances are fragmenting the traditional crush-refine model, enabling modular production closer to end-use demand clusters.
Membrane filtration systems for lecithin fractionation are unifying protein and lipid recovery streams that previously required separate solvent extraction trains. Pharmaceutical-grade lecithin producers in Germany and Japan are adopting these systems to reduce hexane handling costs. The technology is compressing capital requirements for mid-scale entrants.
REACH authorization timelines for novel bio-based surfactants are tightening as ECHA prioritizes endocrine disruption screening. European formulators are pre-subscribing testing consortia to secure data cost-sharing. The personal care segment is accelerating green chemistry substitutions ahead of 2026 sunset dates.
Long-term offtake contracting is displacing spot purchasing among North American biodiesel producers. Crush facilities in Iowa and Illinois are locking five-year supply agreements with renewable diesel refiners. This procurement compression is stripping liquidity from cash soy oil markets.
Soy Chemicals Market Segmentation
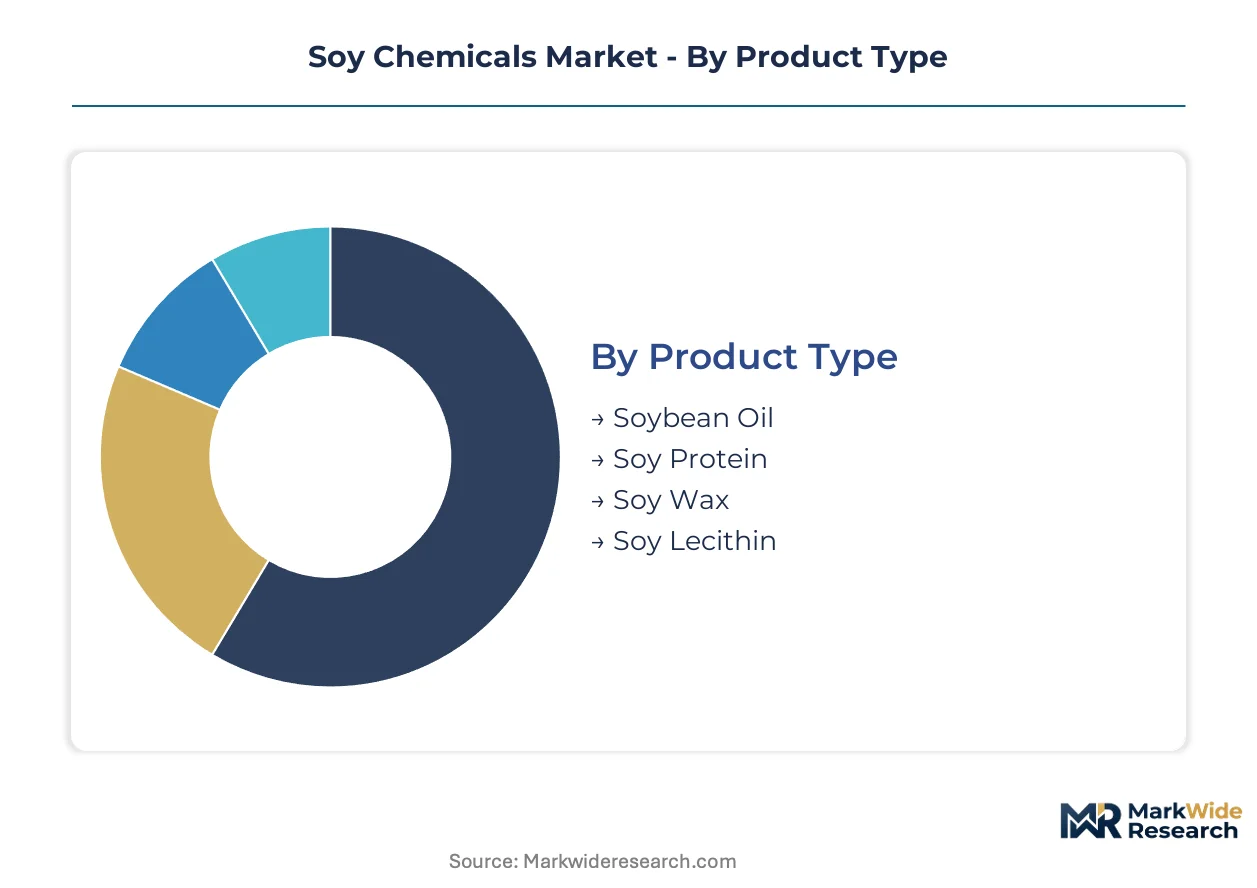
Soy chemicals fragment across distinct value chains where technical specifications, certification requirements, and end-use performance standards reshape procurement patterns. Buyers prioritize different attributes—oxidative stability for fuel applications, emulsification indices for food systems, or melting point precision for cosmetic formulations—creating tiered demand pools that processors must target discretely.
Product Type:
Cost tier separates commodity buyers from specialty purchasers, with hydrogenation depth and purity grades determining margin capture.
- Soybean Oil:Refined, degummed, and partially hydrogenated grades serve biodiesel transesterification and industrial lubricant bases. Demand concentrates in Iowa and Illinois crush corridors where renewable diesel offtake contracts are restructuring flow patterns toward fuel conversion rather than food refining.
- Soy Protein:Isolates and concentrates with 90% and 70% protein content respectively supply meat analog formulations and nutritional fortification. German food manufacturers are scaling enzymatic fractionation capacity to meet EFSA novel food application requirements for textured protein ingredients.
- Soy Wax:Fully hydrogenated technical-grade fractions displace petroleum paraffin in candle and personal care applications. Midwestern refiners retrofit hydrogenation trains to capture technical wax premiums.
- Soy Lecithin:Fluid, de-oiled, and modified phospholipid fractions serve pharmaceutical delivery systems and chocolate confections. Membrane filtration adoption in Japan reduces hexane handling costs for pharmaceutical-grade output.
Volume sits with Soybean Oil; growth tilts toward Soy Lecithin.
Application:
Application maturity determines whether buyers specify certified sustainable supply chains or accept conventional grades.
- Food Additives:Emulsifiers, texturizers, and stabilizers require FDA food-contact compliance and kosher/halal certification. Clean-label momentum in US and European retail channels is elevating non-GMO and organic soy derivative specifications.
- Biodiesel:Fatty acid methyl ester production consumes crude and refined soybean oil as primary feedstock. EU Renewable Energy Directive II sustainability thresholds are filtering supply toward certified deforestation-free origination.
- Personal Care:Surfactants, emollients, and wax bases in skin and hair formulations demand REACH-registered intermediates with endocrine disruption screening clearance. German formulators are pre-subscribing testing consortia ahead of 2026 authorization deadlines.
- Adhesives:Polyol components for polyurethane systems and pressure-sensitive applications compete with petroleum-derived alternatives. Automotive interior specifications from German OEMs are embedding bio-based content scorecards into supplier qualification.
Volume concentrates in Food Additives; Biodiesel is climbing the fastest.
End User:
Customer scale and technical sophistication fragment procurement—multinational formulators demand traceability systems while regional compounders prioritize spot pricing.
- Food Industry:Processed meat, dairy alternative, and bakery manufacturers specify protein functionality indices and oil oxidative stability parameters. Cargill and ADM anchor supply agreements with major US retail brand owners.
- Cosmetics:Formulators seek lecithin fractions with defined phosphatidylcholine content and waxes with narrow melting ranges. Japanese pharmaceutical-grade producers command premium positioning through enzymatic processing licenses.
- Agriculture:Adjuvant and crop protection applications consume soy methyl esters and lecithin-based dispersants. Indian agrochemical compounders are testing domestic soy alternatives to reduce palm oil import exposure.
- Automotive:Interior polyurethane foam and lubricant manufacturers require polyols with consistent hydroxyl numbers and low volatile organic compound profiles. US Inflation Reduction Act credits are expanding qualifying feedstock categories for soy-derived materials.
Volume sits with Food Industry; Cosmetics exhibits the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks buyer technical capability—sophisticated formulators bypass intermediaries while smaller compounders rely on distributor technical service.
- Wholesale:Bulk refined oil and protein concentrate movements through terminal and elevator networks dominate commodity flow. Bunge Limited leverages port-advantaged logistics to serve export-oriented biodiesel producers.
- Direct Sales:Technical-grade lecithin and wax fractions move through processor technical service teams to qualified formulators. Long-term offtake contracting is displacing spot purchasing among North American renewable diesel refiners.
- Online Retail:Small-batch specialty wax and cosmetic-grade lecithin serve artisan candle makers and independent formulators. E-commerce penetration remains marginal for industrial volumes.
- Specialty Stores:Health food and natural product retailers stock non-GMO soy protein isolates and lecithin supplements for consumer packaged goods. Certification labeling requirements vary by jurisdiction.
Volume concentrates in Wholesale; Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern soybean crushing corridors in the United States anchor feedstock supply for chemical conversion, while German hydrogenation capacity expands to meet EU sustainability mandates. Argentina-Paraguay export volumes transmit price volatility through global oil markets.
United States
Iowa and Illinois crush facilities are locking five-year offtake contracts with renewable diesel refiners, stripping liquidity from cash soy oil markets. The EPA Renewable Fuel Standard and Inflation Reduction Act Section 45Q credits expand qualifying feedstock categories. Cargill leverages its crush-and-refine infrastructure to anchor downstream chemical output across the Farm Belt.
Germany
Chemical manufacturers are scaling oleochemical conversion capacity to meet EU Renewable Energy Directive II certified sustainable supply requirements. REACH registration requirements constrain formulation chemistry and import pathways for novel intermediates. The country's hydrogenation clusters are retrofitting refineries to produce technical-grade wax fractions for personal care applications.
Argentina
Exportable soy oil volumes from South American crushing capacity dominate global trade flows, transmitting immediate price shocks from weather disruptions or export tax shifts. The country's national agricultural regulator oversees deforestation-free origination certifications required by EU buyers. Rosario and Buenos Aires provinces concentrate crushing infrastructure serving European biodiesel demand.
India
Local detergent and agrochemical formulators seek domestic oleochemical feedstocks to reduce palm oil import dependence, creating procurement pivot opportunities for soy-based alternatives. The Bureau of Indian Standards and FSSAI govern food-contact and industrial chemical specifications. Maharashtra and Gujarat processing corridors are testing soy methyl ester capacity for adjuvant applications.
Japan
Pharmaceutical-grade lecithin producers are adopting membrane filtration systems to reduce hexane handling costs, unifying protein and lipid recovery streams. METI oversees industrial chemical standards while PMDA regulates pharmaceutical delivery system ingredients. Osaka and Nagoya clusters specialize in enzymatic fractionation licenses for high-purity phospholipid fractions.
Soy Chemicals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty lecithin and enzymatic fractionation niches. The market structures around three maturity tiers: multinational agribusinesses with captive crush capacity, mid-scale chemical converters with hydrogenation expertise, and biotechnology licensors with novel processing patents. Strategic moves concentrate on long-term offtake contracting and refinery retrofitting for technical-grade output.
Among North American agribusinesses, Cargill, Archer Daniels Midland, and Bunge Limited exemplify the scale-driven archetype with integrated origination and refining infrastructure. Cargill anchors downstream chemical output through crush-and-refine assets across the Farm Belt. Archer Daniels Midland sustains origination density in core soybean production regions. Bunge Limited occupies a position emphasizing port-advantaged export logistics for international biodiesel markets.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Dow |
| LANXESS |
| Bunge Limited |
| Elevance Renewable Sciences |
| Ag Processing Inc. |
| Vertec BioSolvents |
| BioBased Technologies LLC |
| Others |
Supply Flow & Price Mechanics
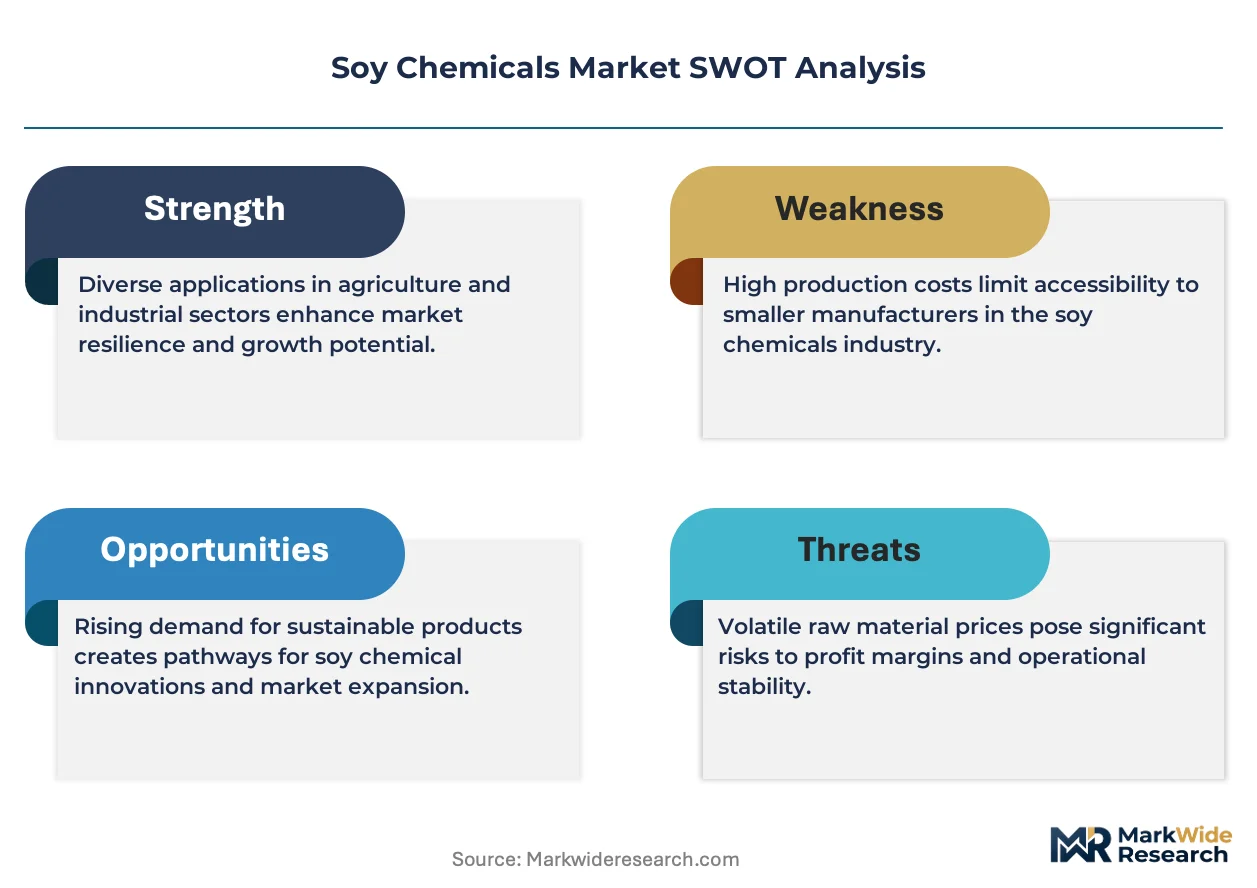
Process chemist scarcity in the Midwestern hydrogenation corridor widens spreads between technical-grade wax premiums and commodity soybean oil baselines, as labor-cost differentials compound certification premiums for pharmaceutical-grade lecithin fractions.
Pricing Analysis
After-sales technical service bundling separates contract-based long-term offtake agreements from spot-market transactions, with dedicated process support commanding 15-20% premiums over unbundled commodity supply. Price differentiation hinges on REACH registration tier and volume scale, with certified sustainable supply chains capturing margin premiums over conventional grades. Pricing pressure stems from crude oil volatility compressing bio-based margins in lubricant applications. Biodiesel refiners exhibit lowest price sensitivity due to tax credit stacking, while artisan candle makers face acute cost compression.
Supply Chain Analysis
EU Renewable Energy Directive II certification gates European market entry, filtering supply toward deforestation-free origination systems that command procurement preference. Geographic concentration centers on the United States, Argentina, and Germany, with crush capacity clustering in Iowa-Illinois corridors and Rosario-Buenos Aires provinces. Raw material flows draw from soybean seedstock, hexane solvent, and hydrogenation catalysts. Single-source vulnerability runs through South American export tax policy shifts. Distribution runs through wholesale terminal networks for commodity volumes and direct technical sales for specialty fractions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over enzymatic fractionation patents determines specialty-grade margin capture.
For Market Incumbents: Lock in five-year renewable diesel offtake contracts to strip liquidity from spot markets and defend against emerging biotechnology licensors. Retrofit hydrogenation trains for technical-grade wax output to capture petroleum paraffin displacement premiums. Prioritize REACH registration dossier completion ahead of ECHA authorization deadlines. For New Entrants and Emerging Players: Membrane filtration technology for pharmaceutical-grade lecithin offers a technology-first wedge into the Japanese and German personal care supply chains. White-space targets include Indian industrial surfactant procurement pivots and soy-based polyol qualification for automotive interior scorecards. Pursue enzymatic processing licenses from Osaka and Nagoya clusters as go-to-market anchor. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale chemical converters possessing hydrogenation expertise given EU bio-based content mandate acceleration. Long-term viability favors processors with captive crush capacity and downstream oleochemical conversion assets. Watch ECHA endocrine disruption screening timelines as inflection indicator for green chemistry substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzymatic Processing | Captures pharmaceutical-grade lecithin premiums through in-house protease and lipase systems. |
| Long-term Supply Agreement with Renewable Diesel Refiners | Locks crush capacity utilization via Iowa and Illinois corridor offtake contracting. |
| Green Manufacturing Transition to Membrane Filtration | Reduces hexane handling costs for Japanese pharmaceutical-grade output. |
| Capacity Expansion in German Hydrogenation Clusters | Aligns technical-grade wax output with EU Renewable Energy Directive II thresholds. |
| Joint Venture for Indian Surfactant Feedstock Supply | Penetrates Maharashtra and Gujarat detergent and agrochemical formulator procurement. |
Methodological Framework
Independent corroboration across plant managers at Midwestern crush facilities, procurement leads at German biodiesel refiners, and technical R&D directors at Japanese lecithin processors underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of listed agribusinesses, and Cefic oleochemical reports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Comparable historical periods spanning crush-margin cycles and biofuel policy regime shifts anchor the projection horizon. Segmentation dimensions include product grade tier, end-use application, and regional production hub. CAGRs derive from regression analysis against feedstock price elasticity and policy incentive trajectories. Forecast inputs incorporate EPA Renewable Fuel Standard pathway approvals and EU carbon-border adjustment mechanism progression.
Several conditions sit outside the modeled scope, including abrupt South American export tax shifts and unscheduled ECHA authorization delays. Forecasts reflect documented assumptions regarding crush capacity expansion timelines and enzymatic fractionation adoption rates. A model refresh is warranted upon material change in EU Green Deal implementation velocity or US Inflation Reduction Act credit stacking rules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Mercaptopropionic Acid Market