
 Bio-Acetic Acid Market | 2026-2036
Bio-Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Acetic Acid Market Intelligence
The application of advanced metabolic engineering in microbial strains is narrowing the cost gap between bio-fermentation and traditional synthesis methods for acetic acid. LanzaTech specializes in gas fermentation technology to convert industrial waste gases. Godavari Biorefineries leverages its integrated sugar-to-chemicals model in India. Novozymes A/S provides critical enzymes for efficient biomass conversion.
Bio-acetic acid is chemically identical to its synthetic counterpart but is derived from renewable biological sources. Production often involves the bacterial fermentation of feedstocks like sugarcane or corn using Acetobacter species. Its primary commercial purpose is as a food preservative, a chemical solvent, and an intermediate. The fermentation production method remains the dominant pathway, driven by demand from the Food & Beverage industry for natural ingredients in preservation applications.
Regulatory frameworks are critical for market access and premium pricing. The FDA's Generally Recognized As Safe (GRAS) designation in the United States and EFSA's guidelines in Europe dictate use in food products. These standards, along with China's GB standards for food additives, create demand for certified bio-based sources. Key decisions for producers now revolve around managing agricultural feedstock price volatility versus the cost of synthetic alternatives.
Market Dynamics
The primary structural force shaping the bio-acetic acid market is the regulatory and consumer-driven preference for renewable feedstocks over petrochemical sources. This shift, codified by frameworks like the EU Green Deal, creates protected demand and pricing power for certified bio-based products, especially within the food industry.
Growth Catalysts
- Regulatory Mandates:Policies like the EU Green Deal and national bio-economy strategies incentivize a transition away from fossil-based chemicals, creating a direct pull for bio-acetic acid in industrial applications.
- Consumer Preference for Natural Ingredients:The Food & Beverage industry's move towards "clean labels" drives demand for bio-acetic acid as a preservative, a trend particularly strong in North American and European markets.
- Fermentation Technology Advancement:Innovations in microbial strain development and gas fermentation are steadily improving yields and reducing the production cost differential compared to synthetic acetic acid.
Market Restraints
- Feedstock Price Volatility:Dependence on agricultural commodities like corn and sugarcane exposes producers to price swings and supply chain disruptions driven by weather, crop yields, and food-versus-fuel competition.
- Cost Competitiveness:Synthetic acetic acid produced via methanol carbonylation remains a lower-cost alternative for industrial applications where a bio-based origin is not a regulatory or marketing requirement.
- Scale-Up Capital Intensity:Building and operating large-scale fermentation facilities requires significant upfront capital investment and specialized engineering expertise, creating a high barrier to entry for new producers.
Strategic Opportunities
- Waste-Based Feedstocks:Utilizing non-food biomass, agricultural residues, or industrial off-gases as feedstocks can mitigate price volatility and strengthen circular economy credentials, opening new value chains.
- Bio-polymer Precursor:Positioning bio-acetic acid as a key building block for biodegradable plastics and other green polymers provides access to high-growth, non-food markets.
- Geographic Market Development:Penetrating markets in Asia-Pacific where governments are beginning to implement sustainability mandates and consumer demand for natural products is rising.
Industry Challenges
- Certification and Compliance Burden:Securing and maintaining distinct certifications for different markets, such as FDA GRAS, EFSA food additive approval, and China's GB standards, is a complex and resource-intensive process.
- Process Standardization:A lack of standardization in fermentation and purification processes across the industry can lead to variability in product quality and complicates direct substitution for buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Acetic Acid Market |
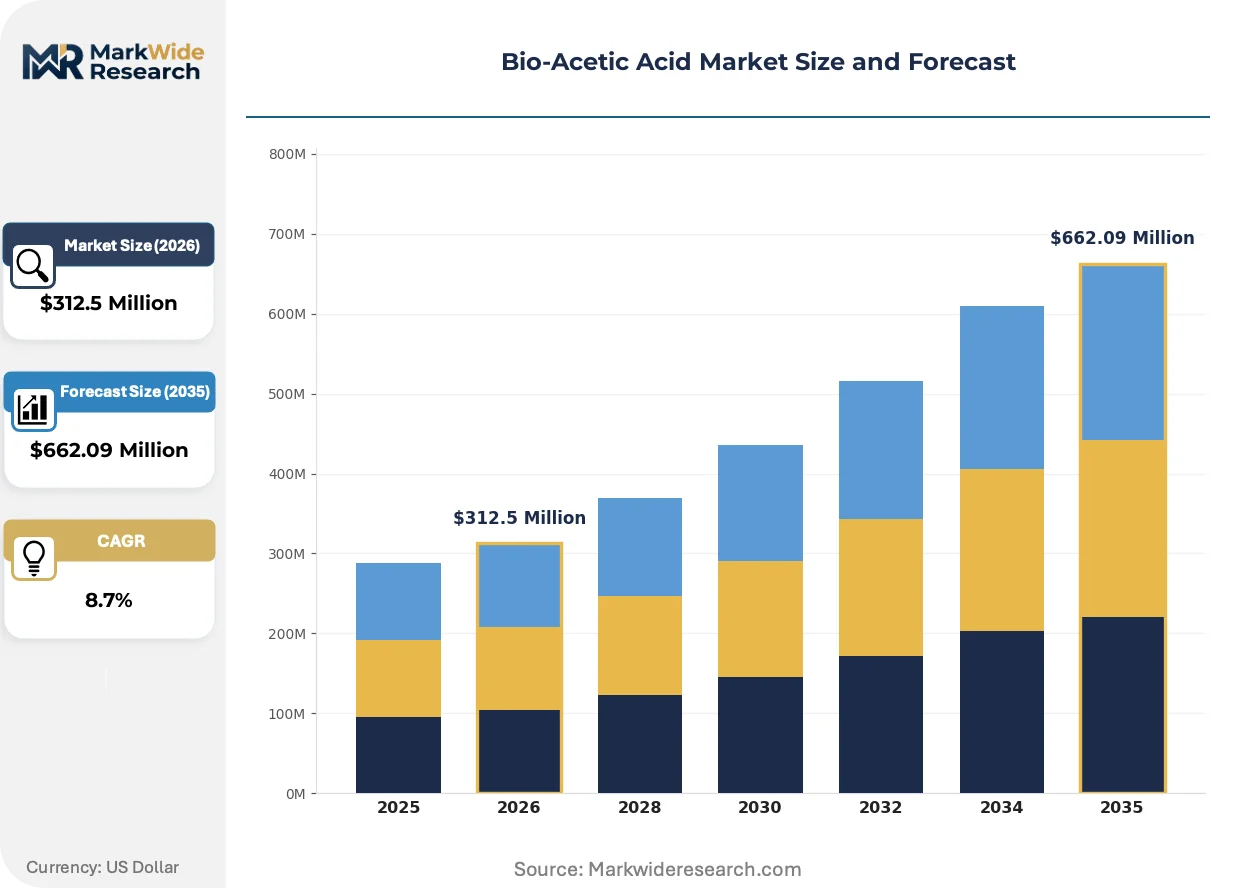
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Fermentation, Synthesis, Catalytic, Biomass Application: Food Preservation, Pharmaceuticals, Chemical Solvents, Industrial End Use Industry: Food & Beverage, Textiles, Plastics, Personal Care Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Godavari Biorefineries Ltd., Airedale Chemicals, Novozymes A/S, LanzaTech, Cargill, Inc., Sucroal SA, Bio-Corn Products EPZ Ltd., Afyren SAS, Sekab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Acetic Acid Market Strategic Shifts & Innovations
Technological convergence between synthetic biology and advanced process automation is redefining efficiency in bio-acetic acid production. This integration allows for greater control over biological processes, steering the industry toward more predictable and cost-effective manufacturing that can utilize a wider array of sustainable feedstocks.
Digital twin technology creates dynamic, in-silico models of fermentation bioreactors, capturing thousands of data points. Bioprocess engineers are adopting these models to test and optimize parameters like nutrient feed rates and gas exchange without physical trials. This high-fidelity simulation is virtualizing the otherwise costly and time-consuming process of physical pilot runs for improving microbial strain performance and validating new process designs.
The European Union's Carbon Border Adjustment Mechanism (CBAM) is a significant policy development. This regulation imposes a carbon-linked tariff on certain goods imported into the EU, effectively penalizing products with a high carbon footprint from their manufacturing process. As a result, petrochemical-derived acetic acid faces a potential cost disadvantage, making lower-carbon bio-acetic acid a more attractive alternative for European importers.
A clear shift toward traceability-verified sourcing is altering procurement patterns within the food and cosmetics sectors. Buyers are increasingly demanding verifiable proof of a product's bio-based origin, moving beyond simple supplier declarations to require lot-level data from farm to finished ingredient. This trend is most advanced in North American and German markets, where retailers face intense scrutiny over "natural" and "sustainable" product claims.
Bio-Acetic Acid Market Segmentation
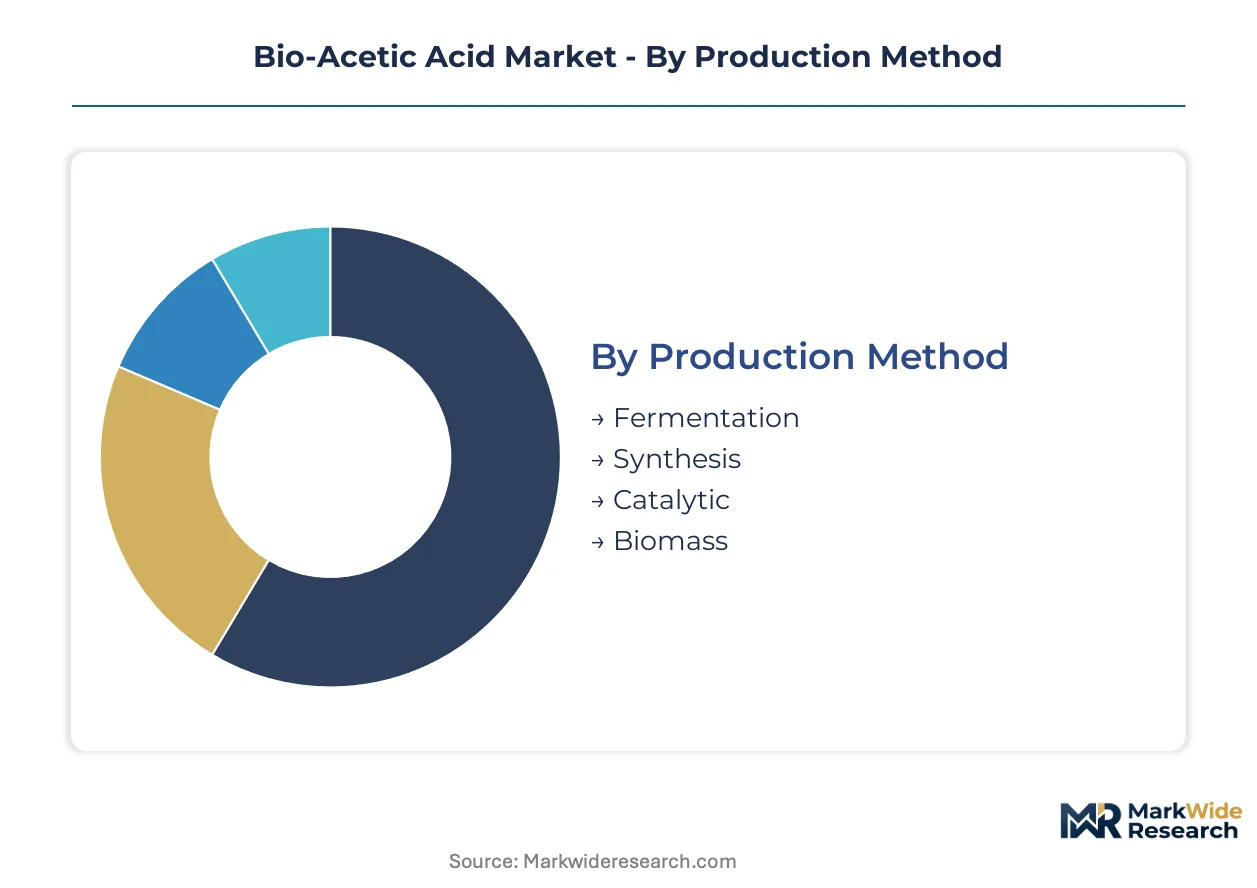
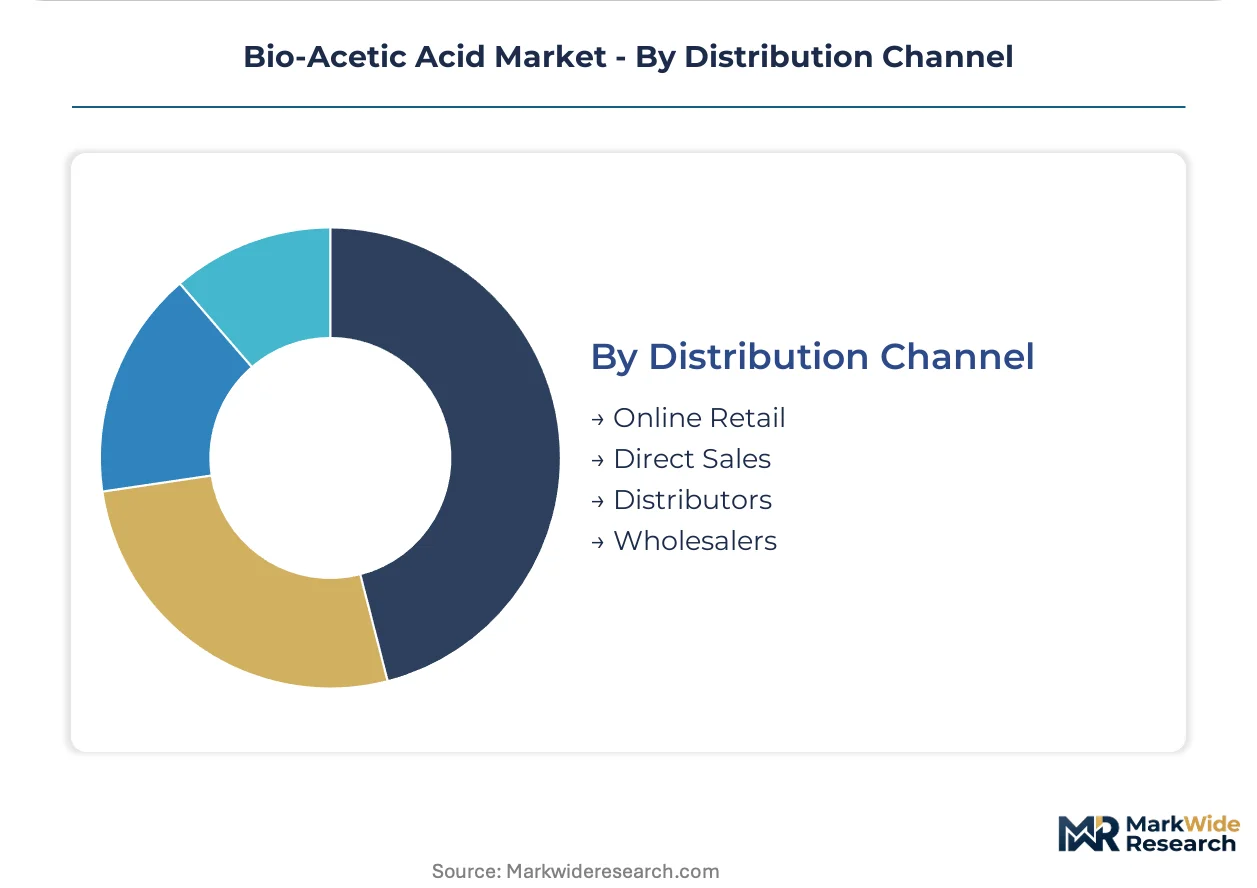
The bio-acetic acid market exhibits distinct segmentation across production methods, applications, end-use industries, and distribution channels. Understanding these segments clarifies the varying demands and supply mechanisms shaping the market. Each segment reflects unique technological requirements and commercial pathways for bio-acetic acid products.
Production Method:
The intensity of after-sales service and technical support varies significantly across bio-acetic acid production methods, reflecting process complexity and the need for specialized operational expertise.
- Fermentation:This method involves bacterial conversion of renewable feedstocks like sugarcane or corn into acetic acid. Demand concentrates in the food and beverage industry, driven by the need for naturally derived ingredients and clean label products.
- Synthesis:While chemically identical, synthetic acetic acid is typically derived from petrochemical sources through processes like methanol carbonylation. Its demand is strong in industrial applications where bio-based origin is not a regulatory or marketing priority, due to its cost competitiveness.
- Catalytic:Catalytic processes offer potential for efficient conversion of various carbon sources, including waste gases, into acetic acid.
- Biomass:Direct conversion of lignocellulosic biomass provides a sustainable pathway, reducing reliance on food-grade agricultural feedstocks.
By volume, Fermentation leads. By growth pace, Biomass is ahead.
Application:
The cost tiering of bio-acetic acid is often dictated by its application, with higher purity requirements for sensitive uses commanding premium pricing.
- Food Preservation:Bio-acetic acid functions as a natural preservative, inhibiting microbial growth in various food and beverage products. North American and European food industries drive significant demand due to stringent clean label consumer preferences and regulatory approvals.
- Chemical Solvents:Bio-acetic acid serves as an effective solvent in numerous industrial processes, including the production of paints, coatings, and adhesives. Its demand is increasing in chemical manufacturing hubs like Germany, as industries seek greener alternatives to petrochemical solvents.
- Pharmaceuticals:Bio-acetic acid finds use as an excipient or intermediate in the synthesis of various pharmaceutical compounds.
- Industrial:This broad category includes applications beyond solvents, such as textile dyeing, rubber production, and metal surface treatment.
Supply concentration for bio-acetic acid applications heavily favors the Food Preservation and Chemical Solvents segments.
End Use Industry:
Specific end-use industries prioritize bio-acetic acid based on its functional characteristics and alignment with their sustainability mandates.
- Food & Beverage:This industry is a primary consumer of bio-acetic acid, leveraging its role as a natural preservative and acidulant. Consumer demand for natural ingredients and clean label products in Europe and North America sustains market expansion.
- Plastics:Bio-acetic acid serves as a key precursor for bio-polymers and biodegradable plastics, supporting the shift towards sustainable packaging and materials. The European Union's push for circular economy initiatives stimulates demand in this segment.
- Textiles:Bio-acetic acid is employed in textile dyeing and finishing processes, contributing to more environmentally friendly production methods.
- Personal Care:The personal care sector utilizes bio-acetic acid in formulations for its pH adjustment and antimicrobial properties.
Customer types in the Food & Beverage and Plastics industries exhibit distinct procurement patterns for bio-acetic acid.
Distribution Channel:
Distribution channels for bio-acetic acid are largely determined by the volume requirements and logistical complexities of industrial procurement.
- Direct Sales:Major producers often engage in direct sales to large industrial customers, facilitating bulk orders and customized supply agreements. This channel ensures consistent supply for high-volume users in the chemical and food processing sectors.
- Distributors:Specialized chemical distributors play a crucial role in reaching medium-sized enterprises and regional markets. They manage inventory and logistics, providing essential access to bio-acetic acid for diverse industrial clients, particularly in Europe.
- Wholesalers:Wholesalers aggregate products from various manufacturers, supplying smaller businesses with bio-acetic acid in smaller quantities.
- Online Retail:Online platforms cater to niche applications and smaller-scale buyers, offering convenience for specialized bio-acetic acid products.
Margin structures differ significantly across distribution channels, with Direct Sales typically offering more favorable terms for producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bio-acetic acid trade flows from agricultural powerhouses to industrial demand centers, driven by sustainability mandates and consumer preferences. European and North American markets exhibit strong demand for bio-based ingredients. Regulatory frameworks increasingly shape regional market access and pricing dynamics.
Germany
Germany's chemical production hubs drive significant demand for bio-acetic acid as a green alternative to petrochemical sources. The EU Green Deal heavily incentivizes the transition towards bio-based chemicals across industrial applications. Key chemical manufacturing clusters in North Rhine-Westphalia are actively seeking certified bio-acetic acid for solvent and intermediate uses.
United States
The United States market prioritizes bio-acetic acid for food preservation and natural ingredients within the Food & Beverage industry. The FDA's Generally Recognized As Safe (GRAS) designation facilitates market entry for bio-based food additives. Food processing centers in the Midwest and California are major consumers, responding to clean label consumer preferences.
China
China's market for bio-acetic acid is expanding, influenced by evolving sustainability mandates and consumer demand for natural products. The country's GB standards for food additives are creating a demand for certified bio-based sources. Industrial zones along the Yangtze River Delta are exploring bio-acetic acid for various chemical applications.
India
India represents a significant production base for bio-acetic acid, leveraging its abundant sugarcane feedstocks and integrated sugar-to-chemicals models. National bio-economy strategies support the development of renewable chemical industries. States like Maharashtra and Uttar Pradesh, with strong agricultural and chemical sectors, are key production and consumption centers.
Brazil
Brazil exhibits strong potential for bio-acetic acid production, capitalizing on its extensive sugarcane cultivation and established bioethanol infrastructure. Government initiatives promoting bio-economy and sustainable industrial development encourage bio-based chemical manufacturing. Agricultural regions in São Paulo and Minas Gerais are pivotal for feedstock supply and initial processing.
Bio-Acetic Acid Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for bio-acetic acid. The market features large chemical conglomerates alongside specialized biotech firms and feedstock integrators. Companies frequently pursue strategic partnerships to secure feedstock supply and expand geographic reach, particularly into emerging markets.
Specialists in fermentation technology and feedstock conversion exemplify innovation within the bio-acetic acid market. Godavari Biorefineries Ltd., an India-based company, leverages its integrated sugar-to-chemicals model, showcasing efficiency in feedstock utilization. LanzaTech, an American firm, represents advancements in gas fermentation, converting industrial waste gases into valuable chemicals. Novozymes A/S, a Danish biotechnology company, provides critical enzymes that enhance the efficiency of biomass conversion processes, underpinning sustainable production methods.
| Leading Market Players |
|---|
| Godavari Biorefineries Ltd. |
| Airedale Chemicals |
| Novozymes A/S |
| LanzaTech |
| Cargill, Inc. |
| Sucroal SA |
| Bio-Corn Products EPZ Ltd. |
| Afyren SAS |
| Sekab |
| Others |
Cost & Logistics Intelligence
Undercapacity in advanced fermentation technology in Europe drives supplier behavior, emphasizing premium pricing for certified bio-acetic acid for specific applications.
Pricing Analysis
Cost-plus contract patterns, often indexed to agricultural commodity prices, govern large-volume bio-acetic acid transactions. Price differentiation stems from certification levels, such as FDA GRAS or EFSA food additive approval, and volume scale. Pricing pressure on industrial-grade bio-acetic acid intensifies due to the cost competitiveness of synthetic alternatives. Food & Beverage industry buyers exhibit lower price sensitivity for certified bio-based products compared to industrial chemical manufacturers.
Supply Chain Analysis
Feedstock price volatility, particularly for sugarcane and corn, dominates the bio-acetic acid supply chain risk profile. Geographic supply concentrates in India and Brazil, leveraging abundant agricultural resources, while demand centers in Germany and the United States. Raw material dependencies include renewable feedstocks like sugarcane, corn, and lignocellulosic biomass. Distribution runs through direct sales to large industrial customers and specialized chemical distributors serving regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
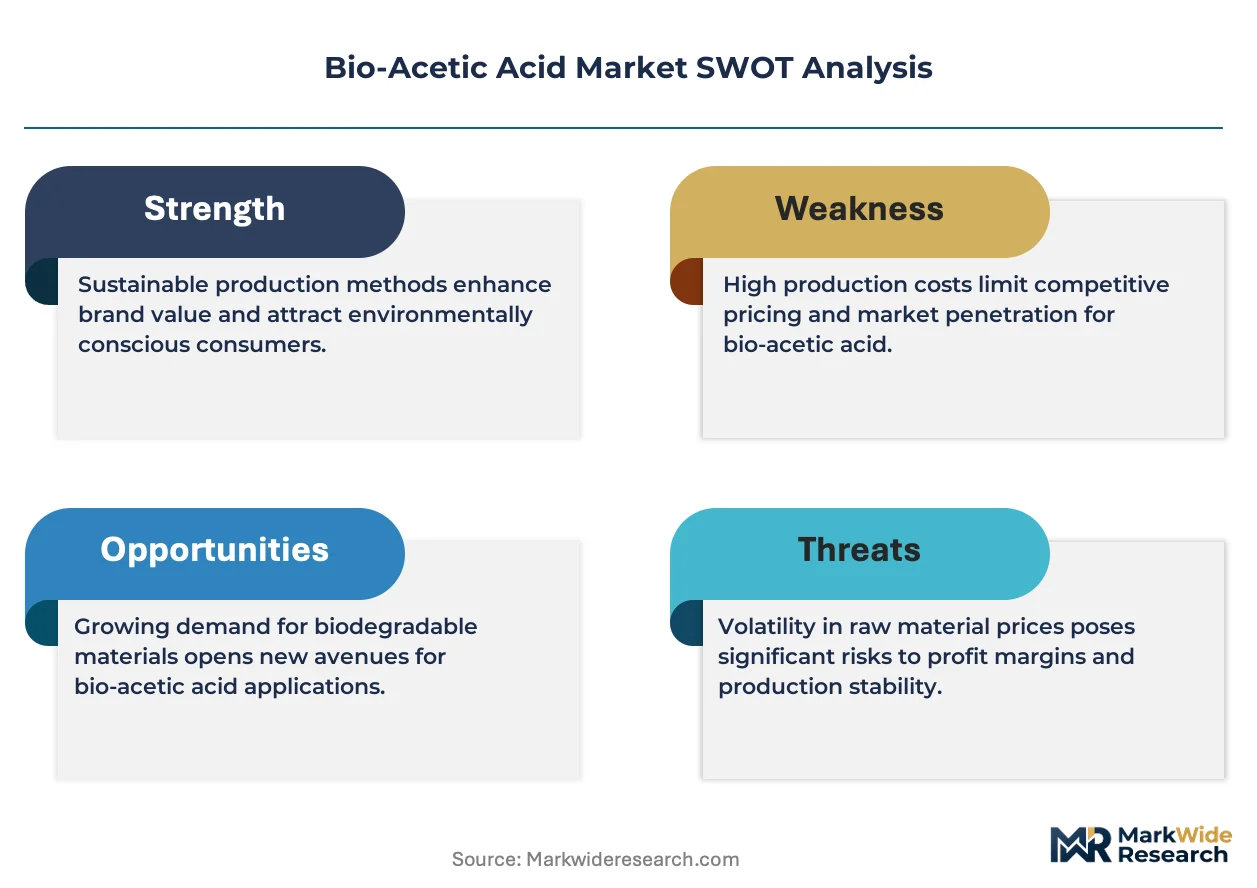
The bio-acetic acid market demands a robust substitution defense against cost-effective synthetic acetic acid alternatives, which incumbents must navigate.
For Market Incumbents: Pre-empt further market share erosion from synthetic alternatives by investing in advanced gas fermentation technologies. Expand certified production capacity in strategic regions like the European Union to capitalize on regulatory mandates. Secure long-term feedstock supply agreements to mitigate agricultural commodity price volatility. Invest in R&D for waste-based feedstock utilization, strengthening circular economy credentials.
For New Entrants and Emerging Players: Establish a beachhead in the Asia-Pacific region, targeting rising demand for natural food ingredients and evolving sustainability mandates. Position bio-acetic acid as a key building block for bio-polymers, accessing high-growth non-food markets. The most penetrable segment lies in specialized industrial applications where bio-based origin offers a competitive advantage. A go-to-market angle emphasizing verifiable traceability and circular economy credentials will resonate with buyers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bio-acetic acid producers with integrated feedstock-to-chemical models, offering long-term viability. Target acquisition archetypes include specialists in gas fermentation or advanced biomass conversion technologies. A signal to watch for strategic investment is the broader adoption of carbon border adjustment mechanisms, similar to the EU CBAM, globally.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production capacity reduces unit costs and meets growing demand for bio-acetic acid. |
| Green Manufacturing Transition | Adopting sustainable production methods enhances market appeal and aligns with global environmental goals. |
| Long-term Supply Agreement | Securing feedstock supply ensures production stability and mitigates price volatility for producers. |
| Joint Venture | Partnerships facilitate technology transfer and market access, particularly in emerging bio-economy hubs. |
| Technology Licensing | Licensing advanced fermentation technologies improves efficiency and broadens feedstock flexibility for manufacturers. |
Research Approach
The analysis maps bio-acetic acid sub-sectors, including food preservation and chemical solvents, each validated through chemical plant managers and biotechnology R&D directors. Primary interviews with regulatory compliance officers and food industry procurement leads inform market dynamics. Secondary data sources include EU Green Deal reports, FDA and EFSA guidelines, national bio-economy strategies, and customs trade data, triangulating findings from bottom-up and top-down approaches.
Assumptions regarding regulatory stability and sustained consumer preference for natural ingredients were held fixed across the analysis window. The analytical framework considers segmentation dimensions such as production method, application, end-use industry, distribution channel, and regional regulatory landscape. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected technological advancements. Forecast inputs include agricultural feedstock prices and regulatory policy shifts.
Sensitivities concentrate around unforeseen shifts in agricultural commodity prices or accelerated synthetic technology advancements. Forecasts reflect these underlying assumptions, acknowledging potential impacts from global economic fluctuations and geopolitical events affecting feedstock supply. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market