
 1,3-Dichloroacetone Market | 2026-2036
1,3-Dichloroacetone Market Size, Share, and Industry Trends Forecast 2026-2036
1,3-Dichloroacetone Market Insights
Multi-source procurement among contract fine-chemical buyers is expanding as pharmaceutical and agrochemical formulators reduce reliance on single-region supply. Merck sustains European reagent-grade leadership through captive chlorination assets and ISO-certified batch controls. Tokyo Chemical Industry (TCI) anchors Asia-Pacific distribution with stocked regional warehouses and custom synthesis services. Oakwood Products competes on niche catalog breadth for North American laboratory customers.
1,3-Dichloroacetone is an alpha-halogenated ketone with the molecular formula C3H4Cl2O, typically synthesized via acid-catalyzed chlorination of acetone or through 1,3-dichloro-2-propanol oxidation, and serves primarily as a reactive intermediate in organochlorine chemistry and cyclic compound formation. The intermediate product type commands the deepest margin pool due to long-term supply agreements with agrochemical multinationals, while reagent-grade volumes expand fastest from pharmaceutical discovery outsourcing. Fine chemicals as an end-use industry retains mature, price-sensitive demand patterns compared with the specification-driven pharmaceutical segment.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements in Europe compel producers to document impurity profiles and ecotoxicity data before market access. China's MEE enforces wastewater discharge limits on chlorinated solvent manufacturing that elevate compliance costs for domestic producers. India's CDSCO and BIS certification pathways for pharmaceutical-grade inputs create additional qualification barriers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and qualification timeline shifts.
Market Dynamics
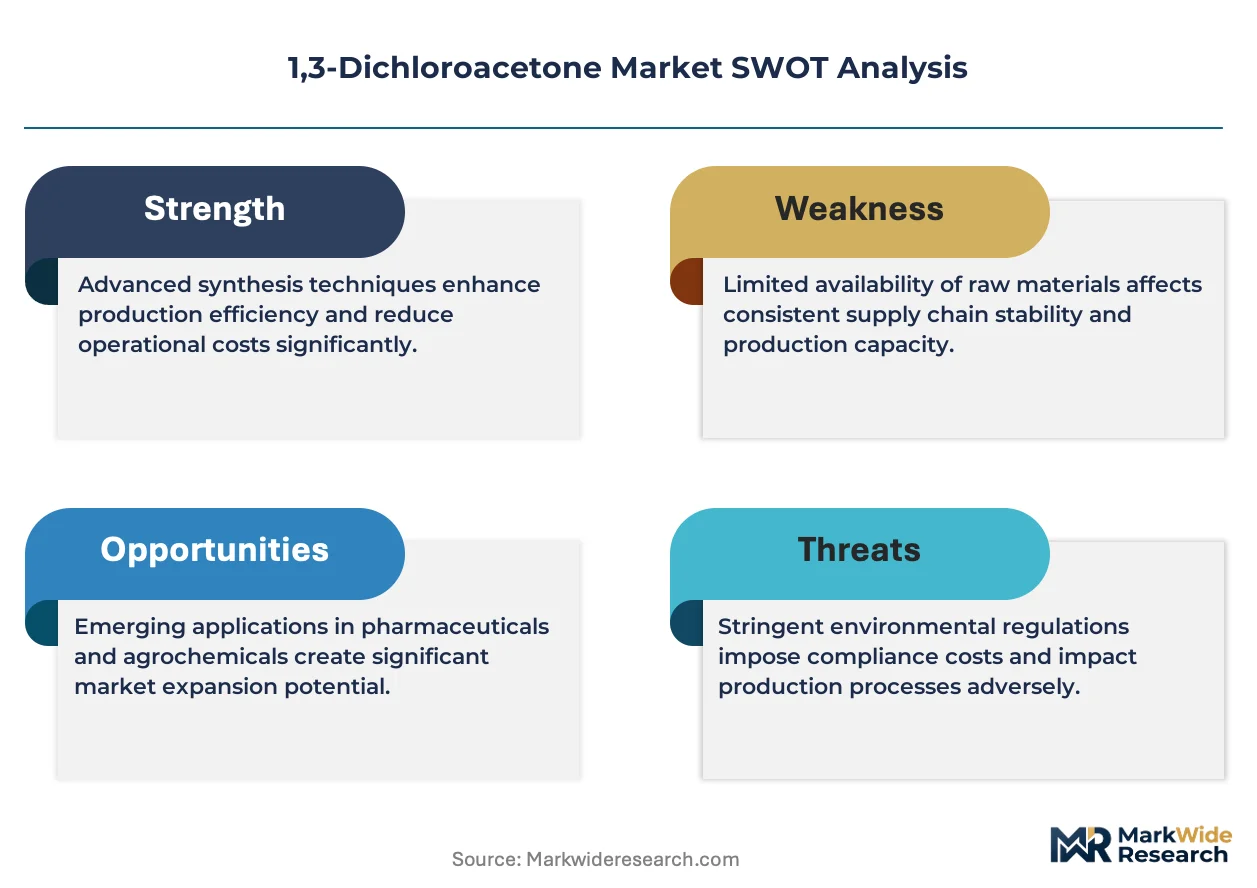
Pharmaceutical-grade specification tightening across multiple jurisdictions is compressing the supplier base for 1,3-Dichloroacetone, forcing producers to invest in captive chlorination assets and batch-level impurity profiling to retain qualification status with multinational formulators.
Growth Catalysts
- REACH Registration Tier III Deadlines:European agrochemical multinationals now require documented ecotoxicity data from suppliers, locking in long-term contracts with compliant producers and excluding spot-market traders from strategic procurement.
- India's PLI Scheme for Active Pharmaceutical Ingredients:Domestic fine-chemical manufacturers receive production-linked incentives that lower effective input costs for chlorinated ketone derivatives used in cardiovascular and oncology synthesis.
- Flow Chlorination Technology:Continuous processing equipment reduces acetone feedstock waste by enabling precise stoichiometric control, cutting per-unit variable costs for intermediate-grade material destined for herbicide precursors.
Market Restraints
- Acetone Price Volatility:Propylene supply disruptions and refinery operating rate fluctuations transmit directly to 1,3-Dichloroacetone production economics, compressing margins during feedstock spike periods.
- Jiangsu Province Supply Concentration:Over half of China's chlorinated solvent capacity clusters in this coastal region, exposing buyers to simultaneous weather-related shutdown risks and concentrated environmental enforcement actions.
- Trifluoroacetone Substitution:Fluorinated ketone alternatives gain traction in agrochemical R&D pipelines due to superior metabolic stability, threatening long-term volume retention in crop protection applications.
Strategic Opportunities
- Vietnam Fine-Chemical Investment Zones:New industrial parks near Ho Chi Minh City offer five-year tax holidays and streamlined environmental permitting for producers serving ASEAN pharmaceutical formulators seeking China-plus-one sourcing.
- Biocatalytic Halogenation Convergence:Enzymatic chlorination methods paired with membrane separation technology promise selective mono-chlorination control, enabling premium pricing for ultra-high-purity reagent grades.
- CDSCO Fast-Track API Certification:India's streamlined qualification pathway for imported starting materials reduces timeline uncertainty for foreign producers targeting domestic generic drug manufacturers.
Industry Challenges
- Chlorine Handling Certification Gaps:Licensed operators for pressurized chlorination systems remain scarce in emerging production hubs, constraining capacity expansion timelines.
- Multi-Jurisdiction Qualification Parallelism:Simultaneous EPA TSCA pre-manufacture notices, REACH dossier preparation, and BIS import testing create compliance resource bottlenecks for mid-scale exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1,3-Dichloroacetone Market |
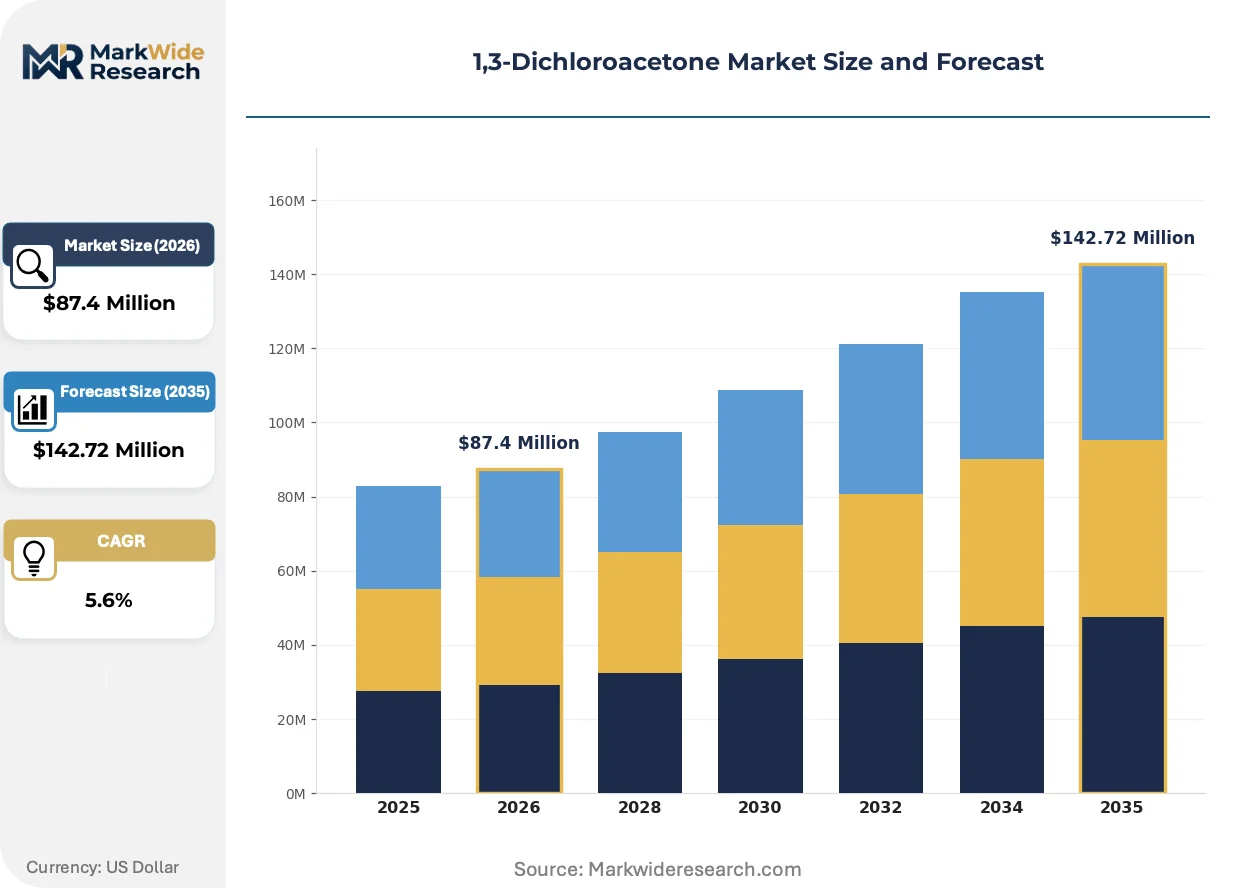
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $142.72 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Chemical Reagent, Industrial Chemical End Use Industry: Pesticides, Pharmaceuticals, Agrochemicals, Fine Chemicals Grade: Industrial Grade, Reagent Grade, Analytical Grade, Pharmaceutical Grade Application: Organic Synthesis, Solvent Applications, Chemical Manufacturing, Laboratory Use |
| Companies Covered | Thermo Fisher Scientific, Merck, Abcr, Achemtek, Tokyo Chemical Industry (TCI), Matrix Scientific, Key Organics, Oakwood Products, Smolecule, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,3-Dichloroacetone Market Trends and Innovations
Process intensification and regulatory data automation are reshaping competitive advantage in chlorinated ketone manufacturing. Producers now compete on impurity prediction capabilities and batch documentation speed rather than commodity scale alone.
Membrane-assisted reactive distillation is absorbing capital allocation from traditional chlorination train investments. European fine-chemical houses deploy this hybrid unit operation to achieve pharmaceutical-grade purity without multiple crystallization steps. The technology compresses working capital requirements by reducing intermediate inventory buffers between reaction and isolation stages.
REACH Article 33 supply chain communication obligations now mandate automatic disclosure of Substances of Very High Concern above threshold concentrations. Downstream agrochemical formulators face reformulation pressure when 1,3-Dichloroacetone batches contain trace chlorinated byproducts on the candidate list. German and French manufacturers lead the response by installing in-line mass spectrometry for real-time impurity detection.
Multi-source qualification mandates from top-ten pharmaceutical buyers are fragmenting incumbent supplier relationships. Procurement teams now require qualified secondary sources for all starting materials above defined volume thresholds, with India and South Korea emerging as preferred alternative origins. This pattern is most pronounced among US-based generic drug manufacturers with concentrated supply risk exposure to single-China-source dependencies.
1,3-Dichloroacetone Market Segmentation
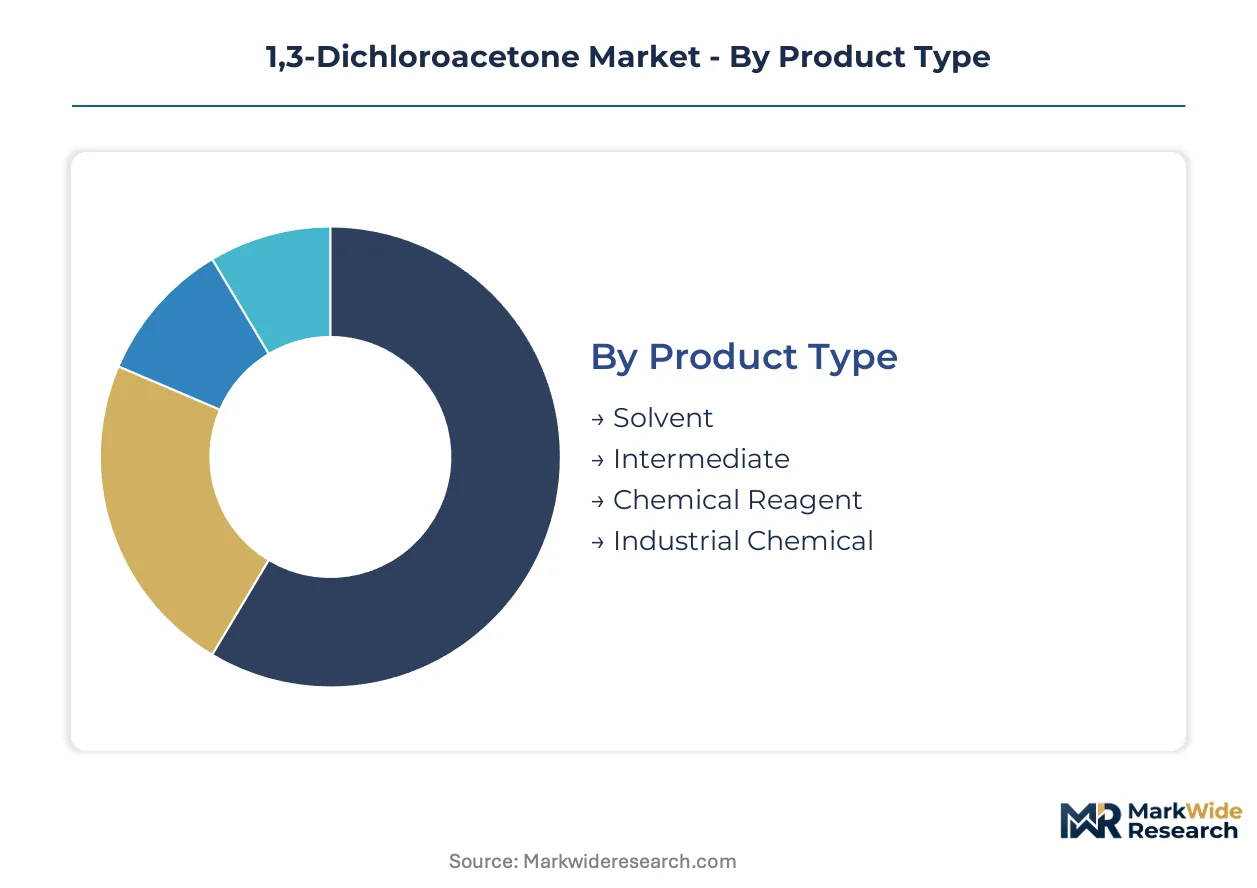
Segmentation in 1,3-Dichloroacetone reveals how purity specifications and regulatory pathways split procurement behavior across pharmaceutical formulators and agrochemical manufacturers. Specification tiers determine qualification barriers, while end-use concentration shapes regional production investments.
Product Type:
Technical differentiation centers on chlorination depth and downstream processing intensity required for each functional category.
- Intermediate:Alpha-halogenated ketone structure with 85-92% purity specifications serves as feedstock for cyclic compound formation in herbicide synthesis. Long-term supply agreements with Bayer CropScience and Syngenta procurement teams in Basel and Shanghai lock in volume commitments. REACH Tier III dossier requirements exclude spot-market traders from this segment.
- Chemical Reagent:Higher-purity grades (≥98%) support organochlorine chemistry in discovery-phase pharmaceutical programs. Tokyo Chemical Industry's regional warehouses in Osaka and Singapore stock these SKUs for just-in-time delivery to contract research organizations. Custom synthesis services command premium pricing for non-catalog specifications.
- Solvent:Technical-grade material functions as reaction medium in chlorinated solvent manufacturing trains.
- Industrial Chemical:Bulk volumes enter non-pharmaceutical chemical processing with minimal certification overhead.
Mature deployment sits with Intermediate contracts. Newer deployment is concentrated in Chemical Reagent spot purchasing for discovery outsourcing.
End Use Industry:
Customer sophistication spans specification-driven pharmaceutical qualification to price-sensitive bulk chemical procurement.
- Pharmaceuticals:GMP-compliant starting material for cardiovascular and oncology active pharmaceutical ingredient synthesis. India's PLI scheme for API manufacturing reduces effective input costs for domestic formulators in Hyderabad and Ahmedabad. CDSCO and BIS certification pathways create multi-month qualification timelines for imported material.
- Agrochemicals:Precursor for herbicide active ingredients targeting metabolic pathways in weed species. Procurement teams at BASF Agricultural Solutions and Corteva Agriscience require documented ecotoxicity data under REACH Article 33 obligations. Flow chlorination technology adoption compresses per-unit variable costs for this volume segment.
- Fine Chemicals:Custom synthesis houses consume specification-variable batches for diverse downstream transformations.
- Pesticides:Technical-grade material enters formulated crop protection products with lower purity thresholds.
Specification intensity peaks in Pharmaceuticals. Volume scale concentrates in Agrochemicals.
Grade:
Purity thresholds determine regulatory jurisdiction and pricing architecture across application tiers.
- Pharmaceutical Grade:≥99.5% purity with full impurity profiling and ICH Q3D elemental impurity compliance. Merck's captive chlorination assets in Darmstadt achieve this specification through ISO-certified batch controls. EPA TSCA pre-manufacture notices and REACH dossier preparation create compliance resource bottlenecks for mid-scale exporters targeting this tier.
- Reagent Grade:≥98% purity for analytical and research applications without full pharmaceutical documentation. Oakwood Products competes on catalog breadth for North American laboratory customers requiring rapid fulfillment. Membrane-assisted reactive distillation investments compress working capital requirements by reducing crystallization steps.
- Analytical Grade:Standardized purity for quality control reference standards and method validation.
- Industrial Grade:Technical specifications for bulk chemical processing with minimal documentation overhead.
Qualification complexity escalates from Industrial to Pharmaceutical Grade. Fastest share gains appear in Reagent Grade from pharmaceutical discovery outsourcing.
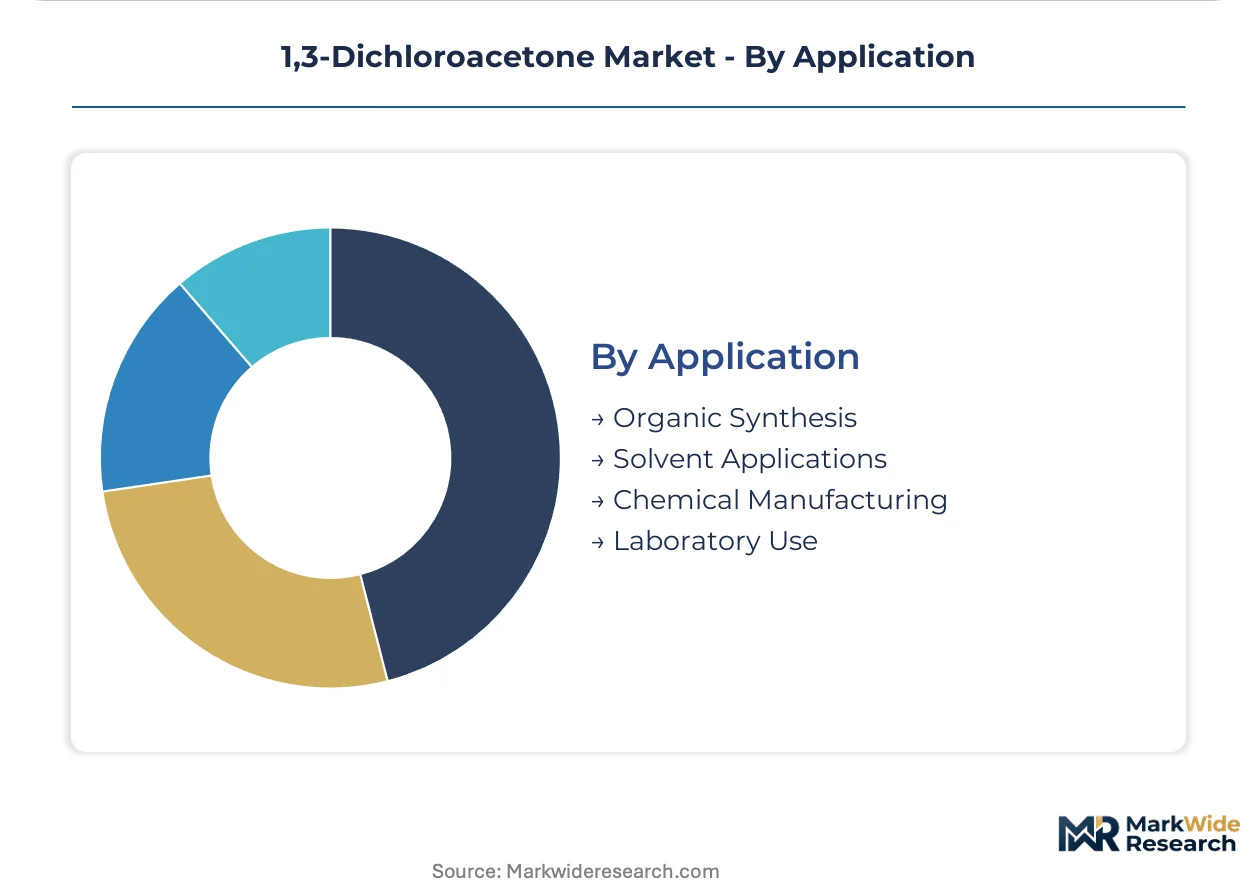
Application:
Functional use cases split between synthetic transformation chemistry and physical process roles.
- Organic Synthesis:Reactive intermediate for carbon-carbon bond formation and heterocyclic ring construction. Agrochemical R&D pipelines in Jiangsu Province and Research Triangle Park deploy this application for next-generation herbicide candidates. Trifluoroacetone substitution threats concentrate in this segment due to metabolic stability advantages of fluorinated alternatives.
- Chemical Manufacturing:Process intermediate for downstream chlorinated derivative production. China's MEE wastewater discharge limits on chlorinated solvent manufacturing elevate compliance costs for domestic producers serving this application. Jiangsu Province capacity concentration exposes buyers to simultaneous weather-related shutdown risks.
- Solvent Applications:Physical dissolution medium in reaction and extraction operations.
- Laboratory Use:Small-scale consumption for analytical method development and research protocols.
Process scale differentiates Chemical Manufacturing from Laboratory Use. Innovation investment concentrates in Organic Synthesis applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acetone feedstock availability and chlorination infrastructure anchor production economics across major manufacturing geographies. Procurement patterns diverge sharply between REACH-compliant European formulators and cost-optimized Asian agrochemical buyers.
China
Jiangsu Province hosts over half of national chlorinated solvent capacity, serving agrochemical multinationals with intermediate-grade material. MEE wastewater discharge limits elevate compliance costs for producers in Taixing and Changzhou chemical parks. Flow chlorination technology adoption concentrates in Nantong industrial zones to reduce acetone waste.
India
Hyderabad and Ahmedabad generic drug manufacturers drive pharmaceutical-grade procurement volumes under PLI scheme incentives. CDSCO fast-track API certification reduces timeline uncertainty for imported starting materials. Gujarat's Dahej and Ankleshwar chemical corridors attract chlorinated ketone investments serving domestic cardiovascular synthesis.
Germany
Merck's Darmstadt captive chlorination assets supply REACH Tier III-compliant reagent grades to European pharmaceutical formulators. ECHA documentation requirements for ecotoxicity data exclude spot-market traders from long-term agrochemical contracts. Bavarian fine-chemical houses deploy membrane-assisted reactive distillation for pharmaceutical-grade purity.
United States
EPA TSCA pre-manufacture notice requirements create compliance bottlenecks for mid-scale importers targeting reagent-grade segments. Research Triangle Park agrochemical R&D pipelines consume intermediate material for herbicide precursor development. Oakwood Products anchors North American laboratory distribution through catalog breadth.
Japan
Tokyo Chemical Industry's Osaka and Singapore regional warehouses stock chemical reagent grades for just-in-time CRO delivery. METI industrial standards govern chlorinated solvent handling certification for pressurized chlorination systems. Kanto region pharmaceutical discovery outsourcing sustains premium reagent demand.
1,3-Dichloroacetone Market Competitive Landscape
Strategic partnerships dominate the current landscape as qualification barriers fragment supply relationships. The vendor base organizes around three tiers: integrated multinationals with captive chlorination assets, regional distributors with stocked warehouse networks, and catalog specialists serving laboratory spot demand. Two strategic archetypes anchor competitive positioning: European reagent-grade leaders with ISO-certified batch controls, and Asia-Pacific distributors with custom synthesis capabilities. Technology licensing and geographic expansion represent the dominant competitive moves, with producers seeking alternative origins to reduce China-concentrated supply risk.
Among integrated multinationals, Merck exemplifies the European reagent-grade archetype through captive production assets, while Tokyo Chemical Industry occupies the Asia-Pacific distribution position with regional warehouse infrastructure. Oakwood Products represents the North American catalog specialist tier competing on niche breadth for laboratory customers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck |
| Abcr |
| Achemtek |
| Tokyo Chemical Industry (TCI) |
| Matrix Scientific |
| Key Organics |
| Oakwood Products |
| Smolecule |
| Others |
Pricing and Supply Chain Analysis
Acetone spot-price indices on the US Gulf Coast and Rotterdam barge markets cascade directly into 1,3-Dichloroacetone production economics, compressing margins for intermediate-grade producers while pharmaceutical-grade suppliers buffer volatility through long-term chlorination feedstock contracts.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade quotations from unbundled technical-grade spot transactions. Three-tier pricing structure across pharmaceutical, reagent, and industrial grades reflects REACH dossier completion status and batch-level impurity documentation. Cost compression in intermediate tiers intensifies as Jiangsu Province environmental enforcement elevates per-unit compliance spend. Agrochemical formulators exhibit highest price sensitivity, while discovery-phase pharmaceutical buyers absorb premiums for rapid custom synthesis turnaround.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds for API starting materials redirect procurement toward Gujarat and Hyderabad production corridors. Feedstock flows draw from propylene derivative networks in China, South Korea, and Saudi Arabia. Single-source vulnerability concentrates in Jiangsu Province chlorination capacity exposed to MEE wastewater discharge enforcement. Distribution runs through regional warehouse networks anchored by Tokyo Chemical Industry in Osaka and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive chlorination assets has become the decisive competitive lever as REACH Tier III documentation requirements and EPA TSCA pre-manufacture notices fragment supplier qualification pools.
For Market Incumbents: Anchor qualification status through ISO-certified batch control investments and membrane-assisted reactive distillation deployment in Darmstadt or Bavarian production corridors. Trifluoroacetone substitution threats in agrochemical R&D pipelines demand accelerated ecotoxicity data generation for herbicide precursor contracts. Capacity rationalization in Jiangsu Province creates acquisition opportunities for compliant producers.
For New Entrants and Emerging Players: Capture Vietnam fine-chemical investment zone incentives near Ho Chi Minh City, leveraging five-year tax holidays and streamlined MEE-equivalent permitting for ASEAN pharmaceutical formulators. CDSCO fast-track API certification offers the most penetrable regulatory pathway for imported starting materials. Custom synthesis capabilities command premium positioning against catalog distributors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European reagent-grade specialists with incomplete REACH dossiers in Germany and France. Five-to-ten year viability hinges on biocatalytic halogenation technology maturation and membrane separation scale-up. Monitor flow chlorination technology adoption rates in Nantong industrial zones as inflection signal for cost-competitive intermediate production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorination Assets | Captive supply of chlorinated intermediates locks in REACH Tier III qualification with Bayer and Syngenta procurement teams. |
| Membrane-Assisted Reactive Distillation Deployment | Bavarian fine-chemical houses achieve pharmaceutical-grade purity without multiple crystallization steps, compressing working capital. |
| CDSCO Fast-Track API Certification | Streamlined qualification pathway reduces timeline uncertainty for foreign producers targeting Hyderabad generic drug manufacturers. |
| Flow Chlorination Technology Adoption | Continuous processing equipment in Nantong zones cuts acetone feedstock waste for herbicide precursor production. |
| Vietnam Fine-Chemical Investment Zone Entry | Five-year tax holidays near Ho Chi Minh City enable China-plus-one sourcing for ASEAN pharmaceutical formulators. |
Research Methodology
Trade statistics from China Customs, EUROSTAT chemical production databases, and USITC import records formed the secondary backbone, cross-referenced with primary interviews involving chlorination plant managers, agrochemical procurement leads at BASF and Corteva, fine-chemical distribution channel partners, and CDSCO regulatory affairs specialists. Bottom-up volume estimates from individual production facilities triangulated against top-down consumption models derived from downstream derivative demand.
Historical trendline analysis of acetone-to-chlorinated ketone price spreads anchored the projection framework across the analysis window. Segmentation modeling incorporated grade tier, end-use industry concentration, regional production hub classification, and chlorination technology type. CAGRs derived from weighted average growth rates across pharmaceutical discovery outsourcing, agrochemical contract manufacturing, and fine-chemical custom synthesis demand clusters.
The model holds under stable propylene derivative supply and continued REACH enforcement intensity; deviation in Jiangsu Province environmental shutdown frequency or trifluoroacetone substitution acceleration would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Dimethylformamide (DMF) Market