
 Anthracene Market | 2026-2036
Anthracene Market Size, Share, and Industry Trends Forecast 2026-2036
Anthracene Market Analysis
Specialty chemical synthesis revenue is tilting toward high-purity refined grades as downstream pharmaceutical and electronics applications tighten feedstock specifications. Merck KGaA leverages its analytical standards portfolio to anchor premium positioning in laboratory-grade anthracene supply. Tokyo Chemical Industry Co., Ltd. dominates Asia-Pacific distribution through localized synthesis capabilities and regional warehousing.
Anthracene is a tricyclic aromatic hydrocarbon with formula C₁₄H₁₀, occurring naturally in coal tar at concentrations of roughly one to two percent and produced industrially via fractional crystallization or catalytic dehydrogenation of anthracene oil; it serves primarily as a chemical intermediate for dyes, pigments, and scintillation crystals. Refined anthracene commands the dominant margin pool due to pharmaceutical-grade purity requirements, while synthetic anthracene represents the fastest-growing product type as producers seek independence from coal tar supply volatility. The dyes application segment retains mature volume leadership, though electronics end use is accelerating with organic semiconductor research.
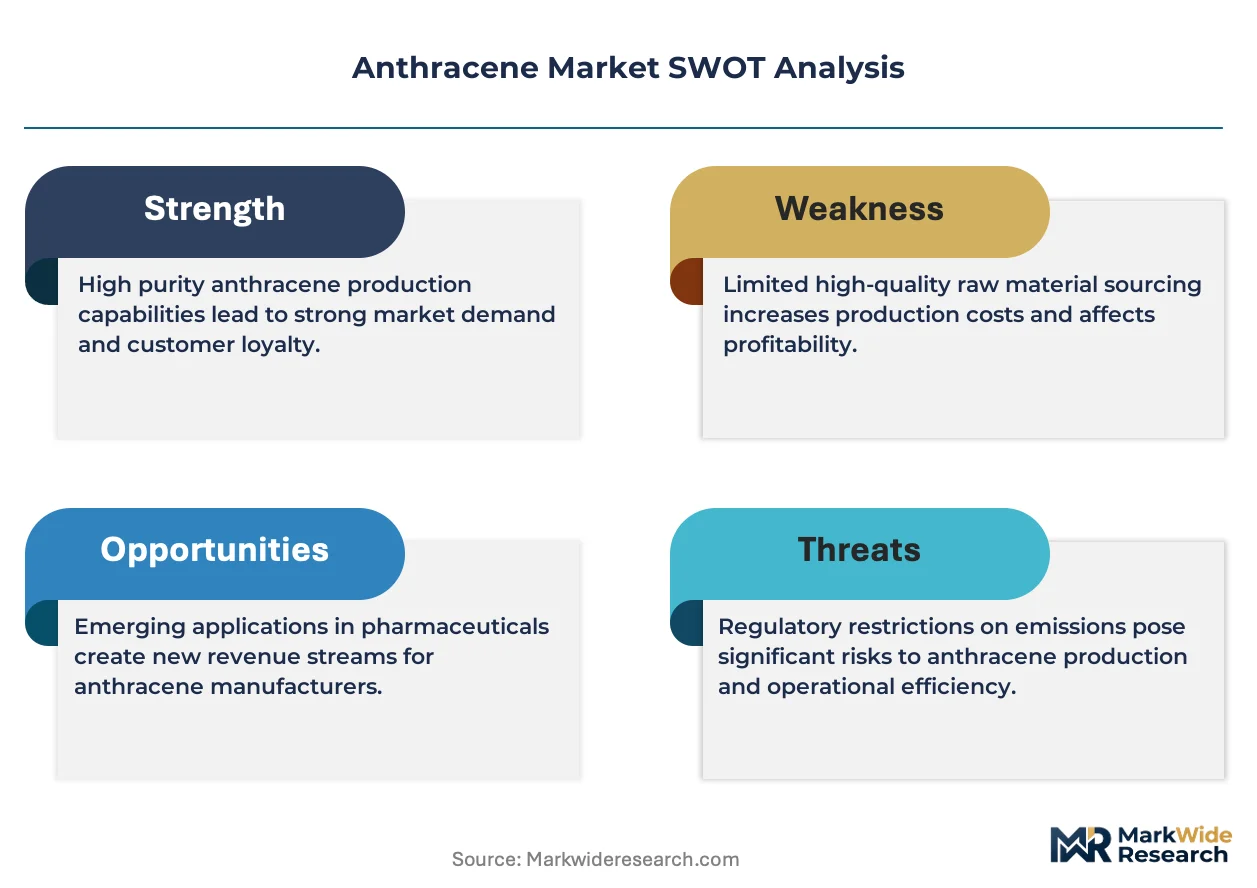
EPA oversight of polycyclic aromatic hydrocarbon emissions shapes US production facility permitting and wastewater discharge standards, while REACH registration in Europe mandates comprehensive toxicity dossiers for anthracene imports above one-ton thresholds. China's MEE enforces dual carbon goals that pressure coal tar distillers to upgrade emission controls or consolidate capacity. Stakeholders must monitor evolving purity certifications across jurisdictions to sustain market access and capture specification-driven premiums.
Market Dynamics
Coal tar supply volatility is compressing merchant anthracene availability as metallurgical coke production shifts toward electric arc furnace feedstocks, forcing downstream buyers to qualify synthetic alternatives or deepen relationships with integrated tar distillers.
Growth Catalysts
- Organic semiconductor R&D:Scintillation crystal manufacturers in Japan and South Korea are expanding pilot lines for radiation detection arrays, pulling pharmaceutical-grade anthracene through specialized chemical distributors.
- REACH Article 33 disclosure requirements:European electronics OEMs now document polycyclic aromatic hydrocarbon content in component supply chains, creating specification premiums for certified-low-impurity feedstock.
- Jiangsu province chemical cluster expansion:Integrated dye intermediates producers are absorbing locally refined anthracene output, reducing spot market liquidity but securing offtake for regional tar distillers.
Market Restraints
- Coal tar yield compression:Declining blast furnace operations in Germany and Poland are constraining anthracene oil feedstock availability, pushing European buyers toward Chinese imports with extended lead times.
- Substitution by pyrene derivatives:Fluorescent dye formulators in India are qualifying alternative polycyclic aromatic hydrocarbons for select colorant applications, eroding volume in mature pigment segments.
- ECHA SVHC listing friction:Anthracene's classification under REACH Candidate List obligations triggers downstream notification requirements that deter small-volume electronics assemblers from specification.
Strategic Opportunities
- Brazilian pharmaceutical manufacturing:ANVISA's accelerated API registration pathways are attracting contract synthesis investment, creating demand for GMP-certified anthracene as a photodimerization precursor.
- Synthetic anthracene process licensing:Catalytic dehydrogenation technology from petrochemical naphtha is virtualizing supply independence from coal tar, enabling regional production in hydrocarbon-rich jurisdictions.
- Dual carbon policy alignment:China's MEE carbon intensity benchmarks reward tar distillers with carbon capture retrofits, positioning compliant producers for preferential procurement by state-owned dye enterprises.
Industry Challenges
- Pharmaceutical-grade certification timelines:ICH Q7 compliance documentation for anthracene excipient qualification extends 18-24 months, straining working capital for specialty chemical distributors serving CDMOs.
- Analytical standards traceability:NIST-traceable reference material shortages for ultratrace PAH quantification are delaying purity verification protocols at third-party testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anthracene Market |
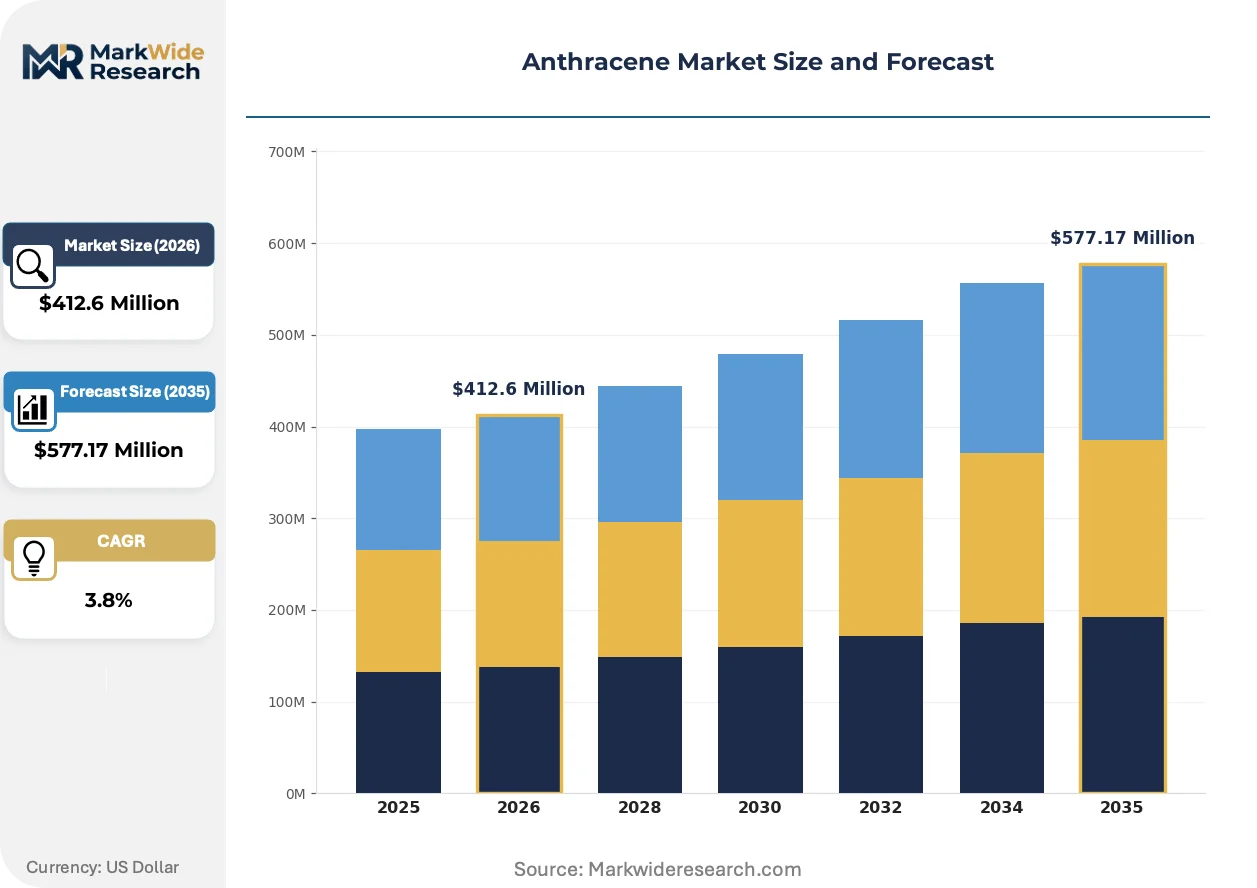
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $577.17 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Anthracene, Refined Anthracene, Anthracene Oil, Synthetic Anthracene Application: Dyes, Pigments, Plastics, Pharmaceuticals End Use Industry: Chemicals, Coatings, Rubber, Electronics Packaging Type: Bags, Drums, IBC Totes, Bulk |
| Companies Covered | Santa Cruz Biotechnology, Inc., Wego Chemical Group, Fisher Scientific, Spectrum Chemical, Glentham Life Sciences, Tokyo Chemical Industry Co., Ltd., Haihang Industry Co., Ltd., Merck KGaA, CHEMOS GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anthracene Market Emerging Trajectories
Digital process control and alternative feedstock chemistry are restructuring how anthracene purity grades are manufactured, certified, and contracted across fragmented regional supply bases.
Continuous crystallization systems with inline Raman spectroscopy are virtualizing real-time purity adjustment during anthracene oil fractionation. Japanese electronics chemical suppliers are deploying these units to reduce batch-to-batch variation for scintillation-grade material. The technology is compressing qualification cycles for pharmaceutical customers who previously required multiple pre-shipment samples.
REACH Annex XVII restrictions on PAH content in consumer articles are tightening import inspection protocols at Rotterdam and Hamburg. European dye distributors now require supplier-declared conformity certificates for anthracene-derived pigments entering toy and textile applications. This regulatory layer is favoring integrated producers with in-house toxicology dossiers over merchant traders.
Specification-driven procurement is consolidating buyer power among large dye houses and pharmaceutical CDMOs. Long-term offtake agreements with fixed purity bands are displacing spot market purchases in China's Shandong corridor. This behavioral shift is most visible among export-oriented intermediates producers seeking supply security for REACH-registered downstream derivatives.
Anthracene Market Segmentation
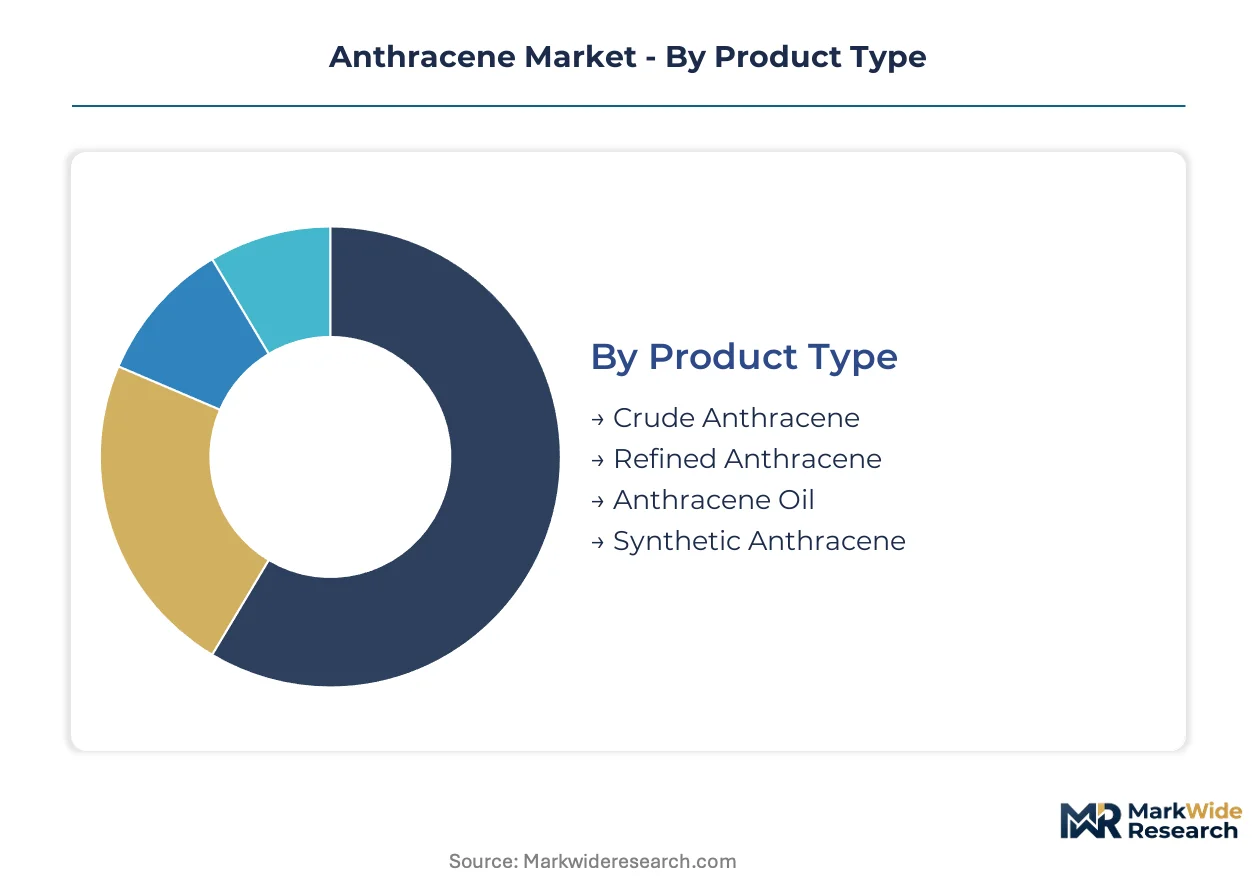
Anthracene market segmentation reflects divergent purity requirements and supply chain configurations across downstream applications. Specification tiers separate commodity chemical feedstocks from pharmaceutical-grade intermediates, creating distinct margin pools and qualification barriers.
Product Type:
Cost tier differentiation separates coal-tar-derived materials from synthetic alternatives, with purity premiums widening as downstream applications tighten feedstock specifications.
- Refined Anthracene:Pharmaceutical-grade material achieves purity thresholds exceeding 99.9% through multi-stage crystallization and solvent washing. Demand concentrates in Japanese and South Korean scintillation crystal manufacturing, where radiation detection arrays require ultralow polycyclic aromatic hydrocarbon contamination. REACH Article 33 disclosure obligations in Europe are amplifying specification premiums for certified-low-impurity grades.
- Synthetic Anthracene:Catalytic dehydrogenation of petrochemical naphtha yields supply independence from metallurgical coke volatility. Production is scaling in hydrocarbon-rich jurisdictions seeking captive anthracene supply for dye intermediate manufacturing. The technology is compressing lead times for buyers previously dependent on Chinese coal tar distillate imports.
- Crude Anthracene:One to two percent concentration in coal tar requires fractional crystallization for upgrade. Jiangsu province chemical clusters absorb regional output for captive dye intermediate production.
- Anthracene Oil:Distillate fraction from coal tar refining serves as feedstock for further purification or direct use in heavy carbon black applications. German and Polish blast furnace decline is constraining European availability.
Refined anthracene holds installed capacity. Synthetic anthracene is rotating up the share rankings.
Application:
Application segmentation tracks maturity gradients across colorant chemistry, polymer additives, and active pharmaceutical ingredient synthesis.
- Dyes:Anthraquinone derivatives dominate vat and disperse dye production for textile applications. Shandong province intermediates producers are securing long-term offtake agreements with fixed purity bands, reducing spot market liquidity. China's state-owned dye enterprises are prioritizing procurement from tar distillers with MEE carbon capture retrofits.
- Pharmaceuticals:Photodimerization precursors for API synthesis require GMP certification and ICH Q7 compliance documentation extending 18-24 months. Brazilian ANVISA accelerated registration pathways are attracting contract synthesis investment, pulling certified feedstock through specialized distributors.
- Pigments:Carbon black feedstock applications face substitution pressure from pyrene derivatives in Indian fluorescent dye formulation. REACH Annex XVII restrictions on PAH content in consumer articles are tightening import inspection protocols at Rotterdam and Hamburg.
- Plastics:UV stabilizer and polymer additive applications utilize lower-purity grades with less stringent toxicity dossier requirements.
Dyes retain volume leadership. Pharmaceuticals is gaining share fastest.
End Use Industry:
End use concentration varies by regional industrial structure, with electronics and coatings showing divergent specification trajectories.
- Chemicals:Integrated dye intermediates producers in China's manufacturing corridors consume the majority of merchant anthracene output. Regional warehousing by Tokyo Chemical Industry Co. anchors Asia-Pacific distribution.
- Electronics:Organic semiconductor R&D in Japan and South Korea is expanding pilot lines for radiation detection arrays. Scintillation-grade material requires batch-to-batch variation control through inline Raman spectroscopy during crystallization.
- Coatings:Industrial and automotive coating applications drive steady demand for pigment-grade material with moderate purity requirements.
- Rubber:Carbon black reinforcement applications utilize anthracene oil derivatives in tire manufacturing.
Chemicals holds installed capacity. Electronics is rotating up the share rankings.
Packaging Type:
Packaging segmentation reflects shipment scale economics and contamination risk management across purity grades.
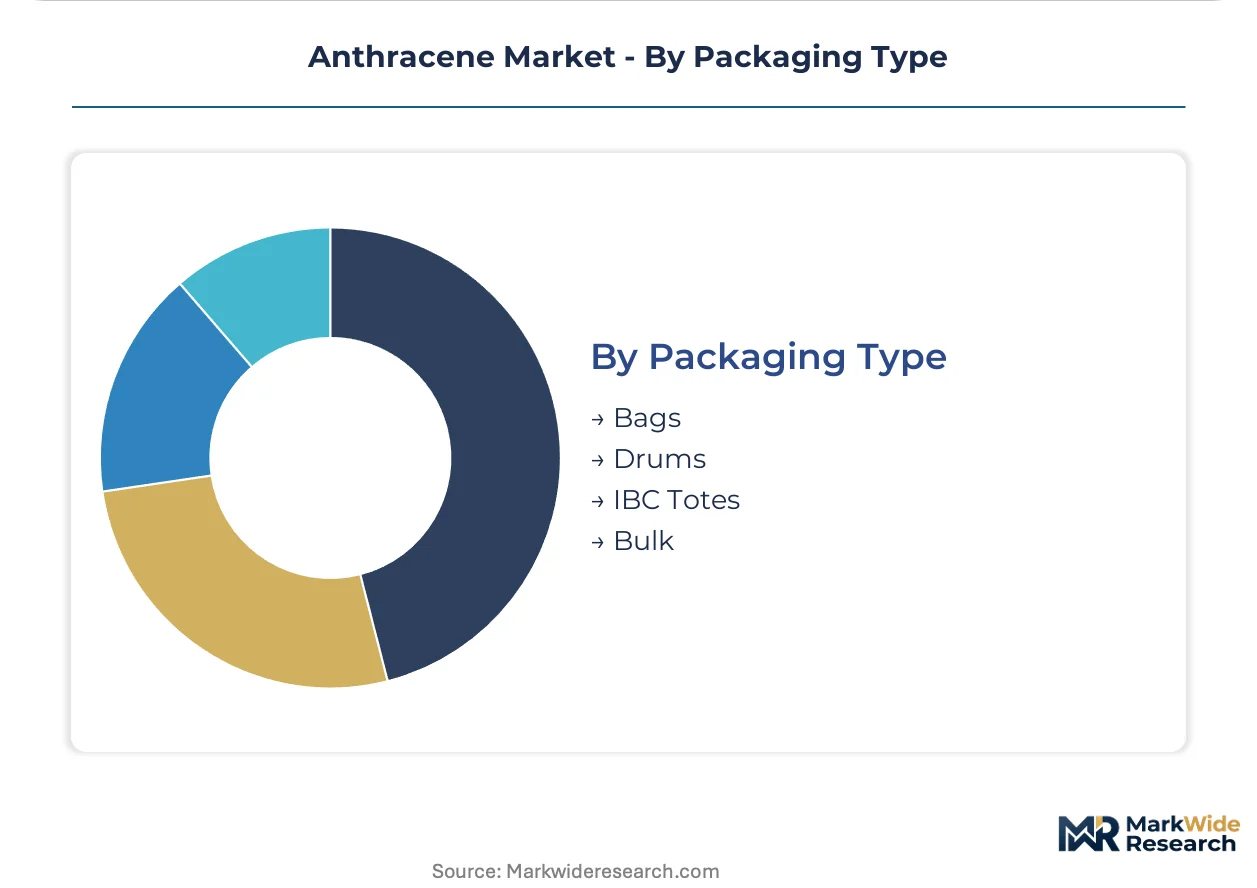
- Bulk:Tanker and railcar delivery serves high-volume dye intermediates producers with dedicated handling infrastructure. Jiangsu and Shandong chemical clusters favor this format for integrated operations.
- Drums:Steel and fiber drums dominate pharmaceutical-grade shipments requiring lot traceability and sealed containment. Merck KGaA leverages this format for analytical standards portfolio distribution.
- IBC Totes:Intermediate bulk containers serve mid-scale specialty chemical distributors serving CDMOs with variable offtake patterns.
- Bags:Multi-wall paper and woven polypropylene bags handle lower-purity pigment and plastics additive grades.
Bulk holds installed capacity. Drums is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's fluorescent dye sector exhibit acute price sensitivity to pyrene substitution, while Japanese scintillation crystal manufacturers absorb substantial purity premiums without volume elasticity. European electronics OEMs occupy the middle ground, trading compliance documentation for specification security.
China
Jiangsu and Shandong province chemical clusters absorb the majority of regional anthracene output for captive dye intermediate production. MEE dual carbon goals pressure coal tar distillers to upgrade emission controls or consolidate capacity. State-owned dye enterprises now prioritize procurement from tar distillers with carbon capture retrofits, reshaping supplier qualification protocols.
Japan
Scintillation crystal manufacturers in Japan are expanding pilot lines for radiation detection arrays, pulling pharmaceutical-grade anthracene through specialized chemical distributors. METI industrial standards govern polycyclic aromatic hydrocarbon purity thresholds for electronics feedstock. Kanto region electronics chemical suppliers deploy continuous crystallization systems with inline Raman spectroscopy to reduce batch-to-batch variation.
Germany
Declining blast furnace operations in Germany's Ruhr industrial belt are constraining anthracene oil feedstock availability from domestic metallurgical coke production. ECHA REACH Candidate List obligations trigger downstream notification requirements that deter small-volume electronics assemblers from anthracene specification. Hamburg port authorities now enforce tightened import inspection protocols for PAH content under Annex XVII restrictions.
United States
EPA oversight of polycyclic aromatic hydrocarbon emissions shapes production facility permitting and wastewater discharge standards for remaining coal tar distillation capacity. Gulf Coast petrochemical complexes are evaluating synthetic anthracene process licensing from naphtha feedstock to virtualize supply independence. Specialty chemical distributors serving pharmaceutical CDMOs face extended ICH Q7 compliance documentation timelines straining working capital.
Brazil
ANVISA's accelerated API registration pathways are attracting contract synthesis investment, creating demand for GMP-certified anthracene as a photodimerization precursor. São Paulo state pharmaceutical manufacturing corridors represent the primary demand concentration. Domestic supply gaps force Brazilian distributors to qualify Asian imports with extended lead times and enhanced purity certification requirements.
Anthracene Market Vendor Landscape
Capability concentration sits with laboratory-grade specialists commanding specification premiums; scale advantage sits with integrated tar distillers feeding regional dye clusters. The market structures around three tiers: multinational analytical standards houses, Asia-Pacific synthesis-and-distribution platforms, and regional merchant traders. Strategic moves center on synthetic process licensing for supply independence and long-term offtake agreements with fixed purity bands displacing spot market liquidity.
Among Germany-based chemical suppliers, Merck KGaA and CHEMOS GmbH & Co. KG occupy positions anchoring premium laboratory-grade supply. Tokyo Chemical Industry Co., Ltd. exemplifies the Asia-Pacific synthesis-and-distribution archetype through localized production and regional warehousing. Santa Cruz Biotechnology, Inc. represents the North American life sciences reagent specialist tier. These three company structures illustrate how geographic origin and corporate suffix signal divergent competitive positioning across purity grades and end-use specifications.
| Leading Market Players |
|---|
| Santa Cruz Biotechnology, Inc. |
| Wego Chemical Group |
| Fisher Scientific |
| Spectrum Chemical |
| Glentham Life Sciences |
| Tokyo Chemical Industry Co., Ltd. |
| Haihang Industry Co., Ltd. |
| Merck KGaA |
| CHEMOS GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Jiangsu province chemical clusters concentrate anthracene refining capacity, feeding captive dye intermediate operations that compress spot market liquidity and transfer pricing power toward integrated producers with long-term offtake agreements. This geographic concentration enables specification-driven premiums for REACH-compliant grades while synthetic alternatives from naphtha feedstock disrupt traditional coal-tar-based cost structures.
Pricing Analysis
After-sales certification services and ICH Q7 compliance documentation drive lifetime value for pharmaceutical-grade anthracene suppliers. Three-tier pricing structure across refined, synthetic, and crude grades separates premium scintillation-crystal material from standard dye-intermediate feedstock. Price differentiation centers on purity certification and carbon-capture retrofit credentials under China's MEE dual carbon policy. Cost compression in crude anthracene intensifies because declining European blast furnace operations constrain anthracene oil availability. Indian fluorescent dye formulators exhibit acute price sensitivity, while Japanese scintillation crystal manufacturers absorb substantial purity premiums without volume elasticity.
Supply Chain Analysis
Anthracene oil from metallurgical coke production draws from China, Germany, and Poland as primary upstream feedstock sources. Coal tar distillation, catalytic dehydrogenation of naphtha, and fractional crystallization equipment constitute critical input dependencies. Single-source vulnerability runs through Jiangsu and Shandong province integrated dye clusters where state-owned enterprises prioritize carbon-capture-compliant suppliers. Distribution runs through specialized chemical distributors for pharmaceutical-grade material and bulk tanker delivery for high-volume dye intermediates producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anthracene supply is approaching a platform-economics inflection as REACH Article 33 disclosure requirements and ICH Q7 certification protocols create interoperability standards that favor integrated producers with in-house toxicology dossiers over merchant traders.
For Market Incumbents: Build certification moats through ICH Q7 compliance documentation and REACH-registered derivative portfolios that lock in pharmaceutical CDMO relationships. Deepen backward integration into synthetic anthracene production via catalytic dehydrogenation licensing to virtualize supply independence from coal tar volatility. Capture preferential procurement status with China's state-owned dye enterprises by completing MEE carbon capture retrofits ahead of consolidation mandates. For New Entrants and Emerging Players: Synthetic anthracene production in hydrocarbon-rich jurisdictions with underdeveloped dye intermediate manufacturing represents the most penetrable entry point for supply-independent capacity. Brazilian pharmaceutical manufacturing corridors offer white-space demand as ANVISA accelerated API registration pathways attract contract synthesis investment without entrenched supplier relationships. Deploy direct technical sales teams to CDMOs facing 18-24 month qualification timelines with incumbent distributors. For Investors and Strategic Acquirers: Long-term, this sits as a specification-premium consolidation play because laboratory-grade analytical standards and pharmaceutical-grade purification capabilities concentrate margin capture with specialists commanding NIST-traceable reference material positions. Target acquisition archetypes include regional tar distillers with carbon-capture retrofit completion certificates and specialized distributors with established ICH Q7 documentation workflows. Watch synthetic anthracene process licensing announcements as inflection indicators for supply structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Feedstock | Catalytic dehydrogenation licensing from naphtha virtualizes supply independence from coal tar volatility. |
| Carbon Capture Retrofit Completion | MEE dual carbon compliance positions tar distillers for preferential procurement by state-owned dye enterprises. |
| Long-term Offtake Agreement Structuring | Fixed purity band contracts displace spot market liquidity in Shandong corridor chemical clusters. |
| ICH Q7 Certification Investment | Pharmaceutical-grade documentation workflows capture CDMO relationships with 18-24 month qualification barriers. |
| Joint Venture with Electronics Chemical Suppliers | Inline Raman spectroscopy deployment reduces batch-to-batch variation for scintillation-grade material. |
Methodological Framework
Cross-validation between primary interviews with coal tar distillation plant managers, pharmaceutical procurement leads at CDMOs, and specialty chemical distribution channel partners anchors the qualitative findings against secondary validation from customs trade data, ECHA REACH registration databases, and SEC filings of publicly listed chemical producers. Bottom-up capacity assessments across Jiangsu and Shandong province clusters were triangulated with top-down demand modeling from dye intermediate production statistics and scintillation crystal manufacturing expansion announcements.
Calibration against historical purity premium realizations and synthetic process licensing transaction patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, packaging format, and regional production hub with carbon compliance status. CAGRs were derived from elasticity-adjusted demand projections incorporating substitution dynamics from pyrene derivatives and regulatory threshold effects from REACH Annex XVII restrictions.
Stress conditions across coal tar yield compression, synthetic process cost curves, and MEE enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding blast furnace operation trajectories and pharmaceutical CDMO qualification timeline stability. Cross-checking against ECHA registration volume trends and ANVISA API approval pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
US Humate Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Benzethonium Chloride Market