
 APAC Container Technology Market | 2026-2036
APAC Container Technology Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Container Technology Market Analysis
The gap between enterprise-grade container orchestration and basic runtime packaging is shifting wider across APAC procurement cycles. Docker sustains its developer-centric footprint through lightweight runtime tooling favored by early-stage software shops. Amazon Web Services dominates cloud-native deployments with managed Kubernetes services across Singapore, Sydney, and Tokyo regions. Red Hat differentiates through OpenShift's integrated DevOps pipelines that appeal to regulated BFSI workloads in Australia and India.
Container technology encapsulates application code with dependencies into portable, isolated units that execute consistently across computing environments using Linux kernel features such as cgroups and namespaces. The technology eliminates environment-specific failures by abstracting infrastructure heterogeneity, enabling IT services and telecommunications operators to deploy microservices architectures at scale. Cloud-based deployment leads value generation as hyperscalers expand managed container offerings across Southeast Asian data center zones. Kubernetes anchors the technology layer with the broadest ecosystem traction, while Docker retains relevance at the runtime edge for simpler workload portability. The DevOps use case captures the fastest expansion as banks and telecom carriers automate CI/CD pipelines for regulatory release velocity.
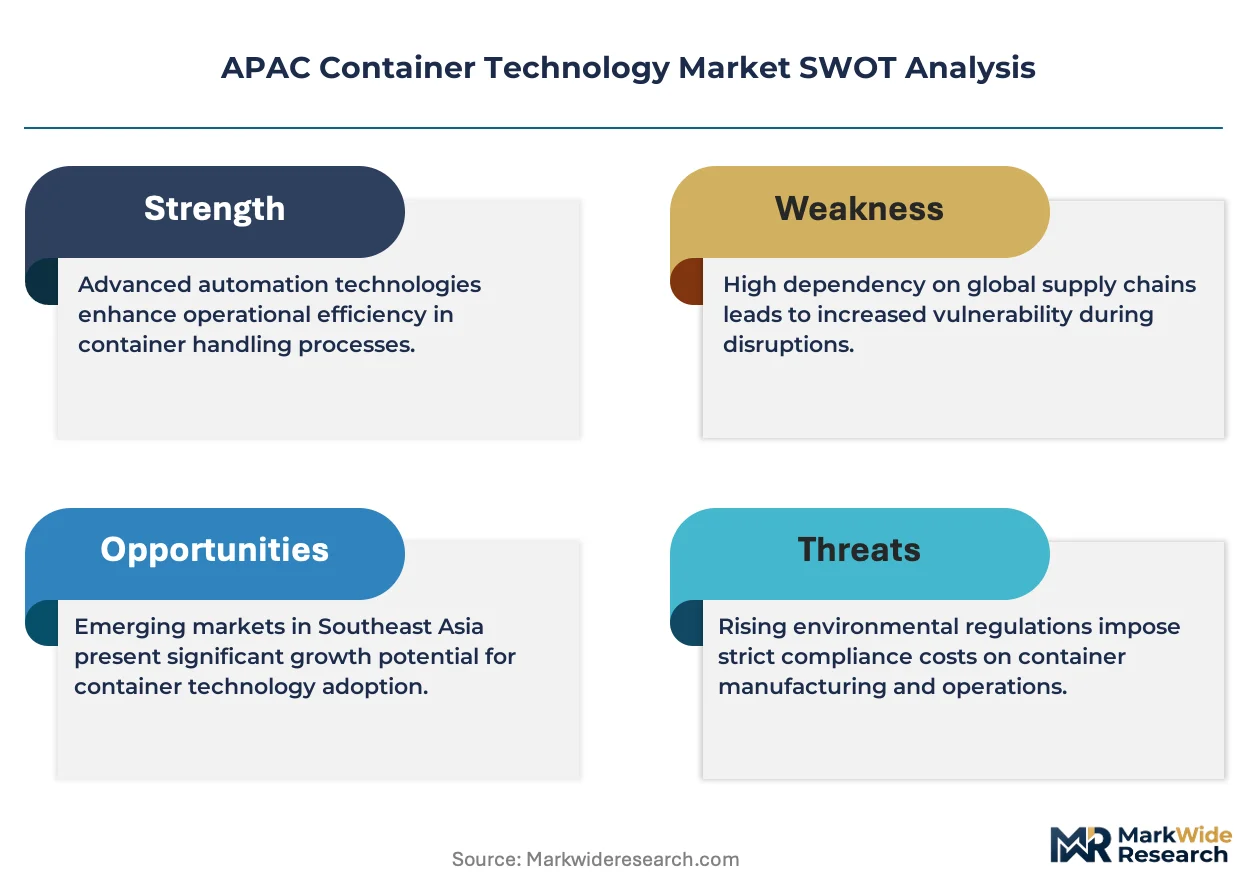
Australia's Privacy Act enforcement through the OAIC, India's BIS cloud security certification mandates, and Japan's METI data governance guidelines collectively shape product standards and procurement criteria for container platforms. Compliance with these frameworks determines market access for vendors serving BFSI and healthcare end users across the region. Stakeholders must monitor evolving data residency rules that could fragment multi-cloud container strategies into jurisdiction-specific deployments.
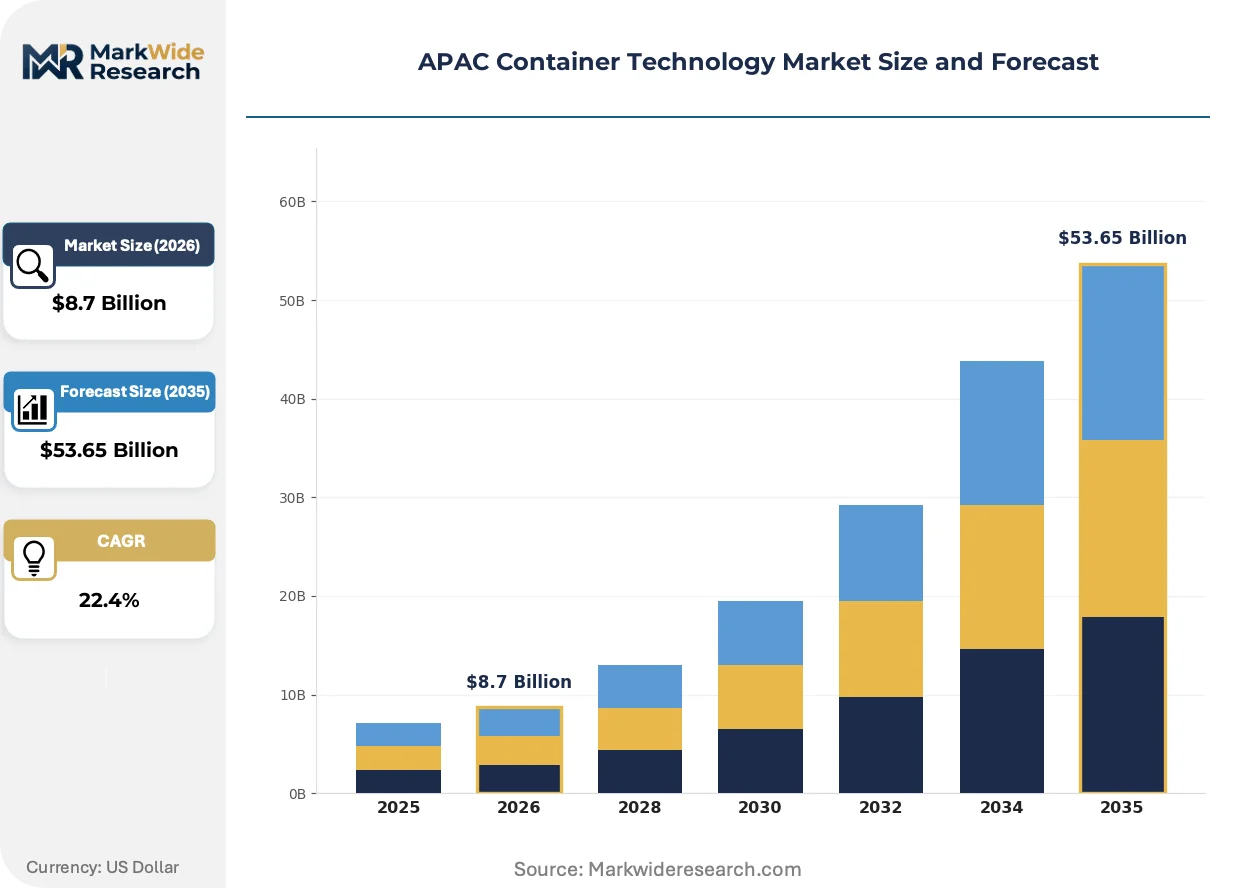
Market Dynamics
The convergence of India's BIS cloud security certification mandates and Australia's Privacy Act amendments is compressing procurement cycles for compliant container platforms across financial services and healthcare verticals.
Growth Catalysts
- BIS cloud security guidelines:India's mandatory certification for cloud service providers is accelerating compliance-driven container adoption among IT services firms operating captive platforms in the Bengaluru-Chennai corridor.
- Real-time payment infrastructure:Financial services firms in Singapore and Sydney are deploying Kubernetes clusters to process high-velocity transactions, creating sustained demand for orchestration expertise.
- Microservices architecture migration:Telecommunications operators across Southeast Asian data center zones are containerizing network functions to achieve elastic scaling and reduced deployment friction.
Market Restraints
- Specialized talent scarcity:Certified Kubernetes administrators and DevOps engineers command premium compensation in Sydney and Singapore, inflating operational costs for platform operators.
- Hyperscaler dependency:Managed container services concentrate within AWS, Azure, and Google Cloud regions, creating vendor lock-in risks for multi-cloud strategies.
- Data residency fragmentation:Evolving jurisdiction-specific storage rules are forcing redundant container deployments across Singapore, Australia, and India rather than unified regional architectures.
Strategic Opportunities
- Indonesia's digital banking expansion:Unmet container orchestration demand exists among emerging fintechs in Jakarta seeking compliant alternatives to hyperscaler-managed services.
- Edge container convergence:Integration of lightweight Kubernetes distributions with 5G network edge nodes is enabling low-latency workloads for industrial IoT applications in Japan and South Korea.
- PLI scheme alignment:India's production-linked incentive schemes for electronics manufacturing are attracting container platform investments to support domestic cloud infrastructure buildout.
Industry Challenges
- Legacy system integration complexity:Mainframe-dependent banks in Australia and Japan face extended migration timelines when containerizing core banking functions without disrupting regulatory reporting.
- Cross-border certification reciprocity gaps:Australia's OAIC enforcement standards and India's BIS frameworks lack mutual recognition, forcing vendors to duplicate compliance audits for multi-country deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Container Technology Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Multi-cloud Technology: Docker, Kubernetes, OpenShift, Mesos Use Case: DevOps, Microservices, Application Modernization, Continuous Delivery End User: IT Services, BFSI, Telecommunications, Healthcare |
| Companies Covered | Docker, Amazon Web Services, Red Hat, Microsoft, IBM Corporation, Cisco, VMware, CoreOS, Mesosphere, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Container Technology Market Emerging Trajectories
Container runtime architectures are bifurcating between developer-centric simplicity and enterprise-grade orchestration, with regulatory compliance emerging as the decisive procurement filter across APAC financial services.
WebAssembly (Wasm) runtimes are integrating with Kubernetes control planes to enable near-native performance for sandboxed workloads. Australian banks and Indian IT services firms are piloting Wasm modules for payment processing functions that demand sub-millisecond cold-start latency. This convergence is compressing the traditional boundary between container and virtual machine deployment models.
Australia's Privacy Act amendments enforced through the OAIC are mandating encryption-at-rest and audit logging capabilities for all cloud-hosted customer data. Container platform vendors must embed these controls into base images to maintain eligibility for BFSI procurement in Sydney and Melbourne. Healthcare providers in Queensland are delaying Kubernetes migrations until certified compliant distributions reach market.
Buyers in Singapore and Hong Kong are consolidating vendor relationships around integrated DevOps platforms rather than assembling best-of-breed tooling. Financial services procurement teams now require single-vendor accountability for CI/CD pipelines, container registries, and runtime security. This concentration favors platform providers with localized support presence over pure-play orchestration specialists.
APAC Container Technology Market Segmentation
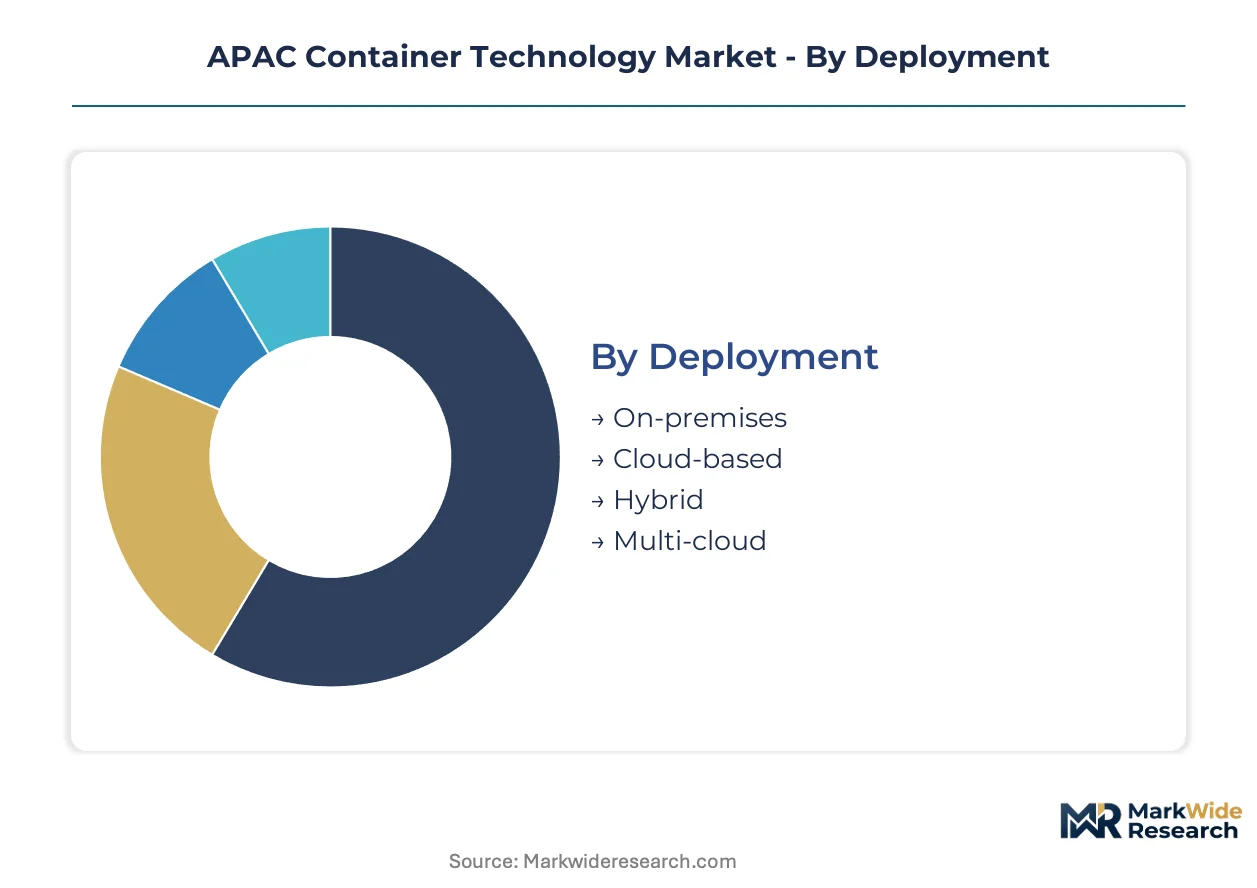
Container technology procurement across APAC splits sharply between capital-heavy private infrastructure and operational expenditure cloud models. Financial services and telecommunications operators drive segment selection through compliance mandates and latency requirements that dictate deployment architecture choices.
Deployment:
Capital intensity peaks with on-premises infrastructure requiring dedicated hardware, data center buildout, and specialized engineering teams before workload deployment.
- Cloud-based:Hyperscaler-managed Kubernetes services eliminate upfront infrastructure investment while shifting operational costs to consumption-based billing. Singapore and Sydney financial services firms favor this model for real-time payment processing where AWS, Azure, and Google Cloud maintain dedicated regions.
- Hybrid:Workloads split between private data centers and public cloud based on data sensitivity, with regulated BFSI workloads remaining on-premises while customer-facing applications burst to cloud. Australia's Privacy Act amendments and India's BIS guidelines accelerate this bifurcated approach.
- On-premises:Captive container platforms in Bengaluru and Chennai IT services corridors demand substantial capital allocation for server clusters, networking gear, and facility security certification.
- Multi-cloud:Distribution across AWS, Azure, and Alibaba Cloud regions mitigates vendor concentration risk but multiplies integration complexity and operational overhead.
Cloud-based deployments absorb the bulk of installed capacity; hybrid architectures are expanding most quickly as regulatory frameworks harden data residency requirements.
Technology:
Engineering talent density and certification availability determine which technology layers command premium implementation costs versus commodity runtime tooling.
- Kubernetes:The dominant orchestration layer automates container deployment, scaling, and management across distributed clusters. Sydney and Singapore banks deploy certified Kubernetes administrators at premium compensation to maintain payment processing uptime.
- Docker:Lightweight runtime packaging remains the developer standard for local development and simple workload portability, particularly among early-stage software shops in India's IT corridor.
- OpenShift:Red Hat's integrated platform embeds DevOps pipelines and security controls that satisfy Australian OAIC enforcement and Indian BIS certification mandates for regulated workloads.
- Mesos:Legacy two-level scheduling persists in specific telecommunications deployments but faces displacement as Kubernetes ecosystem maturity accelerates.
Kubernetes anchors the majority of production deployments; OpenShift is gaining share fastest among compliance-sensitive BFSI procurement cycles.
Use Case:
Organizational maturity and automation ambition separate basic containerization from full pipeline transformation.
- DevOps:CI/CD pipeline automation demands integrated tooling across source control, build systems, container registries, and runtime orchestration. Australian banks and Japanese telecommunications carriers prioritize this use case for regulatory release velocity.
- Microservices:Decomposition of monolithic applications into independently deployable services enables elastic scaling and team autonomy. Southeast Asian data center operators containerize network functions to achieve deployment friction reduction.
- Application Modernization:Lift-and-shift migration of legacy workloads into containers without architectural reengineering delivers limited value but serves as an intermediate step for mainframe-dependent institutions.
- Continuous Delivery:Automated deployment pipelines extending through production environments require sophisticated testing and rollback capabilities that mature IT services firms in India are building for captive platforms.
DevOps automation captures the steepest expansion trajectory; microservices deployment holds the largest installed base among telecommunications and financial services operators.
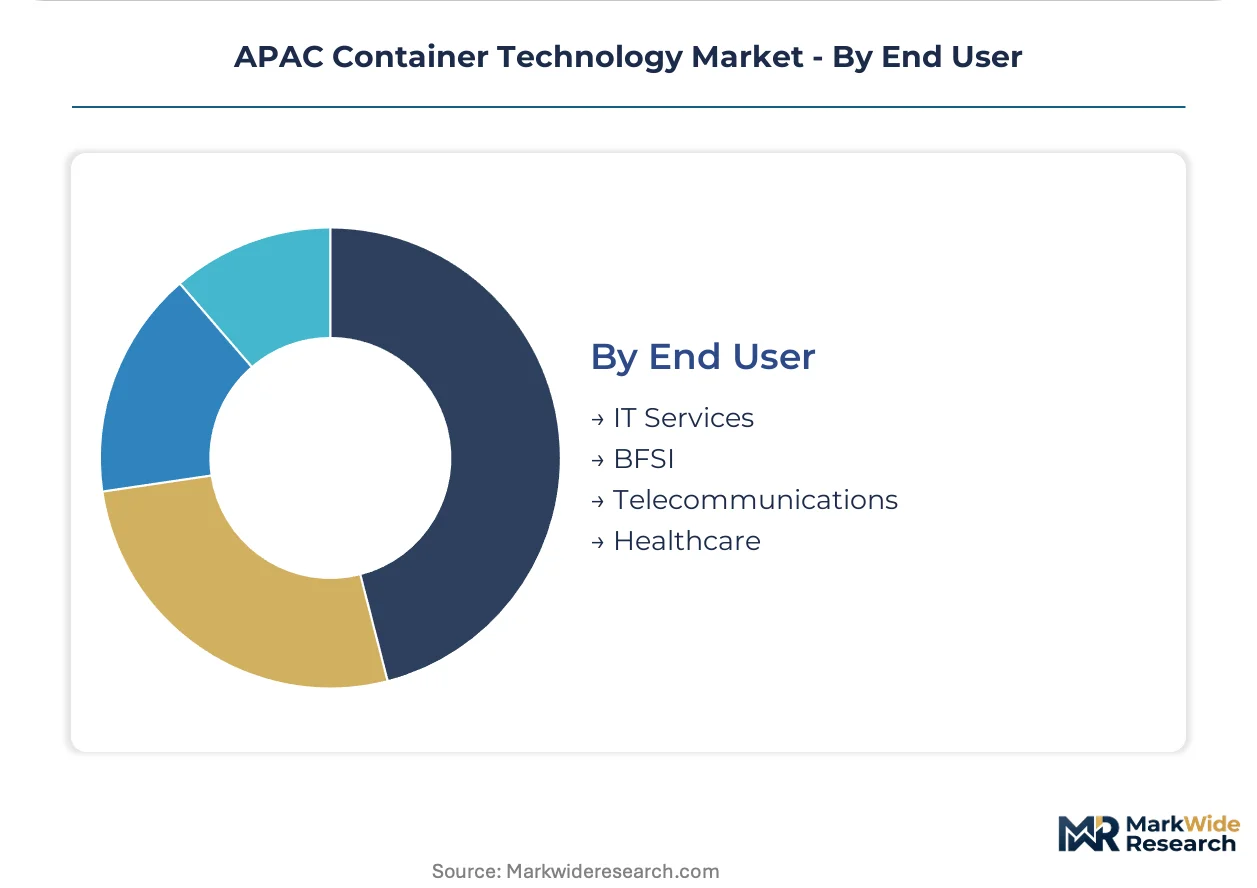
End User:
Regulatory exposure and transaction velocity create divergent procurement specifications across verticals.
- IT Services:Captive container platforms in Bengaluru-Chennai corridor support multi-tenant delivery for global enterprise clients, with BIS cloud security certification becoming mandatory for government contract eligibility.
- BFSI:Real-time payment processing in Singapore and Sydney demands sub-millisecond latency with full audit logging and encryption-at-rest mandated by Australia's OAIC and India's RBI guidelines.
- Telecommunications:5G network function virtualization across Southeast Asian data centers requires elastic scaling and edge deployment capabilities.
- Healthcare:Queensland providers delay Kubernetes migrations until certified compliant distributions satisfy patient data protection requirements under Australia's Privacy Act amendments.
IT Services maintains the broadest deployment footprint; BFSI is climbing the fastest as payment modernization accelerates across Singapore, Sydney, and emerging Jakarta fintechs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bengaluru-Chennai corridor anchors container technology deployment across Asia-Pacific, hosting captive platforms for IT services giants that process workloads for global financial services clients. Singapore and Sydney financial districts drive real-time payment infrastructure demand. Regulatory fragmentation between India's BIS mandates, Australia's Privacy Act amendments, and Japan's METI guidelines shapes procurement criteria across the region.
India
IT services firms operate captive container platforms across the Bengaluru-Chennai corridor to serve multi-tenant enterprise clients with BIS cloud security certification now mandatory for government contract eligibility. The RBI guidelines for financial data localization accelerate on-premises Kubernetes deployments among payment processors. Hyderabad and Pune emerging technology clusters attract DevOps engineering talent for platform operations.
Australia
Sydney and Melbourne financial services firms deploy Kubernetes clusters for real-time payment processing with OAIC enforcement mandating encryption-at-rest and audit logging capabilities. The Privacy Act amendments compress procurement cycles for compliant container platforms across BFSI and healthcare verticals. Queensland healthcare providers delay migrations until certified distributions satisfy patient data protection requirements.
Singapore
Financial institutions deploy managed Kubernetes services across AWS, Azure, and Google Cloud dedicated regions for high-velocity transaction processing with sub-millisecond latency requirements. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria for cloud-native infrastructure. Marina Bay financial district concentration drives demand for localized DevOps support presence.
Japan
Telecommunications carriers containerize 5G network functions across Tokyo-Osaka data center zones with METI data governance guidelines influencing platform procurement standards. Manufacturing enterprises pilot edge Kubernetes distributions for industrial IoT applications requiring low-latency processing. Nagoya industrial corridor demand concentrates among automotive supply chain digitization initiatives.
APAC Container Technology Market Vendor Landscape
Capital-heavy infrastructure vendors compete with asset-light platform specialists across Asia-Pacific container technology procurement. The vendor base splits between hyperscaler-managed services, integrated enterprise platforms, and developer-centric runtime tooling. Three strategic archetypes dominate: cloud-native orchestration providers, compliance-embedded DevOps platforms, and lightweight runtime specialists. Competitive moves concentrate on geographic certification expansion and localized support infrastructure buildout.
Within the integrated enterprise platform tier, Red Hat and IBM Corporation exemplify vendors embedding regulatory controls directly into base images for BFSI compliance. Amazon Web Services anchors the hyperscaler-managed services segment with dedicated region presence across Singapore, Sydney, and Tokyo. Docker occupies the developer-centric runtime edge for simpler workload portability among early-stage software shops in India's IT corridor.
| Leading Market Players |
|---|
| Docker |
| Amazon Web Services |
| Red Hat |
| Microsoft |
| IBM Corporation |
| Cisco |
| VMware |
| CoreOS |
| Mesosphere |
| Others |
Supply Flow & Price Mechanics
Certified Kubernetes administrators concentrated in Sydney and Singapore command premium compensation that compresses margins for platform operators, widening pricing-tier spreads between enterprise-grade orchestration and developer-centric runtime tooling across APAC procurement cycles.
Pricing Analysis
Uptime guarantees anchor value-based pricing for managed Kubernetes services serving Singapore and Sydney financial services firms processing real-time payments. Pricing stratifies across premium certified distributions, standard managed services, and economy self-hosted tiers, with BIS and OAIC compliance certification commanding substantial premiums. Cost compression in the economy tier is intensifying as Indian IT services firms automate captive platform operations. Early-stage software shops in Bengaluru exhibit highest price sensitivity, while Australian BFSI procurement teams prioritize compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler-managed Kubernetes control planes concentrated in AWS, Azure, and Google Cloud regions across Singapore, Sydney, and Tokyo. Container runtime distributions draw from open-source upstream projects, commercial Linux kernel maintainers, and specialized hardware security module providers. Tariff exposure on semiconductor components for data center infrastructure creates procurement uncertainty for on-premises deployments. Distribution runs through direct enterprise sales teams, systems integrators in the Bengaluru-Chennai corridor, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS cloud security certification mandates erect a cost-of-compliance barrier that favors incumbent vendors with established audit infrastructure and regulatory relationships.
For Market Incumbents: To counter emerging fintechs in Jakarta seeking compliant alternatives to hyperscaler-managed services, deepen certification coverage across India's BIS framework and Australia's OAIC enforcement standards while expanding localized DevOps support presence in Southeast Asian financial districts. For New Entrants and Emerging Players: Systems integrators in Indonesia's digital banking expansion represent the most penetrable channel partnership, offering white-label container platform deployment without hyperscaler dependency. Target unmet demand among emerging fintechs seeking compliant orchestration alternatives with bundled compliance-as-a-service positioning. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platform specialists with embedded regulatory controls and captive engineering talent pools. Long-term viability hinges on certification moat durability across fragmented APAC compliance regimes. Watch for BIS-OAIC mutual recognition agreements as inflection indicators for multi-country deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Expansion | BIS and OAIC compliance coverage unlocks government and BFSI procurement eligibility across India and Australia. |
| Localized Support Infrastructure | Marina Bay and Sydney presence satisfies financial services requirements for sub-hour incident response. |
| Edge Kubernetes Integration | 5G network function containerization captures telecommunications demand across Tokyo-Osaka zones. |
| WebAssembly Runtime Development | Sub-millisecond cold-start capabilities differentiate payment processing offerings for Singapore banks. |
| Hybrid Cloud Platform | Split workload management addresses Australia's Privacy Act data residency fragmentation. |
Methodological Framework
SEC filings from hyperscaler cloud providers, BIS certification registries, and OAIC enforcement determinations formed the secondary backbone, cross-referenced against primary interviews with Kubernetes platform engineers, DevOps directors at Australian banks, regulatory compliance officers, and IT services procurement leads in the Bengaluru-Chennai corridor. Bottom-up and top-down triangulation validated deployment volume estimates across cloud, hybrid, and on-premises segments.
Bottom-up modeling aggregated cluster deployment counts by region and vertical, while top-down analysis tracked hyperscaler capex disclosures and managed services revenue attribution. Segmentation dimensions included deployment model, orchestration technology layer, compliance certification tier, and end-user vertical across the projection horizon. CAGRs derived from regression analysis against historical infrastructure software adoption curves, with inputs from telecommunications 5G rollout timelines and financial services payment modernization programs.
Caveats apply where BIS-OAIC regulatory reciprocity agreements or METI data governance revisions could materially shift the outlook for multi-country platform deployments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Shipping Container Liners Market
Containers
Wide Mouth Jars Market
Containers
Disposable Cups and Lids Market
Containers
Collapsible Food Packaging Containers Market
Containers
Vacuum Formed Tray Market
Containers
Tottle Containers Market
Containers
Acrylic Container Market
Containers
Thin Wall Containers Market
Containers
Wooden Barrels Market
Containers
Global Flexitanks Market
Containers
Jug Shipper Market
Containers
Child-Resistant Containers Market
Containers
Oblong Jar Market
Containers
Corrugated Open-Head Drums Market
Containers
North America Plastic Bottles and Containers Market
Containers
Cylindrical Cans Market