
 Latin America Injection Molding Machines Market | 2026-2036
Latin America Injection Molding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Injection Molding Machines Market Foresight
CE marking compliance for machinery exports is bifurcating the competitive landscape between qualified and non-qualified suppliers. Haitian International leverages its scale economics to dominate mid-tonnage electric and hybrid deliveries across Mexican industrial parks. KraussMaffei sustains premium positioning through technical service density in São Paulo and Monterrey. Indústrias Romi S.A. anchors its position as Brazil's only significant domestic assembler, competing on localized support and spare-part velocity.
Injection molding machines are clamping and plasticizing systems that heat thermoplastic or thermoset polymers to a molten state, inject the material under controlled pressure into precision-machined molds, and cool the formed part to net shape; clamp forces range from under 50 tons for micro-components to over 4,000 tons for automotive structural panels, with cycle times typically spanning 15 seconds to several minutes depending on wall thickness and resin chemistry. Electric machines now lead in precision-demanding segments such as medical and electronics, while hydraulic units retain cost advantage in thick-walled commodity applications across the packaging end user base. Hybrid architectures are capturing the fastest expansion in medium machine size classes where automotive tier suppliers seek energy efficiency without sacrificing shot capacity.
Brazil's INMETRO and Mexico's NOM standards for industrial equipment safety and energy efficiency create dual compliance burdens that favor suppliers with established certification infrastructure. The EU's F-Gas Regulation indirectly shapes Latin American procurement patterns as exporters align refrigerant and cooling system specifications to maintain access to European-molded component markets. Buyers must monitor how evolving energy-efficiency thresholds and local content rules in Mexican automotive incentive programs reshape total cost of ownership calculations for new press investments.
Market Dynamics
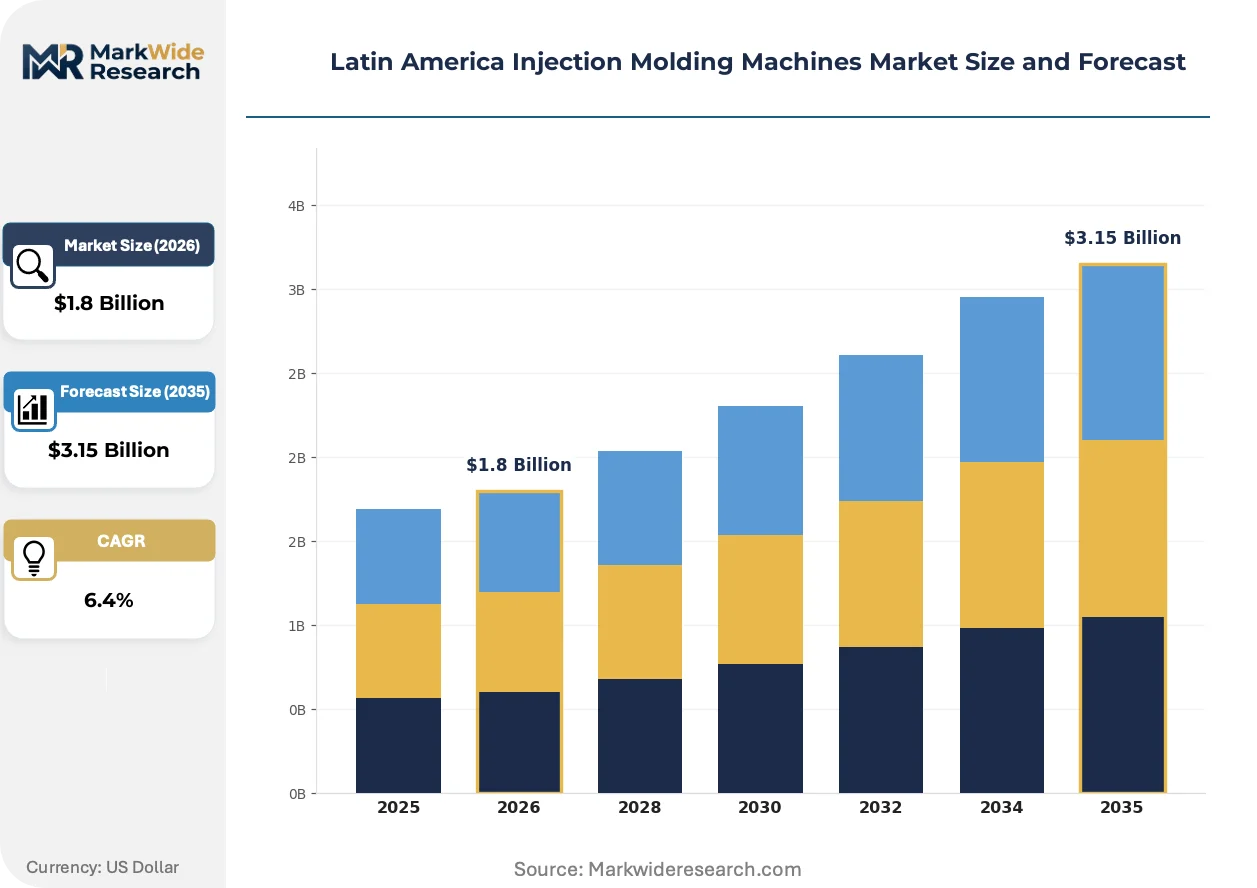
Nearshored automotive supply chains are restructuring procurement geography across Latin America, forcing tier suppliers to modernize press fleets and comply with dual certification regimes in Mexico and Brazil.
Growth Catalysts
- Automotive corridor densification:OEMs relocating assembly to Mexico's Bajío region are pulling injection molding capacity into Querétaro and Guanajuato, creating clustered demand for medium-tonnage hybrid machines.
- INMETRO safety mandates:Brazil's industrial machinery certification requirements are filtering non-compliant imports and expanding the addressable market for certified equipment assemblers.
- Electric machine precision gains:Medical device and electronics manufacturers are specifying all-electric architectures for micron-tolerance components, opening premium replacement cycles.
Market Restraints
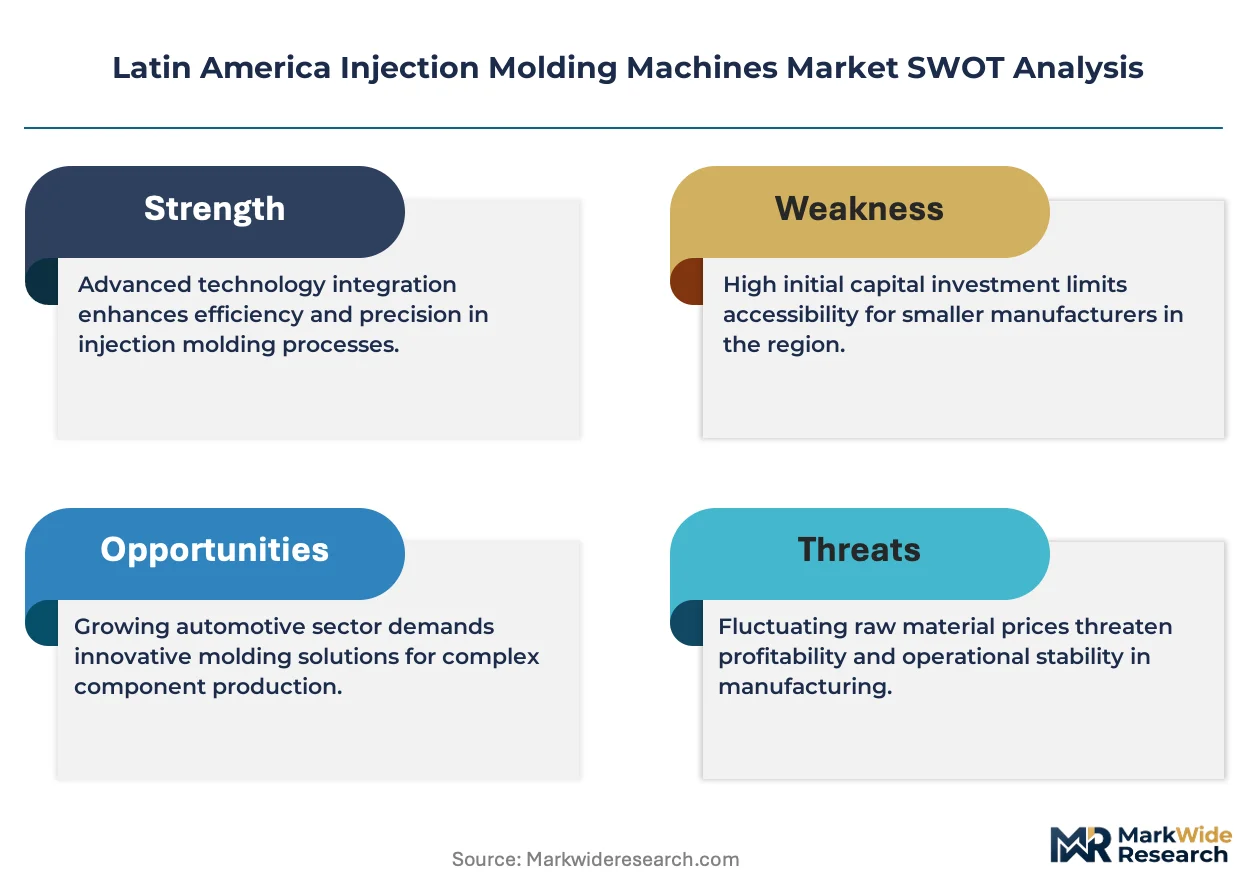
- Steel and copper input volatility:Machine frame and heating element costs fluctuate with commodity indexes, compressing margin visibility for Brazilian domestic assemblers.
- Controller chip supply concentration:Servo drive and PLC sourcing remains concentrated in East Asian foundries, exposing Latin American builders to extended lead times.
- Hydraulic fluid environmental liability:Spill remediation costs and disposal regulations are extending total cost of ownership for legacy hydraulic fleets beyond electric alternatives.
Strategic Opportunities
- Colombian Andean manufacturing:Underdeveloped automotive tier supply in Bogotá and Medellín corridors offers first-mover positioning for hybrid machine distributors.
- Medical packaging sterilization standards:Evolving ANVISA requirements for pharmaceutical primary packaging are mandating clean-room-compatible machine specifications.
- Remanufacturing and retrofit services:Aging hydraulic installed base across São Paulo industrial suburbs creates aftermarket revenue streams for servo motor and control system upgrades.
Industry Challenges
- Servomechanics technician scarcity:Electric and hybrid machine maintenance requires skills distinct from hydraulic hydraulics, and regional vocational pipelines have not scaled accordingly.
- Dual NOM-INMETRO certification timelines:Suppliers seeking cross-border sales must navigate concurrent Mexican and Brazilian approval processes, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Injection Molding Machines Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Hybrid, Others End User: Automotive, Consumer Goods, Electronics, Packaging Injection Technology: Hot Runner, Cold Runner, Stack Molding, Others Machine Size: Small, Medium, Large, Extra Large |
| Companies Covered | Haitian International, Arburg GmbH & Co. KG, KraussMaffei, Indústrias Romi S.A., Milacron, Engel, Sumitomo (SHI) Demag Plastics Machinery, Husky Injection Molding Systems Ltd, The Japan Steel Works Ltd, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Injection Molding Machines Market Shifts & Advancements
Machine architecture decisions are splitting buyer segments along precision-versus-throughput lines, while regulatory pressure on energy consumption and refrigerant chemistry reshapes cooling system design.
All-electric injection molding systems eliminate hydraulic oil circuits and replace variable-displacement pumps with direct-drive servomotors for screw rotation and clamp actuation. Medical device molders in Tijuana and São Paulo's pharmaceutical corridor are specifying these architectures for clean-room compatibility and shot-to-shot repeatability. This technology is bifurcating the competitive landscape between precision-focused premium suppliers and commodity hydraulic builders.
Brazil's INMETRO Ordinance 371 mandates energy-efficiency labeling and safety interlock standards for industrial plastics machinery sold domestically. The regulation requires documented power consumption testing and third-party conformity assessment, raising compliance costs for imported equipment. Domestic assemblers and established multinationals with local certification infrastructure are capturing share from gray-market importers.
Automotive tier suppliers are consolidating machine procurement through direct OEM-aligned supplier programs rather than independent capital equipment decisions. Tier-two and tier-three molders in Guanajuato are receiving press specifications from upstream customers, compressing vendor selection autonomy. This pattern concentrates most visibly in seating and interior component supply chains serving Detroit Three nearshored assembly operations.
Latin America Injection Molding Machines Market Segmentation
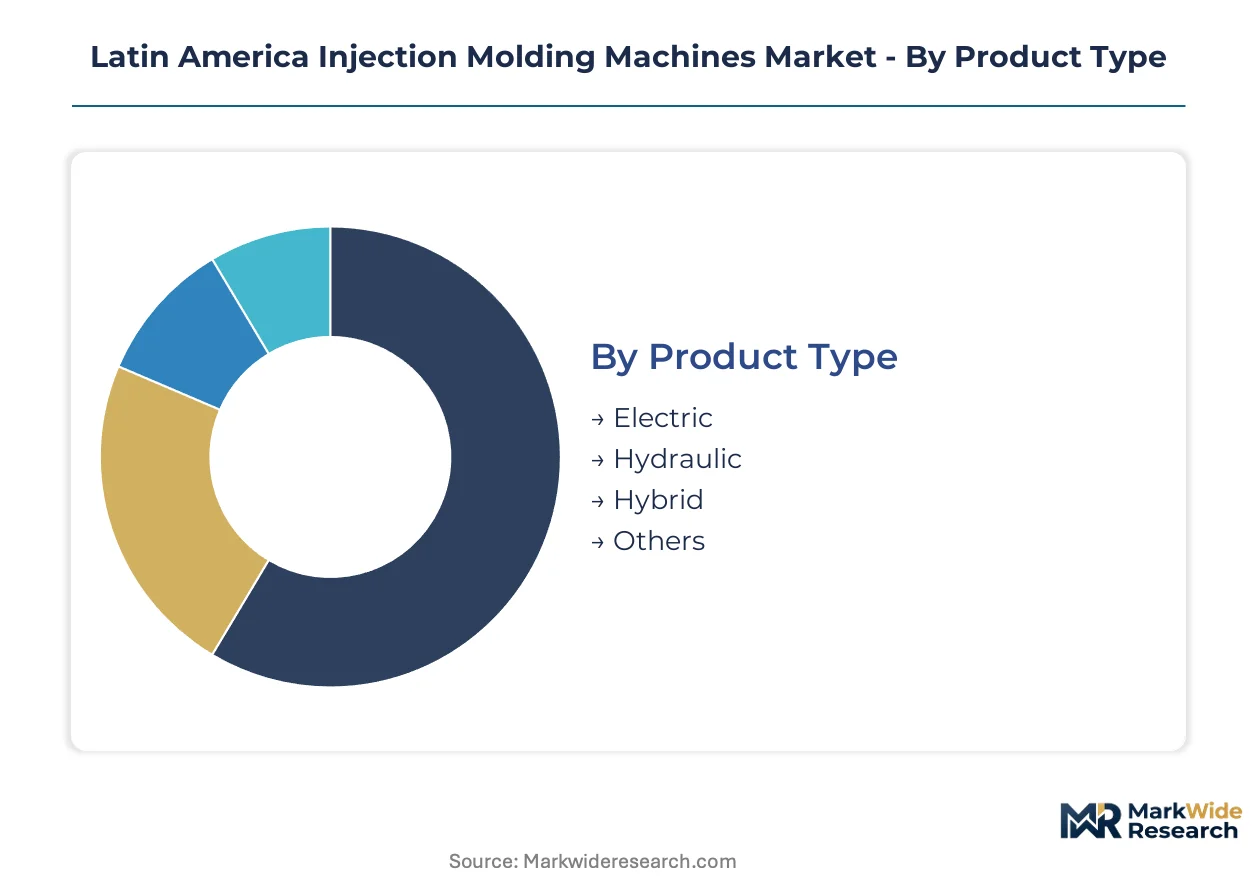
Segmentation in Latin American injection molding equipment tracks how regulatory pressure and end-use precision requirements split procurement decisions across technology architectures. Buyers in Mexico and Brazil face divergent certification burdens that reshape which machine types dominate specific industrial corridors.
Product Type:
INMETRO and NOM energy-efficiency thresholds filter which architectures qualify for domestic sales, creating tiered compliance costs across electric, hydraulic, and hybrid platforms.
- Electric:All-electric architectures employ direct-drive servomotors for screw rotation and clamp actuation, eliminating hydraulic circuits entirely. Medical device manufacturers in Tijuana and São Paulo's pharmaceutical corridor specify these systems for clean-room compatibility and micron-level repeatability. The technology commands premium positioning where ANVISA sterilization standards apply.
- Hybrid:Hybrid systems combine servo-electric screw drives with hydraulic clamping circuits, capturing demand from automotive tier suppliers in Querétaro and Guanajuato who need shot capacity without sacrificing energy efficiency. These machines lead replacement cycles among seating and interior component molders serving nearshored OEM supply chains.
- Hydraulic:Conventional hydraulic units retain cost advantage in thick-walled commodity packaging applications across Brazil's domestic consumer goods sector.
- Others:Specialized two-platen and multi-component configurations serve niche automotive lighting and multi-material consumer electronics housing production.
Hydraulic machines handle the majority of installed throughput across Latin America; hybrid architectures are climbing the fastest on share as automotive suppliers modernize press fleets.
End User:
Customer procurement autonomy varies sharply across value chain tiers, with automotive OEM-aligned programs constraining vendor selection more than independent electronics or packaging buyers.
- Automotive:Tier-two and tier-three suppliers in Mexico's Bajío region receive machine specifications directly from upstream seating and interior component programs, compressing independent capital equipment decisions. INMETRO certification and NOM compliance operate as dual gates for cross-border supplier qualification.
- Packaging:Food and beverage container producers across São Paulo and Monterrey operate with greater procurement independence, prioritizing cycle time and energy consumption metrics over mandated supplier lists. Hydraulic machines retain penetration here due to lower capital intensity and simpler maintenance protocols.
- Consumer Goods:Appliance and houseware molders in Brazil's domestic market favor medium-tonnage hybrid systems balancing part complexity with production volume.
- Electronics:Connector and housing manufacturers specify all-electric precision for miniaturized components, particularly in Tijuana's export-oriented manufacturing parks.
Automotive applications concentrate the highest equipment value per facility; electronics represents the steepest expansion trajectory driven by medical-grade precision requirements.
Injection Technology:
Runner system selection directly determines material waste rates and cycle consistency, with hot runner adoption accelerating where engineered resins command premium pricing.
- Hot Runner:Heated manifold systems maintain thermoplastic melt temperature through precision temperature control zones, eliminating solidified runner waste. Automotive structural component molders in Guanajuato deploy these systems for glass-filled nylon and PBT applications where material costs dominate part economics.
- Cold Runner:Conventional solid runner systems remain standard in commodity packaging and low-complexity consumer goods where material waste tolerance is higher and tooling capital constraints apply.
- Stack Molding:Multi-level cavity configurations double output from single clamp units, penetrating medical packaging and thin-wall food container segments in São Paulo and Medellín corridors.
- Others:Specialized valve-gate and sequential injection systems serve cosmetic surface quality requirements in premium consumer electronics housings.
Cold runner technology retains the broadest installed base; hot runner systems are expanding most quickly among automotive and medical precision molders.
Machine Size:
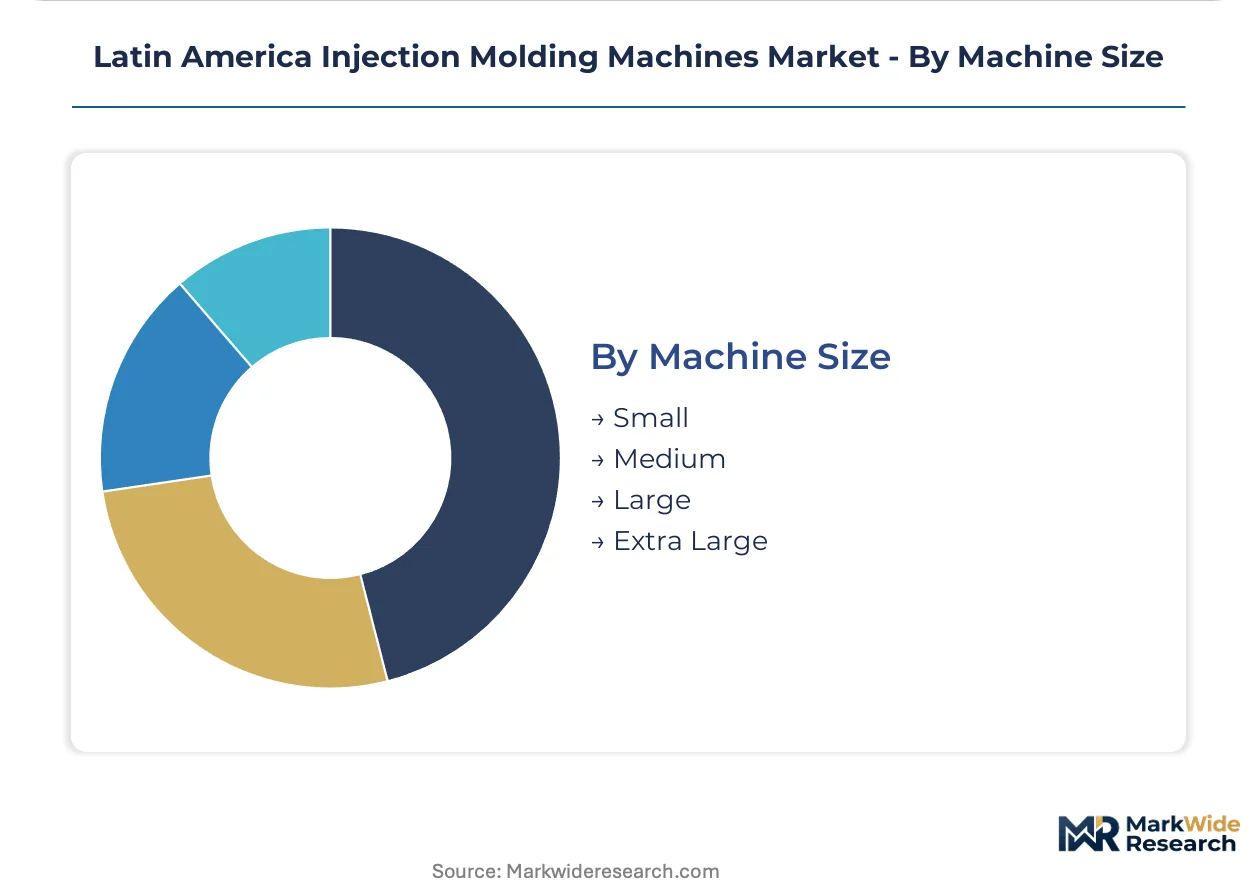
Clamp force requirements map directly to end-use part scale, with medium tonnage capturing the densest demand concentration across Latin American automotive corridors.
- Medium:Machines in the 150-500 ton clamp range dominate Querétaro and Guanajuato automotive tier supply, handling door panels, instrument clusters, and HVAC housings for nearshored OEM assembly. Hybrid architectures lead in this segment where energy efficiency mandates intersect with shot volume requirements.
- Small:Under-150-ton units concentrate in medical device and electronics connector applications across Tijuana and São Paulo's pharmaceutical manufacturing zones, with all-electric architectures specified for clean-room compatibility.
- Large:500-1500 ton systems serve automotive bumper and structural panel production, with demand concentrated among tier-one suppliers in Puebla and São Paulo state.
- Extra Large:Over-1500-ton presses remain limited to specialized industrial pallet, waste container, and automotive structural foam applications with sparse Latin American demand.
Medium tonnage equipment handles the majority of regional unit volume; small machines are gaining share fastest as medical and electronics precision requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lázaro Cárdenas-Manzanillo Pacific port corridor funnels Asian machine imports into Mexico's industrial heartland, while Santos port handles equivalent throughput for São Paulo manufacturers. These maritime gateways determine equipment availability timelines and landed cost structures across the region.
Mexico
Automotive seating and interior component molders in Querétaro and Guanajuato are expanding hybrid press capacity to serve Detroit Three nearshored assembly operations. NOM energy-efficiency standards for industrial machinery filter import eligibility and reshape procurement specifications. The Bajío corridor concentrates the densest demand cluster, with tier suppliers modernizing legacy hydraulic fleets under OEM-aligned supplier programs.
Brazil
Domestic appliance and consumer goods manufacturers in São Paulo state favor medium-tonnage hybrid systems balancing part complexity with production volume. INMETRO Ordinance 371 mandates third-party conformity assessment for industrial plastics machinery, raising compliance costs for imported equipment. The ABC Paulista industrial suburbs host the region's largest installed base of aging hydraulic machines, creating retrofit demand for servo motor upgrades.
Argentina
Packaging producers in Greater Buenos Aires operate with greater procurement independence than automotive-tier counterparts elsewhere, prioritizing cycle time metrics over mandated supplier lists. The country's national industrial safety regulator enforces machinery certification requirements that parallel Brazilian standards. Córdoba's automotive component cluster remains underdeveloped relative to Mexican and Brazilian corridors, limiting injection molding equipment density.
Colombia
Medical device packaging manufacturers in Bogotá are specifying clean-room-compatible machine specifications under evolving pharmaceutical sterilization standards. The national pharmaceutical regulator mandates documentation protocols that favor certified equipment suppliers with established local service infrastructure. Medellín's emerging manufacturing corridor offers first-mover positioning for hybrid machine distributors seeking Andean market entry.
Chile
Mining equipment component molders in Santiago's industrial periphery demand large-tonnage presses for structural polymer parts serving extractive industries. The country's national standards body aligns industrial machinery safety requirements with Mercosur technical regulations. Valparaíso port logistics constrain equipment import timelines, favoring suppliers with established regional distribution networks over direct Asian sourcing.
Latin America Injection Molding Machines Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and service density dimensions, producing a tiered structure where scale advantages intersect with localized compliance capabilities. Haitian International leverages manufacturing scale to dominate mid-tonnage electric and hybrid deliveries across Mexican industrial parks. KraussMaffei sustains premium positioning through technical service density in São Paulo and Monterrey. The competitive landscape rewards suppliers with concurrent NOM and INMETRO certification capabilities, while M&A activity concentrates service networks and technology licensing agreements expand electric architecture access.
Within the premium-tier vector, KraussMaffei and Engel occupy positions defined by technical service density and precision-engineering heritage. Haitian International exemplifies the scale-driven archetype, competing on unit economics across standardized machine configurations. Indústrias Romi S.A. anchors the domestic assembler category, competing on localized support velocity and spare-part availability within Brazil. These three represent distinct strategic postures: premium service integration, manufacturing scale, and national-market embedding.
| Leading Market Players |
|---|
| Haitian International |
| Arburg GmbH & Co. KG |
| KraussMaffei |
| Indústrias Romi S.A. |
| Milacron |
| Engel |
| Sumitomo (SHI) Demag Plastics Machinery |
| Husky Injection Molding Systems Ltd |
| The Japan Steel Works Ltd |
| Others |
Supply & Pricing Matrix
Haitian International's manufacturing scale across Ningbo and Guangdong plants compresses unit economics for mid-tonnage electric and hybrid architectures, establishing price floors that domestic Brazilian assemblers struggle to match without sacrificing margin. This scale concentration simultaneously shapes supply chain routing through Pacific port corridors and reinforces tiered procurement patterns across Latin American automotive corridors.
Pricing Analysis
Certification level (INMETRO/NOM-grade) creates the primary spread between premium European suppliers and Asian scale players. Three-tier pricing structure separates CE-marked precision systems from NOM-compliant mid-market hybrids and uncertified gray-market hydraulics. Pricing pressure stems from steel and copper input volatility squeezing Brazilian domestic assemblers. Packaging producers across São Paulo operate with greatest price sensitivity; medical device molders in Tijuana exhibit least.
Supply Chain Analysis
China and Taiwan anchor controller chip and servo drive fabrication for Latin American machine builders. Japan and Germany supply precision ball screws and injection units. Supply chain risk centers on single-source vulnerability in East Asian foundries for PLC modules. Distribution runs through Lázaro Cárdenas-Manzanillo and Santos port corridors into Querétaro and São Paulo industrial parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servomechanics technician scarcity across Mexico and Brazil constrains electric and hybrid machine maintenance capacity, creating a bottleneck that favors suppliers with embedded training infrastructure over pure equipment vendors.
For Market Incumbents: Compound technical service density in São Paulo and Monterrey to defend against Haitian International's scale economics. Deepen backward integration into spare-part warehousing across Guanajuato corridors. Prioritize concurrent NOM-INMETRO certification investment to compress product launch cycles versus gray-market entrants. For New Entrants and Emerging Players: Differentiate on remanufacturing and retrofit capabilities targeting São Paulo's aging hydraulic installed base. Target Colombian Andean manufacturing corridors in Medellín where automotive tier supply remains underdeveloped. Pursue medical packaging sterilization compliance as the most penetrable premium segment under evolving ANVISA requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid architecture specialists with established certification infrastructure over pure-play electric entrants. Long-term viability hinges on service network density rather than manufacturing scale alone. Watch technician training pipeline expansion as the signal for regional maintenance capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Concurrent NOM-INMETRO Certification Investment | Compresses cross-border product launch timelines for Mexican-Brazilian corridor access. |
| Servomechanics Training Academy Buildout | Addresses technician scarcity constraining electric and hybrid machine maintenance capacity. |
| Retrofit Service Network Expansion | Captures aftermarket revenue from São Paulo's aging hydraulic installed base. |
| Andean Distribution Partnership | Establishes first-mover positioning in Colombia's emerging Medellín manufacturing corridor. |
| Medical Packaging Sterilization Compliance | Aligns machine specifications with evolving ANVISA pharmaceutical primary packaging mandates. |
Research Methodology
Desk research of trade customs data, INMETRO certification registries, and NOM energy-efficiency filings preceded structured interviews with maintenance directors at automotive tier suppliers, plant engineers across packaging facilities, OEM procurement teams in Querétaro corridors, and aftermarket service heads in São Paulo industrial suburbs. Primary intelligence combined with secondary validation from SEC filings of listed equipment manufacturers, Brazilian industrial machinery import statistics, and Mexican automotive production databases. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, end user, injection technology, and machine size segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycles, capacity expansion announcements, and regulatory compliance phase-in schedules. Forecast inputs incorporated automotive nearshoring pipeline commitments and energy-efficiency threshold escalation trajectories.
Forecasts assume regulatory continuity in INMETRO Ordinance 371 and NOM industrial machinery standards; material policy shifts would require re-modeling. Specific risks include dual certification timeline extensions, controller chip supply disruptions, and steel input cost spikes. Recalibration cycles align with material shifts in automotive OEM supplier program specifications and energy-efficiency mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market