
 Organophosphate Insecticides Market | 2026-2036
Organophosphate Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Organophosphate Insecticides Market Analysis
Food-grade residue tolerance thresholds is collapsing the viable product universe for legacy organophosphate suppliers. Bayer AG sustains its position through backward integration into active ingredient synthesis, while ADAMA competes on cost-optimized emulsifiable concentrate formulations for emerging markets. FMC Corporation specializes in granular delivery systems that reduce applicator exposure and extend its footprint in professional pest management channels.
Organophosphate insecticides are phosphorus-based ester compounds that inhibit acetylcholinesterase enzyme activity in target pests, typically manufactured through phosphorylation of alcohol precursors with phosphorus oxychloride intermediates. These agents serve commercial agriculture, public health vector control, and structural pest management by disrupting neural transmission in insects. Chlorpyrifos formulations face structural decline across multiple jurisdictions, while malathion retains broader regulatory acceptance for mosquito abatement and stored-grain protection. Wettable powders and suspensions capture expanding share in precision application equipment, whereas granules dominate soil-incorporation uses in row-crop systems.
EPA registration review proceedings, EU REACH authorization restrictions, and India's Central Insecticides Board registration protocols collectively determine which active ingredients remain commercially viable in major consumption zones. Regulatory divergence between jurisdictions fragments product portfolios and forces parallel formulation development tracks. Stakeholders must monitor residue limit harmonization negotiations between Codex Alimentarius and national food safety authorities to anticipate which chemistries retain multi-country market access.
Market Dynamics
EPA registration review proceedings and EU REACH authorization restrictions are systematically eliminating chlorpyrifos-based formulations while redirecting R&D investment toward malathion and diazinon alternatives with more favorable toxicological profiles.
Growth Catalysts
- Specialty crop protection demand:Brazil's fruit and vegetable growers and Southeast Asian horticulture operations require targeted pest management solutions that organophosphate formulations deliver effectively.
- REACH authorization timelines:The EU's phased restrictions on legacy chemistries create temporary market windows for compliant alternatives before full substitution mandates take effect.
- Stored-grain protection protocols:Malathion retains broad regulatory acceptance for mosquito abatement and post-harvest grain preservation in jurisdictions with stringent food safety frameworks.
Market Restraints
- Phosphorus oxychloride supply volatility:Concentrated production of this critical phosphorylation intermediate in Chinese chemical manufacturing clusters exposes formulators to input cost fluctuations and trade policy disruptions.
- Residue tolerance compression:Codex Alimentarius negotiations and national food safety authority harmonization efforts are collapsing maximum residue limits for legacy active ingredients across multiple jurisdictions simultaneously.
- Biological insecticide substitution:Bacillus thuringiensis and pheromone-based alternatives are capturing share in specialty crop applications where export market access depends on residue-free certification.
Strategic Opportunities
- Precision application equipment integration:Wettable powders and microencapsulated suspensions align with drone-based and variable-rate sprayer adoption in Brazil's soybean corridor and India's cotton-belt states.
- Applicator exposure reduction mandates:Granular delivery systems and closed-transfer packaging respond to OSHA and national agricultural safety authority requirements for handler protection.
- Public health vector control procurement:WHO prequalification pathways and national malaria control program tenders sustain demand for malathion in sub-Saharan Africa and Southeast Asian dengue-endemic regions.
Industry Challenges
- Parallel registration track management:Formulators must maintain separate dossiers for EPA, EU REACH, and India's Central Insecticides Board with divergent data requirements and review timelines.
- Active ingredient synthesis capability:Backward integration into phosphorus-based chemistry requires capital deployment that mid-scale competitors cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organophosphate Insecticides Market |
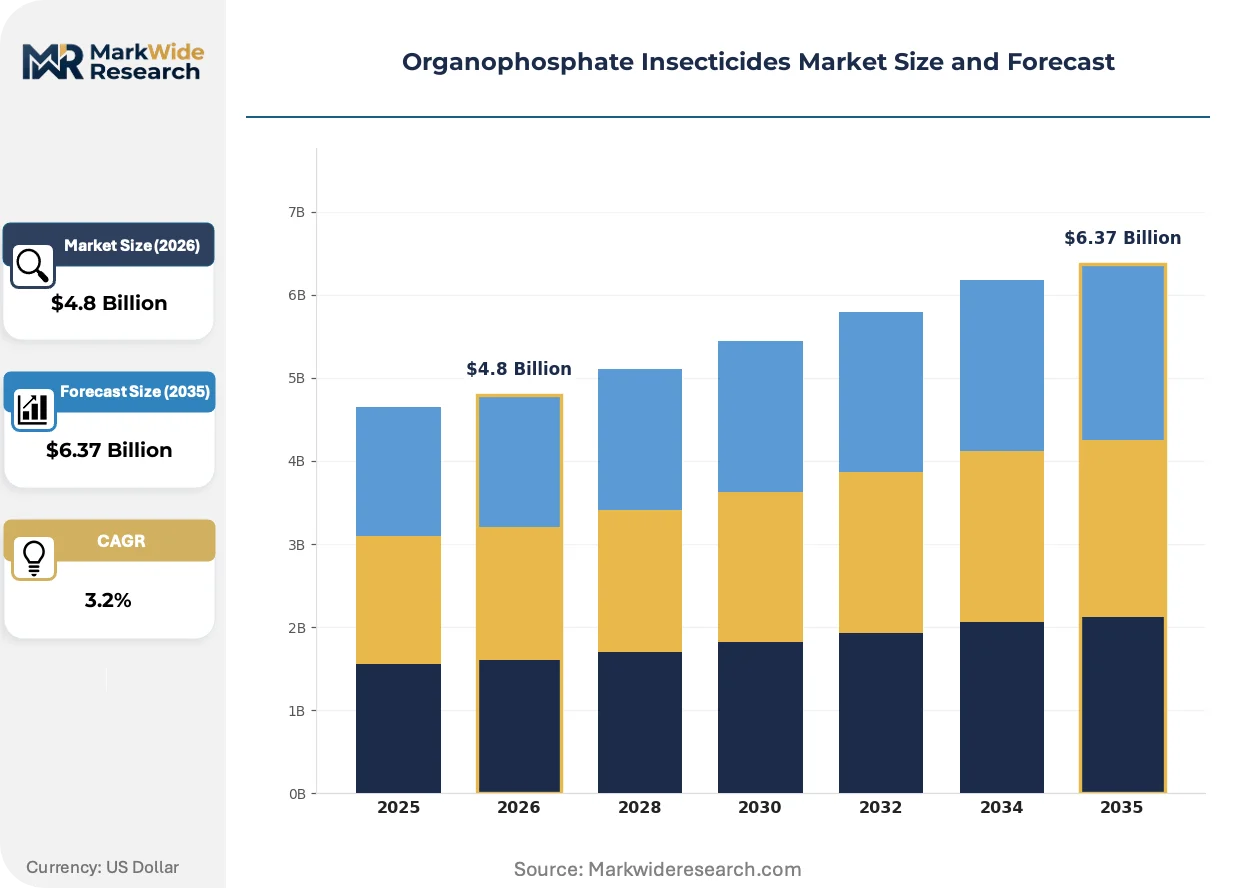
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorpyrifos, Malathion, Diazinon, Parathion Application: Agricultural, Residential, Commercial, Industrial Formulation Type: Granules, Emulsifiable Concentrates, Wettable Powders, Suspensions Distribution Channel: Online Retail, Offline Retail, Wholesale, Agribusiness |
| Companies Covered | Syngenta Crop Protection AG, Bayer AG, BASF SE, ADAMA, Sumitomo Chemicals, Nufarm Limited, FMC Corporation, UPL, American Vanguard Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organophosphate Insecticides Market Emerging Trajectories
Formulation chemistry and application technology are converging to extend the commercial viability of organophosphate insecticides amid tightening residue standards and applicator safety requirements.
Microencapsulation technology is decomposing traditional emulsifiable concentrate market share by enabling controlled-release active ingredient delivery. Specialty crop growers in California's Central Valley and Spain's Almería greenhouse complexes are adopting these formulations to reduce spray frequency and buffer against wash-off. The technology is decomposing price competition at the commodity formulation level while creating premium positioning for precision agriculture suppliers.
EU REACH authorization restrictions on chlorpyrifos and related organophosphates are forcing portfolio restructuring across European formulators. The regulation eliminates indoor use cases and compresses outdoor application windows to pre-bloom intervals only. Professional pest management channels in Germany and France are accelerating substitution toward pyrethroid and neonicotinoid alternatives despite higher unit costs.
Integrated pest management certification requirements are reshaping procurement criteria for export-oriented growers. Supermarket chain sustainability protocols and GLOBALG.A.P. audit standards now penalize organophosphate residues above detection thresholds. Chilean table grape exporters and Kenyan flower producers are prioritizing biocontrol and mating disruption technologies to maintain EU and UK market access.
Organophosphate Insecticides Market Segmentation
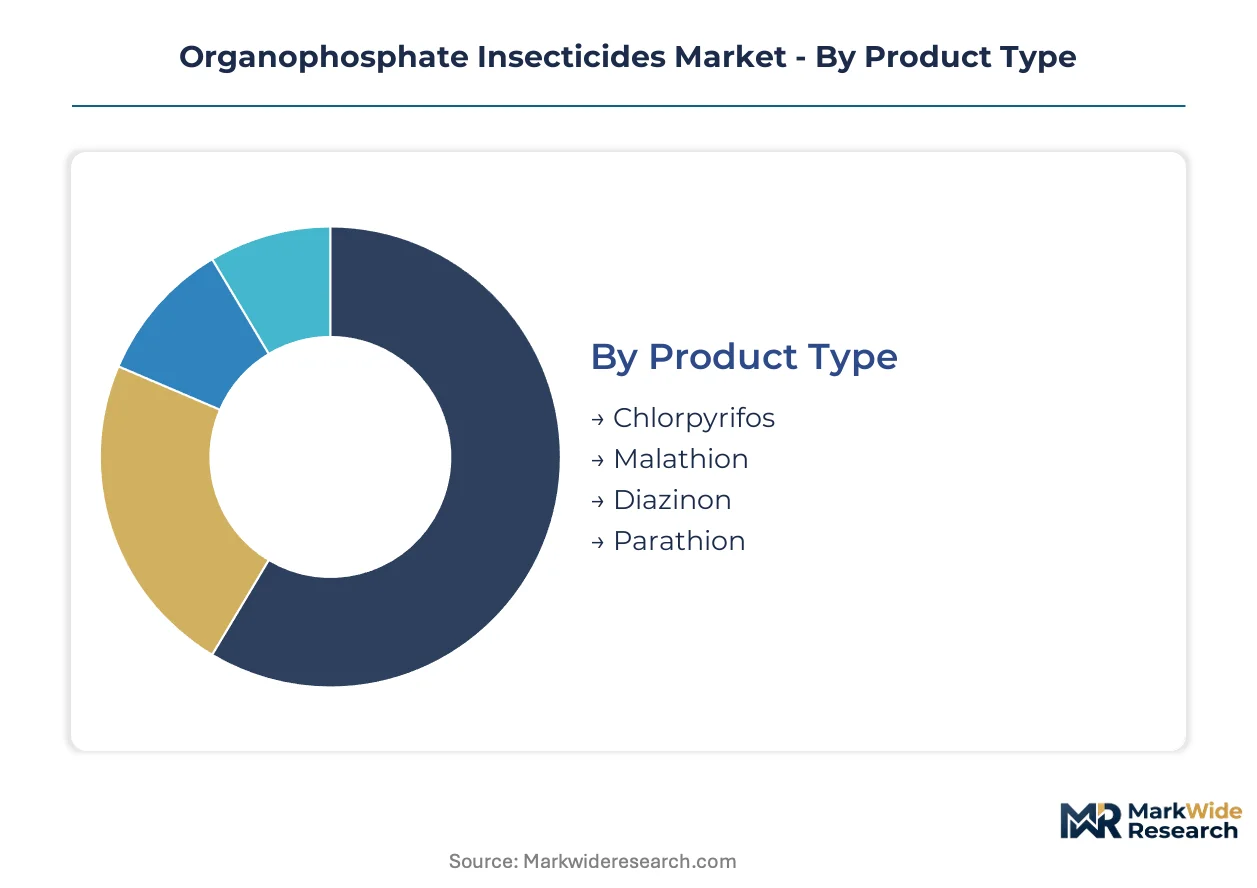
Organophosphate insecticide procurement patterns diverge sharply between export-oriented specialty crop operations and domestic food security programs. Formulation investments track regulatory tolerance thresholds rather than agronomic performance alone.
Product Type:
Domestic consumption concentrates on chemistries with retained registration in home jurisdictions; export demand flows toward actives with multi-country residue harmonization.
- Chlorpyrifos:Phosphorothioate ester with broad-spectrum efficacy against soil-dwelling and foliar pests. Demand concentrates in Brazil's soybean corridor and India's cotton-belt states where pre-bloom application windows remain permissible under national protocols. EPA registration review proceedings and EU REACH authorization restrictions are systematically eliminating this chemistry from indoor use and compressing outdoor application intervals.
- Malathion:Carboxyester organophosphate with favorable toxicological profile relative to legacy alternatives. Brazilian stored-grain protection programs and Southeast Asian public health vector control tenders sustain procurement volumes. WHO prequalification pathways reinforce its position in malaria and dengue abatement across sub-Saharan Africa.
- Diazinon:Pyrimidinyl phosphorothioate effective against soil insects and turf pests. Residential lawn care and golf course maintenance in North American jurisdictions with retained registration drive remaining commercial volumes.
- Parathion:Nitrophenyl phosphorothioate with restricted use classification in most jurisdictions. Professional pest management channels in limited geographies with specialized applicator certification requirements.
Malathion holds the largest share; momentum sits with diazinon as chlorpyrifos faces structural decline.
Application:
Cost tier separation distinguishes commodity row-crop treatments from precision specialty crop protocols requiring residue-free certification.
- Agricultural:Dominant consumption channel spanning pre-plant soil incorporation, foliar spray programs, and post-harvest grain protection. Brazil's fruit and vegetable growers and Southeast Asian horticulture operations require targeted pest management solutions that organophosphate formulations deliver effectively.
- Residential:Consumer-facing formulations for lawn, garden, and perimeter pest control. Regulatory compression of homeowner-accessible chemistries redirects demand toward pyrethroid alternatives in EU and North American markets.
- Commercial:Professional pest management services for structural, turf, and ornamental applications. Integrated pest management certification requirements reshape procurement criteria toward reduced-risk alternatives.
- Industrial:Vector control for food processing facilities, warehouses, and transportation infrastructure. Malathion retains broad regulatory acceptance for mosquito abatement in jurisdictions with stringent food safety frameworks.
Agricultural applications command the dominant revenue position; commercial services are expanding most quickly through professional channel consolidation.
Formulation Type:
Application technology compatibility determines formulation selection across precision equipment versus conventional ground-rig systems.
- Granules:Clay or polymer-based carriers for soil-incorporation in row-crop systems. OSHA and national agricultural safety authority mandates for handler protection reinforce demand in Brazil's soybean corridor and India's cotton-belt states.
- Emulsifiable Concentrates:Oil-in-water systems with rapid knockdown characteristics. Cost-optimized formulations for emerging markets where ADAMA competes on price-positioned supply.
- Wettable Powders:Fine particle suspensions compatible with drone-based and variable-rate sprayer adoption. California's Central Valley and Spain's Almería greenhouse complexes favor these formulations for reduced spray frequency.
- Suspensions:Microencapsulated controlled-release systems extending residual activity. Premium positioning for precision agriculture suppliers as microencapsulation technology decomposes traditional emulsifiable concentrate market share.
Emulsifiable concentrates retain volume leadership; suspensions are gaining share fastest through precision equipment integration.
Distribution Channel:
Customer type separation distinguishes large-scale agribusiness procurement from fragmented retail access.
- Online Retail:E-commerce platforms for professional applicator supplies and specialized equipment. Regulatory documentation requirements limit direct-to-consumer availability for restricted-use formulations.
- Offline Retail:Brick-and-mortar agricultural supply cooperatives and garden centers. Remains dominant for immediate-need procurement in rural production zones.
- Wholesale:Volume distribution to formulators and regional blending operations. Phosphorus oxychloride supply volatility from Chinese chemical manufacturing clusters exposes intermediaries to input cost fluctuations.
- Agribusiness:Integrated procurement through seed-chemical-equipment bundles. Bayer AG leverages backward integration into active ingredient synthesis to secure preferred channel positioning.
Agribusiness channels capture the largest transaction value; online retail is climbing the fastest through professional buyer digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese chemical manufacturing clusters dominate phosphorus oxychloride intermediate supply, exposing formulators worldwide to input cost fluctuations and trade policy disruptions. National registration protocols diverge sharply across major consumption zones.
United States
EPA registration review proceedings are systematically eliminating chlorpyrifos-based formulations while redirecting investment toward malathion alternatives. California's Central Valley specialty crop growers adopt microencapsulated suspensions to meet residue tolerance thresholds for export markets. Professional pest management channels in Florida and Texas sustain demand for granular delivery systems.
Brazil
Fruit and vegetable growers in São Paulo state and Mato Grosso's soybean corridor require targeted pest management that organophosphate formulations deliver effectively. ANVISA protocols align increasingly with Codex Alimentarius standards, compressing application windows for legacy chemistries. Stored-grain protection programs in Rio Grande do Sul sustain procurement volumes for malathion-based protocols.
India
The Central Insecticides Board registration protocols determine which active ingredients remain commercially viable across Maharashtra, Gujarat, and Telangana cotton-belt states. Pre-bloom application windows for chlorpyrifos persist under national protocols despite EPA and EU restrictions. ADAMA competes on cost-optimized emulsifiable concentrate formulations for domestic smallholder markets.
Germany
EU REACH authorization restrictions eliminate chlorpyrifos indoor use and compress outdoor intervals to pre-bloom only. Professional pest management channels in Bavaria and North Rhine-Westphalia accelerate substitution toward reduced-risk alternatives. Bayer AG leverages backward integration into active ingredient synthesis to maintain preferred positioning.
China
Domestic phosphorus oxychloride production clusters in Jiangsu and Zhejiang provinces supply phosphorylation intermediates to global formulators. MEE environmental compliance requirements reshape manufacturing footprints for export-oriented active ingredient synthesis. Yangtze River Delta chemical parks concentrate formulation packaging for Southeast Asian markets.
Organophosphate Insecticides Market Vendor Landscape
Concentration sits with diversified agrochemical conglomerates possessing captive synthesis capabilities. Three to five integrated multinational groups command formulation registration portfolios across multiple jurisdictions. Strategic archetypes separate backward-integrated active ingredient producers from regional blenders dependent on merchant supply. Competitive moves center on parallel registration track management and precision application equipment partnerships.
Among Swiss and German-based integrated suppliers, Syngenta Crop Protection AG and Bayer AG occupy positions reflecting synthesis-to-formulation control. BASF SE anchors the specialty chemicals tier with differentiated delivery system investments. ADAMA represents the cost-optimized regional blender archetype competing on emulsifiable concentrate price positioning.
| Leading Market Players |
|---|
| Syngenta Crop Protection AG |
| Bayer AG |
| BASF SE |
| ADAMA |
| Sumitomo Chemicals |
| Nufarm Limited |
| FMC Corporation |
| UPL |
| American Vanguard Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates at Chinese phosphorus oxychloride manufacturing clusters in Jiangsu and Zhejiang provinces determine global price floors for phosphorylation intermediates. Scale concentration among state-affiliated chemical parks creates asymmetric bargaining power against mid-scale formulators in India and Southeast Asia, compressing margins at the emulsifiable concentrate tier while premium suspension formulations capture value through equipment integration partnerships.
Pricing Analysis
EPA registration review proceedings dictate the pricing tier structure across the organophosphate insecticide market. Three-tier pricing structure across premium microencapsulated suspensions, standard wettable powders, and economy emulsifiable concentrates separates precision agriculture suppliers from commodity blenders. Cost compression in the emulsifiable concentrate tier is intensifying because ADAMA and regional competitors compete on price-positioned supply for smallholder markets in India's cotton-belt states. Agricultural cooperatives in Brazil's soybean corridor exhibit highest price sensitivity, while professional pest management channels in Germany and California accept premium positioning for applicator exposure reduction.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose formulators to inbound logistics cost volatility for phosphorus oxychloride intermediates. Supply concentrates in Chinese chemical manufacturing clusters, with secondary sourcing from Indian phosphorylation facilities and German specialty chemical producers. Raw material dependencies center on phosphorus oxychloride, alcohol precursors, and clay carrier substrates for granular formulations. Single-source vulnerability from Yangtze River Delta environmental compliance shutdowns threatens global active ingredient synthesis. Distribution runs through agribusiness channel bundling, wholesale regional blending operations, and agricultural supply cooperatives for last-mile access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology adoption represents a high-growth disruption as precision agriculture equipment penetration accelerates regulatory compliance through reduced spray frequency. EPA and EU REACH authorization timelines create temporary market windows for compliant alternatives before full substitution mandates take effect.
For Market Incumbents: Shield formulation portfolios from chlorpyrifos structural decline by accelerating malathion and diazinon registration dossiers across EPA, EU REACH, and India's Central Insecticides Board parallel tracks. Backward integration into phosphorus-based chemistry secures captive supply against Chinese phosphorus oxychloride price volatility. Bayer AG's synthesis-to-formulation control demonstrates how upstream capability anchors preferred channel positioning against ADAMA's cost-optimized regional blending model. For New Entrants and Emerging Players: WHO prequalification fast-track for malathion vector control formulations opens procurement pathways into sub-Saharan African malaria control programs and Southeast Asian dengue abatement tenders. White-space targets center on drone-compatible wettable powder formulations for Brazil's precision agriculture adoption and closed-transfer packaging systems responding to OSHA handler protection mandates. Go-to-market execution should prioritize equipment manufacturer partnerships over commodity distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated suppliers with captive active ingredient synthesis and multi-jurisdiction registration portfolios spanning EPA, EU REACH, and India's Central Insecticides Board protocols. Long-term viability over the projection horizon favors acquisition targets possessing backward integration into phosphorus-based chemistry rather than formulation-only regional blenders. Signal to monitor: Codex Alimentarius residue limit harmonization negotiations, which would collapse viable product universes for legacy-dependent suppliers overnight.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Bayer AG's captive phosphorus oxychloride supply secures margin protection against Chinese intermediate volatility. |
| Microencapsulation Technology Deployment | FMC Corporation's controlled-release systems capture premium positioning in California Central Valley specialty crop channels. |
| Parallel Registration Track Management | Simultaneous EPA, EU REACH, and India CIB dossier maintenance preserves multi-country market access amid regulatory divergence. |
| Precision Equipment Partnership | Wettable powder and suspension formulations aligned with drone-based application capture share in Brazil's soybean corridor. |
| Applicator Exposure Reduction Certification | Granular delivery systems and closed-transfer packaging respond to OSHA mandates for professional pest management channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA registration databases, EU ECHA authorization records, and India Central Insecticides Board filing archives. Primary interviews engaged formulation chemists at multinational agrochemical conglomerates, procurement leads at Brazilian agricultural cooperatives, regulatory affairs directors navigating REACH authorization timelines, and technical R&D heads at Chinese phosphorus intermediate manufacturers. Secondary validation drew from customs trade data, SEC 10-K agrochemical segment disclosures, and WHO prequalification pathway documentation. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, formulation, and distribution channel dimensions.
Segmentation dimensions modeled include active ingredient chemistry, end-use sector spanning agricultural through public health vector control, formulation technology compatibility with precision equipment, and regional regulatory cluster divergence across EPA, EU REACH, and India CIB jurisdictions. CAGRs were derived from regression analysis of historical procurement volumes against projected specialty crop protection demand and stored-grain protection program tenders. Industry-specific forecast inputs incorporated phosphorus oxychloride supply elasticity from Chinese chemical park capacity data and Codex Alimentarius residue limit negotiation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA registration review timelines and stable India CIB pre-bloom application windows for chlorpyrifos; material deviation through accelerated EU substitution mandates or Chinese environmental compliance shutdowns would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Industrial Closures Market