
 US Seaweed Fertilizers Market | 2026-2036
US Seaweed Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
US Seaweed Fertilizers Market Intelligence
Organic-certified extract grades are rotating toward premium positioning as growers face residue scrutiny from export buyers. Acadian Seaplants Limited leverages cold-pressed extraction infrastructure to sustain supply consistency for high-value fruit producers. FoxFarm Fertilizers, LLC anchors West Coast distribution through dedicated agricultural supply partnerships. Espoma specializes in home gardener SKUs with OMRI-listed formulations that differentiate at retail shelf.
US seaweed fertilizers encompass marine-derived biostimulants processed through aqueous extraction or mechanical pressing of kelp and macroalgae biomass, delivering cytokinins, auxins, and betaines that enhance nutrient uptake efficiency and abiotic stress tolerance in crop systems. Liquid extracts command the dominant volume position due to compatibility with existing fertigation infrastructure, while granular products capture margin pools among soil-applied broadacre operators seeking slow-release organic matter integration. Organic farmers represent the fastest-expanding end-user category, though commercial greenhouses retain the highest per-acre application intensity due to controlled-environment precision requirements.
The USDA National Organic Program and OMRI listing standards govern product eligibility for certified organic operations, while state-level fertilizer registration requirements in California and Florida shape interstate market access protocols. EPA oversight of pesticide-biostimulant boundary definitions creates compliance complexity for manufacturers positioning dual-function claims. Stakeholders must monitor evolving FDA and USDA jurisdiction debates over plant health product classifications to anticipate reformulation requirements and labeling obligations.
Market Dynamics
USDA National Organic Program certification mandates are compressing synthetic fertilizer margins while redirecting procurement budgets toward OMRI-listed marine biostimulants across California specialty crop operations.
Growth Catalysts
- California Fertilizer Registration Requirements:State-level compliance protocols for biostimulant labeling are clarifying product positioning and accelerating interstate distribution standardization for liquid kelp extracts.
- Controlled-Environment Agriculture:Commercial greenhouse operators in the Pacific Northwest are intensifying per-acre application rates of cytokinin-rich formulations to optimize nutrient uptake precision in hydroponic systems.
- Export Buyer Residue Scrutiny:Premium fruit producers facing EU and Japanese phytosanitary standards are rotating toward organic-certified extract grades to maintain market access for high-value shipments.
Market Restraints
- Marine Biomass Supply Concentration:Atlantic coast kelp harvesting operations face seasonal variability that constrains raw material consistency for domestic processing facilities.
- Cold-Pressed Extraction Capex:Mechanical pressing infrastructure requires substantial capital deployment compared to aqueous extraction methods, limiting manufacturer scale-up velocity.
- Synthetic NPK Substitution Threat:Conventional fertilizer price volatility creates intermittent arbitrage opportunities that delay grower conversion to organic nutrition programs.
Strategic Opportunities
- Florida State Fertilizer Registration Pathway:Dedicated registration protocols for biostimulant products are opening distribution channels for soil-applied granular formulations in southeastern broadacre operations.
- IRA-Aligned Carbon Sequestration Incentives:Federal climate agriculture funding is creating procurement subsidies for organic matter integration practices that favor slow-release seaweed products.
- Home Gardener Retail Channel:OMRI-listed consumer SKUs are capturing shelf space differentiation through dedicated agricultural supply partnerships with independent garden centers.
Industry Challenges
- EPA Pesticide-Biostimulant Boundary Disputes:Jurisdictional ambiguity over plant health product classifications is forcing reformulation cycles and relabeling expenditures for dual-function claimants.
- Biostimulant Standardization Delays:Absence of unified analytical methods for cytokinin and auxin quantification is complicating batch consistency verification and quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Seaweed Fertilizers Market |
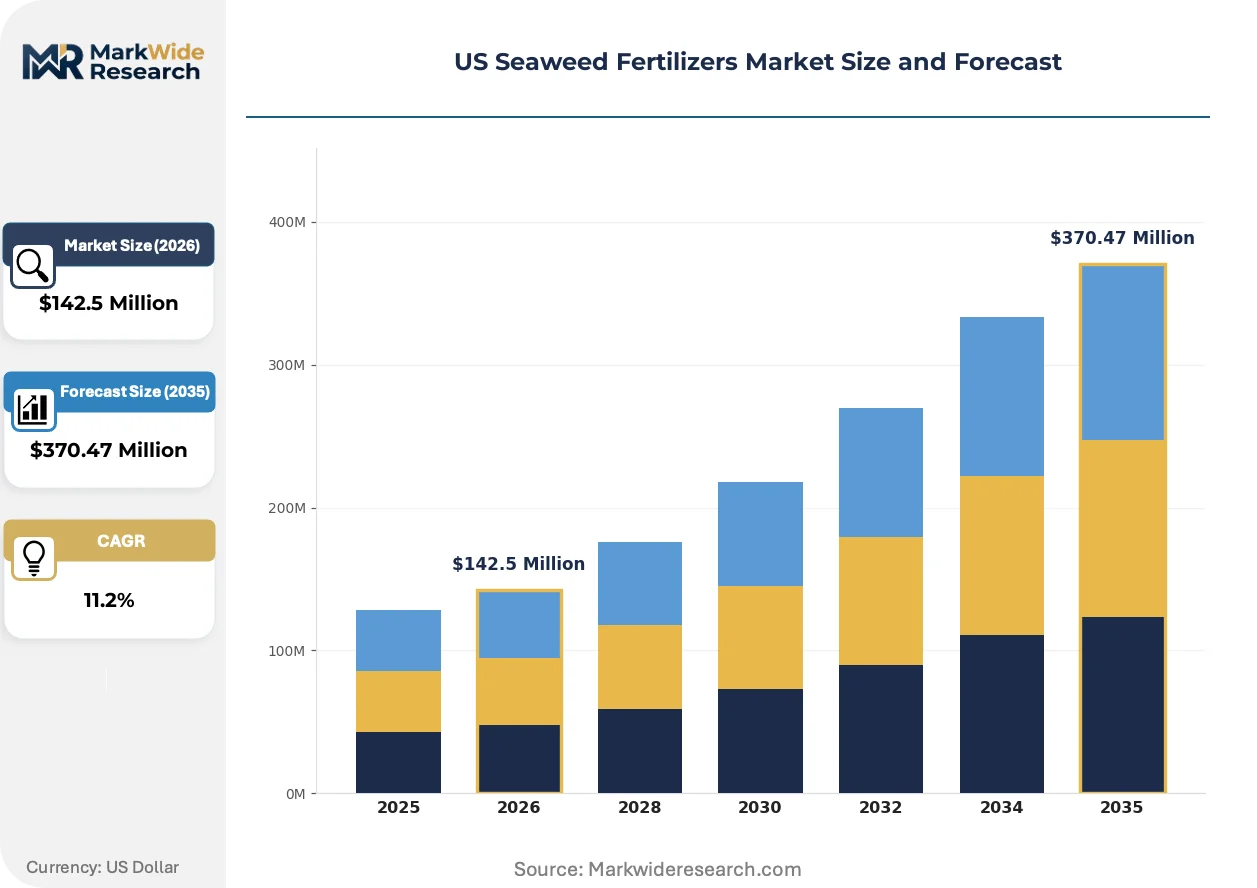
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $370.47 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Granular Products, Powder Formulations, Pelleted Fertilizers End User: Agricultural Producers, Home Gardeners, Organic Farmers, Commercial Greenhouses Application Method: Soil Application, Foliar Spray, Drip Irrigation, Seed Treatment Distribution Channel: Online Retail, Garden Centers, Agricultural Supply Stores, Wholesale Distributors |
| Companies Covered | SeaNutri LLC, FoxFarm Fertilizers, LLC, Acadian Seaplants Limited, Atlantic Sea Farms, Espoma, Kelpak, Dr. Earth Inc., Hydrofarm LLC, Maxicrop USA, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Seaweed Fertilizers Market Strategic Shifts & Innovations
Extraction technology advancement and regulatory classification clarity are restructuring competitive positioning across domestic manufacturing operations while demand patterns fragment between precision agriculture and consumer retail channels.
Cold-pressed mechanical extraction is supplanting traditional aqueous processing for high-value fruit producer segments seeking concentrated bioactive retention. California vineyard and orchard operators are adopting these premium grades at accelerated procurement cycles. This technology shift is compressing commodity-grade extract margins while enabling supply consistency premiums for certified organic operations.
USDA National Organic Program and EPA oversight convergence is tightening residue tolerance documentation requirements for biostimulant products crossing into plant protection claims. Manufacturers face reformulation expenditures to maintain OMRI eligibility while satisfying state fertilizer registration protocols. California and Florida registration authorities are responding with accelerated review timelines for single-function nutrition products.
Direct-to-grower digital procurement platforms are fragmenting traditional agricultural supply distributor control over product recommendation and technical support. Pacific Northwest organic vegetable producers are bypassing conventional channels to source certified extracts with batch-level traceability documentation. This channel disintermediation concentrates among specialty crop operations with in-house agronomy expertise and export market compliance requirements.
US Seaweed Fertilizers Market Segmentation
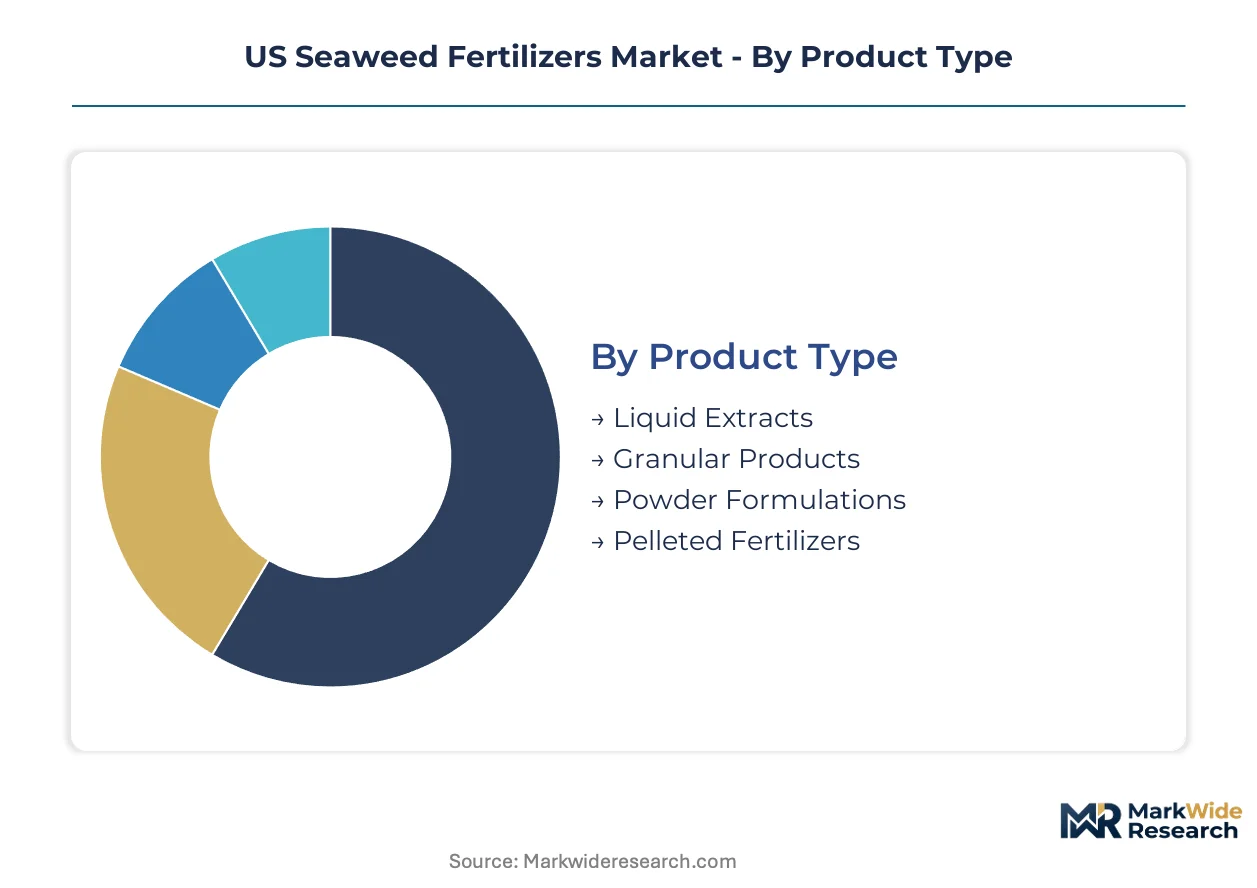
Segmentation in the US seaweed fertilizers market reveals distinct procurement patterns between export-facing specialty crop operations and domestic-focused soil amendment programs. Each dimension captures divergent technical requirements, regulatory sensitivities, and margin structures that manufacturers must navigate.
Product Type:
Liquid extracts dominate domestic volume through fertigation compatibility, while granular products concentrate among export-oriented broadacre operators seeking slow-release organic matter certification.
- Liquid Extracts:Aqueous or cold-pressed kelp concentrates delivering cytokinins and auxins in solution form. Demand concentrates among California vineyard and orchard operators facing EU phytosanitary residue thresholds for premium fruit exports. These formulations integrate seamlessly with existing drip irrigation infrastructure.
- Granular Products:Mechanically processed macroalgae biomass compressed into slow-release soil amendments. Pacific Northwest organic vegetable producers favor these for soil-applied broadacre programs requiring batch-level OMRI traceability documentation.
- Powder Formulations:Dehydrated kelp meals suited for custom blending operations and on-farm compost integration.
- Pelleted Fertilizers:Compacted granular forms optimized for mechanical spreading equipment in row-crop applications.
Liquid extracts hold the largest share; momentum sits with granular products as IRA-aligned carbon sequestration incentives expand.
End User:
Customer segmentation reflects divergent price sensitivity and technical sophistication, with organic certification requirements creating procurement standardization across otherwise fragmented demand pools.
- Organic Farmers:USDA National Organic Program compliance mandates drive OMRI-listed product specifications and residue documentation. These operators exhibit the steepest expansion trajectory as synthetic input substitution accelerates across California specialty crop regions.
- Commercial Greenhouses:Controlled-environment agriculture operators in the Pacific Northwest maintain the highest per-acre application intensity due to hydroponic precision requirements and year-round production cycles.
- Agricultural Producers:Conventional broadacre operators adopting biostimulant supplements alongside reduced synthetic programs.
- Home Gardeners:Consumer segment capturing retail shelf differentiation through independent garden center channels.
Commercial greenhouses anchor premium pricing; organic farmers are climbing the fastest as certification mandates harden.
Application Method:
Technical deployment patterns correlate directly with crop system architecture, from precision fertigation in controlled environments to broadcast soil incorporation in open-field operations.
- Foliar Spray:Direct leaf-surface application of diluted extracts for rapid nutrient uptake. High-value fruit producers facing Japanese export residue standards favor this method for targeted bioactive delivery with minimal soil interaction.
- Drip Irrigation:Continuous fertigation integration delivering diluted kelp solutions through subsurface delivery systems. Commercial greenhouse operators in Washington and Oregon dominate this segment for hydroponic nutrient precision.
- Soil Application:Surface or incorporated placement of granular or pelleted products for root-zone availability.
- Seed Treatment:Pre-planting bioactive coating for germination enhancement and early root establishment.
Drip irrigation commands the highest technical premium; foliar spray is gaining share fastest among export certification-driven operations.
Distribution Channel:
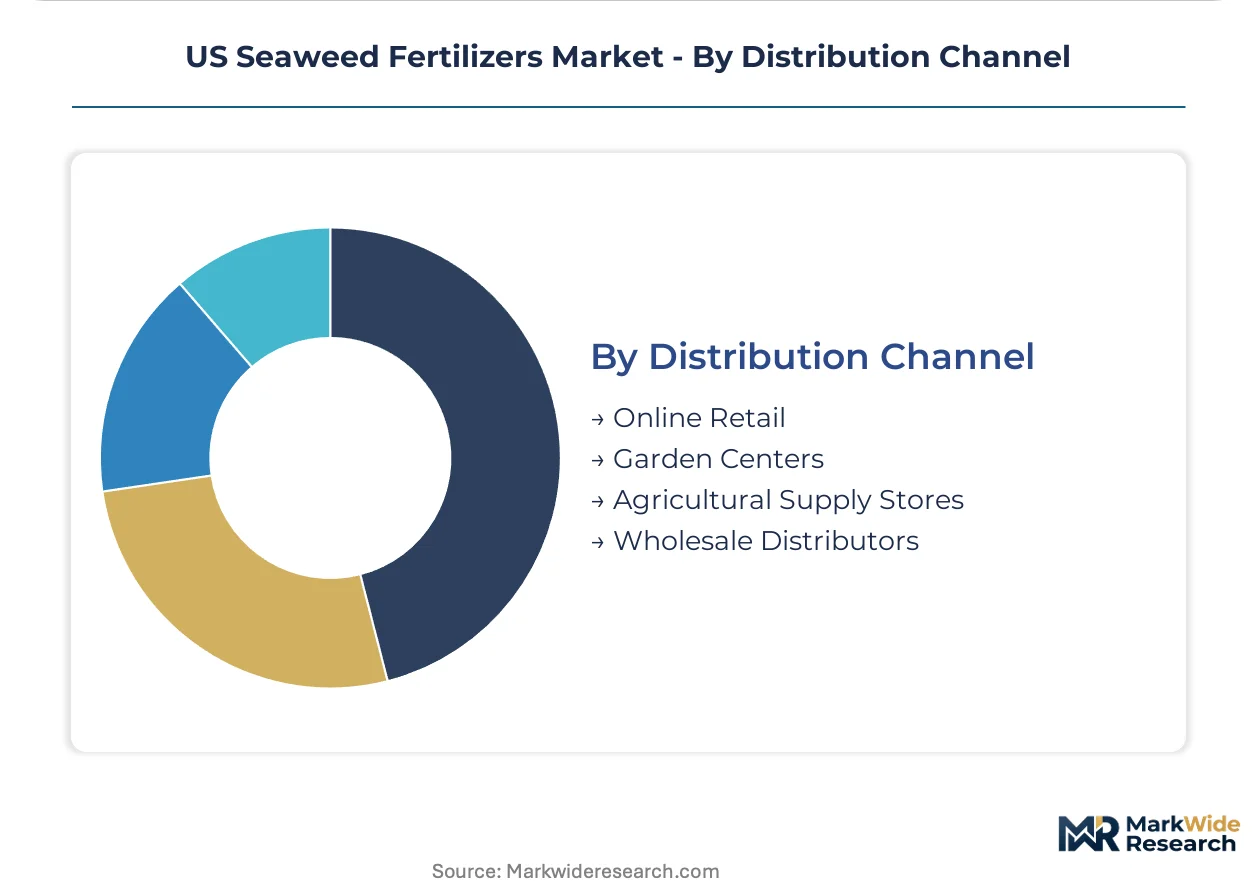
Channel structure reflects fragmentation between institutional procurement through agricultural supply partnerships and disintermediation via direct digital platforms.
- Agricultural Supply Stores:Dedicated distribution partnerships serving commercial producers with technical support and batch documentation. FoxFarm anchors West Coast presence through these relationships.
- Online Retail:Direct-to-grower digital procurement platforms enabling Pacific Northwest organic vegetable producers to bypass conventional distributors for certified extracts with traceability documentation.
- Garden Centers:Independent retail channels capturing home gardener demand through OMRI-listed consumer SKUs.
- Wholesale Distributors:Volume intermediaries serving broadacre operators with consolidated logistics.
Agricultural supply stores retain institutional volume; online retail is expanding most quickly among specialty crop operations with in-house agronomy expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic kelp harvesting concentrates along the Atlantic and Pacific coastlines, with processing infrastructure clustering near major specialty crop production zones. State-level regulatory frameworks create distinct market access conditions across key agricultural regions.
California
Specialty crop growers in the Central Valley and Central Coast are expanding biostimulant-based nutrition programs for export-facing vineyards and orchards. The California Department of Food and Agriculture maintains stringent fertilizer registration requirements that shape interstate distribution protocols. Monterey County and Sonoma County anchor concentrated demand among organic-certified vegetable and wine grape producers.
Pacific Northwest
Commercial greenhouse operators in Washington and Oregon maintain the highest per-acre application intensity of cytokinin-rich formulations for hydroponic systems. Washington State Department of Agriculture oversees biostimulant labeling compliance for controlled-environment agriculture facilities. The Willamette Valley and Skagit Valley host dense clusters of organic vegetable producers bypassing traditional distribution channels.
Florida
Southeastern broadacre operators are adopting soil-applied granular formulations for citrus and vegetable production systems. Florida Department of Agriculture and Consumer Services operates dedicated registration pathways for biostimulant products entering the state. The Lake Wales Ridge and Immokalee region concentrate demand among large-scale organic matter integration programs.
Northeast Corridor
Atlantic coast kelp harvesting operations in Maine and Massachusetts supply raw biomass for domestic processing facilities. Maine Department of Marine Resources regulates sustainable harvesting quotas that constrain seasonal supply consistency. Portland and Boston harbor areas anchor processing infrastructure serving specialty crop markets throughout New England.
US Seaweed Fertilizers Market Key Industry Players
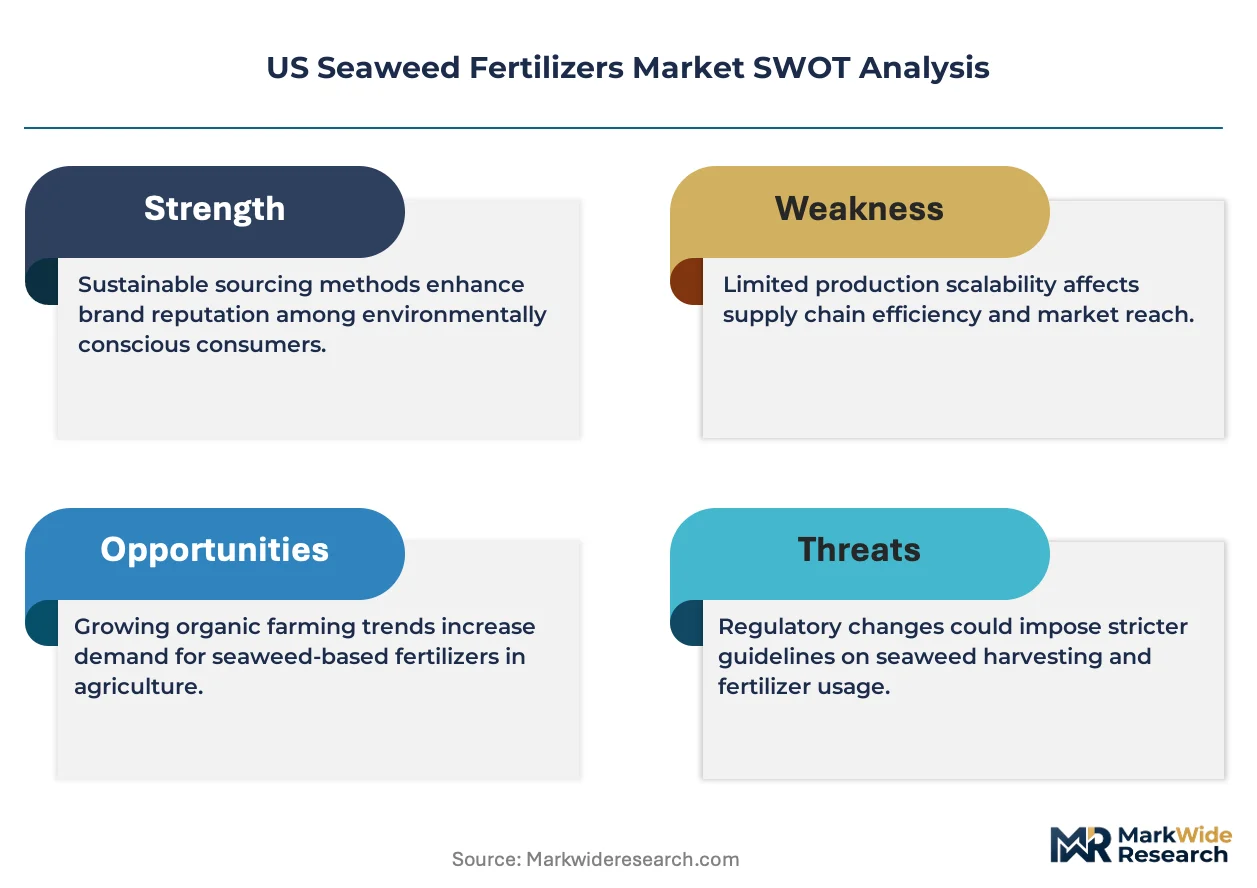
Concentration sits with marine biotechnology specialists and agricultural supply integrators rather than diversified chemical conglomerates. The vendor base spans three tiers: cold-pressed extraction specialists commanding premium positioning, aqueous processing operators serving volume markets, and retail-focused brands capturing home gardener segments. Strategic moves center on backward integration into kelp harvesting assets and geographic expansion through state-level registration acquisitions.
Among North American marine biotechnology specialists, Acadian Seaplants Limited and Atlantic Sea Farms exemplify the cold-pressed extraction archetype, while FoxFarm Fertilizers, LLC occupies a position within the agricultural supply partnership tier serving West Coast commercial producers.
| Leading Market Players |
|---|
| SeaNutri LLC |
| FoxFarm Fertilizers, LLC |
| Acadian Seaplants Limited |
| Atlantic Sea Farms |
| Espoma |
| Kelpak |
| Dr. Earth Inc. |
| Hydrofarm LLC |
| Maxicrop USA, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Atlantic coast kelp harvesters and California processing facilities lock in both raw material access and price visibility for certified organic extract grades. These arrangements insulate premium-tier buyers from seasonal biomass volatility while compressing spot-market flexibility for smaller operators.
Pricing Analysis
USDA National Organic Program certification dictates the pricing tier structure across the US seaweed fertilizers landscape. Three-tier pricing structure across premium cold-pressed, standard aqueous, and economy-grade kelp meals separates export-facing specialty crop producers from domestic soil amendment programs. Price differentiation rests on OMRI listing status and extraction method sophistication. Cost compression in commodity aqueous extracts is intensifying because synthetic NPK price volatility creates intermittent substitution arbitrage. Home gardeners through retail channels exhibit highest price sensitivity; commercial greenhouse operators in the Pacific Northwest show least sensitivity due to per-acre yield optimization requirements.
Supply Chain Analysis
Atlantic coast kelp harvesting quotas underwrite supply consistency constraints for domestic processing infrastructure. Raw biomass sourcing draws from Maine and Massachusetts coastal operations, with secondary feedstock from Nova Scotia maritime zones. Mechanical pressing equipment and aqueous extraction vessels constitute critical capital dependencies. Single-source vulnerability concentrates in seasonal Atlantic kelp harvest windows that constrain year-round processing capacity. Distribution runs through dedicated agricultural supply partnerships serving California Central Valley and Pacific Northwest greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Pacific Northwest organic vegetable producers consolidating procurement through direct digital platforms, fragmenting traditional distributor control over technical recommendation and pricing.
For Market Incumbents: Fortify backward integration into Atlantic coast kelp harvesting assets to secure captive supply of raw biomass against seasonal quota restrictions. Deepen OMRI-listed certification portfolios to defend margin position against aqueous extraction commoditization. Cold-pressed extraction capacity expansion in Maine anchors supply consistency premiums for California export-facing producers. For New Entrants and Emerging Players: Technical support gaps in batch-level traceability documentation for Pacific Northwest organic operations create entry pathways for specialized service providers. Florida citrus and vegetable broadacre segments present most penetrable geography given dedicated state registration pathways for biostimulant products. Direct-to-grower digital platforms with integrated compliance documentation offer differentiated go-to-market positioning against legacy agricultural supply partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cold-pressed extraction specialists serving export-certified organic operations with multi-year offtake arrangements. Long-term viability over the five-to-ten year horizon favors marine biotechnology specialists with captive kelp harvesting assets and California-Florida dual-registration footprints. Acquisition target archetype: mid-scale aqueous processors with underutilized capacity and Pacific Northwest distribution relationships. Signal to watch: EPA clarification on pesticide-biostimulant boundary definitions triggering consolidation among dual-function claimants facing reformulation expenditures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kelp Harvesting | Captive Atlantic biomass supply insulates against Maine Department of Marine Resources quota volatility. |
| California-Florida Dual Registration | State-level compliance coverage unlocks distribution access to specialty crop and broadacre segments simultaneously. |
| Cold-Pressed Extraction Capacity Expansion | Mechanical pressing infrastructure captures premium positioning among EU export-facing vineyard operators. |
| Direct-to-Grower Digital Platform Launch | Bypassing agricultural supply distributors concentrates margin capture among Pacific Northwest organic vegetable producers. |
| OMRI Certification Portfolio Deepening | USDA National Organic Program eligibility sustains pricing power as synthetic input substitution accelerates. |
Research Approach
Operator-level perspectives from kelp harvesting coordinators, California specialty crop agronomists, Pacific Northwest greenhouse operations managers, and agricultural supply distribution heads anchored the qualitative base. Primary field engagement combined with secondary validation against USDA National Organic Program filings, California Department of Food and Agriculture registration databases, EPA plant health product classifications, and state-level fertilizer compliance records. Bottom-up volume modeling across extraction method tiers triangulated with top-down macroeconomic agriculture expenditure patterns.
Sensitivity analysis tested forecast robustness against synthetic fertilizer price volatility scenarios and regulatory classification shifts across the projection horizon. Segmentation dimensions modeled include product type, end-user category, application method, and distribution channel, with additional granularity on OMRI certification status and state registration coverage. CAGRs were derived from historical adoption trajectory analysis and forward-looking substitution elasticity estimates. Industry-specific inputs incorporated IRA-aligned carbon sequestration incentive uptake rates and export buyer residue standard evolution.
Forecasts assume regulatory continuity in USDA National Organic Program and EPA oversight regimes; material policy shifts would require re-modeling of certification-driven demand segments. Revision becomes warranted when EPA pesticide-biostimulant boundary clarification crosses implementation thresholds or Atlantic kelp harvesting quotas undergo material contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Global Liquid Fertilizer Market