
 Dermal Regeneration Market | 2026-2036
Dermal Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Dermal Regeneration Market Intelligence
Software-as-a-service platforms for post-treatment outcome tracking is realigning the value proposition beyond the physical scaffold or membrane. Integra LifeSciences leverages its deep R&D in acellular matrices to command a premium in complex surgical repair. Smith & Nephew competes with a diversified portfolio spanning multiple wound care applications. Organogenesis differentiates through its focus on bioengineered living cell-based products for chronic wounds.
Dermal regeneration utilizes biocompatible materials to repair and reconstruct damaged skin tissue. These products often consist of a porous scaffold, frequently made from collagen or synthetic polymers, designed to guide cellular growth and neo-tissue formation. Scaffolds and matrix products dominate the market, integral to surgical repair and burns treatment applications. The wound care segment, however, is expanding rapidly due to the high prevalence of chronic non-healing wounds.
Market access is governed by stringent regulatory frameworks, including the US FDA's requirements for biologics and devices and the EU's Medical Device Regulation (MDR). These bodies mandate extensive clinical evidence for safety and efficacy, creating significant hurdles for new entrants. Navigating the development pathway between standardized allogeneic products and personalized autologous therapies remains a critical strategic decision for manufacturers.
Market Dynamics
The strategic tension between developing standardized, off-the-shelf allogeneic products versus patient-specific autologous therapies defines the market's core dynamic. This choice dictates a company's entire R&D, manufacturing, and commercialization model, from supply chain logistics to regulatory pathway selection.
Growth Catalysts
- Regulatory Pathways:The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation provides an expedited pathway for innovative cell therapies, encouraging investment and accelerating product development for critical unmet needs in wound care.
- Chronic Disease Prevalence:A rising global incidence of chronic conditions, particularly diabetic foot ulcers and venous leg ulcers, creates a sustained clinical demand for more effective and faster-healing dermal regeneration solutions.
- Stem Cell Innovation:Advances in stem cell biology and bioengineering are enabling the creation of more sophisticated living cell-based products that actively participate in the healing process, moving beyond simple structural support.
Market Restraints
- Reimbursement Hurdles:The high upfront cost of advanced cellular and bioengineered therapies faces inconsistent reimbursement coverage from payors, limiting patient access and creating commercial risk for manufacturers despite proven clinical efficacy.
- Stringent Regulations:Extensive clinical data requirements for safety and efficacy mandated by regulatory bodies like the US FDA and under the EU's Medical Device Regulation (MDR) create significant barriers to entry.
- Logistical Complexity:Living cell-based products require specialized cold-chain logistics and have a short shelf life, complicating distribution and limiting their use to well-equipped hospital systems, primarily in the United States and Germany.
Strategic Opportunities
- Geographic Expansion:Untapped markets in Asia-Pacific countries with increasing healthcare investments and a growing middle class present significant expansion opportunities for established dermal regeneration products, particularly for chronic wound applications.
- Aesthetic Applications:Developing scaffolds and matrices specifically for aesthetic and reconstructive plastic surgery represents a high-value opportunity, moving beyond the traditional focus on acute and chronic wound care.
- Technology Convergence:The integration of 3D bioprinting with dermal scaffold technology opens pathways for creating highly customized, patient-specific implants that can precisely match complex wound geometries and promote superior healing outcomes.
Industry Challenges
- Specialized Skill Gaps:A shortage of surgeons and clinical staff trained in the proper application and management of advanced dermal regeneration products can limit the adoption of new technologies, even after regulatory approval is secured.
- Clinical Outcome Standardization:The lack of standardized, widely accepted protocols for measuring and comparing treatment outcomes across different products and patient populations complicates clinical trial design and value-based assessments.
- Trial Timelines:Demonstrating long-term safety and durability for implantable biologics requires lengthy and expensive clinical trials, delaying the market entry of next-generation products and straining the resources of smaller innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermal Regeneration Market |
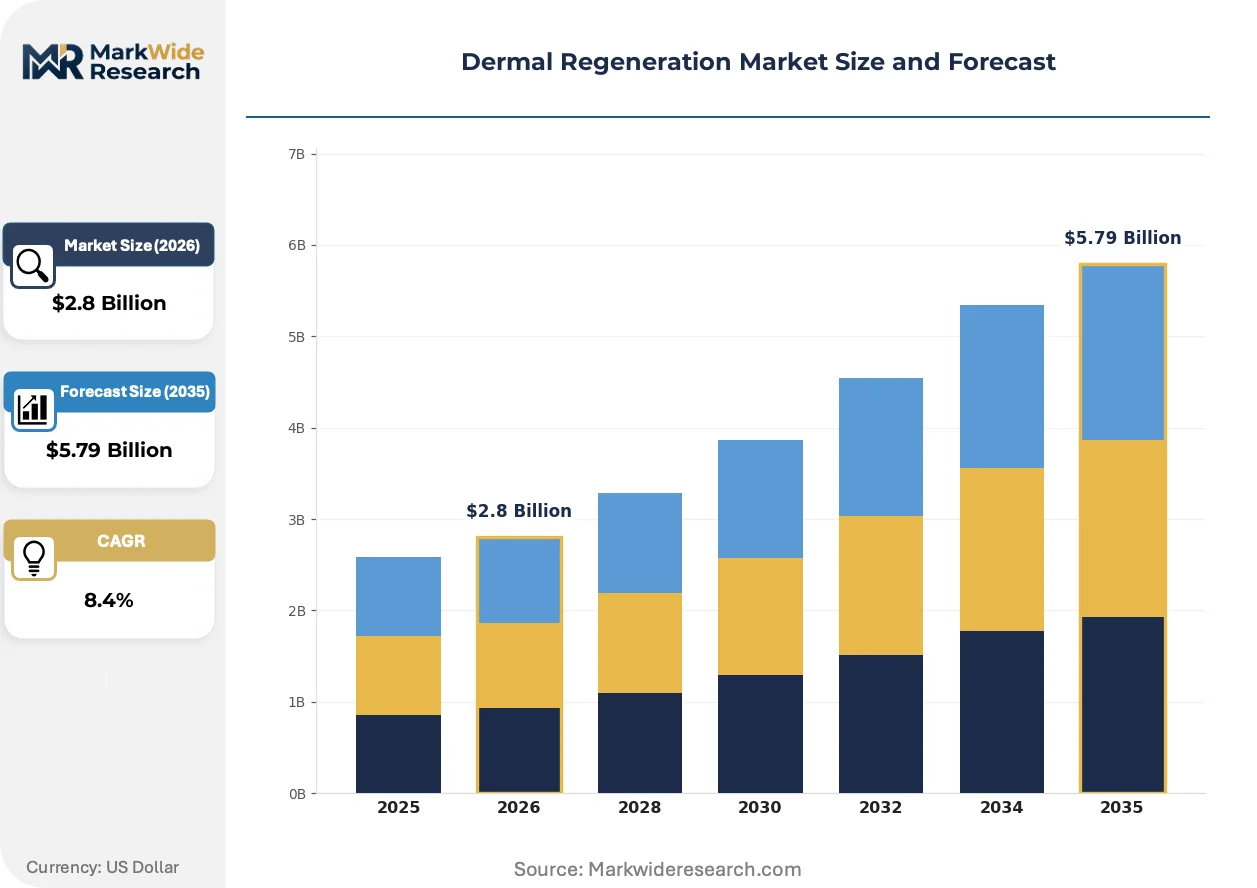
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Gels, Membranes, Matrix Application: Wound Care, Surgical Repair, Aesthetic Procedures, Burns Treatment Technology: 3D Bioprinting, Stem Cell Therapy, Biochemical Techniques, Growth Factor Release End User: Hospitals, Dermatology Clinics, Research Laboratories, Home Care |
| Companies Covered | Integra LifeSciences, Smith & Nephew, Organogenesis, MiMedx Group, Coloplast, Zimmer Biomet, Avita Medical, Matricel, Eurosurgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermal Regeneration Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from selling physical products to delivering integrated therapeutic systems. This involves embedding dermal scaffolds and matrices within a larger ecosystem of digital tracking and data analytics to validate clinical and economic outcomes.
Bioresorbable synthetic polymer scaffolds provide a predictable degradation rate and tunable mechanical properties. Surgical teams in complex reconstructive procedures are adopting these materials to ensure reliable tissue integration over a specific healing timeframe. This technology is modularizing scaffold design, enabling the fabrication of devices with customized porosity and resorption profiles tailored to individual wound characteristics and anatomical locations.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance on all medical devices. This regulatory shift elevates the data generation burden for manufacturers, especially for acellular matrices previously classified under a lower-risk framework. Consequently, companies targeting the EU market must now invest in more rigorous clinical studies to substantiate safety and performance claims, aligning device oversight more closely with pharmaceutical standards.
Hospital procurement is evolving toward value-based contracts that link payment to demonstrated patient healing rates and reduced complication risks. This model challenges the conventional unit-based sales approach, creating an advantage for manufacturers that can provide robust outcome data through post-treatment tracking platforms. The trend is most pronounced within large, integrated hospital networks in the United States and Germany that manage care for large populations with chronic conditions.
Dermal Regeneration Market Segmentation
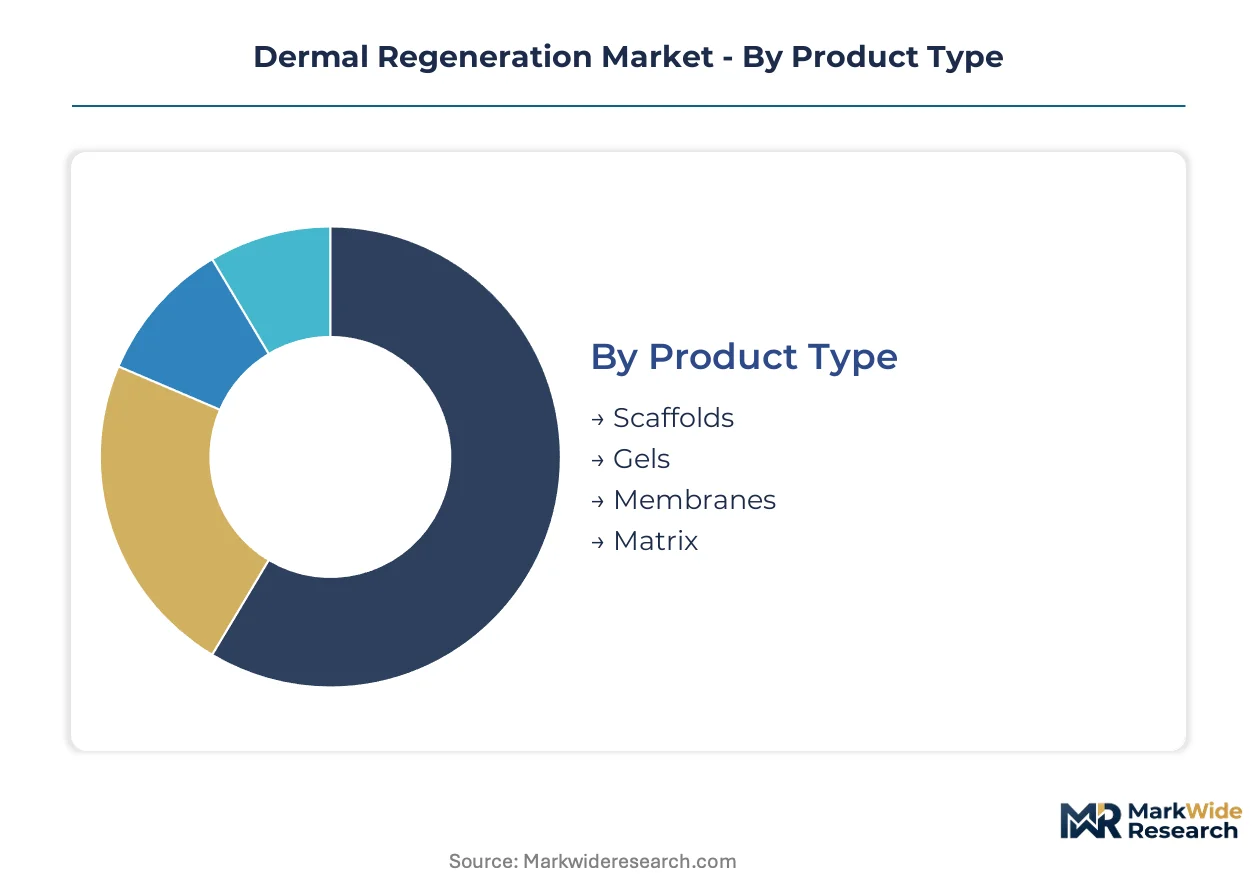
Understanding the Dermal Regeneration Market's segmentation reveals how diverse product forms, applications, technologies, and end-user settings influence demand and adoption. Manufacturers strategically align their R&D and commercialization efforts with these distinct market needs. This granular view helps identify specific growth pockets and areas requiring tailored product development.
Product Type:
Buyers in the dermal regeneration market differentiate their choices based on the required structural support and biological interaction for tissue repair. Each product type offers distinct advantages for specific wound characteristics and surgical needs.
- Scaffolds:These porous structures, often made from collagen or synthetic polymers, provide a temporary framework for cellular infiltration and new tissue formation. Demand for scaffolds concentrates in complex surgical repair and deep wound healing applications across hospital systems in the United States.
- Matrix:Acellular dermal matrices serve as biological templates, guiding host tissue integration and regeneration without introducing foreign cells. These products command a premium in reconstructive surgery and severe burn treatment, particularly within specialized trauma centers.
- Gels:Hydrogel formulations deliver bioactive agents or cells directly to the wound bed, promoting a moist healing environment.
- Membranes:Thin, flexible barriers protect wounds and facilitate gas exchange, often used in conjunction with other regenerative therapies.
Scaffolds lead volumes today; Matrix products are gaining share fastest.
Application:
Patient needs and clinical urgency drive differentiation across various dermal regeneration applications. Each segment addresses distinct medical challenges, from chronic conditions to acute traumatic injuries.
- Wound Care:This segment addresses chronic non-healing wounds, including diabetic foot ulcers and venous leg ulcers, which require prolonged and effective regenerative solutions. The rising global incidence of chronic conditions creates sustained demand for these advanced healing products.
- Surgical Repair:Dermal regeneration products are integral to reconstructive procedures, hernia repair, and soft tissue augmentation, providing structural support and promoting tissue integration. Specialized hospital systems in Germany frequently utilize these solutions for complex cases.
- Aesthetic Procedures:Products in this area focus on skin rejuvenation, scar revision, and cosmetic augmentation, emphasizing natural-looking outcomes.
- Burns Treatment:Severe burns require immediate and effective skin replacement or regeneration to prevent infection and facilitate recovery.
Wound Care applications currently generate the largest demand, while Aesthetic Procedures exhibit the steepest expansion trajectory.
Technology:
The underlying technological approach defines the regenerative capabilities and complexity of dermal reconstruction products. Innovation in this area aims to enhance healing efficacy and customize treatment options.
- Stem Cell Therapy:This technology utilizes living cells to actively participate in the healing process, moving beyond simple structural support for chronic wounds. The FDA's RMAT designation expedites development for these innovative cell therapies in the United States.
- 3D Bioprinting:This advanced manufacturing method creates highly customized, patient-specific implants matching complex wound geometries. Integration with dermal scaffold technology offers superior healing outcomes for intricate defects.
- Biochemical Techniques:These methods involve the use of growth factors and signaling molecules to stimulate natural healing processes.
- Growth Factor Release:Products incorporating controlled release mechanisms deliver therapeutic proteins to the wound site over an extended period.
Stem Cell Therapy is transforming treatment paradigms, and 3D Bioprinting is climbing the fastest in terms of R&D investment.
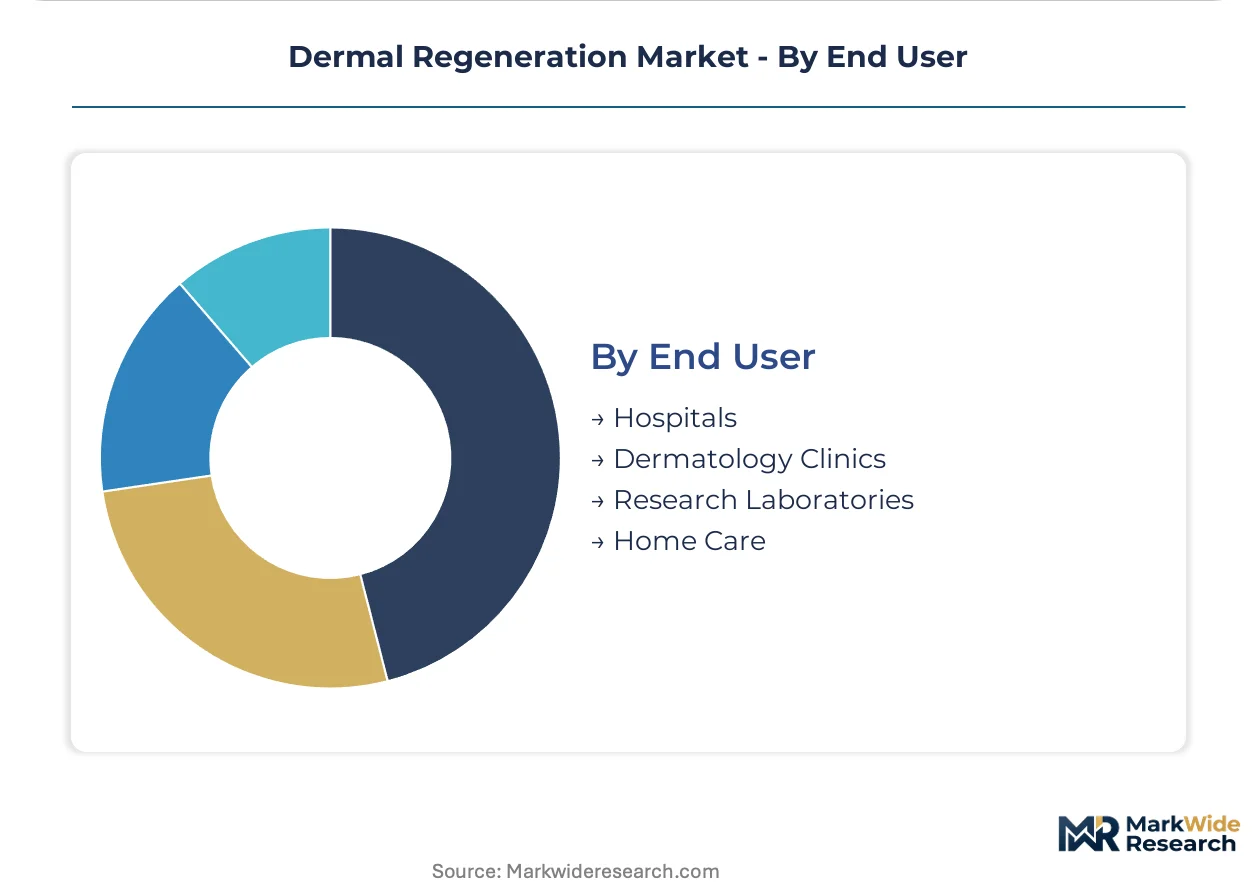
End User:
The care setting and available infrastructure significantly influence the adoption and utilization of dermal regeneration products. Different end-user environments require varying levels of product complexity and logistical support.
- Hospitals:Integrated hospital networks and specialized medical centers represent the primary end-users, equipped for complex surgical procedures and managing chronic conditions. These facilities demand products compatible with advanced operating room protocols and post-operative care.
- Dermatology Clinics:These clinics increasingly adopt dermal regeneration products for aesthetic and reconstructive plastic surgery applications. Their focus often includes scar revision, skin rejuvenation, and minor tissue augmentation procedures.
- Research Laboratories:These institutions utilize dermal regeneration materials for preclinical studies, product development, and tissue engineering research.
- Home Care:Simpler, user-friendly wound care products are slowly emerging for management of less severe conditions outside clinical settings.
Hospitals remain the largest consumer segment, while Dermatology Clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany exhibit distinct leadership in dermal regeneration, driven by advanced healthcare infrastructure and specialized medical systems. These nations concentrate demand for complex procedures and advanced bioengineered therapies. Other key regions are rapidly developing their capabilities.
United States
The United States generates substantial demand for dermal regeneration products in complex surgical repair and chronic wound management. The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates the development of innovative cell therapies. Boston's biotech hub drives significant research and development for advanced bioengineered products.
Germany
Germany leads European demand for dermal regeneration in reconstructive surgery and severe burn treatment. The EU's Medical Device Regulation (MDR) imposes rigorous clinical evidence requirements on manufacturers. Specialized hospital systems in Munich and Berlin frequently adopt advanced dermal matrices for complex cases.
Japan
Japan's aging population and focus on advanced medical technology fuel demand for aesthetic applications and sophisticated regenerative solutions. PMDA approval processes guide market entry for innovative dermal products. Tokyo's medical research centers actively integrate 3D bioprinting with dermal scaffold technologies.
China
China presents significant expansion opportunities due to increasing healthcare investments and a growing middle class. The NMPA regulates medical device approvals and market access for dermal regeneration products. Shanghai's medical device sector focuses on localizing production for bioengineered living cell-based therapies.
India
India exhibits substantial demand driven by the high prevalence of chronic conditions like diabetic foot ulcers. The CDSCO governs medical device regulations for product registration and market entry. Bangalore's medical technology parks are actively developing cost-effective dermal regeneration solutions for widespread wound care.
Dermal Regeneration Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the dermal regeneration market. This market exhibits a tiered structure, with established players commanding premium pricing in complex surgical repair and advanced wound care. Key strategic archetypes include bioengineered cell therapy innovators, scaffold and matrix product leaders, and diversified wound care providers. Companies pursue portfolio diversification, strategic partnerships, and targeted geographic expansion to enhance their market reach and competitive positioning.
Specialists in advanced regenerative solutions, Integra LifeSciences and Organogenesis, exemplify distinct approaches within this competitive environment. Integra LifeSciences leverages its deep research and development in acellular matrices, occupying a premium position in complex surgical repair applications. Organogenesis differentiates through its focus on bioengineered living cell-based products, particularly for chronic wounds, representing the innovative edge of cellular therapies. Smith & Nephew sits within the diversified portfolio archetype, offering a broad range of wound care applications and competing across various market segments.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Smith & Nephew |
| Organogenesis |
| MiMedx Group |
| Coloplast |
| Zimmer Biomet |
| Avita Medical |
| Matricel |
| Eurosurgical |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists in advanced wound care often dictate pricing power by controlling niche manufacturing capabilities, influencing both supply behavior and market value perception for bioengineered products.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for standardized acellular matrices. Value-based contracts are becoming the dominant pricing model, linking payment to demonstrated patient healing rates. Price differentiation stems from product innovation, particularly for living cell-based therapies, and stringent regulatory certifications like FDA RMAT. Pricing softness runs through commodity scaffold products due to increased competition. Hospitals managing complex surgical repair cases are less price-sensitive than dermatology clinics seeking aesthetic solutions.
Supply Chain Analysis
Workforce availability in specialized bioengineering and manufacturing hubs across the United States and Germany critically impacts production scalability. The dermal regeneration supply chain primarily draws from collagen and advanced synthetic polymers as raw material dependencies. Cold-chain logistics for living cell-based products represent a significant structural risk, limiting distribution reach and increasing operational costs. Distribution runs through a highly specialized network of hospital systems and trauma centers equipped for complex procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, driven by a demand-shift toward premium specifications for patient-specific implants and advanced bioengineered solutions.
For Market Incumbents:Deepen research and development into next-generation stem cell therapies, particularly for chronic non-healing wounds. Consolidate market share through strategic acquisitions of smaller innovators specializing in 3D bioprinting technology. Address the growing threat of reimbursement hurdles by investing in robust post-treatment outcome tracking platforms. Maintain strong channel control within specialized hospital systems for complex surgical repair applications.
For New Entrants and Emerging Players:Regional distributors represent a key channel partner type for penetrating untapped markets in Asia-Pacific countries with increasing healthcare investments. Target aesthetic applications and specific chronic wound types with novel, cost-effective scaffold designs for market entry. Leverage rapid regulatory pathways like the FDA's RMAT designation for innovative cell therapies. Focus go-to-market strategies on demonstrating clear clinical and economic outcomes through digital tracking platforms.
For Investors and Strategic Acquirers:Valuations sit cheapest among smaller innovators with promising preclinical data in living cell-based products or 3D bioprinting. The long-term viability of this market hinges on continued innovation in bioengineered solutions for chronic conditions. Acquisition targets should prioritize companies demonstrating strong intellectual property in personalized autologous therapies. The signal to watch for inflection is the consistent approval and reimbursement of advanced cellular products under value-based contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Stem Cell R&D | Accelerates development of sophisticated living cell therapies for chronic wounds. |
| 3D Bioprinting Integration | Enables highly customized, patient-specific implants for complex wound geometries. |
| Geographic Expansion into Asia-Pacific | Captures demand from growing middle-class populations with increasing healthcare access. |
| Value-Based Contract Development | Aligns payment with demonstrated patient healing outcomes and reduced complication risks. |
| Regulatory Pathway Optimization | Streamlines FDA RMAT and EU MDR compliance for faster market entry of innovative products. |
Research Approach
Direct dialogue with clinicians, hospital procurement managers, regulatory affairs leads, and R&D directors provided qualitative grounding for this analysis. This primary research was complemented by secondary validation from sources including FDA filings, EMA submissions, industry reports, and company financial statements. A rigorous process of bottom-up and top-down triangulation ensured data consistency and accuracy.
A bottom-up analytical lens was applied to build detailed market sizing across the analysis window. Segmentation dimensions modeled included product type, application, technology, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected through quantitative models, incorporating industry-specific inputs such as chronic disease prevalence and RMAT designation uptake.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement policy shifts and major regulatory changes. Forecasts reflect assumptions documented through extensive primary and secondary research. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Retinoids Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Incontinence Skin Care Products Market
Skincare
Organic Skincare Products Market
Skincare
Peel Off Face Mask Market
Skincare
Global Skin Tears Treatment Market
Skincare
Biological Skin Substitutes Market
Skincare
Europe Functional Cosmetics Market
Skincare
Skincare Ingredients Market
Skincare
Skin Bioactive Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Tinted Sunscreen Market
Skincare
Skin Care Emulsion Market
Skincare
Skin Antiseptic Market