
 Cosmetic Threads Market | 2026-2036
Cosmetic Threads Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Threads Market Analysis
Multi-source procurement for polydioxanone and polycaprolactone raw materials is decoupling from traditional single-source polymer supply chains in the cosmetic threads industry. Croma-Pharma leverages captive European manufacturing to control batch consistency for its PDO thread portfolios. Medtronic anchors its position through R&D intensity in resorbable polymer engineering for aesthetic applications. Aptos International competes via specialized barbed-thread geometries that differentiate its lifting systems from smooth-monofilament alternatives.
Cosmetic threads are absorbable sutures manufactured from biocompatible polymers such as polydioxanone, poly-L-lactic acid, or polycaprolactone, typically ranging from 18 to 30 gauge with tensile strengths engineered to maintain tissue lift for 6–24 months before hydrolytic degradation. Their primary commercial purpose is to provide minimally invasive soft-tissue suspension and collagen neogenesis for facial and body rejuvenation without excisional surgery. PDO threads occupy the largest volume position due to established clinical familiarity and lower material cost, while PCL threads represent the fastest-expanding category because extended longevity commands premium pricing in medical spa channels. Facial rejuvenation applications concentrate margin pools where thread lifting displaces traditional blepharoplasty and rhytidectomy procedures among patients aged 35–55.
The FDA regulates cosmetic threads as Class II medical devices requiring 510(k) clearance for specific indications, while the EU MDR mandates updated clinical evidence and notified-body certification for continued market access. South Korea's MFDS maintains stringent biocompatibility protocols that domestic manufacturers use as export-quality benchmarks for Southeast Asian registrations. Stakeholders must monitor evolving polymer degradation profiles against tightening post-market surveillance requirements as regulators link long-term tissue response data to renewal timelines.
Market Dynamics
EU MDR's tightened biocompatibility standards are forcing thread manufacturers to rebuild clinical evidence packages and diversify polymer sourcing away from single-origin supply chains. This regulatory compression is reshaping competitive positioning by privileging firms with captive manufacturing and in-house polymer engineering capabilities.
Growth Catalysts
- Absorbable polymer longevity extension:Polycaprolactone threads now maintain tissue lift for 24-plus months, commanding premium positioning in medical spa channels and displacing shorter-duration PDO alternatives among patients seeking durable results.
- MFDS export-quality benchmarks:South Korea's stringent biocompatibility protocols have become de facto quality standards for Southeast Asian registrations, enabling domestic manufacturers to capture share in Thailand, Vietnam, and Indonesian aesthetic markets.
- Dermatology clinic channel expansion:Minimally invasive thread lifting is capturing patient flow from traditional surgical facelift practices, with clinics in Seoul, São Paulo, and Dubai building dedicated thread procedure suites.
Market Restraints
- Polydioxanone raw material concentration:Three Asian polymer suppliers control majority capacity for medical-grade PDO, creating input cost volatility and qualification delays for manufacturers seeking secondary sourcing.
- 510(k) clearance pathway friction:FDA's evolving evidentiary requirements for absorbable suture indications have extended pre-market timelines, compressing revenue recognition windows for product iterations.
- Surgical facelift substitution resilience:High-definition liposuction and energy-based skin tightening technologies retain preference among patients seeking single-procedure outcomes, limiting thread penetration in premium aesthetic segments.
Strategic Opportunities
- Brazil's ANVISA registration acceleration:Streamlined medical device pathways for absorbable polymers create first-mover advantage for manufacturers establishing local distributor partnerships ahead of competitor entry.
- Body contouring application expansion:Thread lifting protocols for décolletage, buttock, and knee laxity represent unpenetrated volume pools beyond established facial rejuvenation indications.
- Combination therapy protocol integration:Thread procedures bundled with energy-based devices and biostimulatory injectables are capturing higher per-patient revenue in Dubai and London medical spa channels.
Industry Challenges
- Practitioner certification standardization:Absence of unified training curricula across MFDS, FDA, and EU MDR jurisdictions creates variable outcomes and liability exposure for clinic operators.
- Post-market surveillance data assembly:Regulators now mandate long-term tissue response documentation for renewal timelines, forcing manufacturers to rebuild legacy product clinical portfolios retroactively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Threads Market |
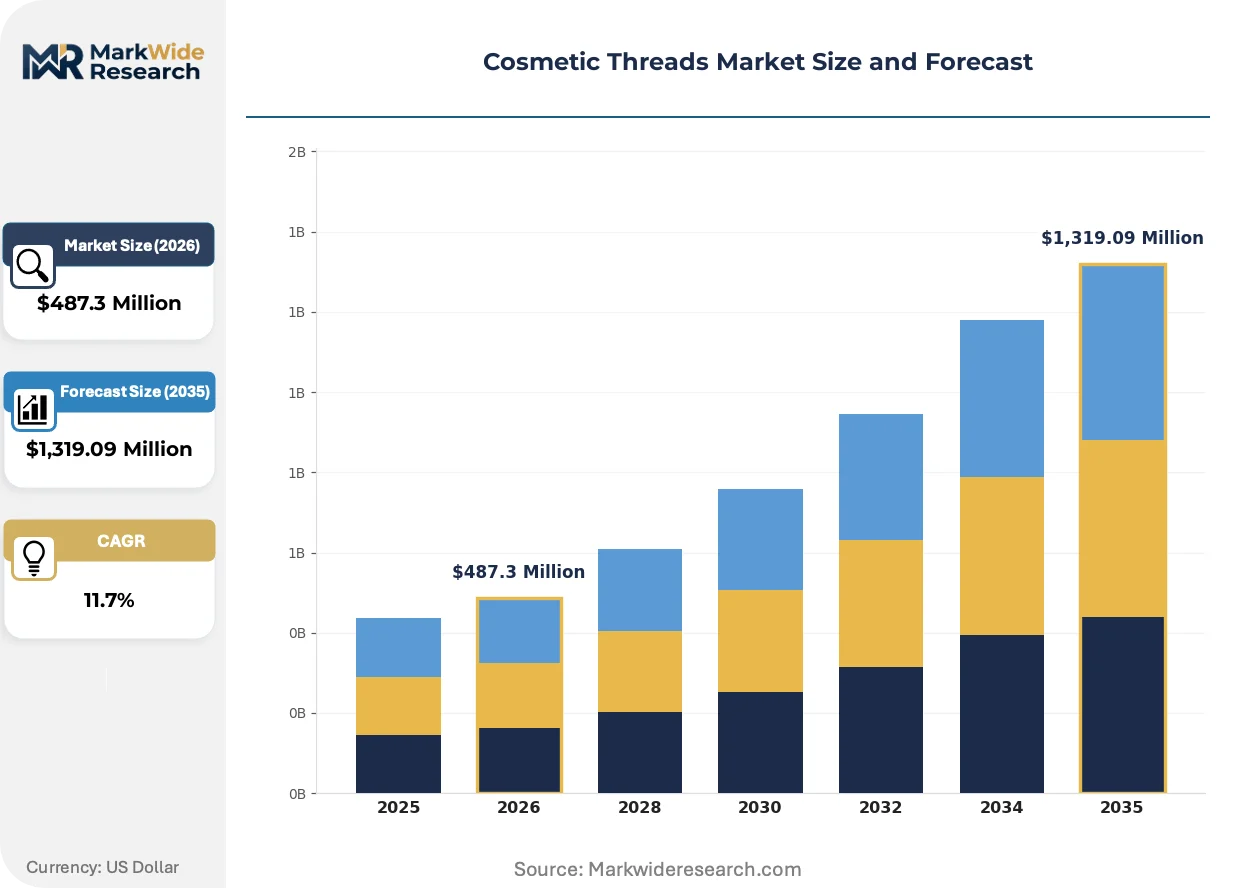
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PDO Threads, PLLA Threads, PCL Threads, Suture Threads Application: Facial Rejuvenation, Neck Lifting, Body Contouring, Eyelid Tightening End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Home Users Distribution Channel: Direct Sales, Online Retail, Distributors, Medical Suppliers |
| Companies Covered | Croma-Pharma, Medtronic, Aptos International, Medytox, Jeisys Medical, Sinclair Pharma, Johnson & Johnson, Caregen, Merz Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Threads Market Emerging Trajectories
Barbed thread geometries and resorbable polymer engineering are converging to extend procedure longevity while compressing practitioner learning curves. These developments are automating aspects of tissue placement and reducing reliance on surgical skill depth.
3D-printed thread molds with variable barb density are automating quality consistency in barbed-lift production. Korean and German manufacturers are adopting these systems to reduce batch-to-batch mechanical variation. The technology is compressing defect rates and enabling tighter tolerance specifications for premium-tier product lines.
EU MDR's updated clinical evidence requirements are mandating biocompatibility study protocols that exceed prior Medical Device Directive standards. Thread manufacturers must now submit hydrolytic degradation data and long-term tissue integration profiles for continued CE marking. Absorbable polymer portfolios face the steepest compliance burden, with PCL and PLLA thread categories requiring expanded toxicology packages.
Medical spa channels are unbundling thread procedures from traditional plastic surgery practice affiliations. Independent aesthetic clinics in São Paulo, Bangkok, and Istanbul are building direct procurement relationships with polymer manufacturers, bypassing distributor markups. This channel fragmentation is most visible in markets where regulatory enforcement permits parallel importation of Korean-manufactured devices.
Cosmetic Threads Market Segmentation
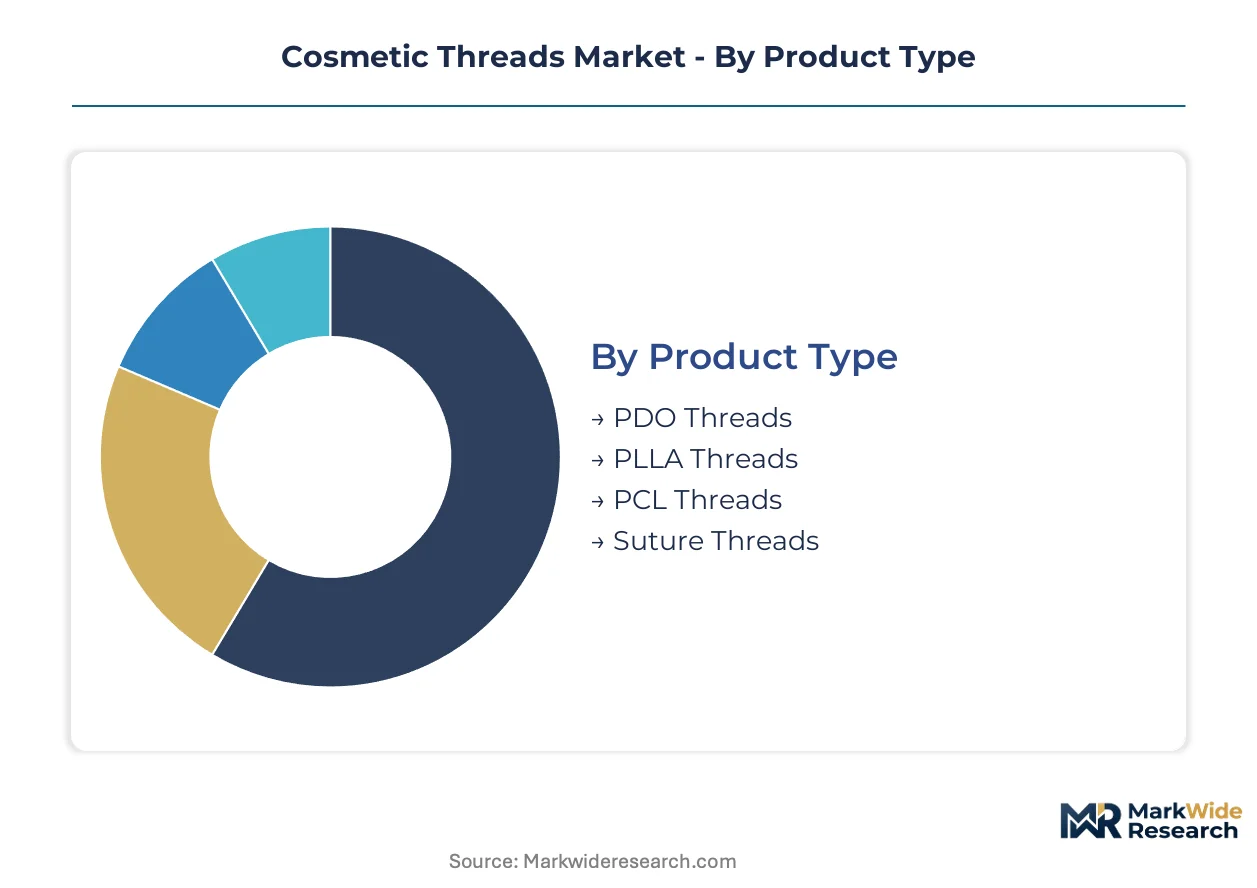
Segmentation in cosmetic threads reveals how polymer chemistry, anatomical application, and channel economics partition margin pools. Manufacturers configure R&D and certification investments differently across these dimensions.
Product Type:
Capital intensity escalates with polymer complexity and degradation profile engineering.
- PDO Threads:Polydioxanone monofilaments hydrolyze within 6–12 months, requiring simpler extrusion equipment and shorter toxicology packages. Demand concentrates in Seoul's medical spa corridor where price-sensitive volume procedures dominate. Korean manufacturers leverage this segment to amortize polymer plant capacity across aesthetic and surgical suture lines.
- PCL Threads:Polycaprolactone's extended 24-plus month degradation window demands advanced copolymer formulation and longer-term biocompatibility studies. Dubai and London clinics absorb premium positioning for durable lift outcomes. Capital recovery timelines stretch longest here.
- PLLA Threads:Poly-L-lactic acid threads stimulate collagen neogenesis through particulate degradation, occupying mid-tier positioning between PDO and PCL economics.
- Suture Threads:Smooth monofilament variants for superficial dermal placement require minimal barbing equipment investment, serving entry-level practitioner training markets.
Most installed capacity flows through PDO Threads. Expansion is steepest in PCL Threads.
Application:
Procedure reimbursement rates and liability exposure diverge sharply across anatomical zones.
- Facial Rejuvenation:Mid-face and jowl lifting commands the deepest practitioner training investments and highest consumable pricing. São Paulo's dermatology clinics have built dedicated thread suites around this indication. Malpractice coverage requirements concentrate capital in certified operator networks.
- Body Contouring:Décolletage, buttock, and knee protocols remain underpenetrated with limited standardized training curricula. Bangkok aesthetic chains are piloting thread lifting for post-liposuction skin retraction. Regulatory clarity lags facial applications.
- Neck Lifting:Submental thread placement requires precise platysma engagement, restricting adoption to advanced certification tiers.
- Eyelid Tightening:Periorbital anatomy limits thread gauge options and demands micro-cannula instrumentation, compressing addressable volume.
Certified practitioner pools concentrate in Facial Rejuvenation. Steepest expansion trajectory runs through Body Contouring.
End User:
Customer type determines procurement scale, brand loyalty cycles, and technical support intensity.
- Dermatology Clinics:Physician-supervised settings in Germany and South Korea drive protocol standardization and combination therapy adoption. These accounts negotiate direct manufacturer relationships with volume commitments.
- Medical Spas:Non-surgical aesthetic centers in Istanbul and Bangkok prioritize turnkey training packages and disposable instrument bundling. Purchase decisions emphasize consumable cost per procedure over capital equipment.
- Cosmetic Surgery Centers:Hybrid surgical facilities thread lifting as adjunct to excisional procedures, requiring regulatory documentation bridging device and biologic classifications.
- Home Users:Self-administration remains fringe due to MFDS and FDA prohibition on direct-to-consumer absorbable suture sales, limiting legitimate channel development.
Dermatology Clinics absorb the majority of premium-tier volume. Medical Spas are climbing the fastest.
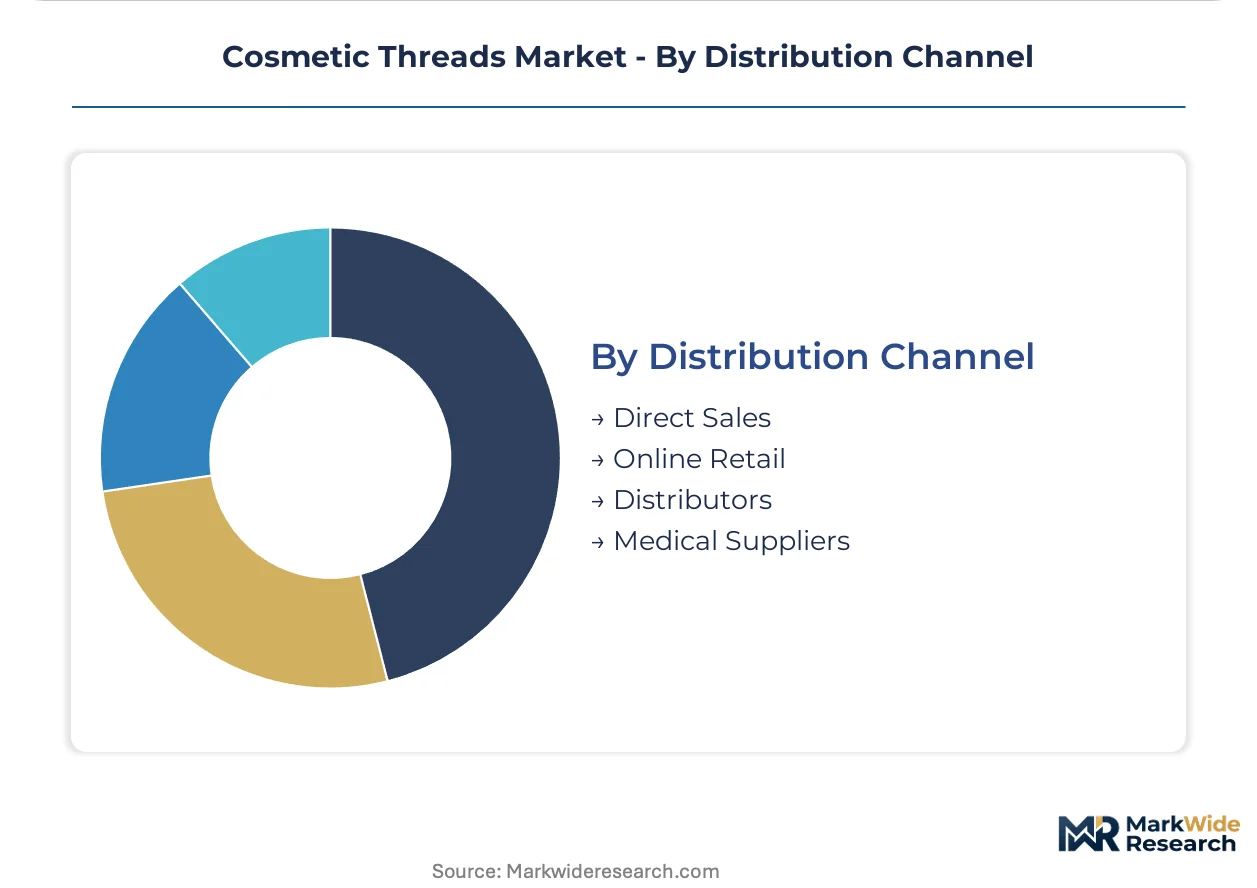
Distribution Channel:
Channel selection locks in margin capture, geographic reach, and post-sale technical support obligations.
- Direct Sales:Manufacturer field forces serve high-volume clinic chains in Seoul and São Paulo with embedded training and procedure support. Salesforce compensation and clinical education infrastructure represent substantial fixed cost layers.
- Distributors:Regional medical device wholesalers dominate Southeast Asian market development, requiring inventory financing and regulatory filing assistance. Vietnamese and Indonesian registrations flow through these intermediaries.
- Medical Suppliers:Group purchasing organizations aggregate demand across hospital-affiliated aesthetic departments, compressing pricing through consolidated procurement.
- Online Retail:E-commerce penetration remains constrained by prescription-device classifications in the EU and US, though Brazilian parallel import channels operate in regulatory gray zones.
Distributor relationships capture most emerging market expansion. Direct Sales is gaining share fastest in established aesthetic corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's medical spa corridor concentrates the highest procedure density for absorbable polymer threads, with domestic manufacturers supplying both local clinics and export registrations across Southeast Asia. Demand clusters in metropolitan aesthetic hubs where dermatology practices displace surgical facelift volume.
South Korea
Seoul's Gangnam district hosts the densest concentration of thread-lifting procedure suites, with dermatology clinics capturing patients aged 35–55 seeking minimally invasive alternatives. MFDS biocompatibility protocols exceed regional baselines, creating de facto quality standards that domestic manufacturers leverage for Thai and Vietnamese registrations. Busan-Ulsan industrial clusters supply medical-grade PDO polymers to both aesthetic and surgical suture markets.
United States
Dermatology practices in Los Angeles and Miami have built dedicated thread procedure suites, capturing patient flow from traditional plastic surgery centers. FDA 510(k) clearance pathways for absorbable suture indications have extended pre-market timelines, compressing revenue windows for product iterations. Greater New York aesthetic chains negotiate direct manufacturer relationships, bypassing traditional distributor markups.
Germany
Munich and Frankfurt dermatology clinics drive protocol standardization for combination therapy approaches, bundling threads with energy-based devices. EU MDR mandates updated clinical evidence and notified-body certification, forcing manufacturers to rebuild biocompatibility packages for continued CE marking. Baden-Württemberg polymer engineering clusters supply advanced copolymer formulations for extended-degradation thread categories.
Brazil
São Paulo's independent aesthetic clinics build direct procurement relationships with Asian manufacturers, exploiting ANVISA registration acceleration for absorbable polymers. Streamlined medical device pathways create first-mover positioning for distributors establishing local partnerships. Rio de Janeiro medical spa channels prioritize turnkey training packages and disposable instrument bundling over capital equipment.
United Arab Emirates
Dubai medical spa channels command premium positioning for PCL threads with 24-plus month longevity, targeting patients seeking durable lift outcomes. MOHAP regulations permit parallel importation of Korean-manufactured devices, fragmenting traditional distributor channels. Abu Dhabi cosmetic surgery centers thread lifting as adjunct to excisional procedures, requiring documentation bridging device and biologic classifications.
Cosmetic Threads Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized barbed geometries and extended-degradation polymer formulations. The vendor base stratifies across captive manufacturing specialists, diversified medical device conglomerates, and regional aesthetic-focused suppliers. Three archetypes dominate: polymer engineering specialists controlling upstream material quality, procedure-technology integrators bundling training with consumables, and distributor-anchored regional players leveraging registration expertise. Competitive moves concentrate on M&A to secure polymer plant capacity and strategic partnerships to accelerate multi-jurisdiction regulatory filings.
Within the polymer engineering tier, Croma-Pharma and Medtronic exemplify divergent scale positions, while Aptos International occupies a specialized geometry-focused niche. Croma-Pharma leverages European captive manufacturing to control batch consistency for PDO portfolios. Medtronic anchors its position through R&D intensity in resorbable polymer engineering for aesthetic applications. Aptos International competes via specialized barbed-thread geometries that differentiate its lifting systems from smooth-monofilament alternatives.
| Leading Market Players |
|---|
| Croma-Pharma |
| Medtronic |
| Aptos International |
| Medytox |
| Jeisys Medical |
| Sinclair Pharma |
| Johnson & Johnson |
| Caregen |
| Merz Pharma |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU MDR-compliant and legacy-cleared thread portfolios splits pricing power along regulatory compliance lines, with premium-tier PCL threads commanding three-to-four-fold multiples over economy PDO variants while supply chains reorganize around polymer plant proximity to notified-body jurisdictions.
Pricing Analysis
Input-cost pass-through from medical-grade PDO and PCL polymer feedstocks drives transactional per-unit pricing, with three-tier pricing structure across premium, standard, and economy levels separating extended-degradation PCL from mid-tier PLLA and commodity PDO alternatives. Price differentiation rests on MFDS export-quality certification and EU MDR compliance grade, with Dubai and London clinics showing least price sensitivity for 24-month longevity claims while Bangkok medical spas compress margins on volume PDO procedures. Pricing pressure stems from polydioxanone raw material concentration among three Asian suppliers, forcing secondary-qualification cost absorption.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled thread batches remain minimal given absorbable polymer degradation, yet South Korean manufacturers maintain return protocols for non-conforming barbed geometries to protect MFDS registration integrity. Geographic supply concentrates in South Korea, Germany, and China's polymer engineering clusters, with raw material dependencies on medical-grade PDO, PCL copolymers, and precision extrusion dyes. Single-source vulnerability in Asian PDO feedstock creates qualification delays for Western manufacturers seeking supply diversification. Distribution runs through direct sales forces in Seoul and São Paulo alongside regional distributors capturing Southeast Asian regulatory filing complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between South Korea's stringent MFDS protocols and Brazil's accelerated ANVISA pathways, where regulatory cost differentials of 18-24 months in clearance timelines reward first-mover manufacturing partnerships.
For Market Incumbents: Deepen captive polymer engineering capabilities to defend against PCL formulation specialists eroding premium positioning, while securing dual-source PDO qualifications to mitigate Asian supplier concentration risk. Prioritize EU MDR clinical evidence rebuilds ahead of renewal timelines to maintain CE-marked channel access. For New Entrants and Emerging Players: Capture body contouring application white space in décolletage and knee laxity protocols where standardized training curricula remain undeveloped, with São Paulo's independent aesthetic clinics offering the most penetrable entry point through direct procurement relationships bypassing distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where polymer plant capacity scarcity meets extended-degradation formulation expertise, favoring mid-cap specialists with Korean or German manufacturing footprints and active Southeast Asian registration pipelines. Long-term viability hinges on post-market surveillance data infrastructure; monitor EU MDR renewal timeline announcements as inflection indicators for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Rebuild | Notified-body certification for PCL and PLLA threads ensures continued CE-marked access across German and UAE channels. |
| Dual-Source Polymer Qualification | Secondary PDO sourcing from Baden-Württemberg clusters reduces dependency on concentrated Asian feedstock suppliers. |
| Body Contouring Protocol Development | Décolletage and knee lifting curricula capture unpenetrated volume pools beyond saturated facial rejuvenation indications. |
| Direct Procurement Channel Establishment | Manufacturer-clinic relationships in São Paulo and Istanbul bypass distributor markups and accelerate price positioning. |
| Post-Market Surveillance Infrastructure | Long-term tissue response databases satisfy tightening renewal timelines for absorbable polymer portfolios. |
Methodological Framework
Direct dialogue with dermatology clinic operators, biomedical procurement managers, polymer plant technical directors, and regulatory affairs specialists across Seoul, São Paulo, and Munich grounded qualitative findings, cross-referenced with MFDS registration databases, EU MDR notified-body filings, ANVISA approval records, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down polymer consumption data from Korean and German industrial clusters.
Segment-level outputs across the projection horizon reflect modeled interactions between polymer chemistry tiers, anatomical application zones, and channel economics, with CAGRs derived from elasticity-adjusted adoption curves and practitioner certification pipeline trajectories. Forecast inputs incorporated EU MDR compliance cost absorption rates and Southeast Asian registration velocity differentials.
Regulatory timeline compression, polymer feedstock supply disruption, and practitioner certification standardization delays are the dominant revision risks to modeled adoption trajectories. Practitioners should monitor notified-body queue lengths, Asian PDO plant utilization rates, and combination therapy protocol reimbursement decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Facial Bone Contouring Market