
 Retinoids Market | 2026-2036
Retinoids Market Size, Share, and Industry Trends Forecast 2026-2036
Retinoids Market Analytics
Pharmaceutical-grade retinoid formulations is reorganizing competitive dynamics across the skincare and dermatology sectors. Galderma leverages its vertical integration in prescription dermatology to control supply chains for adapalene and tazarotene portfolios. Johnson & Johnson sustains brand strength in consumer-facing retinol through science-backed positioning and clinical validation. Bayer anchors its position with differentiated oral retinoid compounds serving severe acne and psoriasis protocols.
Retinoids comprise a class of vitamin A derivatives including retinol, retinaldehyde, tretinoin, adapalene, and tazarotene, structurally characterized by a beta-ionone ring and conjugated polyene side chain that binds nuclear retinoic acid receptors to modulate gene transcription. These compounds primarily serve dermatological applications by regulating epidermal cell proliferation, collagen synthesis, and sebaceous gland activity. Topical retinoids dominate current revenue pools due to established reimbursement pathways and physician familiarity, while combination therapies represent the fastest-expanding segment as clinicians seek synergistic mechanisms against resistant acne and photoaging. Oral retinoids command premium pricing structures but face maturity constraints from teratogenicity monitoring requirements and generic competition.
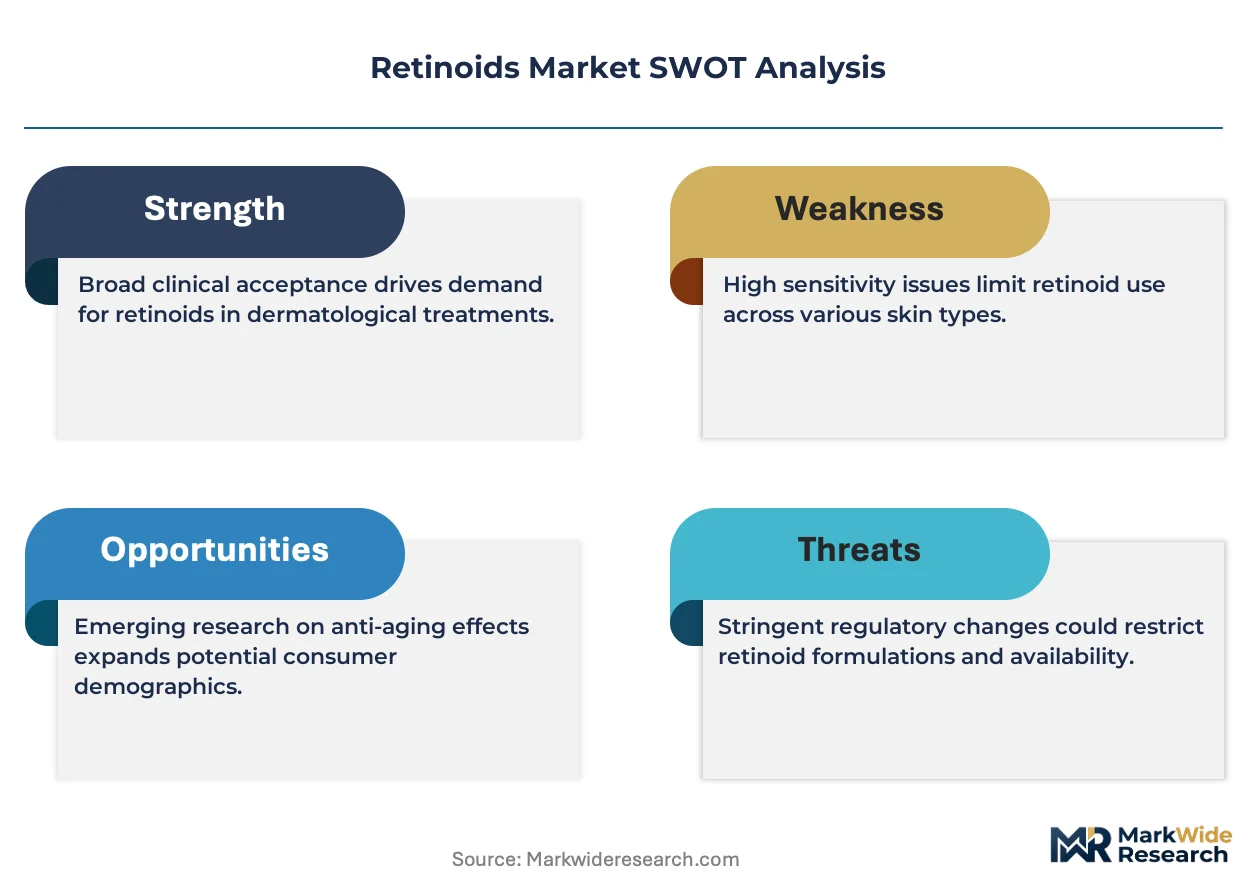
The US FDA maintains stringent bioequivalence and teratogenicity risk evaluation protocols for all retinoid drug applications, directly shaping product development timelines and labeling requirements. The EMA enforces comparable vigilance through its pharmacovigilance framework, while REACH compliance governs cosmetic-grade retinol concentrations across European formulations. Stakeholders must monitor evolving iPLEDGE-equivalent risk management programs and emerging regulatory scrutiny over retinoid stability in compounded preparations.
Market Dynamics
The Retinoids Market is restructuring around FDA-mandated teratogenicity surveillance systems that extend product development timelines and reshape distribution economics for oral formulations.
Growth Catalysts
- Medical aesthetic channel expansion:Dermatology clinics in the United States are scaling retinoid-based photodamage protocols, creating dedicated revenue streams for prescription-grade tretinoin and adapalene.
- iPLEDGE-equivalent risk management frameworks:Strengthened pregnancy prevention programs are legitimizing oral isotretinoin access for severe acne populations previously excluded from therapy.
- Encapsulation chemistry advances:Liposomal and solid-lipid nanoparticle delivery systems are stabilizing retinol in cosmetic formulations, extending shelf life and enabling higher active concentrations.
Market Restraints
- Isotretinoin API supply concentration:Three contract manufacturers in India control the majority of oral retinoid active pharmaceutical ingredient production, creating single-source vulnerability.
- REACH compliance costs for cosmetic-grade retinol:European manufacturers face escalating registration and safety dossier expenditures that compress margin structures on mass-market formulations.
- Teratogenicity litigation exposure:Product liability frameworks in the United States impose open-ended legal risk on oral retinoid prescribers and dispensers, constraining pharmacy participation.
Strategic Opportunities
- Compounding pharmacy channel development:Custom topical retinoid formulations with personalized vehicle bases are capturing patients with sensitivity to commercial excipients.
- Retinoid-benzoyl peroxide fixed-dose combinations:Synergistic acne therapies are securing abbreviated approval pathways under FDA 505(b)(2) regulations, compressing time-to-market versus novel entities.
- Veterinary dermatology applications:Companion animal practices are adopting adapalene for feline acne and canine seborrheic conditions, opening species-specific formulation demand.
Industry Challenges
- Stability testing protocol complexity:Retinoid oxidation kinetics require accelerated degradation studies under ICH Q1A guidelines that extend analytical development timelines.
- Cross-contamination control in multiproduct facilities:Vitamin A derivative potency necessitates dedicated manufacturing suites or complex cleanout validation, constraining capacity utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinoids Market |
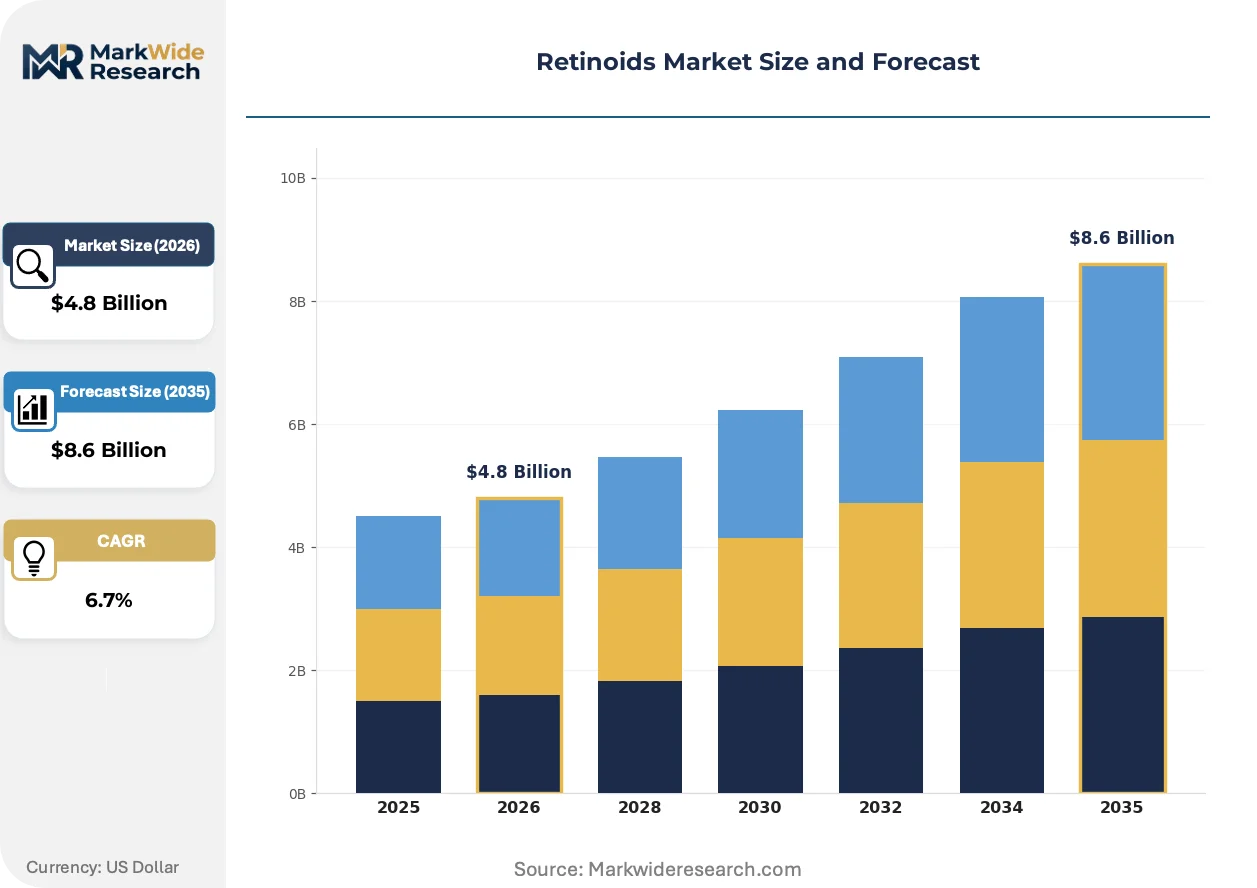
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Retinoids, Oral Retinoids, Combination Therapies, Injectables Indication: Acne, Psoriasis, Anti-Aging, Hyperpigmentation End User: Dermatology Clinics, Hospitals, Homecare, Spa Centers Formulation: Creams, Gels, Capsules, Solutions |
| Companies Covered | Galderma, Johnson & Johnson, Bayer, Bausch Health Companies, Mylan Pharmaceuticals, Sun Pharmaceutical Industries Ltd, GlaxoSmithKline, Valeant Pharmaceuticals, Janssen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinoids Market Evolving Landscape
Formulation science and regulatory stringency are converging to redefine product differentiation. Three developments are compressing competitive windows and reshaping value capture.
Microencapsulation technology is miniaturizing retinoid particle size to sub-micron dimensions, enabling dermal penetration without irritation. Cosmetic manufacturers in South Korea are integrating these systems into overnight repair serums. The technology is miniaturizing the effective dose threshold, allowing concentration claims that previously required prescription classification.
EMA pharmacovigilance framework updates are mandating real-world evidence collection for all topical retinoid products marketed in the European Union. Manufacturers must now fund post-authorization safety studies that track cutaneous adverse events across diverse phototypes. Mid-tier cosmetic brands lacking epidemiological infrastructure are withdrawing from the region rather than absorbing compliance costs.
Direct-to-clinic procurement is displacing wholesale distributor relationships for high-volume dermatology practices. Physician-owned dispensing models in Texas and Florida are capturing pharmacy margin through in-house retinoid fulfillment. This channel shift is most visible in cash-pay aesthetic segments where insurance adjudication friction is eliminated.
Retinoids Market Segmentation
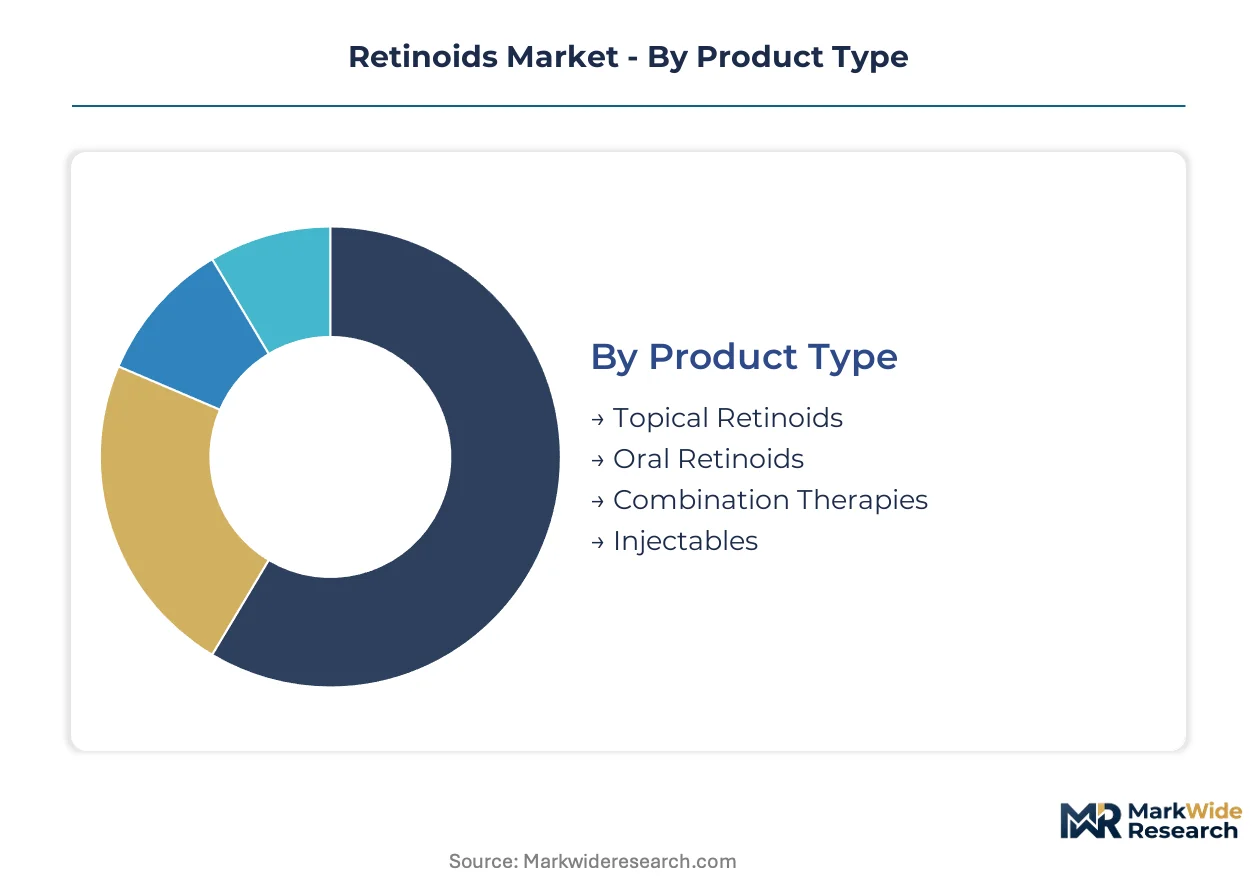
Retinoid product differentiation determines reimbursement pathways, prescribing authority, and competitive moats. Each segmentation dimension reveals distinct substitution pressures and margin architectures that shape portfolio strategy across pharmaceutical and cosmetic channels.
Product Type:
Topical retinoids face intensifying substitution pressure from peptide-based alternatives in cosmetic anti-aging, while oral formulations defend their position through teratogenicity protocols that create regulatory barriers to entry.
- Topical Retinoids:Cream, gel, and solution formulations containing tretinoin, adapalene, or tazarotene bind nuclear retinoic acid receptors to modulate epidermal turnover. Demand concentrates in United States dermatology clinics scaling photodamage protocols, though over-the-counter retinol serums erode prescription volume in mild indication segments.
- Oral Retinoids:Systemic isotretinoin and acitretin compounds deliver potent sebaceous suppression for severe nodular acne and generalized pustular psoriasis. iPLEDGE-equivalent risk management frameworks in the United States legitimize access while constraining dispensing pharmacy participation through liability exposure.
- Combination Therapies:Fixed-dose retinoid-benzoyl peroxide and retinoid-antibiotic pairings target resistant acne through synergistic mechanisms. FDA 505(b)(2) approval pathways compress development timelines versus novel entities.
- Injectables:Depot formulations and sustained-release retinoid delivery systems serve specialty protocols requiring precise pharmacokinetic control.
Topical retinoids anchor the volume base while combination therapies gain share at the steepest rate.
Indication:
Cost tier stratification separates premium-priced oral protocols from mass-market topical applications, with reimbursement intensity varying sharply across medical necessity designations.
- Acne:Vulgaris and nodulocystic presentations drive the largest prescription volume, spanning adolescent through adult demographic segments. Generic isotretinoin competition compresses oral therapy margins while topical adapalene maintains brand loyalty through tolerability differentiation.
- Psoriasis:Plaque and pustular variants require sustained systemic intervention, with acitretin serving as a standard-of-care anchor. Prior authorization requirements in United States commercial insurance constrain access velocity.
- Anti-Aging:Photoaging and fine line indications support cosmetic-grade retinol at concentration thresholds below prescription classification. Encapsulation chemistry advances enable stability claims that justify premium positioning.
- Hyperpigmentation:Melasma and post-inflammatory hyperpigmentation protocols combine retinoids with tyrosinase inhibitors, capturing demand in Asia-Pacific and Latin American markets with higher melanin density populations.
Acne indications anchor the volume base while anti-aging applications expand most quickly through aesthetic channel penetration.
End User:
Customer type determines procurement modality, with institutional purchasers negotiating formularies while direct-to-consumer channels capture margin through bypassing distributor layers.
- Dermatology Clinics:Physician-owned dispensing models in Texas and Florida capture pharmacy margin through in-house retinoid fulfillment, eliminating insurance adjudication friction in cash-pay aesthetic segments.
- Hospitals:Inpatient and emergency department protocols for severe drug reactions and pregnancy screening requirements concentrate oral retinoid administration in controlled settings.
- Homecare:Patient-administered topical regimens dominate maintenance therapy, with telemedicine platforms expanding prescription access beyond traditional clinic geography.
- Spa Centers:Medical aesthetic practices in the United States integrate prescription-grade tretinoin into bundled photodamage protocols, creating dedicated revenue streams distinct from retail cosmetic channels.
Dermatology clinics anchor the volume base while spa centers climb the fastest through aesthetic service bundling.
Formulation:
Supply concentration in API manufacturing shapes formulation economics, with three Indian contract manufacturers controlling oral retinoid active pharmaceutical ingredient production.
- Creams:Emulsion-based vehicles deliver sustained release with reduced irritation profiles, preferred for sensitive skin and initial tolerance building.
- Gels:Alcohol-based matrices enhance penetration for oily and acne-prone skin types, with adapalene gel establishing the benchmark for tolerability.
- Capsules:Oral isotretinoin and acitretin require lipid-rich absorption environments, with soft-gel and liquid-filled hard capsule formats competing on bioavailability claims.
- Solutions:Liquid formulations enable scalp and large-surface-area applications for psoriasis and seborrheic conditions.
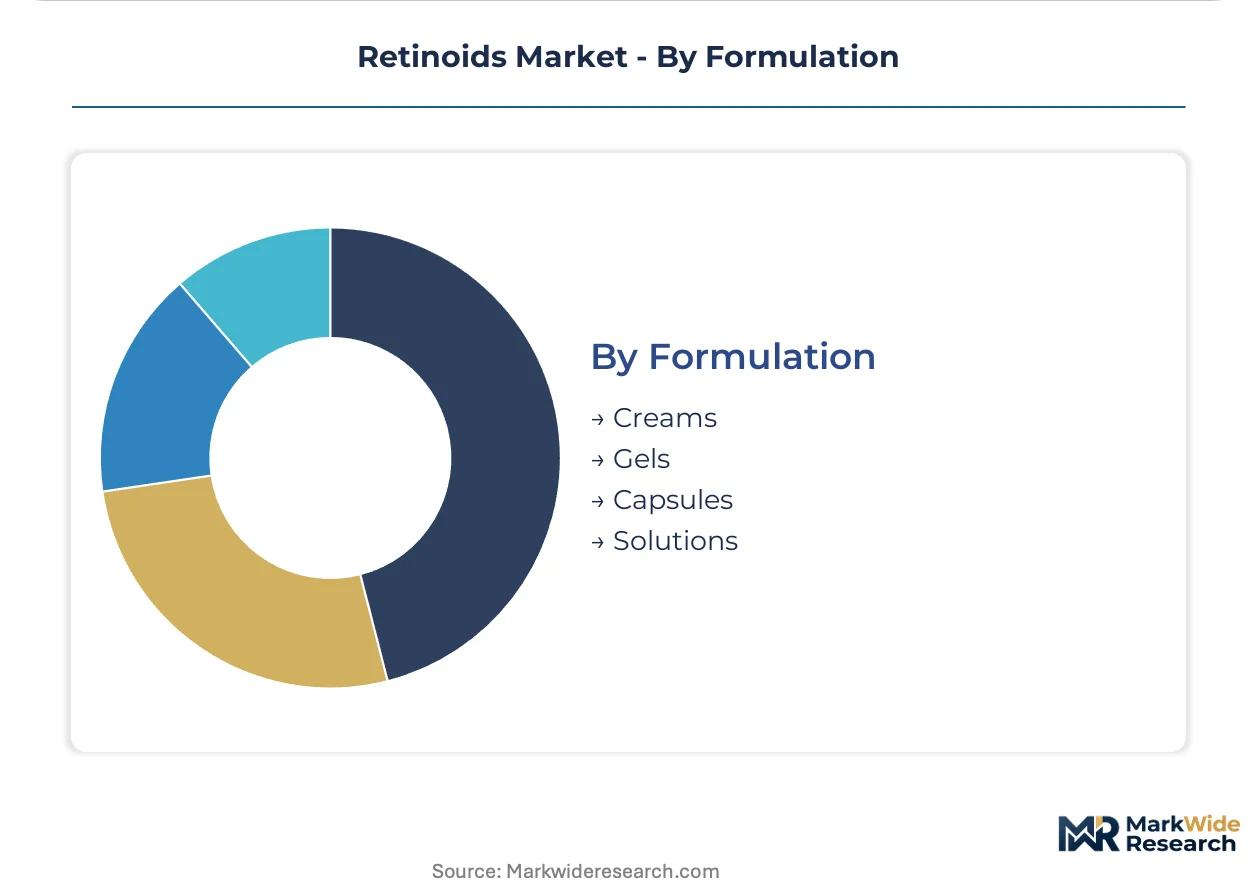
Creams anchor the volume base while gels gain share at the steepest rate through acne indication preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three Indian contract manufacturers control the majority of oral retinoid active pharmaceutical ingredient production, creating geographic concentration at the supply base. Demand clusters in the United States, Germany, and Japan where dermatology infrastructure and reimbursement pathways support prescription-grade protocols. Regulatory fragmentation across FDA, EMA, and national Asian regulators shapes divergent market access timelines.
United States
Medical aesthetic practices in Texas and Florida scale physician-owned dispensing models for prescription-grade tretinoin, capturing pharmacy margin through in-house fulfillment. FDA iPLEDGE-equivalent risk management frameworks legitimize oral isotretinoin access while constraining dispensing participation through liability exposure. The Dallas-Houston corridor anchors dermatology clinic density for cash-pay photodamage protocols.
Germany
EMA pharmacovigilance mandates fund post-authorization safety studies tracking cutaneous adverse events across diverse phototypes. REACH compliance costs for cosmetic-grade retinol compress margin structures on mass-market formulations. The Rhine-Ruhr industrial cluster hosts formulation science capabilities serving encapsulation chemistry advances for stability claims.
India
Contract manufacturers in Hyderabad and Mumbai supply oral retinoid API to global pharmaceutical markets, creating single-source vulnerability for isotretinoin production. CDSCO bioequivalence protocols align with ICH guidelines for generic formulation approvals. The Telangana-Andhra Pradesh pharmaceutical belt concentrates GMP-certified capacity for vitamin A derivative synthesis.
Japan
PMDA maintains stringent teratogenicity evaluation protocols for all retinoid drug applications, extending product development timelines versus Western regulators. METI industrial policy supports microencapsulation technology transfer from cosmetic to pharmaceutical applications. The Kansai region anchors dermal delivery research infrastructure for sub-micron particle formulation.
United Kingdom
MHRA post-Brexit regulatory autonomy permits divergence from EMA pharmacovigilance frameworks for topical retinoid surveillance. The London-Southeast corridor concentrates medical aesthetic clinic networks prescribing bundled photodamage protocols. NHS prior authorization requirements constrain oral retinoid access velocity for severe acne populations.
Retinoids Market Competitive Landscape
Concentration sits with prescription dermatology specialists controlling vertical integration in adapalene and tazarotene supply chains. The market structures around three tiers: multinational pharmaceutical conglomerates with consumer health divisions, pure-play dermatology companies with captive manufacturing, and generic API suppliers serving formulation partners. Strategic moves center on M&A for dermatology portfolio expansion and encapsulation technology licensing for cosmetic-grade stability claims.
Within the integrated pharmaceutical tier, Galderma and Bayer exemplify divergent positioning—Galderma occupying the pure-play dermatology archetype with prescription-focused portfolios, while Bayer anchors oral retinoid compounds through its pharmaceutical division. Johnson & Johnson represents the conglomerate archetype, bridging consumer-facing retinol and clinical validation infrastructure.
| Leading Market Players |
|---|
| Galderma |
| Johnson & Johnson |
| Bayer |
| Bausch Health Companies |
| Mylan Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd |
| GlaxoSmithKline |
| Valeant Pharmaceuticals |
| Janssen Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
FDA iPLEDGE-equivalent risk management frameworks gate both supply qualification and price differentiation simultaneously, as teratogenicity compliance costs create tiered entry barriers that separate prescription-grade oral formulations from cosmetic-grade retinol alternatives. Three Indian contract manufacturers control oral isotretinoin API production, concentrating upstream leverage while downstream dermatology clinics in Texas and Florida capture margin through physician-owned dispensing models.
Pricing Analysis
FDA teratogenicity protocols dictate the pricing tier structure across the retinoids market, with oral isotretinoin commanding premium positioning due to iPLEDGE-equivalent compliance burdens while topical adapalene competes on tolerability differentiation. Three-tier pricing structure across premium prescription oral, standard topical prescription, and economy cosmetic retinol levels reflects certification grade and distribution channel control. Cost compression in mass-market cosmetic retinol intensifies because REACH compliance expenditures in Europe force mid-tier brand withdrawals. Hospital and institutional buyers exhibit highest price sensitivity through formulary negotiation, while cash-pay aesthetic clinics demonstrate lowest sensitivity due to bundled service positioning.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for retinoid API shipments from Indian manufacturing clusters to European formulation facilities. API production concentrates in India, China, and Germany, with Hyderabad and Mumbai contract manufacturers supplying global pharmaceutical markets. Formulation science depends on beta-ionone ring precursors and conjugated polyene side chain intermediates sourced from specialty chemical producers. Single-source vulnerability in oral isotretinoin API creates structural risk from regulatory inspection disruptions. Distribution runs through wholesale pharmaceutical distributors for institutional channels, while direct-to-clinic procurement displaces traditional relationships in high-volume dermatology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation chemistry expertise and teratogenicity risk management infrastructure represent scarce capabilities that constrain competitive entry, as liposomal delivery system development and iPLEDGE-equivalent program administration require specialized assets unavailable to generalist manufacturers.
For Market Incumbents: Consolidate backward integration into adapalene and tazarotene API supply through captive manufacturing or exclusive offtake agreements with Hyderabad-based contract manufacturers. Expand capacity in Texas and Florida physician-owned dispensing corridors to defend margin position against wholesale distributor disintermediation. Prioritize microencapsulation technology licensing to cosmetic partners seeking stability claims that justify premium positioning.
For New Entrants and Emerging Players: Lead with veterinary dermatology applications for feline acne and canine seborrheic conditions, where adapalene demand remains underserved by incumbent portfolios focused on human indications. Target compounding pharmacy channels with personalized vehicle base formulations for patients exhibiting sensitivity to commercial excipients. Pursue telemedicine platform partnerships as the go-to-market angle for patient-administered topical maintenance therapy beyond traditional clinic geography.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation technology development as sub-micron particle formulation requires specialized equipment and analytical infrastructure. Acquisition target archetype: pure-play dermatology companies with captive manufacturing and established iPLEDGE-equivalent program administration capabilities. Watch EMA pharmacovigilance framework enforcement intensity as the inflection indicator for European market access cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | South Korean cosmetic manufacturers integrate sub-micron systems into overnight repair serums, extending shelf life claims. |
| Physician-Owned Dispensing Expansion | Texas and Florida dermatology clinics capture pharmacy margin through in-house tretinoin fulfillment, eliminating insurance friction. |
| Retinoid-Benzoyl Peroxide Fixed-Dose Development | FDA 505(b)(2) pathways compress approval timelines versus novel entities for resistant acne combination therapies. |
| Veterinary Formulation Extension | Companion animal practices adopt adapalene for feline acne, opening species-specific demand outside human dermatology saturation. |
| Compounding Pharmacy Channel Development | Custom topical formulations with personalized vehicle bases capture patients with commercial excipient sensitivity. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dermatology clinic operators, pharmaceutical regulatory affairs leads, formulary directors at United States commercial insurers, and compounding pharmacy owners; and secondary validation through FDA iPLEDGE program documentation, EMA pharmacovigilance framework updates, CDSCO bioequivalence filings, and REACH registration dossiers. Bottom-up triangulation across prescription volume data, API production capacity assessments, and dermatology clinic density metrics reconciled with top-down market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation across topical, oral, combination, and injectable formulations; indication segmentation spanning acne, psoriasis, anti-aging, and hyperpigmentation; and end-user segmentation capturing dermatology clinics, hospitals, homecare, and spa centers. CAGRs derived from regression analysis of historical prescription trends, reimbursement pathway evolution, and aesthetic channel penetration rates incorporated encapsulation chemistry adoption curves and teratogenicity protocol compliance cost trajectories.
Forecasts assume regulatory continuity in FDA iPLEDGE-equivalent frameworks and EMA pharmacovigilance mandates; material policy shifts in teratogenicity risk evaluation protocols or REACH cosmetic-grade concentration limits would require re-modeling. Forecasts reflect assumptions regarding API supply stability from Indian contract manufacturers and dermatology clinic dispensing model expansion velocity. Recalibration cycles align with material shifts in regulatory enforcement intensity, encapsulation technology commercialization timelines, and veterinary dermatology protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Asia-Pacific Skincare Market
Skincare
Medicine Skin Care Market
Skincare
Ampoule Cream Market
Skincare
Professional Skin Care Market
Skincare
Retinol Skincare Product Market
Skincare
Exfoliators and Scrubs Market
Skincare
India Skin Care Products Market
Skincare
After Sun Care Products Market
Skincare
Skin Barrier Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Skin Toner Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Biological Skin Substitutes Market
Skincare
Dermocosmetics Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Mineral Sunscreen Market