
 Skincare Ingredients Market | 2026-2036
Skincare Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Skincare Ingredients Market Analysis
Modular active-ingredient kits is rebalancing how cosmetic brands procure and consumers evaluate skincare efficacy. BASF SE leverages its integrated biotechnology platform to supply peptide and ceramide precursors at manufacturing scale. Croda International Plc anchors its position through lipid chemistry specialization across emollient and surfactant categories. Evonik Industries AG competes via silane and biotech-derived active delivery systems that improve skin penetration.
Skincare ingredients comprise functionally active and inactive chemical substances formulated at specified concentrations, typically ranging from trace actives below one percent to base materials exceeding fifty percent, designed to deliver moisturizing, anti-aging, or cleansing performance in topical applications. Emollients and humectants occupy the largest volume share due to their ubiquity across cream and serum formulations, while bio-derived sources represent the fastest-expanding procurement category as brands reformulate to meet clean-label expectations. Anti-aging functionality commands premium pricing power, though anti-acne segments gain traction among younger demographics seeking retinoid and acid-based treatments.
REACH in Europe and FDA cosmetic labeling requirements in the United States both tighten disclosure obligations and restrict certain preservative chemistries, compelling suppliers to validate alternative stabilization pathways. BIS standards in India and China's GB standards for cosmetics further fragment compliance requirements across manufacturing locations. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and raw material qualification timelines.
Market Dynamics
Prestige beauty brands now compress multi-step routines into single-step formulations, forcing ingredient suppliers to engineer compatible active complexes that maintain stability at combined concentrations rather than discrete applications.
Growth Catalysts
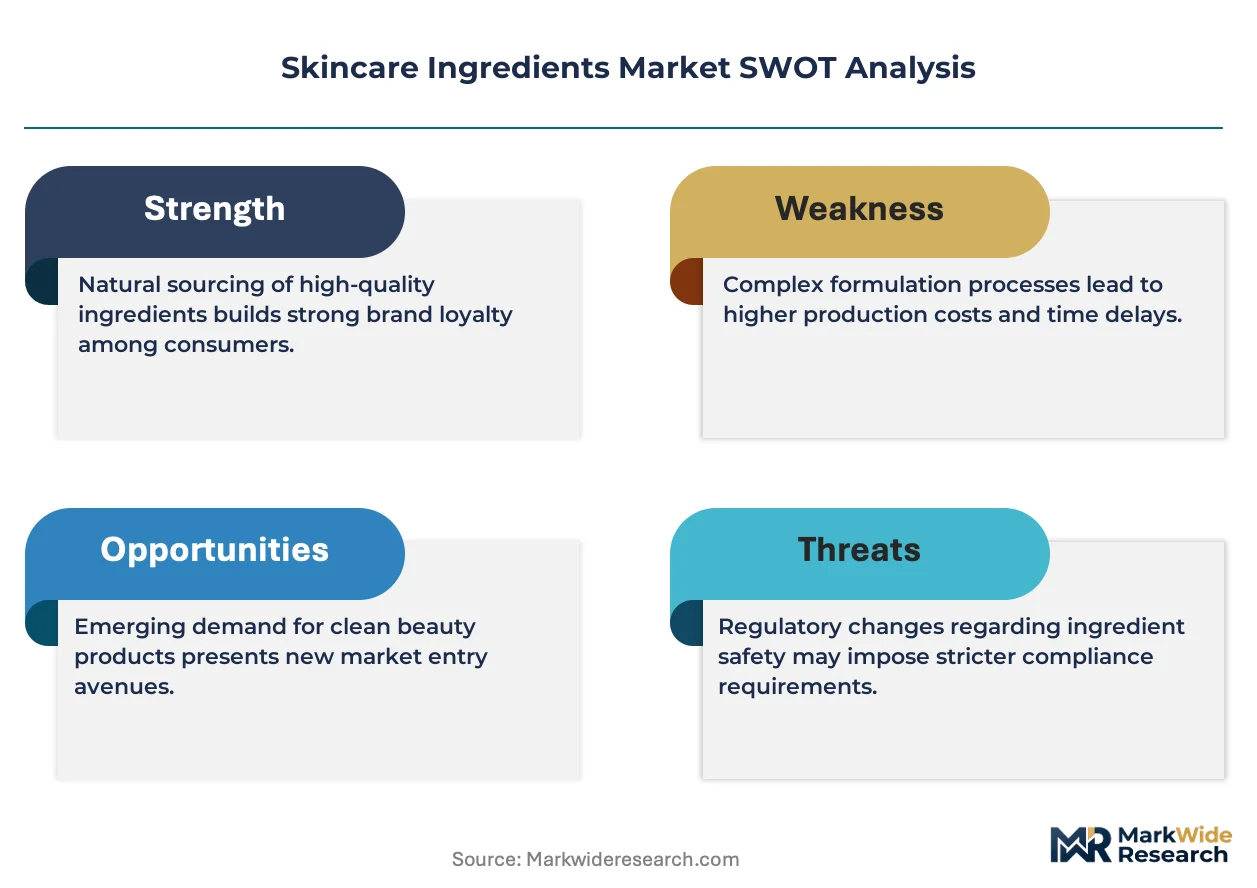
- EU REACH Regulation:Tightened scrutiny on synthetic preservatives accelerates bio-derived alternative development, creating procurement advantages for suppliers with fermentation-derived stabilization platforms.
- K-Beauty Export Infrastructure:South Korea's domestic R&D pipeline and global distribution networks anchor ingredient innovation cycles, pulling adjacent Asian markets into aligned formulation standards.
- Peptide Synthesis Biotechnology:Advances in solid-phase and recombinant production methods reduce unit costs for anti-aging actives, expanding addressable volume in mass-market serum categories.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic emollient and surfactant precursors face input cost swings tied to crude oil derivatives, compressing margin predictability for commodity-grade suppliers.
- Concentrated Preservative Supply:Three chemical manufacturers dominate paraben and phenoxyethanol production, creating single-source vulnerability for formulators awaiting bio-alternative qualification.
- Skin Penetration Ceiling:Stratum corneum barrier properties limit molecular weight thresholds for active delivery, constraining efficacy claims for larger peptide structures without encapsulation systems.
Strategic Opportunities
- India BIS Cosmetic Standards:Formaldehyde-releaser restrictions and heavy metal testing mandates create first-mover advantage for pre-qualified clean-label suppliers entering domestic manufacturing partnerships.
- Microbiome-Friendly Positioning:Preservative-free and biotic-inclusive claims open premium positioning in sensitive-skin segments previously dominated by dermatological pharmacy brands.
- Direct-to-Consumer Sampling Integration:Ingredient suppliers partner with subscription box platforms to embed trace-actives in trial formats, bypassing traditional brand gatekeeper relationships.
Industry Challenges
- Fermentation Scale-Up Expertise:Bio-derived active production requires specialized bioprocess engineering talent scarce outside pharmaceutical and enzyme manufacturing sectors.
- Cross-Jurisdictional Registration Timelines:New ingredient notifications under FDA, REACH, and China's NMPA run asynchronously, delaying coordinated product launches by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skincare Ingredients Market |
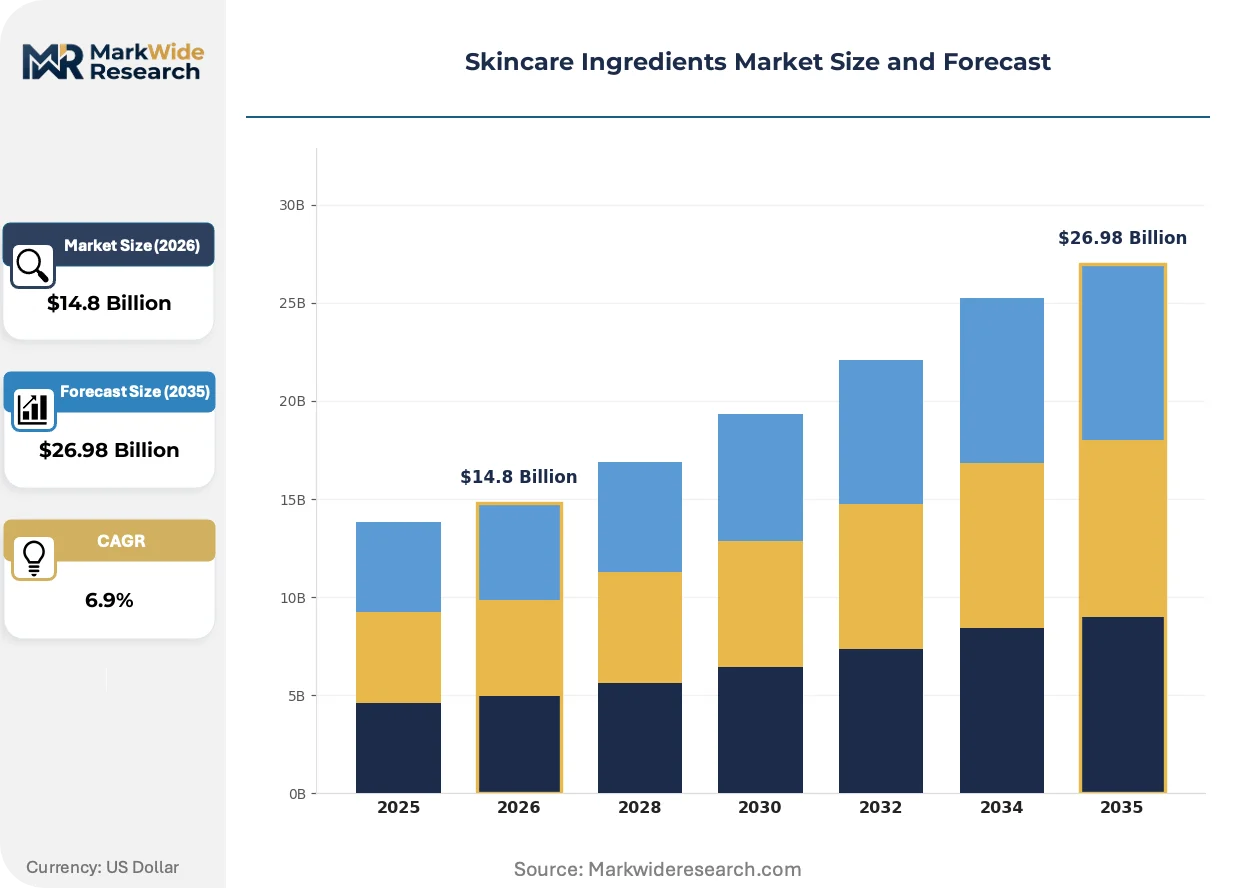
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Emollients, Humectants, Surfactants, Exfoliants Source: Natural, Synthetic, Bio-derived, Organic Functionality: Moisturizing, Anti-aging, Brightening, Anti-acne Form: Creams, Serums, Gels, Oils |
| Companies Covered | BASF SE, Evonik Industries AG, Croda International Plc, Clariant, Symrise, DSM, Wacker Chemie AG, Ashland Global Holdings Inc., Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skincare Ingredients Market Emerging Trajectories
Biotechnology-derived actives and delivery systems are compressing the traditional boundaries between pharmaceutical-grade efficacy and cosmetic accessibility, while regulatory disclosure mandates force transparency through the supply chain.
Encapsulation technology using lipid nanoparticles and cyclodextrin complexes is expanding into high-potency retinoid and acid formulations previously limited by irritation profiles. Mid-tier beauty brands adopt these systems at accelerating rates to compete with prestige positioning. The structural consequence is compression of the efficacy gap between professional and retail channels, forcing ingredient suppliers to differentiate on sustained-release performance metrics rather than concentration claims alone.
REACH authorization requirements for endocrine-disrupting preservative candidates tighten substitution timelines across European manufacturing. Formulators face reformulation costs for existing stock-keeping units containing restricted chemistries. Fragrance-free and preservation-system-minimal segments absorb the highest compliance burden, pivoting toward hurdle technology and packaging-intrinsic protection methods.
Ingredient traceability demands from Sephora and Ulta Beauty's clean certification programs reshape supplier qualification protocols. Raw material vendors now submit full supply chain documentation through blockchain-verified platforms to maintain retail channel access. North American indie beauty brands drive this behavioral shift fastest, using transparent sourcing as primary competitive differentiation against established conglomerate portfolios.
Skincare Ingredients Market Segmentation
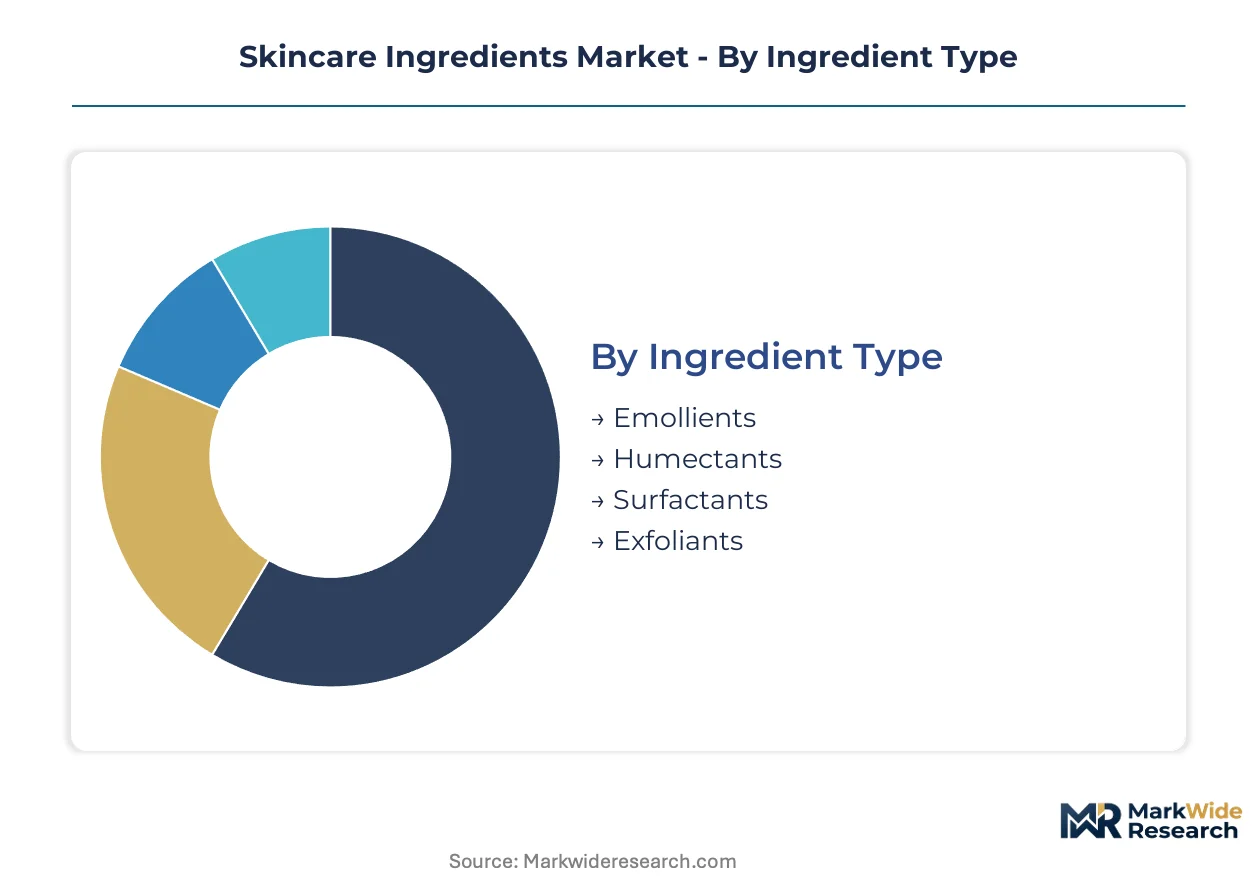
Ingredient classification determines procurement strategy, formulation compatibility, and regulatory qualification pathways for skincare manufacturers. Suppliers align R&D investments with segment-specific performance thresholds and stability requirements. Brand positioning across mass, prestige, and clinical channels maps directly to ingredient tier selection.
Ingredient Type:
Supply concentration clusters around emollient and humectant production, where petrochemical and oleochemical feedstock integration creates scale advantages for integrated suppliers.
- Emollients:Lipid-based compounds including esters, fatty alcohols, and silicones that restore skin barrier function and provide sensory texture. Demand concentrates in cream and lotion formulations across North American prestige brands seeking clean-label alternatives to petrolatum-derived options.
- Humectants:Hygroscopic molecules—glycerin, hyaluronic acid, sorbitol—that bind atmospheric moisture to stratum corneum. South Korean manufacturers drive volume for multi-molecular-weight hyaluronic acid complexes in essence and toner applications, pulled by K-beauty export momentum.
- Surfactants:Amphiphilic compounds enabling emulsification and cleansing action in rinse-off products.
- Exfoliants:Alpha-hydroxy acids, beta-hydroxy acids, and enzymatic agents accelerating cell turnover.
Today's leader: Emollients. Tomorrow's challenger: Exfoliants.
Source:
Cost tier differentiation separates fermentation-derived bio-actives from commodity petrochemicals, with organic-certified inputs commanding premium positioning in Sephora and Ulta clean beauty programs.
- Natural:Plant-extracted oils, butters, and waxes harvested from agricultural supply chains. European formulators under REACH pressure accelerate substitution toward shea butter and jojoba oil as paraben replacements.
- Synthetic:Petrochemically synthesized molecules including mineral oil, silicones, and carbomers. Indian contract manufacturers rely on synthetic emollients for mass-market export production to Middle Eastern markets.
- Bio-derived:Fermentation-produced actives—squalane from sugarcane, ceramides from yeast—combining biotechnology scalability with renewable feedstocks.
- Organic:Certified organic ingredients meeting USDA or ECOCERT standards with full traceability documentation.
Natural sources dominate current procurement volumes. Bio-derived alternatives are climbing the fastest as biotechnology platforms achieve cost parity.
Functionality:
Application-specific efficacy requirements drive concentration thresholds and encapsulation technology adoption, with anti-aging commands justifying premium active loading.
- Moisturizing:Barrier repair and transepidermal water loss reduction through occlusive and humectant synergy. Mass-market body care in Brazil absorbs the highest moisturizing ingredient volumes, pulled by year-round tropical climate conditions.
- Anti-aging:Collagen stimulation, antioxidant defense, and wrinkle reduction through retinoids, peptides, and vitamin C derivatives. Japanese consumers over 50 represent concentrated demand for high-potency retinoid formulations with sustained-release encapsulation.
- Brightening:Melanin inhibition and tone-evening through niacinamide, arbutin, and vitamin C complexes.
- Anti-acne:Sebum regulation and bacterial control via salicylic acid, benzoyl peroxide, and tea tree oil.
Anti-aging functionality captures premium pricing. Anti-acne segments are gaining share fastest among Gen Z demographics seeking acid-based treatments.
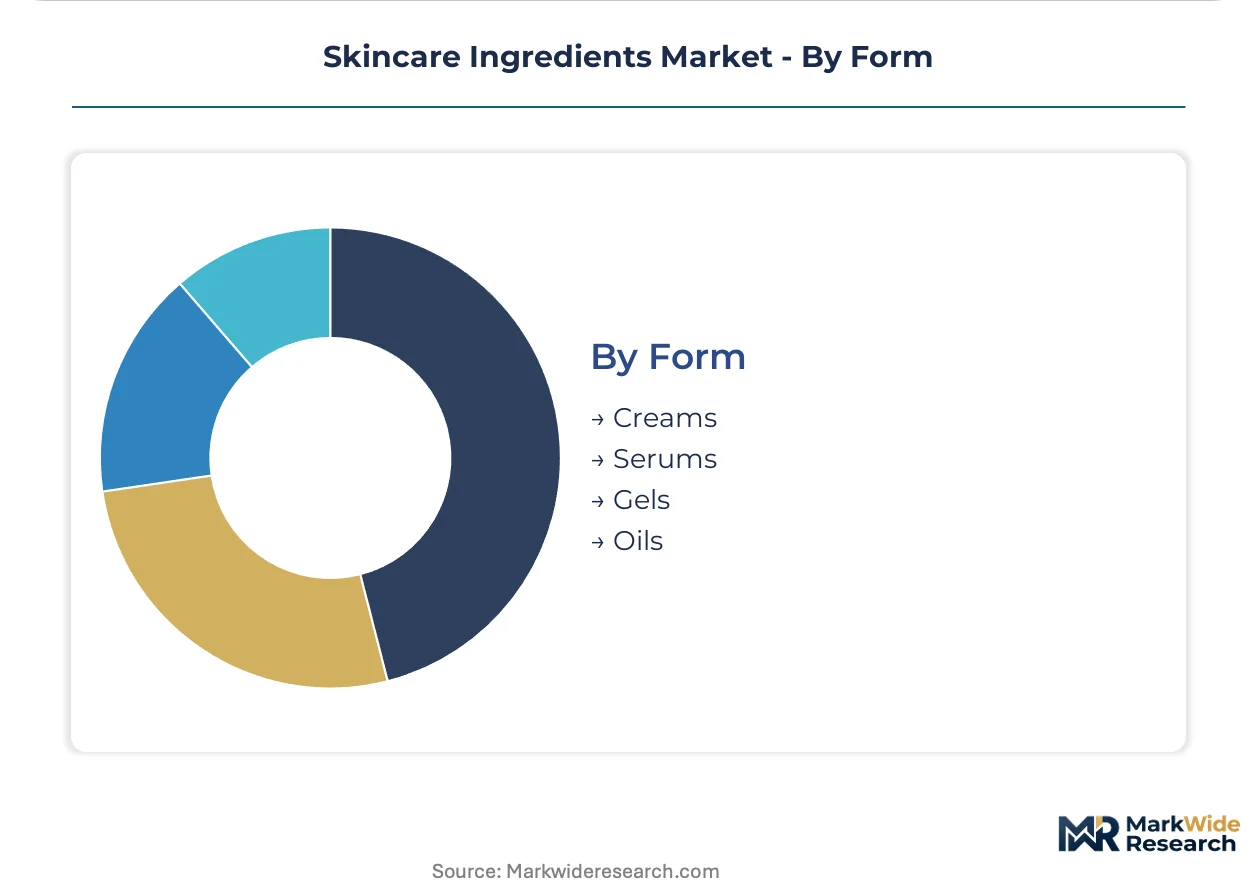
Form:
Customer type segmentation separates professional channel concentrates from retail-ready dilutions, with serum formats justifying highest active loading and price per milliliter.
- Creams:Oil-in-water or water-in-oil emulsions delivering sustained occlusion for dry and mature skin. German pharmacy brands lead European demand for urea-based therapeutic creams targeting atopic dermatitis.
- Serums:Low-viscosity, high-active-concentration fluids designed for targeted treatment prior to moisturization. Chinese direct-to-consumer brands drive serum volume through live-streaming commerce, emphasizing visible efficacy timelines.
- Gels:Water-based, non-comedogenic vehicles preferred for oily and acne-prone skin types.
- Oils:Anhydrous lipid formulations providing intensive nourishment and massage application.
Serums command the steepest expansion trajectory in prestige and masstige channels. Creams remain the volume anchor across mass retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France pioneered modern cosmetic chemistry through Grasse fragrance extraction and Parisian formulation laboratories, establishing supply chain templates that German and Swiss ingredient houses later industrialized at manufacturing scale.
South Korea
Seoul-based R&D clusters drive multi-molecular-weight hyaluronic acid innovation for essence and toner exports. MFDS cosmetic safety standards accelerate clean-label qualification timelines for domestic suppliers. The Gyeonggi-do biotech corridor houses fermentation facilities supplying ceramide precursors to K-beauty brands expanding into Southeast Asian markets.
United States
FDA cosmetic labeling requirements and clean beauty certification programs at Sephora and Ulta Beauty pull ingredient traceability investments from raw material vendors. Indie brands in Los Angeles and Brooklyn prioritize transparent sourcing as competitive differentiation against conglomerate portfolios. New Jersey chemical manufacturing infrastructure supports surfactant and emollient production for North American contract manufacturers.
Germany
REACH authorization timelines for endocrine-disrupting preservatives compress substitution schedules for formulators serving European manufacturing. BASF SE's Ludwigshafen integrated biotechnology platform supplies peptide precursors at industrial fermentation scale. The Düsseldorf-Ruhr industrial corridor concentrates oleochemical processing for clean-label emollient alternatives to petrolatum derivatives.
China
NMPA cosmetic ingredient notification requirements and GB standards fragment compliance timelines for multinational suppliers launching coordinated product releases. Live-streaming commerce platforms in Hangzhou and Guangzhou drive serum volume through direct-to-consumer brands emphasizing visible efficacy timelines. Yangtze River Delta chemical parks house fermentation capacity for bio-derived squalane production from sugarcane feedstocks.
India
BIS cosmetic standards restricting formaldehyde-releasers and mandating heavy metal testing create first-mover advantage for pre-qualified clean-label suppliers. Mumbai and Ahmedabad contract manufacturers absorb high volumes of synthetic emollients for mass-market export production to Middle Eastern markets. Maharashtra's chemical infrastructure supports backward integration into surfactant precursors for domestic formulation houses.
Skincare Ingredients Market Vendor Landscape
Premium-margin players sit above commodity-margin players across biotechnology specialization and regulatory qualification depth, with consolidated supply concentration in peptide synthesis and preservative alternatives coexisting with fragmented emollient commodity supply. Three archetypes dominate: integrated chemical conglomerates with fermentation platforms, lipid chemistry specialists with oleochemical integration, and biotech-focused active delivery system innovators. Competitive moves center on backward integration into renewable feedstock supply and strategic partnerships with direct-to-consumer sampling platforms bypassing traditional brand gatekeepers.
Among integrated chemical conglomerates, BASF SE anchors the biotechnology-derived actives tier through industrial-scale peptide and ceramide precursor supply, while Evonik Industries AG occupies a position within the specialty silane and delivery system segment. Croda International Plc exemplifies the lipid chemistry specialist archetype with emollient and surfactant category concentration. These three entities represent distinct capability vectors—fermentation scale, functional silane chemistry, and oleochemical processing—that define competitive positioning across clean-label and performance-driven formulation demand.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Croda International Plc |
| Clariant |
| Symrise |
| DSM |
| Wacker Chemie AG |
| Ashland Global Holdings Inc. |
| Lonza |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility cascades through synthetic emollient production into three distinct pricing tiers, with fermentation-derived bio-actives commanding premium positioning against commodity-grade petrolatum alternatives. REACH-driven preservative substitution costs concentrate in European manufacturing, forcing formulators to absorb qualification expenses or pass through to clean-label positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates biotechnology-derived actives from oleochemical intermediates and commodity petrochemicals. Price differentiation hinges on certification tier—ECOCERT and USDA organic standards justify 40-60% uplifts—and volume scale, with bulk pharmaceutical-grade peptide contracts compressing unit costs for mass-market serum brands. Pricing pressure stems from crude oil derivative swings eroding synthetic emollient margins, particularly for Indian contract manufacturers serving Middle Eastern export markets. Mass-market body care in Brazil exhibits highest price sensitivity, while Japanese prestige brands over 50 show least elasticity for encapsulated retinoid complexes.
Supply Chain Analysis
Dual-sourcing requirements from Sephora and Ulta Beauty's clean certification programs mandate multi-supplier qualification for raw material vendors seeking North American retail access. Supply concentrates in South Korea for multi-molecular-weight hyaluronic acid, Germany for peptide fermentation platforms, and China for sugarcane-derived squalane production. Raw material dependencies center on oleochemical feedstocks from Malaysian palm and Brazilian soybean supply chains, plus sugarcane biomass for biotechnology platforms. Single-source vulnerability concentrates in paraben and phenoxyethanol production, where three chemical manufacturers dominate global output. Distribution runs through integrated chemical conglomerates with captive fermentation capacity, bypassing traditional merchant trading layers for high-value actives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skincare ingredients market compounds steadily as clean-label reformulation mandates across REACH, FDA, and China's NMPA create durable procurement demand for bio-derived alternatives. Regulatory divergence between jurisdictions extends qualification timelines, embedding supplier switching costs that protect incumbent positions.
For Market Incumbents: Anchor position through backward integration into renewable feedstock supply—BASF SE's Ludwigshafen biotechnology platform exemplifies this model—while accelerating fermentation scale-up expertise acquisition from pharmaceutical sectors. Defend against emerging biotech-focused active delivery innovators by locking long-term offtake agreements with K-beauty brands expanding into Southeast Asian markets. Prioritize certification investment in India's BIS pre-qualification to capture first-mover advantage as formaldehyde-releaser restrictions tighten.
For New Entrants and Emerging Players: Launch via direct-to-consumer sampling integration with subscription box platforms, embedding trace-actives in trial formats that bypass traditional brand gatekeeper relationships. Target microbiome-friendly positioning in sensitive-skin segments previously dominated by dermatological pharmacy brands, where preservative-free claims command premium pricing. Penetrate India's domestic manufacturing partnerships fastest, as BIS cosmetic standards create qualification barriers that favor pre-certified clean-label suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up expertise concentrates outside cosmetic ingredient supply, in pharmaceutical and enzyme manufacturing sectors with transferable bioprocess engineering talent. Long-term viability favors integrated platforms combining biotechnology-derived actives with lipid chemistry specialization, spanning Croda's oleochemical integration through BASF's fermentation scale. Watch for inflection where cross-jurisdictional registration timelines compress from 18-36 months toward synchronized approval pathways, signaling regulatory harmonization that accelerates coordinated product launches.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | BASF SE's sugarcane-derived squalane platform eliminates oleochemical price volatility exposure. |
| Fermentation Scale-Up Capacity Expansion | Gyeonggi-do biotech corridor facilities supply ceramide precursors to K-beauty export channels. |
| Clean Certification Pre-Qualification | ECOCERT and USDA organic documentation unlocks Sephora and Ulta Beauty retail access. |
| Direct-to-Consumer Sampling Partnerships | Ingredient suppliers embed trace-actives in subscription boxes, bypassing brand procurement gatekeepers. |
| Microbiome-Friendly Formulation Development | Preservative-free positioning captures premium margins in sensitive-skin segments. |
Methodological Framework
Coverage spans South Korea, Germany, China, India, and the United States, with primary inputs from each market's regulatory and manufacturing clusters. The approach combines structured interviews with cosmetic formulators, biotechnology R&D directors, regulatory affairs specialists at ingredient suppliers, and procurement leads at prestige beauty brands, validated against secondary sources including ECHA REACH authorization databases, FDA cosmetic labeling guidance, NMPA ingredient notification filings, and BIS cosmetic standards documentation. Bottom-up volume modeling from fermentation capacity and oleochemical processing throughput triangulates against top-down demand estimates from K-beauty export statistics and North American retail audit data.
Granularity-level modeling operates at ingredient type, source origin, functionality claim, and formulation form dimensions, with regional regulatory cluster differentiation for REACH, FDA, NMPA, BIS, and MFDS compliance pathways. CAGRs derive from segmented growth rate assumptions applied across the projection horizon, with biotechnology-derived actives and anti-aging functionality receiving distinct elasticity coefficients. Industry-specific inputs include peptide synthesis cost curves from solid-phase and recombinant production methods, plus encapsulation technology adoption rates for retinoid and acid formulations.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock price shocks, accelerated REACH authorization withdrawals beyond current endocrine-disrupting candidate lists, and geopolitical disruptions to South Korean-Chinese ingredient trade flows. Forecasts assume sustained K-beauty export momentum and stable fermentation scale-up learning curves. Deviation in cross-jurisdictional regulatory harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
India Skin Care Products Market
Skincare
Vitamin C Serum Market
Skincare
Algae Skincare Products Market
Skincare
Global Skin Rejuvenation Market
Skincare
Skincare Serums Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Europe Functional Cosmetics Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Facial Mist Market
Skincare
Biological Skin Substitutes Market
Skincare
Retinoids Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Self-Tanning Care Market
Skincare
Skin Bioactive Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Global Skin Tears Treatment Market