
 Cosmeceutical Ingredients Market | 2026-2036
Cosmeceutical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmeceutical Ingredients Market Analysis
Pharmaceutical-grade purity specifications is reorganizing procurement priorities across cosmeceutical ingredient supply chains. BASF SE leverages its integrated biotechnology platforms to control peptide synthesis quality from fermentation through finished active delivery. Croda International Plc anchors its position through lipid and surfactant specialization that underpins next-generation serum penetration systems. Evonik Industries AG dominates high-potency active encapsulation, extending its Silica and formulation technology leadership into medical-aesthetic crossover applications.
Cosmeceutical ingredients comprise biologically active compounds formulated at concentrations sufficient to exert measurable physiological effects on skin or hair, typically requiring stability thresholds below 0.1% degradation over twelve months and validated dermal penetration rates. Their primary commercial purpose centers on bridging cosmetic elegance with therapeutic outcomes for topical delivery systems. Peptides and antioxidants command premium positioning due to clinical substantiation requirements and complex synthesis pathways that limit supplier pools. Botanical extracts occupy a mature, volume-driven tier where traceability certifications from cultivation through extraction now determine contract eligibility. Serums and creams as formulation types concentrate margin pools where encapsulation technology and time-release architecture differentiate finished goods.
FDA oversight of cosmeceutical claims through its cosmetic-drug distinction shapes how manufacturers position active concentrations and efficacy language in US markets. REACH registration and the EU's MDR framework impose full toxicological dossiers on peptide and antioxidant suppliers seeking European market access. ISO 16128 natural origin standards increasingly filter botanical ingredient procurement specifications across formulation houses. Stakeholders must monitor how regulatory divergence between FDA cosmetic modernization proposals and EU chemical strategy sustainability requirements fragments compliance investment across regional supply strategies.
Market Dynamics
Pharmaceutical-grade purity thresholds are compressing supplier pools across peptide and antioxidant synthesis chains, forcing ingredient houses to reconfigure fermentation and encapsulation infrastructure around stability validation protocols.
Growth Catalysts
- EU MDR toxicological dossier requirements:REACH registration mandates for peptide suppliers entering European markets are filtering out subscale producers and concentrating contract awards among validated manufacturers.
- Seoul-Gyeonggi contract manufacturing cluster:South Korea's corridor supplies both domestic brands and global beauty houses, creating knowledge spillovers that accelerate formulation innovation cycles.
- Antioxidant clinical substantiation:Dermatology clinics in Tokyo and New York are expanding professional-grade treatment menus, pulling pharmaceutical-grade actives into aesthetic protocols.
Market Restraints
- Peptide synthesis input volatility:Amino acid precursors and specialized fermentation media face price instability due to concentrated sourcing from agricultural commodity markets.
- Supplier concentration in lipid specialization:Encapsulation-grade surfactant production clusters among European and Japanese chemical houses, creating single-source vulnerability for serum penetration systems.
- Stability degradation thresholds:The sub-0.1% twelve-month degradation requirement limits viable active concentrations and extends R&D timelines for novel compounds.
Strategic Opportunities
- Medical-aesthetic crossover applications:Silica-based encapsulation technology is extending from cosmetics into post-procedure recovery formulations, opening reimbursement-adjacent revenue streams.
- ISO 16128 natural origin certification:Botanical extract procurement specifications increasingly filter contract eligibility, creating first-mover advantage for vertically integrated cultivation-to-extraction operations.
- Time-release architecture differentiation:Premium serum and cream margins concentrate around encapsulation innovation, rewarding houses that control both active synthesis and delivery system design.
Industry Challenges
- Toxicological dossier compilation expertise:REACH and MDR compliance requires specialized regulatory affairs talent that outpaces current training pipeline output in peptide chemistry.
- Fermentation-to-finished-active integration:Quality control handoffs between biotechnology platforms and formulation houses introduce validation complexity that extends commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmeceutical Ingredients Market |
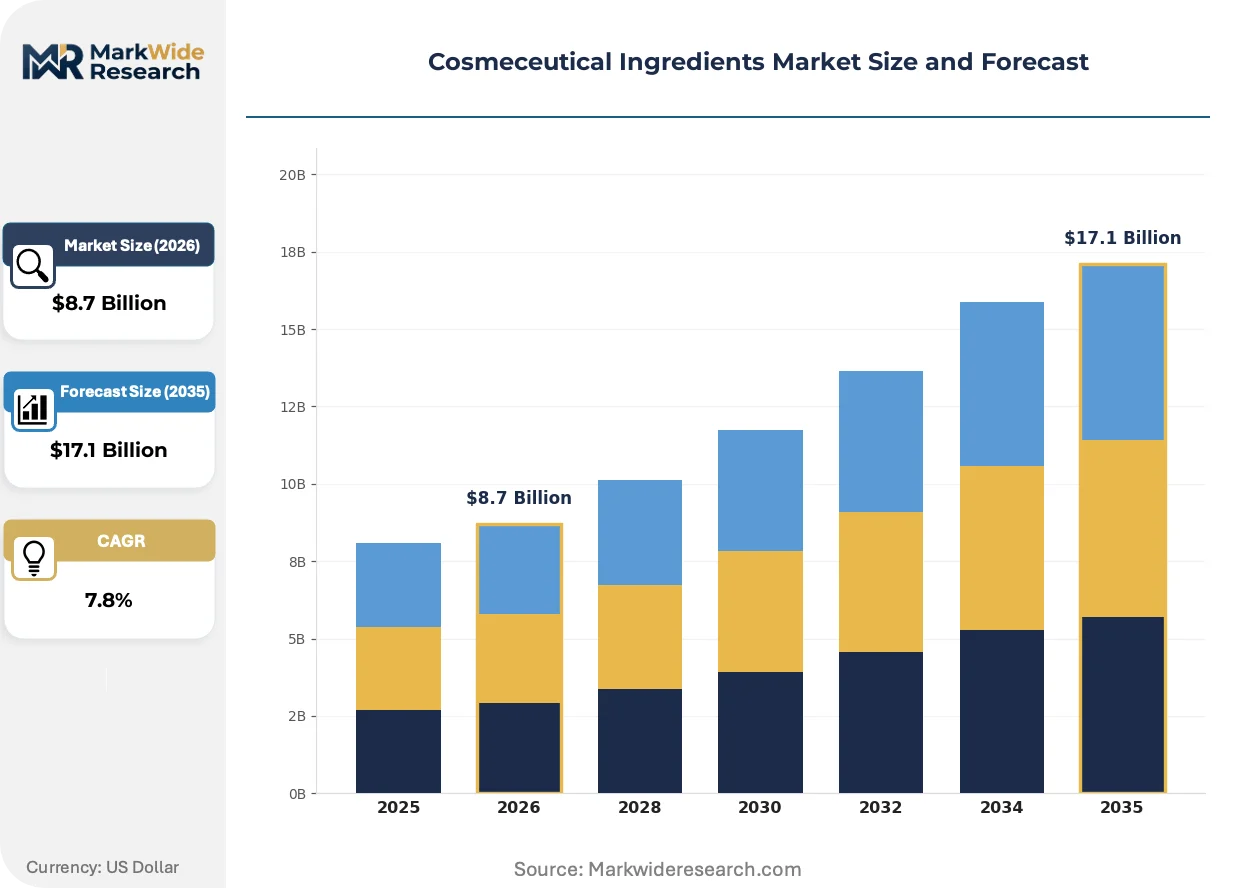
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
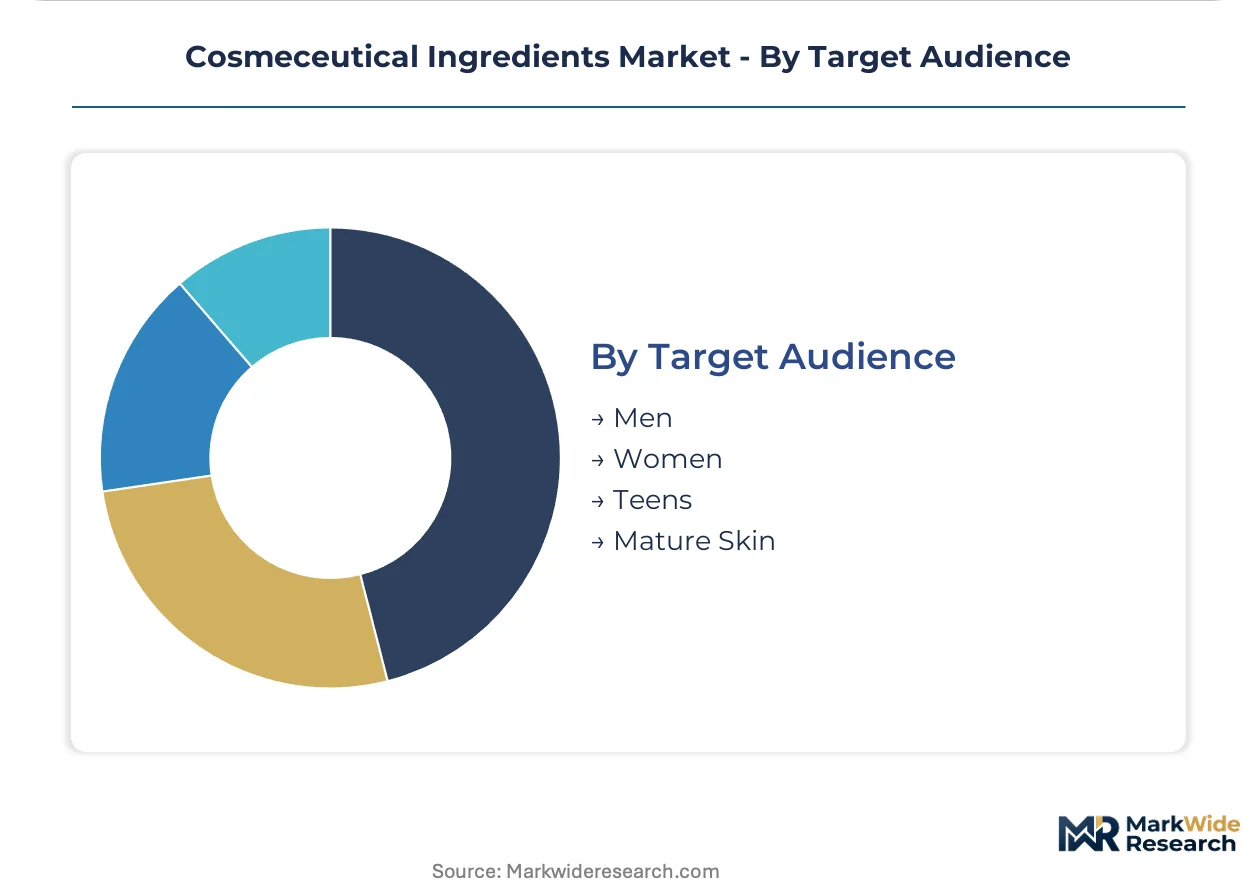
| Segmentation | Ingredient Type: Antioxidants, Peptides, Vitamins, Botanicals Formulation Type: Serums, Creams, Masks, Lotions Application Area: Skin Care, Hair Care, Anti-aging, Acne Treatment Target Audience: Men, Women, Teens, Mature Skin |
| Companies Covered | BASF SE, Croda International Plc, Eastman Chemical Company, The Lubrizol Corporation, Ashland, Symrise, Evonik Industries AG, Clariant AG, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmeceutical Ingredients Market Emerging Trajectories
Active ingredient delivery systems are undergoing architectural transformation as stability requirements and penetration validation reshape R&D investment priorities across formulation houses.
Lipid nanoparticle encapsulation is miniaturizing active payload dimensions to enhance dermal penetration rates while maintaining twelve-month stability thresholds. Premium dermatology clinics in Seoul and New York are adopting these systems for professional-grade protocols. The technology is compressing differentiation timelines between pharmaceutical and cosmetic-grade delivery architectures.
REACH registration deadlines for peptide suppliers are forcing toxicological dossier investments that restructure European market entry economics. Smaller synthesis houses are exiting or partnering with validated chemical majors to share compliance costs. Antioxidant and peptide categories face the steepest documentation burdens under ECHA's evolving substance evaluation criteria.
Direct-to-clinic procurement models are displacing traditional distributor relationships for high-potency actives used in professional treatment settings. Aesthetic medicine practices in Tokyo and New York are establishing captive supply agreements with peptide manufacturers. South Korea's contract manufacturing corridor is adapting fulfillment infrastructure to serve this channel shift.
Cosmeceutical Ingredients Market Segmentation
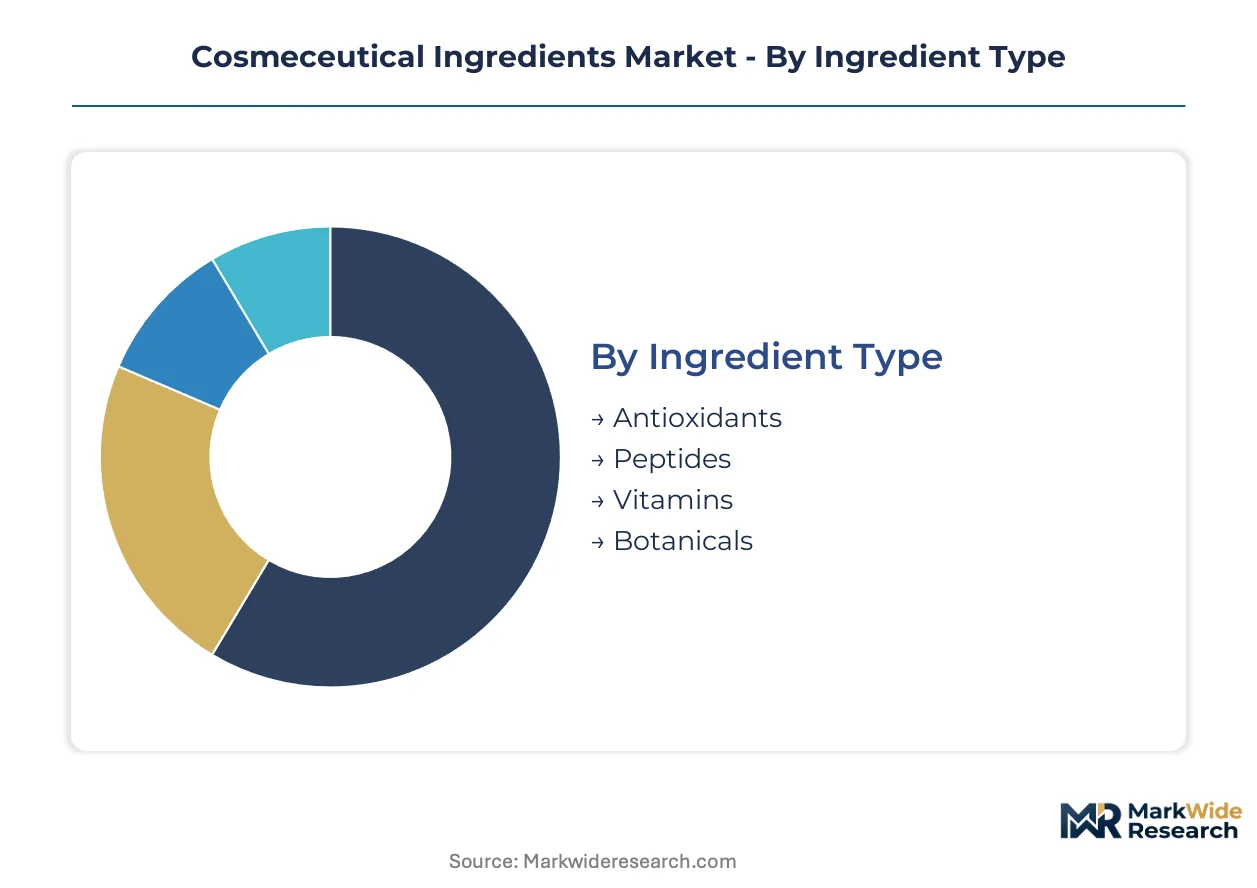
Ingredient classification in cosmeceuticals determines regulatory pathways, stability requirements, and margin structures. Each segment carries distinct synthesis complexity and clinical substantiation burdens that reshape procurement priorities across formulation houses.
Ingredient Type:
Peptides and antioxidants dominate export-led supply chains from South Korea and Germany, while botanical extracts concentrate in domestic cultivation-to-extraction operations across India and Brazil.
- Peptides:Short-chain amino acid sequences requiring fermentation-based synthesis and sub-0.1% stability validation over twelve months. Demand concentrates in Seoul-Gyeonggi corridor contract manufacturers supplying premium dermatology clinics in Tokyo and New York, where clinical substantiation requirements filter supplier pools.
- Antioxidants:Free-radical scavenging compounds including ascorbic acid derivatives and polyphenol complexes. Export volumes from European chemical houses face REACH registration mandates that restructure market entry economics, with ECHA toxicological dossiers compressing viable supplier counts.
- Vitamins:Retinoid and niacinamide compounds for cellular repair and barrier function. Domestic production clusters in China and India serve regional formulation houses with cost-optimized specifications.
- Botanicals:Plant-derived extracts requiring ISO 16128 natural origin certification. Traceability from cultivation through extraction now determines contract eligibility, favoring vertically integrated operations in Brazil and India over fragmented wild-harvesting networks.
Peptides holds the largest share; momentum sits with antioxidants as clinical substantiation requirements deepen.
Formulation Type:
Margin concentration varies sharply by delivery system complexity, with encapsulation-grade formats commanding premium positioning against commodity bases.
- Serums:High-actives, low-viscosity vehicles demanding lipid nanoparticle encapsulation for dermal penetration. Seoul and New York aesthetic clinics are adopting these systems for professional protocols, pulling pharmaceutical-grade actives into medical-aesthetic crossover applications.
- Creams:Emulsion-based vehicles with time-release architecture. European and Japanese chemical houses dominate encapsulation-grade surfactant supply, creating single-source vulnerability for serum penetration systems.
- Masks:Occlusive delivery formats for intensive treatment protocols. South Korean contract manufacturers lead innovation cycles here, supplying both domestic brands and global beauty houses.
- Lotions:Lower-actives, higher-volume vehicles for daily maintenance. Volume-driven procurement favors cost-optimized antioxidant and vitamin specifications without encapsulation overhead.
Serums command premium margins; masks are gaining share fastest through professional channel expansion.
Application Area:
End-use concentration reflects demographic aging patterns and dermatology clinic protocol standardization across major metropolitan markets.
- Skin Care:Barrier repair, hydration, and tone correction commanding the broadest formulation investment. Peptide and antioxidant actives dominate here, with stability requirements limiting viable concentration ranges.
- Anti-aging:Collagen synthesis stimulation and wrinkle reduction. Tokyo and New York aesthetic medicine practices are establishing captive supply agreements directly with peptide manufacturers, displacing traditional distributor relationships.
- Acne Treatment:Sebum regulation and antimicrobial delivery. Retinoid-based specifications face FDA cosmetic-drug claim scrutiny that shapes active concentration positioning in US markets.
- Hair Care:Scalp health and follicle stimulation. This segment trails skin applications in clinical substantiation investment, though antioxidant penetration into post-procedure recovery formulations is opening adjacent revenue streams.
Skin Care holds the largest share; anti-aging shows the steepest expansion trajectory as medical-aesthetic protocols proliferate.
Target Audience:
Demographic-specific formulation requirements are reshaping active concentration ranges and packaging specifications across regional markets.
- Women:The established core demand base spanning all application areas. Premium serum and cream margins concentrate here, with encapsulation innovation differentiating finished goods.
- Mature Skin:Specialized protocols for barrier function degradation and collagen depletion. Dermatology clinics in Seoul and Tokyo are expanding professional-grade treatment menus for this cohort, pulling pharmaceutical-grade actives into aesthetic protocols.
- Men:Simplified regimens with lower SKU complexity but rising actives concentration. Direct-to-clinic procurement models are penetrating this segment as aesthetic medicine practices professionalize male treatment protocols.
- Teens:Acne-focused, price-sensitive specifications with regulatory constraints on retinoid concentrations. FDA oversight of cosmetic-drug distinctions shapes manufacturer positioning here.
Women holds the largest share; mature skin is climbing the fastest as population aging accelerates clinical protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis infrastructure clusters in Germany and South Korea, where fermentation-to-finished-active integration commands premium contract awards. Antioxidant production concentrates among European chemical majors facing REACH dossier deadlines. Botanical extraction gravitates toward Brazil and India, where cultivation traceability certifications filter supplier eligibility.
Germany
Specialty chemical majors anchor European peptide and encapsulation-grade surfactant supply. ECHA REACH registration mandates filter viable antioxidant suppliers, compressing market entry economics for subscale producers. The Rhine-Ruhr corridor houses fermentation infrastructure serving medical-aesthetic crossover formulations.
South Korea
Seoul-Gyeonggi contract manufacturers supply both domestic brands and global beauty houses with pharmaceutical-grade actives. MFDS cosmetic-drug boundary enforcement shapes professional-grade treatment protocol development. Busan-Ulsan chemical complexes support lipid nanoparticle encapsulation for premium dermatology clinics.
United States
New York aesthetic medicine practices establish captive supply agreements directly with peptide manufacturers, displacing traditional distributor channels. FDA cosmetic modernization proposals fragment compliance investment against EU chemical strategy requirements. Greater Boston biotechnology clusters extend fermentation platforms into active synthesis.
Brazil
Vertically integrated cultivation-to-extraction operations capture ISO 16128 natural origin certification advantages in botanical extracts. ANVISA pharmaceutical-grade purity specifications reshape procurement priorities for antioxidant and peptide imports. São Paulo formulation houses source traceable plant actives for premium skin care exports.
Japan
Tokyo dermatology clinics expand professional-grade peptide and antioxidant treatment menus, pulling pharmaceutical-grade actives into aesthetic protocols. METI standards for cosmetic ingredient stability validation align with sub-0.1% twelve-month degradation thresholds. Osaka-Kobe chemical complexes specialize in encapsulation-grade surfactant production.
Cosmeceutical Ingredients Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with fermentation-based peptide specialists commanding premium positioning against commodity antioxidant suppliers. The vendor base stratifies across three tiers: integrated biotechnology platforms controlling synthesis-to-delivery quality chains, lipid and surfactant specialists underpinning penetration systems, and regional botanical extractors competing on traceability certification. Dominant competitive moves include backward integration into cultivation-to-extraction operations and technology licensing partnerships bridging pharmaceutical and cosmetic-grade delivery architectures.
Among Germany-based chemical majors, BASF SE and Evonik Industries AG occupy positions at the technology leadership pole, with the former exemplifying integrated biotechnology platform control and the latter anchoring high-potency active encapsulation specialization. Croda International Plc, a UK-registered specialty chemical house, represents the lipid and surfactant archetype that underpins next-generation serum penetration systems. These three players illustrate how European chemical infrastructure concentrates compliance-capable supply for REACH-registered peptide and antioxidant categories.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Eastman Chemical Company |
| The Lubrizol Corporation |
| Ashland |
| Symrise |
| Evonik Industries AG |
| Clariant AG |
| Lonza |
| Others |
Supply Flow & Price Mechanics
Fermentation-to-finished-active integration at scale creates dual pressure on peptide pricing floors, compressing subscale producers while rewarding validated manufacturers with REACH dossier capabilities. Capacity utilization rates above eighty percent in Seoul-Gyeonggi and Rhine-Ruhr corridors concentrate contract awards among integrated biotechnology platforms, forcing price discipline through supplier pool compression.
Pricing Analysis
EU REACH registration mandates dictate the pricing tier structure across peptide and antioxidant categories, separating pharmaceutical-grade actives from cosmetic-grade specifications. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with ISO 16128 natural origin premiums commanding fifteen to twenty percent spreads over conventional botanicals. Cost compression in standard-grade antioxidants intensifies as Chinese fermentation capacity expands, while premium serums show pricing resilience due to encapsulation-grade surfactant scarcity. Small formulation houses exhibit highest price sensitivity, captive supply agreements at aesthetic medicine practices show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend lead times for amino acid precursors and specialized fermentation media, amplifying working capital requirements for peptide synthesis houses. Supply concentrates in Germany, South Korea, and Japan for encapsulation-grade actives, while Brazil and India anchor botanical extraction. Raw material dependencies span agricultural amino acid feedstocks, silica nanoparticles for delivery systems, and certified organic cultivation bases. Single-source vulnerability in lipid nanoparticle surfactants from Osaka-Kobe and Rhine-Ruhr complexes threatens serum penetration system continuity. Distribution runs through direct-to-clinic procurement models displacing traditional distributor relationships in Tokyo and New York aesthetic medicine markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from stability validation protocols and regulatory dossier compilation is expanding faster than commodity active ingredient sales, creating recurring-revenue architectures for integrated biotechnology platforms.
For Market Incumbents: Consolidate fermentation capacity in Seoul-Gyeonggi and Rhine-Ruhr corridors to defend against Chinese cost competition in standard-grade antioxidants. Deepen captive supply agreements with Tokyo and New York aesthetic medicine practices to lock in professional-grade peptide offtake. Certification investment in ISO 16128 natural origin standards creates switching costs against emerging botanical extractors in Brazil and India. For New Entrants and Emerging Players: ISO 16128 fast-track certification for vertically integrated cultivation-to-extraction operations in underserved botanical corridors creates immediate contract eligibility. White-space concentrates in post-procedure recovery formulations where medical-aesthetic crossover applications lack specialized antioxidant suppliers. Hair care antioxidant penetration offers the most penetrable application segment. Go-to-market through direct-to-clinic procurement partnerships with Seoul aesthetic medicine practices bypasses established distributor gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biotechnology platforms controlling fermentation-to-finished-active quality chains with REACH dossier capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than synthesis scale alone. Acquisition targets should profile as mid-cap peptide specialists with validated stability protocols and existing professional channel relationships. The signal to watch is ECHA substance evaluation criteria expansion, which would accelerate supplier pool compression and reward pre-positioned compliance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation-to-Extraction Operations | ISO 16128 certification capture in Brazil and India secures contract eligibility for premium botanical supply. |
| REACH Dossier Investment Partnership | Shared toxicological documentation costs with European chemical majors preserve European market access for peptide suppliers. |
| Direct-to-Clinic Procurement Infrastructure | Seoul and New York aesthetic medicine captive supply agreements displace traditional distributor relationships for high-potency actives. |
| Lipid Nanoparticle Encapsulation Scale-Up | Busan-Ulsan chemical complex expansion addresses single-source vulnerability in serum penetration system supply. |
| Medical-Aesthetic Crossover Formulation Development | Post-procedure recovery antioxidant protocols open reimbursement-adjacent revenue streams adjacent to pharmaceutical channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association publications to anchor quantitative outputs. Primary interviews engaged peptide synthesis directors, regulatory affairs specialists at formulation houses, procurement managers at Seoul-Gyeonggi contract manufacturers, and aesthetic medicine practitioners in Tokyo and New York. Secondary validation drew from ECHA REACH registration databases, MFDS cosmetic-drug boundary guidance, FDA modernization proposals, and ISO 16128 certification registries. Bottom-up volume triangulation across ingredient type, formulation format, and application area segments converged with top-down market sizing from chemical house revenue disclosures.
Segmentation dimensions modeled span ingredient classification, formulation complexity tier, end-use application, and target demographic cohort across the projection horizon. CAGRs derive from regression analysis of historical volume trends against regulatory milestone timing and professional channel expansion rates. Forecast inputs incorporate ECHA substance evaluation pipeline depth, MFDS enforcement intensity trajectories, and aesthetic medicine clinic protocol standardization velocity in major metropolitan markets.
Decision-makers should treat outputs as directional under assumptions of sustained REACH registration stringency and continued professional channel growth; material deviation would warrant model refresh. Specific risks include regulatory divergence between FDA cosmetic modernization and EU chemical strategy sustainability requirements, amino acid precursor commodity price volatility, and logistics disruption on Asia-Europe trade lanes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Hand Care Market
Skincare
After Sun Care Products Market
Skincare
Medicine Skin Care Market
Skincare
United Kingdom Skincare Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Global Scar Removal Treatment Market
Skincare
Acne Treatment Market
Skincare
Retinol Skincare Product Market
Skincare
Facial Cleansing Balm Market
Skincare
Skin Resurfacing Market
Skincare
Asia-Pacific Skincare Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Skincare Ingredients Market
Skincare
Vitamin C Serum Market