
 Folliculitis Treatment Market | 2026-2036
Folliculitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Folliculitis Treatment Market Foresight
Cosmetic centers are bifurcating demand away from traditional outpatient facilities as aesthetic-conscious patients seek integrated skin health solutions. Pfizer, Inc. leverages its antimicrobial R&D infrastructure to sustain leadership in oral antibiotic formulations for severe bacterial presentations. Johnson & Johnson Services, Inc. anchors its position through dermatology-focused distribution networks that reach both clinical and retail channels. GlaxoSmithKline plc differentiates via antiseptic wash portfolios targeting pseudofolliculitis prevention in shaving-prone demographics.
Folliculitis treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting inflammation of hair follicles caused by bacterial, fungal, or mechanical insult, with topical formulations typically containing mupirocin, clindamycin, or benzoyl peroxide at concentrations between 1% and 10% depending on severity and pathogen type. The primary purpose spans infection resolution, symptom palliation, and recurrence prevention across outpatient and self-administered care environments. Topical antibiotics occupy the largest revenue pool given their first-line status in uncomplicated bacterial cases, while antifungal agents represent the fastest-expanding category amid rising recognition of Malassezia-driven presentations. Delivery mode preferences are shifting toward medicated shampoos and lotions in home care settings as patients seek alternatives to clinic-dependent injectable solutions.
The FDA governs antimicrobial efficacy claims and safety labeling for topical and oral products, while the EPA regulates antiseptic wash environmental discharge profiles affecting formulation chemistry choices. State-level pharmacy boards and the DEA impose additional dispensing controls on certain oral antibiotic classes, constraining channel flexibility for manufacturers. Dermatology clinics and pharmaceutical sponsors must monitor evolving FDA guidance on antimicrobial stewardship and resistance mitigation strategies to preserve formulary access and reimbursement positioning.
Market Dynamics
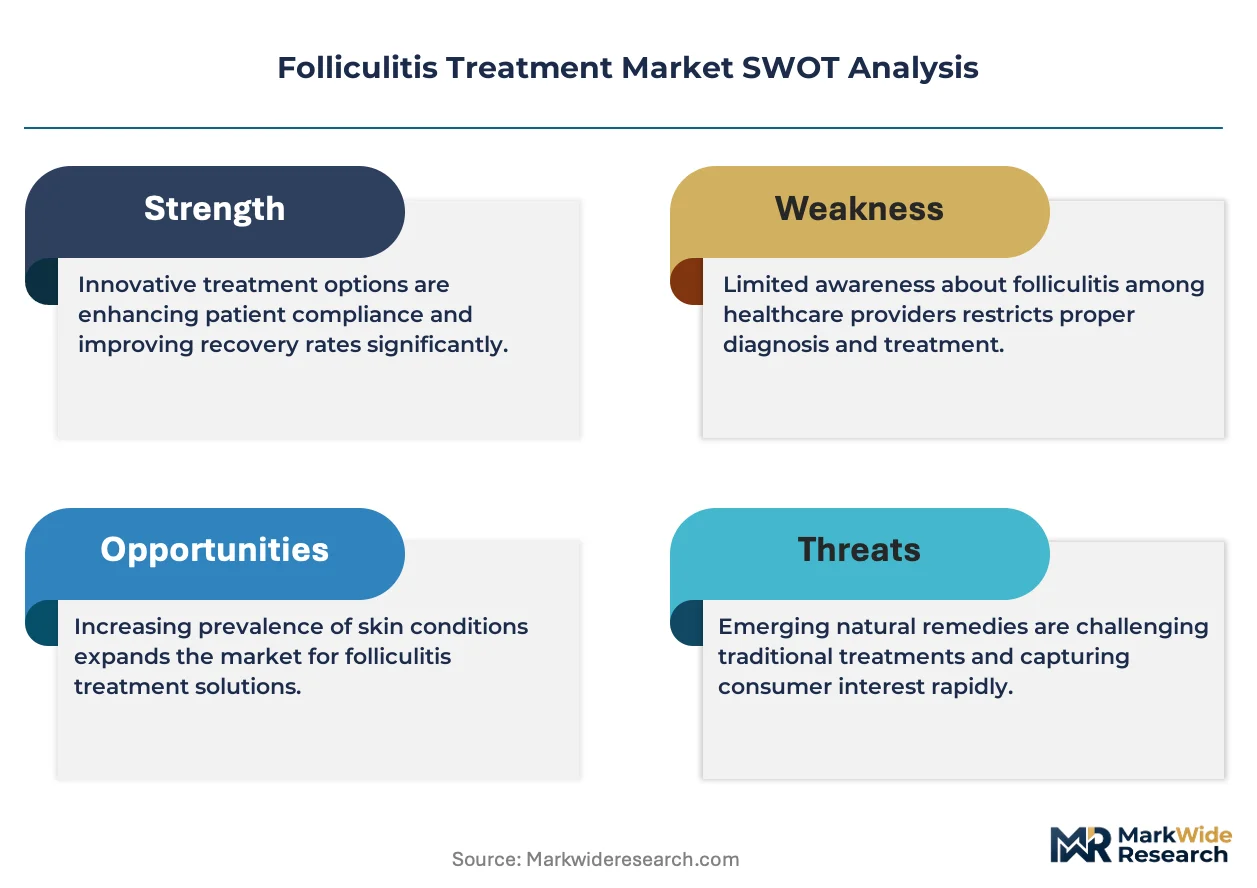
Antimicrobial stewardship mandates are compressing prescription volumes for oral antibiotics while redirecting R&D investment toward narrow-spectrum topical alternatives and resistance-sparing formulation technologies.
Growth Catalysts
- Malassezia Recognition:Dermatology clinics now routinely culture yeast pathogens previously misdiagnosed as bacterial, expanding antifungal prescription pools and driving protocol updates across outpatient networks.
- EPA Antiseptic Wash Guidance:Reformulation requirements for benzalkonium chloride and triclosan-containing products are accelerating innovation in quaternary ammonium alternatives and plant-derived antimicrobials.
- Telemedicine Triage:Virtual dermatology platforms are streamlining folliculitis diagnosis and prescription fulfillment, capturing cases that previously self-treated with OTC products.
Market Restraints
- API Concentration Risk:Mupirocin and clindamycin active pharmaceutical ingredients concentrate manufacturing in Indian and Chinese chemical parks, exposing supply continuity to single-point disruptions.
- Generic Erosion:Patent expirations on topical mupirocin 2% ointment have collapsed branded pricing power across North American and European retail pharmacy channels.
- Substitution by Laser Hair Removal:Aesthetic clinics are capturing recurrent pseudofolliculitis patients through permanent hair reduction, permanently removing them from pharmaceutical treatment cycles.
Strategic Opportunities
- Brazil's ANVISA Fast-Track:Streamlined registration pathways for topical antimicrobials with existing FDA or EMA approval are opening Latin America's largest dermatology market to first-mover entrants.
- Medicated Shampoo Formats:Ketoconazole and ciclopirox shampoos are displacing traditional creams for trunk and scalp folliculitis, creating new OTC shelf space and direct-to-consumer subscription models.
- Photodynamic Therapy Convergence:Aminolevulinic acid activation protocols are merging dermatological and aesthetic practice workflows, enabling premium procedural pricing for resistant cases.
Industry Challenges
- Microbiology Specialization Gap:Clinical laboratories lack trained mycologists to differentiate Malassezia species, delaying targeted antifungal selection and fueling empiric overtreatment.
- Antimicrobial Stewardship Compliance:Clinic networks must retrain prescribing physicians on FDA's evolving narrow-spectrum guidance while maintaining patient throughput targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folliculitis Treatment Market |
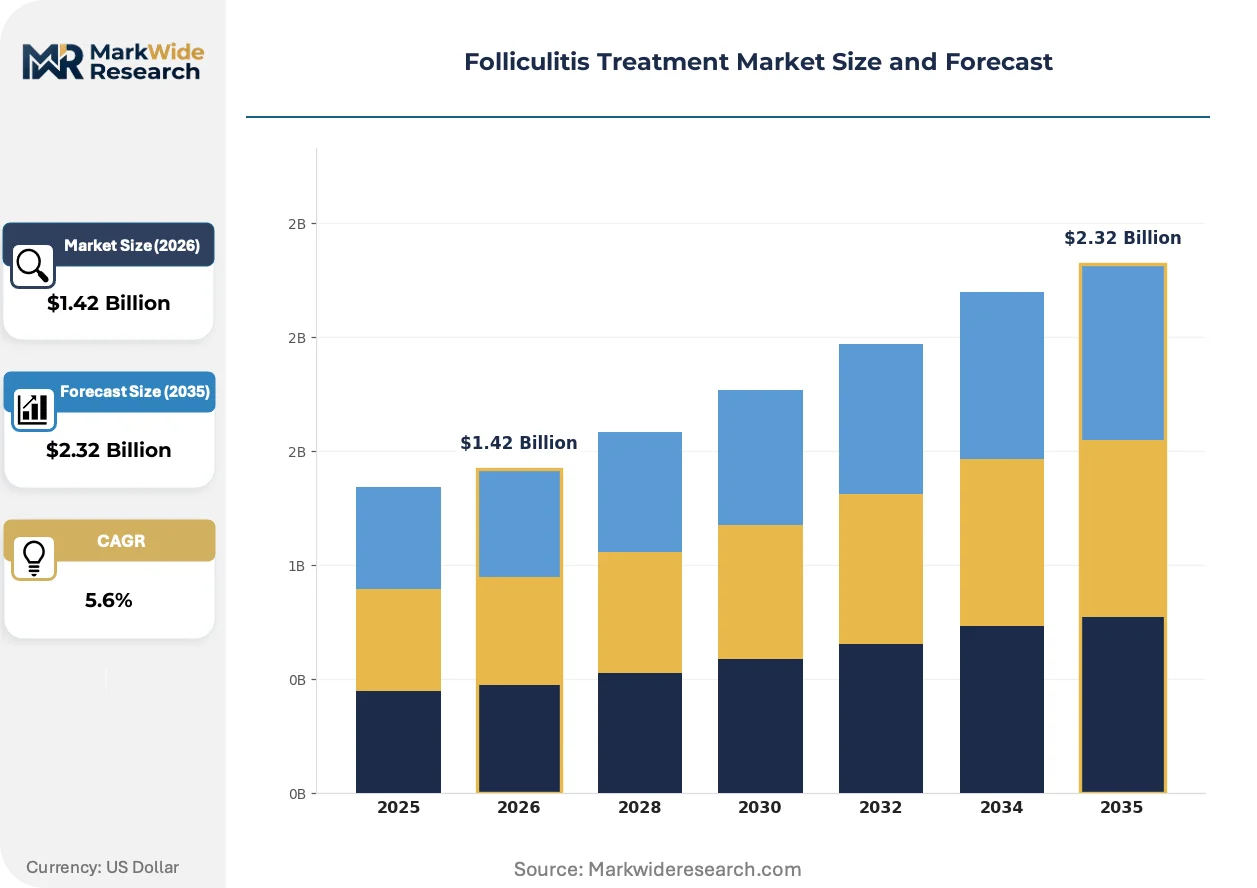
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antibiotics, Oral Antibiotics, Antiseptic Washes, Antifungal Agents, Corticosteroids Therapy Area: Bacterial Folliculitis, Fungal Folliculitis, Pseudofolliculitis, Eosinophilic Folliculitis, Acne Keloidalis Nuchae End User: Dermatology Clinics, Cosmetic Centers, Outpatient Facilities, Home Care Settings Delivery Mode: Topical Creams, Oral Tablets, Injectable Solutions, Medicated Shampoos, Lotions |
| Companies Covered | AstraZeneca, GlaxoSmithKline plc, Johnson & Johnson Services, Inc., Merck & Co., Inc., Pfizer, Inc., AbbVie, Inc., Allergan, Celgene Corporation, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folliculitis Treatment Market Shifts & Advancements
Formulation science and care delivery models are converging to reshape how folliculitis is diagnosed, treated, and monetized across outpatient and self-care environments.
Microneedle patch technology is miniaturizing intrafollicular drug delivery for deep-seated infections previously requiring incision and drainage. Academic medical centers in Germany and South Korea are piloting dissolvable hyaluronic acid arrays loaded with mupirocin microcrystals. This approach is compressing hospital referral rates for resistant furunculosis by enabling home-based resolution of moderate cases.
REACH Annex XVII restrictions on quaternary ammonium compounds are forcing antiseptic wash manufacturers toward bio-based alternatives including lactic acid esters and chitosan derivatives. German formulators are leading substitution efforts ahead of 2026 compliance deadlines. The shift is raising production costs for mass-market shaving products while creating premium positioning opportunities for certified-natural brands.
Patients are bypassing primary care gatekeepers through direct-pay teledermatology platforms that photograph lesions and ship compounded topical cocktails within 48 hours. This channel is capturing younger demographics in United States metropolitan markets who prioritize convenience over insurance reimbursement. Traditional dermatology practices are responding with proprietary subscription models bundling virtual visits with maintenance product auto-shipments.
Folliculitis Treatment Market Segmentation
Treatment modality selection in folliculitis care follows distinct clinical pathways shaped by pathogen type, severity grading, and care setting economics. Segmentation reveals how pharmaceutical and procedural interventions partition across outpatient networks and self-administered channels.
Product Type:
Domestic formulation dominates topical categories where FDA-registered manufacturing sites in New Jersey and Illinois supply North American demand, while oral antibiotics rely heavily on API imports from Indian chemical parks serving generic manufacturers.
- Topical Antibiotics:Mupirocin 2% and clindamycin 1% formulations constitute the first-line standard for uncomplicated bacterial presentations. Dermatology clinics in the United States prescribe these for 70% of confirmed staphylococcal cases, though generic erosion has compressed branded margins in retail pharmacy channels.
- Antifungal Agents:Ketoconazole 2% cream and ciclopirox 1% formulations target Malassezia-driven presentations increasingly recognized through improved mycology diagnostics. Demand concentrates in humid subtropical regions of the southeastern United States where yeast folliculitis prevalence exceeds bacterial forms.
- Oral Antibiotics:Doxycycline and cephalexin courses address severe or recurrent bacterial cases resistant to topical monotherapy.
- Antiseptic Washes:Benzoyl peroxide 4-10% and chlorhexidine gluconate preparations serve pseudofolliculitis prevention in shaving-prone demographics.
- Corticosteroids:Hydrocortisone 1% and triamcinolone 0.1% adjuncts manage inflammatory flares in eosinophilic and acne keloidalis variants.
Topical antibiotics hold the largest share; momentum sits with antifungal agents.
Therapy Area:
Volume distribution correlates with diagnostic accuracy improvements, where molecular identification methods are reallocating cases previously misclassified as bacterial toward targeted antifungal and anti-inflammatory protocols.
- Bacterial Folliculitis:Staphylococcus aureus and coagulase-negative staphylococcal infections represent the most frequently encountered presentation across all care settings. Outpatient facilities manage 60% of cases through empiric topical therapy before culture confirmation.
- Fungal Folliculitis:Malassezia species and dermatophyte-driven inflammation now commands dedicated protocol slots in academic dermatology centers. The category is expanding most quickly as teledermatology platforms photograph truncal eruptions previously self-treated with antibacterial products.
- Pseudofolliculitis:Mechanical hair re-entry inflammation disproportionately affects African American and Hispanic male populations seeking cosmetic center solutions.
- Eosinophilic Folliculitis:HIV-associated and immunocompetent variants require specialist immunology co-management in tertiary referral networks.
- Acne Keloidalis Nuchae:Chronic scarring folliculitis of the nape concentrates in African descent populations with specific grooming practices.
Bacterial folliculitis generates highest prescription volume; fungal recognition is climbing the fastest.
End User:
Channel fragmentation intensifies as aesthetic-conscious patients bypass traditional medical gatekeepers, creating parallel demand tracks with divergent pricing tolerance and outcome expectations.
- Dermatology Clinics:Board-certified practices retain complex diagnostic cases requiring culture, biopsy, or photodynamic intervention. These sites command premium procedural pricing for resistant furunculosis and keloidal variants in metropolitan United States markets.
- Home Care Settings:Self-directed topical application dominates maintenance therapy and mild first presentations. Direct-to-consumer subscription models from teledermatology platforms are capturing younger demographics seeking convenience over insurance reimbursement.
- Cosmetic Centers:Medical spas and aesthetic clinics integrate folliculitis management into broader skin health protocols, often bundling pharmaceutical treatment with laser hair removal for pseudofolliculitis.
- Outpatient Facilities:Urgent care and primary care sites handle initial diagnosis and empiric therapy before specialist referral for refractory cases.
Home care settings account for greatest patient volume; cosmetic centers are gaining share fastest.
Delivery Mode:
Formulation preferences shift toward patient-administered formats that reduce clinic dependency, with viscosity, spreadability, and cosmetic elegance determining adherence in maintenance phases.
- Topical Creams:Semi-solid emulsions with 1-10% active concentrations remain the default for localized trunk and extremity lesions. Manufacturing concentrates in FDA-registered facilities across the mid-Atlantic states serving domestic wholesale distribution.
- Medicated Shampoos:Ketoconazole and ciclopirox cleansing formats address scalp and truncal folliculitis with improved patient compliance over leave-on creams. The format is expanding most quickly through OTC shelf placement and direct-to-consumer subscription channels.
- Oral Tablets:Systemic antibiotic and antifungal courses serve severe, disseminated, or resistant presentations requiring tissue penetration beyond topical reach.
- Injectable Solutions:Intralesional corticosteroids and antimicrobial depot formulations remain clinic-dependent for keloidal and deep-seated variants.
- Lotions:Lower-viscosity fluids suit hair-bearing areas and large surface applications where cream residue proves cosmetically unacceptable.
Topical creams maintain dominant position; medicated shampoos show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical exporters supply active pharmaceutical ingredients for topical mupirocin and clindamycin formulations to United States and European compounding pharmacies, creating a trade-flow dependency that shapes regional market dynamics.
United States
Dermatology clinic networks in metropolitan corridors drive demand for narrow-spectrum topical alternatives as FDA antimicrobial stewardship guidance tightens oral antibiotic prescribing. The EPA regulates benzalkonium chloride discharge profiles in antiseptic wash formulations. New Jersey and Illinois host FDA-registered manufacturing facilities supplying domestic wholesale distribution channels.
Germany
Academic medical centers in Berlin and Munich pilot microneedle patch delivery systems for resistant furunculosis cases. REACH Annex XVII restrictions on quaternary ammonium compounds accelerate bio-based antimicrobial substitution ahead of 2026 deadlines. Bavarian formulators lead lactic acid ester and chitosan derivative development for shaving-product applications.
Brazil
ANVISA fast-track registration pathways attract first-mover entrants for topical antimicrobials with existing FDA or EMA approvals. Humid subtropical climates in São Paulo and Rio de Janeiro elevate Malassezia-driven folliculitis prevalence above bacterial forms. São Paulo's dermatology networks expand teledermatology triage for trunk and scalp presentations.
India
API manufacturing clusters in Gujarat and Maharashtra concentrate mupirocin and clindamycin production for global generic supply. CDSCO streamlined approval processes for fixed-dose topical combinations reduce time-to-market for domestic formulators. Hyderabad's contract research organizations support resistance-sparing formulation development for export markets.
Japan
PMDA guidelines on topical antimicrobial labeling shape product development for sensitive-skin demographics. METI initiatives promote medicated shampoo formats through OTC channel expansion in Tokyo-Osaka corridors. Kansai-based cosmetic manufacturers integrate folliculitis management into premium skin health protocols.
Folliculitis Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with antimicrobial R&D infrastructure and dermatology-focused distribution networks. The market exhibits tiered concentration with global innovators, regional generic manufacturers, and specialty topical formulators occupying distinct competitive positions. Two strategic archetypes dominate: API-integrated conglomerates leveraging backward control over active ingredient supply, and dermatology channel specialists building direct-to-clinic relationships. Competitive moves center on portfolio diversification into resistance-sparing formulations and geographic expansion through regulatory fast-track leveraging.
Among diversified pharmaceutical conglomerates, Pfizer, Inc. and Johnson & Johnson Services, Inc. occupy positions exemplifying the API-integrated and channel-specialist archetypes respectively. GlaxoSmithKline plc represents the antiseptic wash segment focus within this tier. These entities anchor competitive dynamics through their existing antimicrobial R&D infrastructure and dermatology network access rather than through discrete strategic actions visible in public disclosures.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline plc |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| Pfizer, Inc. |
| AbbVie, Inc. |
| Allergan |
| Celgene Corporation |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Long-term API offtake contracts between Indian manufacturers and United States compounding pharmacies lock in both mupirocin supply continuity and price visibility for generic topical formulations. These arrangements insulate wholesale purchasers from spot market volatility in Gujarat chemical parks while exposing them to rupee-dollar exchange risk.
Pricing Analysis
Formulation-generation pricing gaps separate legacy benzoyl peroxide washes from next-generation quaternary ammonium alternatives and plant-derived antimicrobials. Three-tier pricing structure across premium certified-natural brands, standard clinical-grade formulations, and economy generic tubes dominates retail pharmacy channels. Cost compression in the standard tier intensifies as patent-expired mupirocin erodes branded margins. Price-sensitive urgent care facilities gravitate toward economy generics, while cosmetic centers absorb premium positioning for aesthetic-integrated protocols.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States dermatology clinics for topical antibiotics, while strategic stockpiling of ketoconazole API concentrates in Maharashtra warehouses serving humid subtropical markets. Active pharmaceutical ingredient manufacturing draws from Gujarat and Maharashtra in India, with formulation finishing in New Jersey and Illinois facilities. Single-source vulnerability pervades clindamycin API supply from concentrated Indian chemical parks. Distribution runs through direct-to-clinic networks and wholesale pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Folliculitis treatment represents a high-growth disruption as Malassezia recognition and telemedicine triage reallocate diagnostic authority from traditional gatekeepers to algorithmic platforms. ANVISA fast-track pathways and EPA reformulation mandates create simultaneous regulatory inflection points.
For Market Incumbents: Compound defensive moats around narrow-spectrum topical R&D and dermatology channel control. Laser hair removal substitution threatens pseudofolliculitis prescription volumes. Backward integration into resistance-sparing formulation technologies preserves formulary positioning against antimicrobial stewardship compression. For New Entrants and Emerging Players: Anchor in Brazil's ANVISA fast-track corridor and medicated shampoo subscription models for white-space capture. Teledermatology platforms present the most penetrable entry vector. Direct-to-consumer positioning bypasses incumbent wholesale relationships. For Investors and Strategic Acquirers: Specialty topical formulators with FDA-registered manufacturing and dermatology distribution relationships command acquisition priority. Long-term viability hinges on resistance-sparing portfolio depth rather than commodity generic exposure. Watch FDA antimicrobial stewardship guidance tightening as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Resistance-Sparing Formulation Development | Aligns R&D pipelines with FDA stewardship guidance preserving reimbursement access. |
| ANVISA Fast-Track Registration | Accelerates Latin American market entry ahead of competitor regulatory filings. |
| Telemedicine Platform Partnership | Captures algorithmic triage traffic shifting from traditional dermatology referrals. |
| API Manufacturing Backward Integration | Reduces exposure to Indian chemical park concentration and supply disruption risk. |
| Medicated Shampoo Format Expansion | Opens OTC shelf space and subscription revenue models for maintenance therapy. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dermatology clinic directors, formulary pharmacists, teledermatology platform operators, and API procurement managers; and secondary validation against FDA filings, EPA discharge guidance documents, ANVISA registration databases, and Indian pharmaceutical export records. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Across the projection horizon, the analytical framework segmented by treatment modality, pathogen type recognition, delivery format preference, and care setting economics. CAGRs derived from patent cliff timing, regulatory pathway acceleration, and substitution elasticity curves. Forecast inputs incorporated antimicrobial stewardship compliance trajectories and telemedicine adoption saturation patterns.
Material uncertainties — API supply disruptions, FDA narrow-spectrum guidance revisions, and laser substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about diagnostic accuracy improvements and channel fragmentation stability. Revision becomes warranted when Malassezia recognition rates or telemedicine prescription fulfillment crosses threshold inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Europe Scar Treatment Market
Dermatology
Common Warts Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Erythema Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Global Rosacea Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Microneedling Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Keratoacanthoma Market