
 Post-Partum Depression Market | 2026-2036
Post-Partum Depression Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Partum Depression Market Intelligence
Single-source reliance on intravenous brexanolone infusion centers is recalibrating toward multi-channel distribution that incorporates telehealth platforms and outpatient clinics. Sage Therapeutics anchors the novel therapeutic segment with its neuroactive steroid franchise, while Eli Lilly and Company leverages decades of psychiatric drug development infrastructure to compete in the antidepressant space. Pfizer sustains commercial scale through primary care physician networks that remain the dominant prescription channel for post-partum depression pharmacotherapy.
Post-partum depression constitutes a major depressive episode occurring within four weeks after delivery, characterized by mood lability, fatigue, and impaired maternal-infant bonding that disrupts neonatal development and family functioning. The condition demands interventions ranging from serotonin reuptake inhibition to allopregnanolone modulation, with treatment selection governed by symptom severity, lactation status, and patient functional capacity. Antidepressants occupy the mature volume base, yet telehealth applications represent the fastest-growing structural segment as synchronous video platforms collapse geographic barriers to psychiatric access. Outpatient care retains the deepest margin pools due to reimbursement advantages for facility-based administration of novel therapies, while inpatient treatment remains concentrated at severe disease extremes.
FDA Risk Evaluation and Mitigation Strategy requirements for brexanolone constrain distribution to certified healthcare facilities, directly shaping site-of-care economics and patient access patterns. EMA's evolving position on maternal mental health therapeutics under the MDR framework influences parallel approval strategies for European market entry, while HIPAA governs telehealth platform architectures and data exchange protocols that enable remote care expansion. Stakeholders must monitor how CMS reimbursement decisions for digital therapeutic codes will restructure competitive economics between pharmaceutical and platform-based interventions.
Market Dynamics
FDA Risk Evaluation and Mitigation Strategy requirements for brexanolone have locked distribution into certified healthcare facilities, forcing pharmaceutical developers to build parallel telehealth infrastructure while maintaining physical infusion capabilities.
Growth Catalysts
- Neuroactive steroid pipelines:Novel allopregnanolone analogs advancing through clinical stages are creating mechanism-of-action diversity beyond serotonin reuptake inhibition. EMA's evolving maternal mental health framework under MDR is accelerating parallel European development timelines.
- Telehealth reimbursement expansion:CMS decisions enabling digital therapeutic billing codes are collapsing geographic barriers to psychiatric access. Home care settings now integrate synchronous video platforms with remote patient monitoring for post-partum depression management.
- United States policy momentum:State-level maternal mental health screening mandates and expanded Medicaid coverage for perinatal psychiatric services are standardizing care pathways. Commercial payers are following public program precedents on reimbursement parity.
Market Restraints
- Facility-based administration costs:Intravenous brexanolone requires certified healthcare facility staffing and monitoring, creating site-of-care economics that limit patient throughput. Hospital outpatient departments absorb margin through facility fees.
- Supply concentration in neuroactive steroids:Single-source dependence on Sage Therapeutics' manufacturing infrastructure creates vulnerability to production disruptions. No approved second-source allopregnanolone products exist.
- HIPAA compliance architecture:Telehealth platform data exchange protocols impose technical and legal friction on remote care scaling. State-level licensing restrictions on interstate psychiatric practice compound regulatory complexity.
Strategic Opportunities
- Oral neuroactive steroid formulations:SAGE-217 and follow-on compounds promise to eliminate infusion center requirements, expanding addressable patient populations beyond facility-accessible geographies. Outpatient clinics and retail pharmacy channels await this transition.
- Digital therapeutic integration:FDA breakthrough device designation pathways for cognitive behavioral therapy apps create regulatory tailwinds for software-based interventions. Platform developers can stack prescription and non-prescription revenue models.
- Employer-sponsored perinatal benefits:Large self-insured employers are adding dedicated maternal mental health navigation services as retention tools. This channel bypasses traditional payer prior authorization barriers.
Industry Challenges
- Psychiatric-perinatal specialist shortage:Fellowship-trained reproductive psychiatrists number fewer than 500 across the United States, creating access bottlenecks even where reimbursement exists. Telehealth partially mitigates but cannot replicate in-person infant-mother observation.
- REM program compliance complexity:FDA-mandated risk management infrastructure requires dedicated pharmacovigilance staff, specialized training, and continuous monitoring systems that strain mid-cap commercial organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Partum Depression Market |
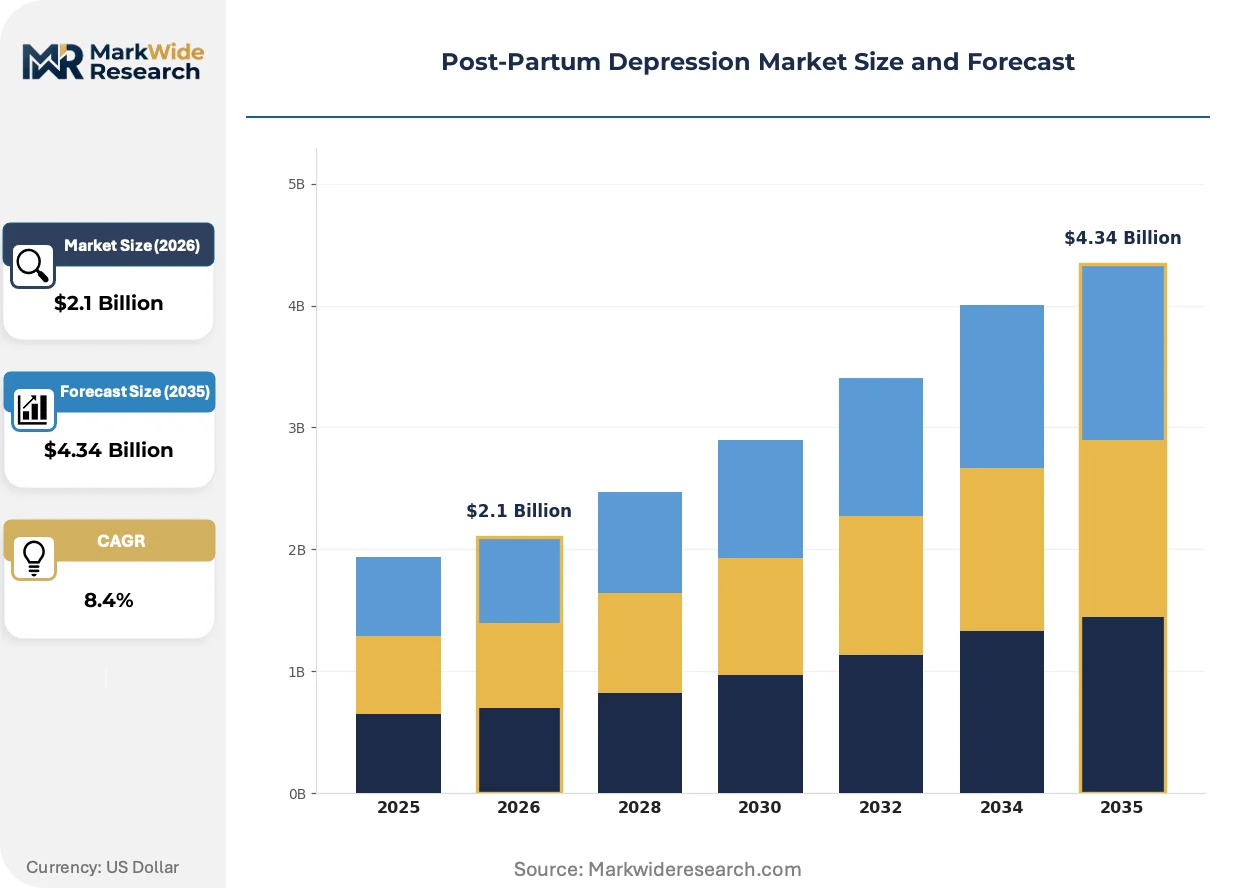
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Psychotherapy, Hormone Therapy, Support Groups Application: Home Care, Outpatient Care, Inpatient Treatment, Telehealth End User: Women, Healthcare Providers, Family Members, Caregivers Delivery Mode: Online Counseling, Medication Administration, Group Therapy, Workshops |
| Companies Covered | Supernus Pharmaceuticals, Sage Therapeutics, Eli Lilly and Company, Pfizer, GlaxoSmithKline, Novartis, Merck, Bausch Health Companies, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Partum Depression Market Strategic Shifts & Innovations
Telehealth-enabled psychiatric access is compressing geographic barriers while novel therapeutic mechanisms are forcing infrastructure reinvestment across outpatient and home care channels.
Remote patient monitoring platforms with integrated mood tracking and infant development screening are expanding into post-partum depression management workflows. OB-GYN practices and pediatric clinics are adopting these tools at accelerating rates to identify at-risk mothers before symptom escalation. The technology is expanding into traditional primary care settings that previously lacked psychiatric referral infrastructure.
EMA's MDR framework for maternal mental health therapeutics is tightening clinical evidence requirements for neuroactive steroid approvals. European manufacturers must now submit extended pharmacovigilance data and real-world pregnancy registries. Smaller developers without existing women's health portfolios are retreating from parallel EMA filings, concentrating European market entry among established maternal health players.
Direct-to-employer contracting for perinatal mental health bundles is displacing traditional payer-channel dominance in the United States. Self-insured employers are purchasing integrated navigation, telepsychiatry, and care coordination services from specialized vendors. This procurement evolution is most visible among technology and professional services firms with concentrated female workforces in California, New York, and Massachusetts metropolitan areas.
Post-Partum Depression Market Segmentation
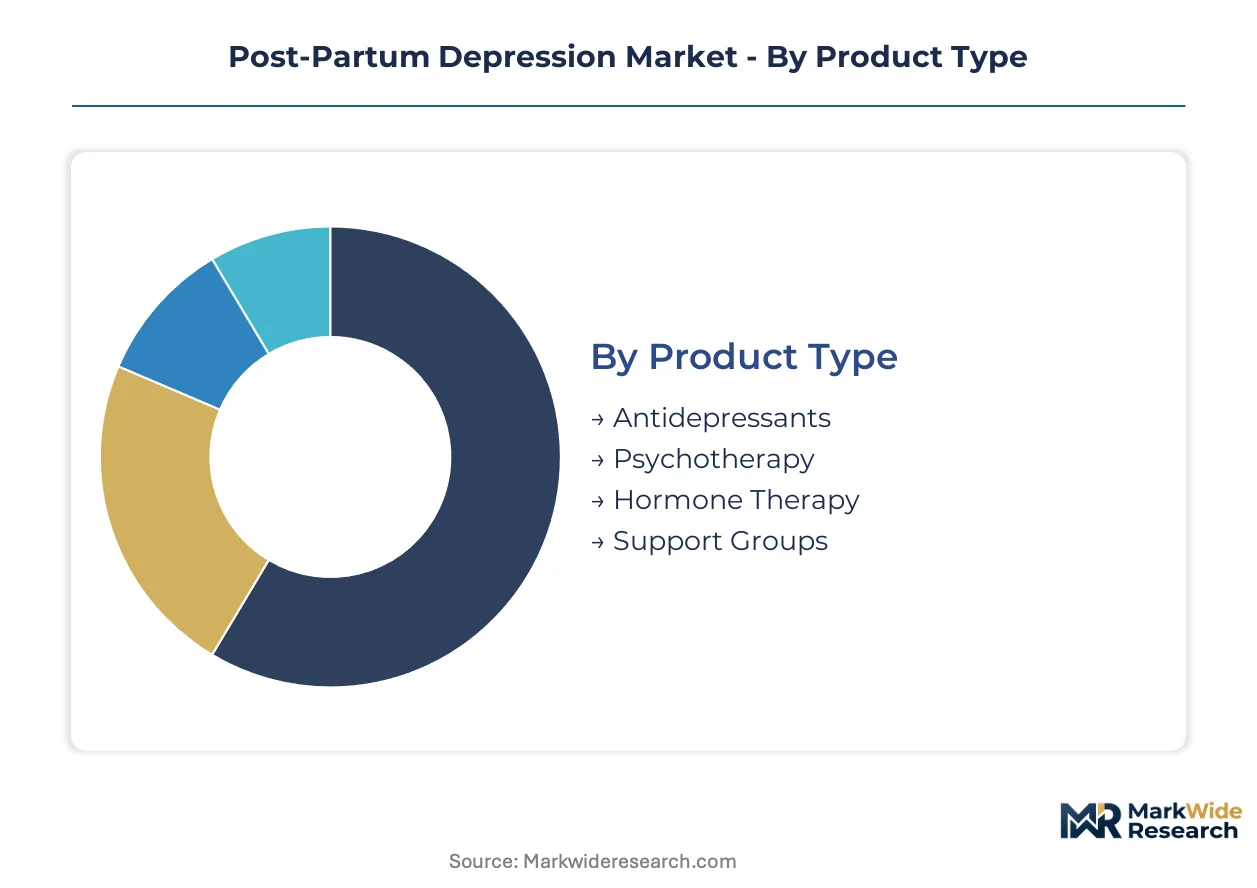
Post-partum depression treatment modalities fragment across therapeutic mechanisms, care settings, and delivery infrastructure. Segmentation reveals where capital deployment concentrates and which channels reshape patient access economics.
Product Type:
Capital intensity varies sharply across therapeutic categories, with neuroactive steroid manufacturing demanding specialized synthesis infrastructure that antidepressant generics avoid.
- Antidepressants:Serotonin reuptake inhibitors and norepinephrine-dopamine modulators constitute the volume foundation. Selective serotonin reuptake inhibitors dominate prescriptions in the United States where primary care physicians manage mild-to-moderate cases without psychiatric referral.
- Psychotherapy:Cognitive behavioral therapy and interpersonal psychotherapy require licensed clinician hours rather than manufacturing capex. Demand clusters in urban United States corridors where perinatal psychiatric specialists concentrate, though telehealth platforms now extend reach into rural counties.
- Hormone Therapy:Allopregnanolone-based interventions command premium facility infrastructure.
- Support Groups:Peer-led community programs operate at minimal fixed cost.
Antidepressants absorb the bulk of installed capacity; psychotherapy is expanding most quickly.
Application:
Site-of-care selection determines reimbursement rates, patient throughput, and regulatory burden simultaneously.
- Home Care:Remote patient monitoring with mood tracking apps and asynchronous clinician messaging eliminates facility overhead. United States Medicaid expansion for perinatal mental health services accelerates adoption in states with rural access gaps.
- Outpatient Care:Hospital-based infusion centers for brexanolone capture the highest reimbursement per episode. OB-GYN practices in California and New York metropolitan areas are adding psychiatric co-location to capture this margin pool.
- Inpatient Treatment:Psychiatric admission for severe post-partum depression with suicidal ideation requires specialized mother-baby unit infrastructure.
- Telehealth:Synchronous video platforms collapse geographic barriers to psychiatric access.
Outpatient care retains the deepest margin pools; telehealth is gaining share fastest.
End User:
Decision-making authority and payment responsibility split across patient, provider, and family stakeholders with divergent price sensitivities.
- Women:Post-partum patients themselves drive initial symptom recognition and treatment-seeking behavior. United States employer-sponsored perinatal benefits now bypass traditional payer prior authorization for this segment.
- Healthcare Providers:OB-GYNs and pediatricians control referral pathways and prescription authority. Screening mandates in several United States states compel systematic identification during well-baby visits.
- Family Members:Partners and extended family influence care initiation and adherence support.
- Caregivers:Post-partum doulas and lactation consultants provide frontline observation.
Healthcare providers anchor prescription volume; women as direct beneficiaries are climbing the fastest as self-advocacy tools proliferate.
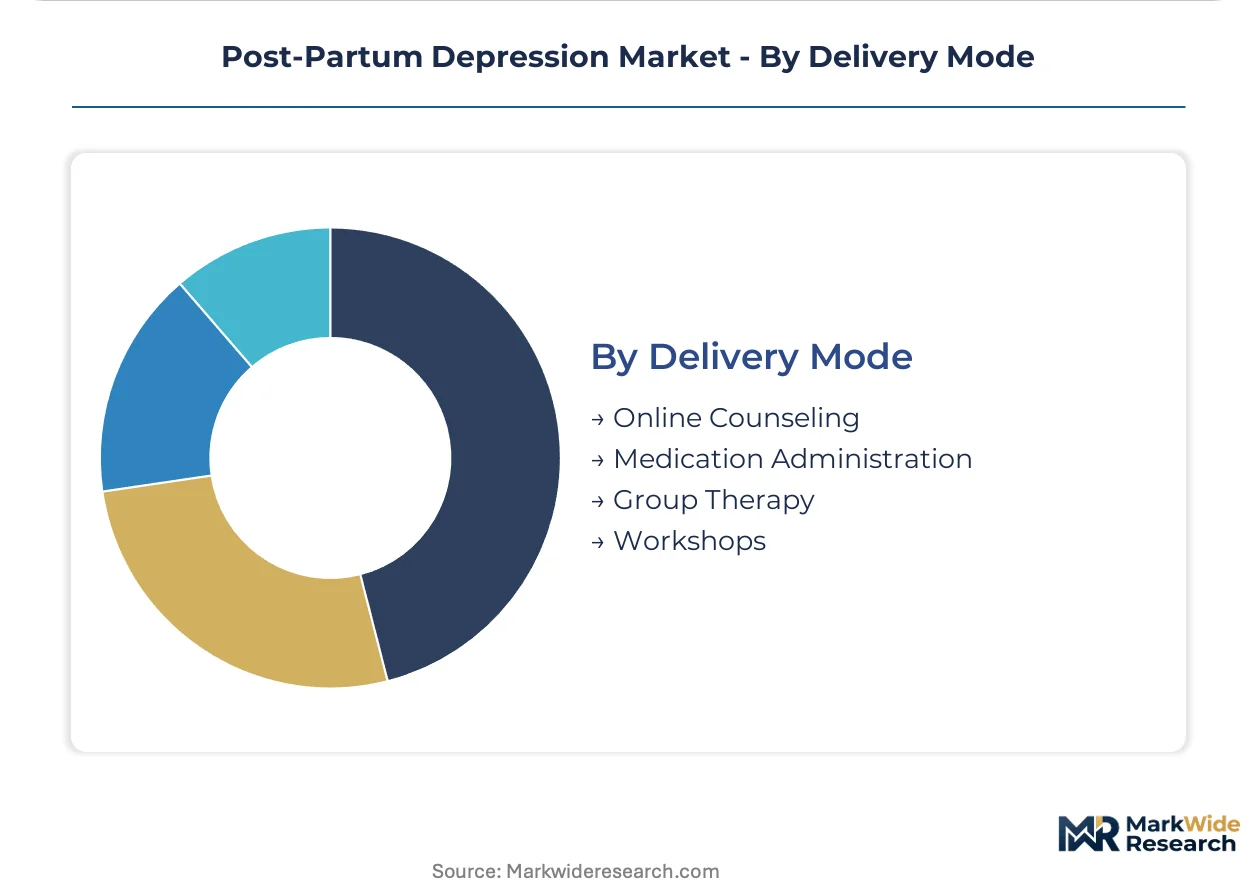
Delivery Mode:
Channel economics diverge between platform-based scaling and labor-intensive service delivery.
- Online Counseling:Text-based and video psychiatric sessions operate on subscription or per-visit pricing. HIPAA-compliant platform architecture imposes technical friction that favors established telehealth vendors with compliance infrastructure.
- Medication Administration:Oral antidepressant dispensing through retail pharmacy channels achieves lowest per-dose cost. Intravenous brexanolone requires certified facility administration that limits addressable geography.
- Group Therapy:Facilitated peer sessions spread clinician hours across multiple patients.
- Workshops:Single-session educational interventions on maternal mental health literacy.
Medication administration captures the largest patient volume; online counseling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuroactive steroid manufacturing infrastructure anchors geographic concentration in the United States, where FDA approval pathways and maternal mental health reimbursement policies have created the deepest market formation. Facility-based administration requirements for intravenous therapies concentrate clinical trial activity and commercial infrastructure around specific metropolitan clusters.
United States
Medicaid expansion for perinatal psychiatric services and state-level screening mandates drive demand concentration in California, New York, and Massachusetts. FDA REMS requirements for brexanolone lock distribution into certified healthcare facilities, creating site-of-care economics that favor hospital outpatient departments. The Greater Boston corridor hosts the dominant neuroactive steroid development cluster, with specialized infusion centers concentrating in urban academic medical centers.
Germany
Reimbursement parity for maternal mental health services under statutory health insurance accelerates adoption of telepsychiatry platforms. EMA's MDR framework for maternal therapeutics demands extended pharmacovigilance data that extends development timelines. The Munich-Stuttgart corridor concentrates perinatal psychiatric specialist training programs that supply clinical expertise across Central Europe.
United Kingdom
NHS perinatal mental health community service expansion targets 30% coverage of expectant mothers by specialized teams. NICE guidelines for postnatal depression prioritize psychological therapies as first-line intervention, shaping prescription patterns for antidepressant pharmacotherapy. London and the Southeast concentrate digital therapeutic development studios that serve NHS procurement frameworks.
Canada
Provincial health authority funding for maternal mental health navigation services expands access beyond traditional psychiatric referral pathways. Health Canada approval pathways for neuroactive steroids follow FDA precedent with additional pregnancy registry requirements. Ontario and Quebec metropolitan areas concentrate telehealth platform vendors serving provincial single-payer reimbursement systems.
Australia
Medicare Benefits Schedule item numbers for perinatal mental health consultations remove cost barriers to psychiatric access in rural regions. TGA approval processes for novel maternal therapeutics require Australian-specific clinical evidence that delays market entry. Sydney and Melbourne host the dominant telehealth infrastructure serving dispersed populations across the continent.
Post-Partum Depression Market Key Industry Players
Strategic partnerships dominate the current landscape as pharmaceutical developers align with telehealth platform vendors to bypass facility-based distribution constraints. The market structure concentrates around three distinct tiers: large-cap psychiatric drug manufacturers with primary care networks, mid-cap neuroactive steroid specialists with REMS infrastructure, and digital therapeutic developers with HIPAA-compliant platform architecture. Portfolio diversification into maternal mental health navigation services represents the second dominant competitive move, particularly among employers and payers seeking integrated care bundles.
Within the neuroactive steroid development tier, Sage Therapeutics occupies the anchor position exemplifying mechanism-of-action specialization. Among large-cap psychiatric drug manufacturers, Eli Lilly and Company and Pfizer represent the established primary care channel dominance that antidepressant volume requires. These three companies illustrate the competitive tension between novel therapeutic infrastructure investment and traditional prescription channel scale.
| Leading Market Players |
|---|
| Supernus Pharmaceuticals |
| Sage Therapeutics |
| Eli Lilly and Company |
| Pfizer |
| GlaxoSmithKline |
| Novartis |
| Merck |
| Bausch Health Companies |
| Teva Pharmaceutical Industries |
| Others |
Cost & Logistics Intelligence
Venture-backed telehealth platforms rolled up by private equity specialists now anchor supply-side financing, tightening pricing discipline across digital therapeutic channels while forcing facility-based neuroactive steroid providers to absorb REMS compliance overhead into bundled service rates.
Pricing Analysis
Warranty and monitoring bundles separate certified infusion center pricing from unbundled telepsychiatry subscriptions that exclude crisis intervention guarantees. Three-tier pricing structure across premium facility-administered neuroactive steroids, standard antidepressant pharmacy dispensing, and economy peer-support platforms dominates the United States market. Price differentiation hinges on FDA REMS certification tier and geographic delivery cost to rural catchments. Cost compression in the telehealth tier is intensifying because platform vendors compete for employer-sponsored perinatal benefit contracts. Self-insured employers show lowest price sensitivity; Medicaid-managed care plans demonstrate highest.
Supply Chain Analysis
Domestic-content mandates for pharmaceutical manufacturing under the FDA's quality agreements are reshaping active pharmaceutical ingredient sourcing toward United States and European contract manufacturers. Neuroactive steroid synthesis concentrates in the United States, Switzerland, and Ireland, drawing from specialized steroid precursor feedstocks and GMP-certified bioreactor infrastructure. Supply chain risk centers on single-source vulnerability for allopregnanolone analog production. Distribution runs through hospital outpatient departments for infusion therapies and retail pharmacy networks for oral antidepressants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
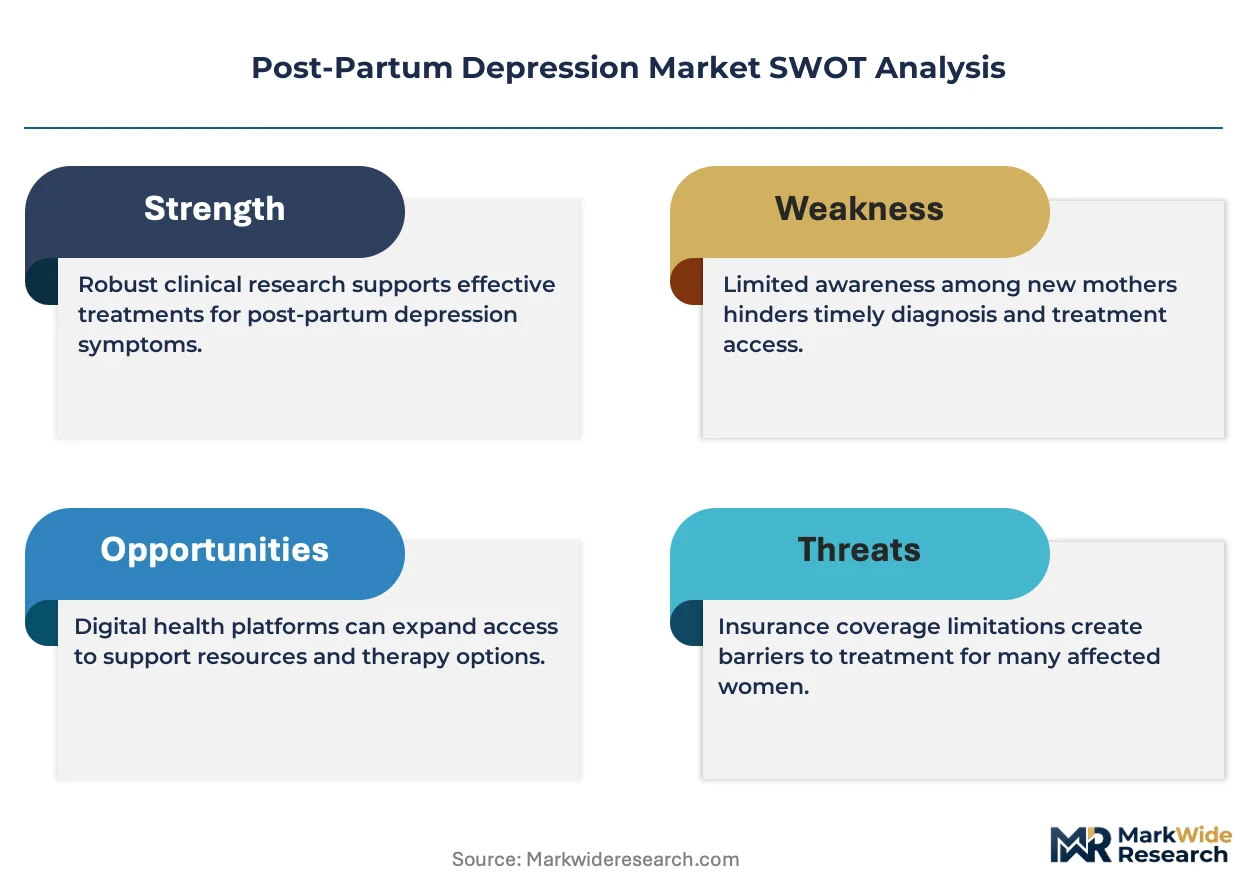
This market reads as a cost-of-compliance story where FDA REMS infrastructure requirements create a barrier-to-entry moat that protects Sage Therapeutics' certified facility network from price-competitive generic entrants.
For Market Incumbents: To counter oral neuroactive steroid formulations that threaten facility-based revenue, expand telehealth platform partnerships while deepening REMS-certified site networks in Medicaid expansion states. Prioritize backward integration into remote patient monitoring technology to capture home care margin pools before oral therapies launch. For New Entrants and Emerging Players: Digital therapeutic platforms with FDA breakthrough device designation offer the most penetrable wedge into employer-sponsored perinatal benefits, bypassing traditional payer prior authorization. Target rural United States counties with psychiatric specialist shortages. Pursue direct-to-employer contracting rather than formulary access battles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap telehealth vendors with HIPAA-compliant infrastructure in California and New York metropolitan areas, where maternal mental health screening mandates ensure demand visibility. Watch CMS reimbursement decisions for digital therapeutic billing codes as the inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Expansion | Certified facility networks lock in brexanolone distribution exclusivity against oral competitors. |
| Digital Therapeutic FDA Submission | Breakthrough device designation accelerates cognitive behavioral therapy app market access. |
| Telehealth Platform Integration | Synchronous video capabilities collapse geographic barriers to psychiatric access in rural regions. |
| Employer Direct Contracting | Self-insured perinatal benefit bundles bypass traditional payer prior authorization friction. |
| Oral Neuroactive Steroid Pipeline | SAGE-217 development eliminates infusion center requirements, expanding addressable populations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with reproductive psychiatrists, REMS program administrators, telehealth platform executives, and employer benefits directors. FDA REMS documentation, CMS reimbursement rulings, state Medicaid expansion records, and clinical trial registry entries provided validation layers. Bottom-up patient volume estimates triangulated against top-down pharmaceutical revenue disclosures.
Granularity-level modeling treated therapeutic mechanism, site-of-care setting, and payer type as fully specified dimensions across the projection horizon. Neuroactive steroid manufacturing capacity, telehealth platform user acquisition costs, and perinatal screening mandate implementation timelines fed the analytical framework. CAGRs derived from segment-level volume trajectories weighted by reimbursement rate differentials.
Several conditions sit outside the modeled scope, including pipeline failure rates for oral neuroactive steroids and state-level licensing reciprocity changes for interstate telepsychiatry. Forecasts reflect documented assumptions about REMS program continuity and CMS digital therapeutic code adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
US Behavioral Health Market
Mental Health Services
Mental Health Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Schizophrenia Market
Mental Health Services
US Workplace Stress Management Market