
 US Psychiatry Clinic Market | 2026-2036
US Psychiatry Clinic Market Size, Share, and Industry Trends Forecast 2026-2036
US Psychiatry Clinic Market Intelligence
Psychiatrist workforce shortages across the American South and rural Midwest is realigning how national clinic networks deploy telepsychiatry capacity. Universal Health Services anchors inpatient psychiatric bed availability across multiple states through its acute-care hospital portfolio. Acadia Healthcare specializes in residential and partial hospitalization programs for substance use and co-occurring disorders. Mayo Clinic sustains premium referral volumes through integrated psychiatric-neurology research protocols.
A psychiatry clinic delivers outpatient and intensive mental health services through licensed psychiatrists, psychiatric nurse practitioners, and specialized therapists using diagnostic frameworks such as DSM-5-TR criteria and structured clinical interviews. These facilities manage medication regimens, provide psychotherapy modalities, and coordinate crisis intervention for conditions spanning mood disorders, psychotic disorders, anxiety spectrum conditions, and neurodevelopmental presentations. Telepsychiatry now leads service-type expansion as state licensure compacts reduce cross-border practice barriers, while medication management retains the deepest margin pools due to recurring visit cadence and pharmacy integration. Insurance-based payment models dominate transaction volume, though private-pay concierge psychiatry represents the fastest-growing revenue channel among affluent urban cohorts.
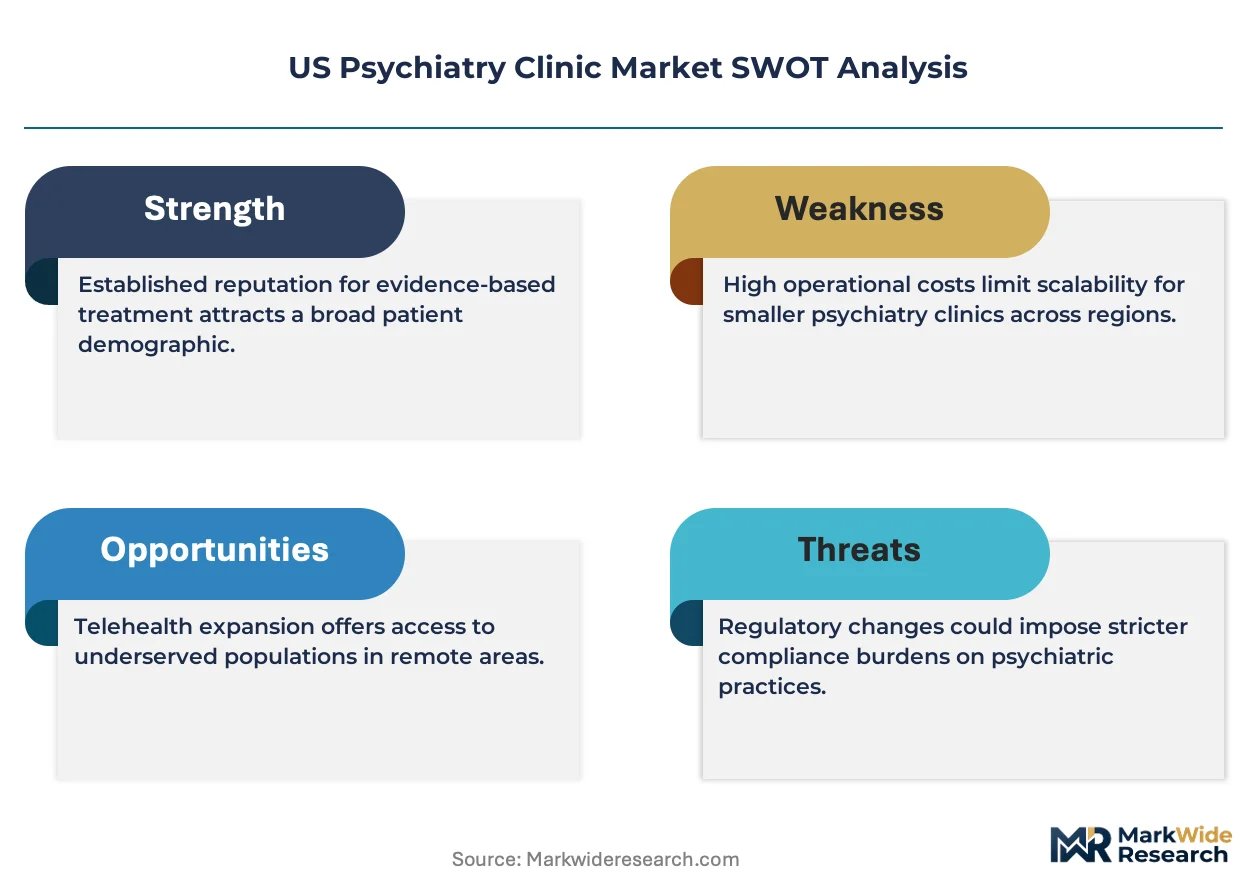
FDA oversight of digital therapeutics and psychedelic-assisted therapy trials shapes which innovative modalities clinics may legally offer, while CMS reimbursement determinations directly determine telehealth service viability for Medicare beneficiaries. HIPAA compliance requirements and state-level scope-of-practice laws for nurse practitioners further constrain operational models and geographic expansion feasibility. Stakeholders must monitor evolving DEA scheduling decisions for psilocybin and MDMA alongside interstate licensure compact ratification to anticipate which service lines warrant capital deployment.
Market Dynamics
Telepsychiatry licensure compacts are dissolving state-by-state practice barriers, forcing clinic networks to reconfigure their provider deployment models around interstate credential reciprocity rather than physical facility footprints.
Growth Catalysts
- CMS Telehealth Reimbursement:Medicare parity payments for virtual psychiatric visits sustain clinic revenue models beyond pandemic-era waivers. Rural health clinics leverage this to access specialist psychiatrists previously unavailable in their service areas.
- Employer Behavioral Health Mandates:Large self-insured employers are expanding carve-in psychiatric benefits. Clinic networks secure direct contracts with benefits administrators, bypassing traditional payer intermediaries.
- California Provider Network Gaps:Concentrated demand in Los Angeles and San Francisco metro areas exceeds psychiatrist supply. Telepsychiatry platforms capture overflow volume from brick-and-mortar capacity constraints.
Market Restraints
- DEA Scheduling Friction:Controlled substance prescribing via telehealth faces renewed in-person examination requirements. Buprenorphine and stimulant medication management encounters compliance cost escalation.
- Malpractice Insurance Concentration:Three national carriers dominate psychiatric professional liability coverage. Premium spikes in Florida and Texas constrain independent practice sustainability.
- EHR Interoperability Limitations:Behavioral health data sharing exclusions in HIPAA hinder care coordination with primary care networks. Information blocking penalties remain narrowly enforced.
Strategic Opportunities
- Psychedelic-Assisted Therapy Trials:FDA breakthrough therapy designations for MDMA and psilocybin create first-mover clinic certification opportunities. Specialized training programs in Oregon and Colorado establish regional competency centers.
- Nurse Practitioner Scope Expansion:Full-practice authority legislation in Arizona and Idaho enables non-physician prescriptive autonomy. Clinic operators reduce physician FTE requirements in compliant states.
- Digital Therapeutics Integration:FDA-cleared prescription software for insomnia and substance use disorder complements medication protocols. Payers increasingly bundle DTx reimbursement with psychiatric visit codes.
Industry Challenges
- Psychiatrist Workforce Pipeline:Residency match rates for psychiatry lag population growth. Academic medical centers struggle to expand training slots despite clinical demand signals.
- Prior Authorization Complexity:Commercial payers impose step-therapy requirements for branded psychiatric medications. Administrative burden consumes 12-15 FTE hours per clinician weekly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Psychiatry Clinic Market |
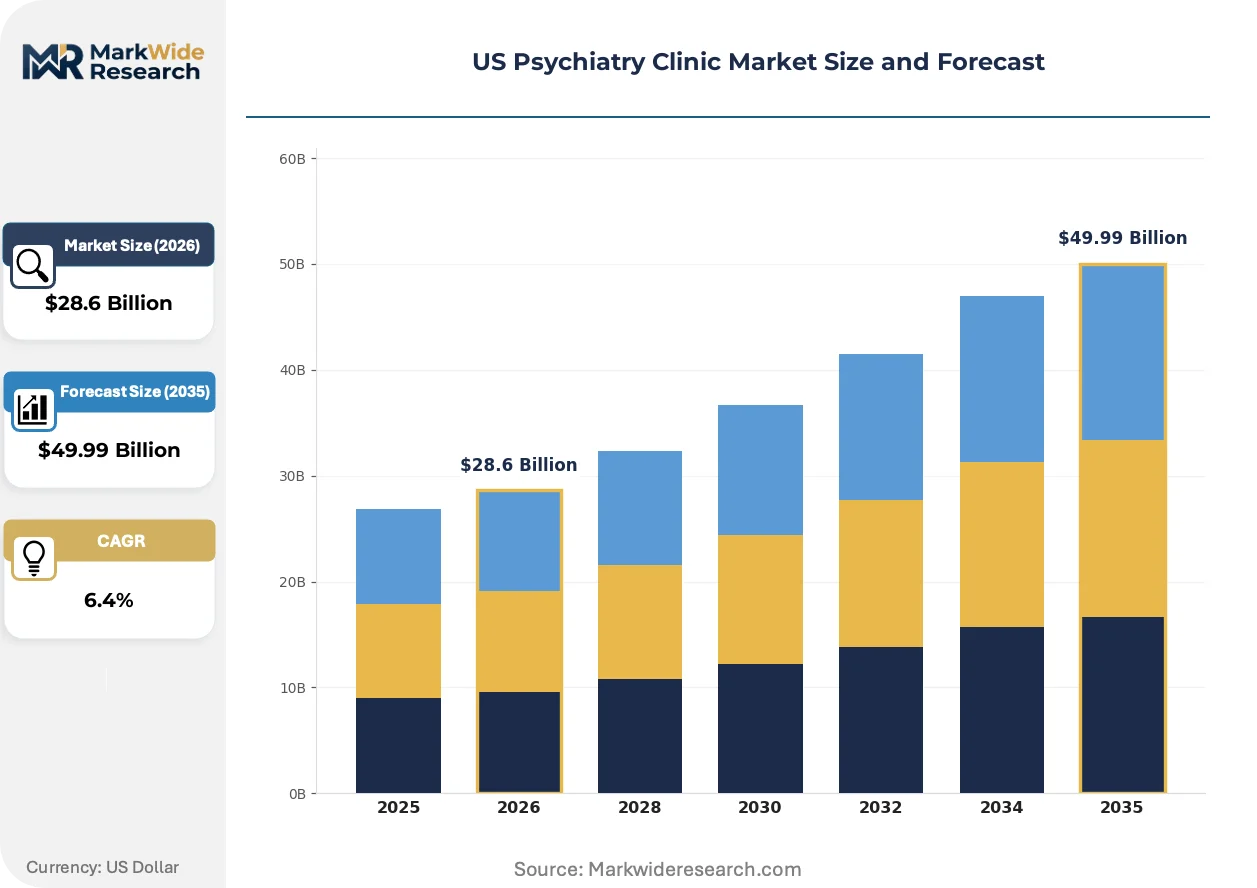
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Individual Therapy, Group Therapy, Telepsychiatry, Medication Management End User: Adults, Adolescents, Seniors, Children Payment Model: Private Pay, Insurance-Based, Government Funded, Out-of-Pocket Treatment Approach: Cognitive Behavioral Therapy, Dialectical Behavior Therapy, Psychodynamic Therapy, Mindfulness-Based Therapy |
| Companies Covered | UCSF Health, Bellevue Hospital, Universal Health Services, Menninger Clinic, Manhattan Psychiatric Center, Acadia Healthcare, Langley Porter Psychiatric Hospital, Tucker Psychiatric Clinic, Mayo Clinic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Psychiatry Clinic Market Strategic Shifts & Innovations
Artificial intelligence diagnostic tools are penetrating clinical workflows, reshaping how psychiatrists allocate time between assessment and therapeutic intervention. Three distinct vectors dominate current innovation patterns.
Natural language processing software is absorbing routine documentation burden from psychiatric encounters. Community mental health centers in Texas and Georgia deploy ambient listening tools to auto-generate progress notes. This technology is compressing clinician administrative time by approximately one-third, enabling expanded patient panels without proportional staffing growth.
FDA digital therapeutics guidance finalized in 2022 establishes predicate device pathways for software-based interventions. The framework permits 510(k) clearance for algorithms treating specific DSM-5-TR diagnoses. Insurers in Massachusetts and Washington now reimburse FDA-cleared DTx as adjunctive to standard pharmacotherapy, creating new revenue line items for early-adopting clinics.
Concierge psychiatry membership models are displacing traditional fee-for-service arrangements in affluent urban corridors. Patients in Manhattan, Miami, and San Francisco prepay annual retainers for guaranteed appointment access and direct physician communication channels. This behavioral shift concentrates premium revenue with practices willing to cap panel size and exit insurance networks entirely.
US Psychiatry Clinic Market Segmentation
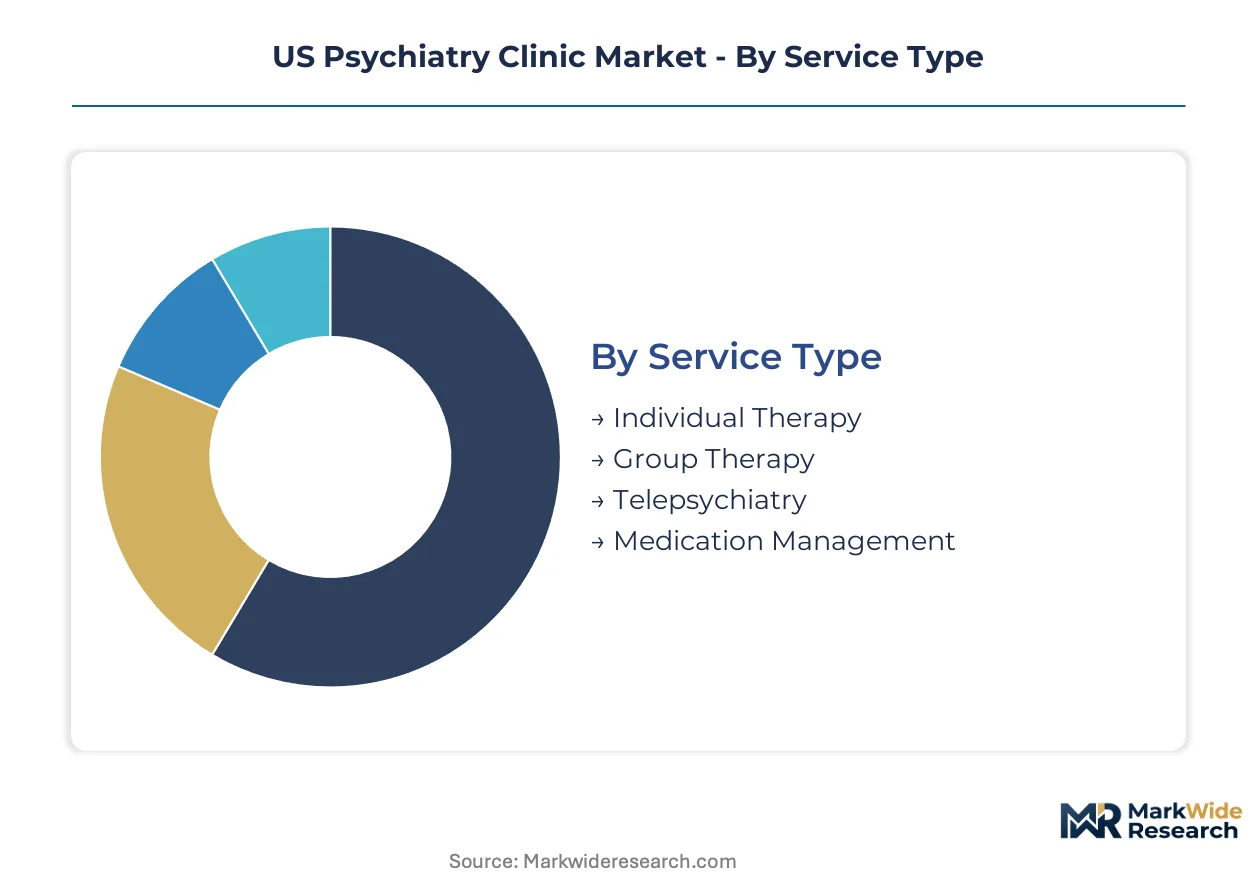
Psychiatry clinic operators configure service portfolios around reimbursement pathways and workforce constraints rather than clinical preference alone. Segment boundaries shift as CMS telehealth rules and state licensure compacts redraw operational feasibility.
Service Type:
Telepsychiatry encounters face DEA controlled-substance prescribing restrictions that exempt medication management and group therapy formats from the Ryan Haight Act's in-person examination requirements.
- Telepsychiatry:Video-based psychiatric consultations leverage interstate licensure compacts to deploy psychiatrists across state lines. Demand concentrates in rural Texas and Florida counties where psychiatrist density falls below one per 30,000 residents, with CMS Medicare parity payments sustaining rural health clinic partnerships.
- Medication Management:Structured pharmacotherapy follow-up visits with standardized rating scales and pharmacy integration. California's Los Angeles and San Francisco metro areas absorb the deepest volume due to commercial payer density and employer-sponsored behavioral health carve-ins.
- Individual Therapy:One-on-one psychotherapy sessions delivered by psychiatrists or licensed therapists.
- Group Therapy:Facilitated multi-patient sessions for substance use disorder and trauma cohorts.
Leading the category by volume: Medication Management. Expanding most quickly: Telepsychiatry.
End User:
Patient age cohorts determine service intensity patterns and prior authorization complexity, with pediatric and geriatric segments triggering additional state-mandated reporting requirements.
- Adults:Working-age patients aged 18-64 presenting mood, anxiety, and substance use conditions. Employer-sponsored benefits drive volume concentration in Texas and Florida corporate corridors, where direct contracts with benefits administrators bypass traditional payer intermediaries.
- Seniors:Medicare-eligible patients requiring dementia care coordination and polypharmacy management. Florida's retiree-dense counties generate disproportionate demand for integrated psychiatric-neurology protocols.
- Adolescents:Patients aged 12-17 requiring parental consent frameworks and school-based care coordination.
- Children:Patients under 12 with neurodevelopmental and early-onset behavioral health presentations.
Dominating transaction volume: Adults. Gaining share fastest: Seniors.
Payment Model:
Revenue stability varies sharply across payment structures, with government-funded segments exposing clinics to state budget cycles and prior authorization backlogs.
- Insurance-Based:Commercial payer contracts with fee-for-service and value-based arrangements. California and Massachusetts markets absorb the deepest concentration due to employer mandate density and narrow network psychiatric carve-ins.
- Private Pay:Direct patient payment including concierge retainers and out-of-network reimbursement. Manhattan, Miami, and San Francisco corridors sustain premium pricing for guaranteed access models.
- Government Funded:Medicaid and Medicare reimbursement with state-specific rate schedules.
- Out-of-Pocket:Patient self-pay for non-covered or elective services.
Highest revenue stability: Insurance-Based. Steepest expansion trajectory: Private Pay.
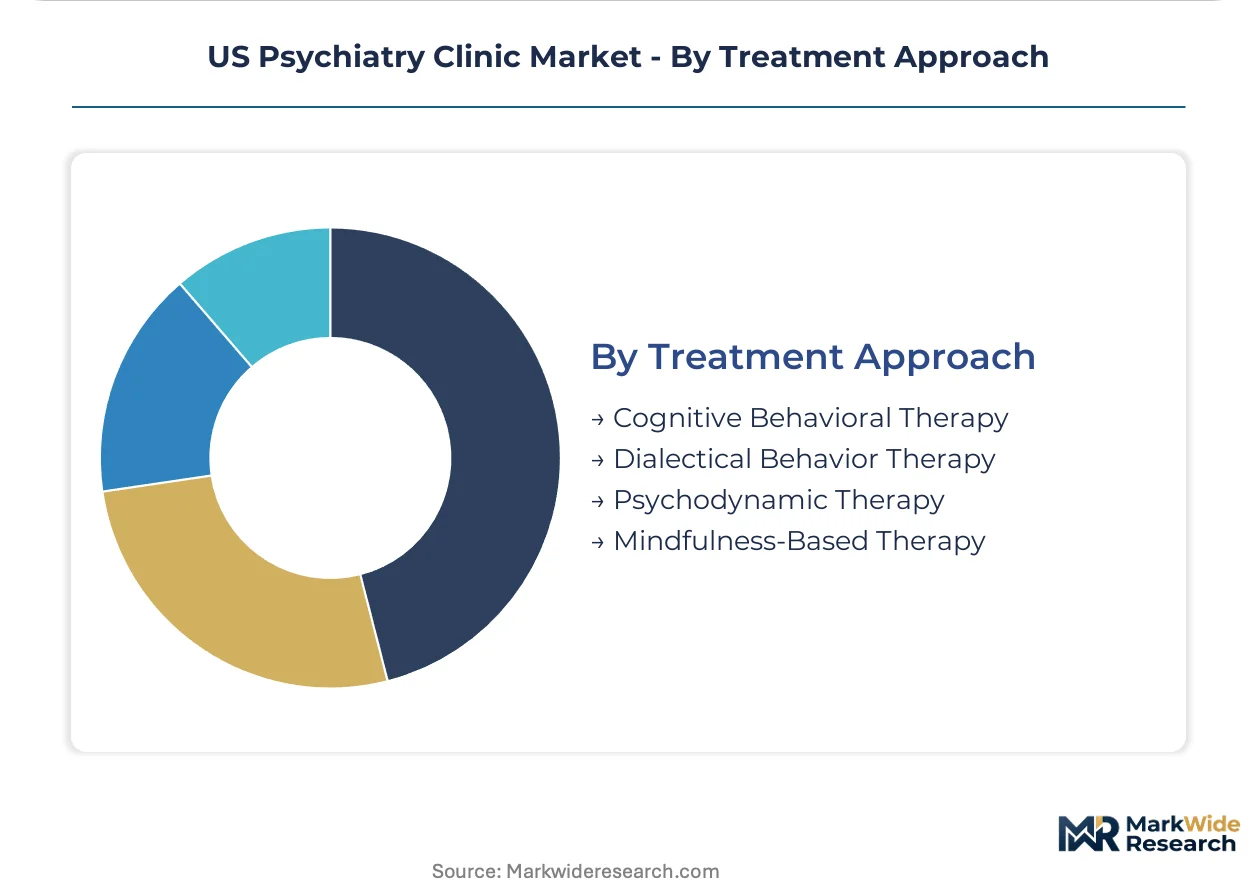
Treatment Approach:
Modalities diverge in training certification requirements and session reimbursement rates, with FDA digital therapeutics guidance creating new predicate pathways for technology-augmented formats.
- Cognitive Behavioral Therapy:Structured, time-limited psychotherapy targeting maladaptive thought patterns. FDA-cleared digital therapeutics for insomnia and substance use disorder in Massachusetts and Washington now bundle CBT protocols with psychiatric visit codes.
- Dialectical Behavior Therapy:Skills-based treatment for borderline personality disorder and self-harm behaviors. Residential programs in Oregon and Colorado anchor specialized certification centers.
- Psychodynamic Therapy:Long-term exploratory psychotherapy with less standardized reimbursement.
- Mindfulness-Based Therapy:Meditative and acceptance-oriented interventions for anxiety and depression.
Widest payer coverage: Cognitive Behavioral Therapy. Climbing the fastest: Dialectical Behavior Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psychiatrist density and Medicaid reimbursement rates anchor geographic deployment decisions across US sub-regions. State-level scope-of-practice laws and telehealth parity statutes determine where clinic networks concentrate capital.
California
Los Angeles and San Francisco metro areas absorb the deepest commercial payer volume through employer-sponsored behavioral health carve-ins. The state's Department of Health Care Services mandates Medi-Cal managed care plans to meet network adequacy standards for psychiatric services. Kaiser Permanente's integrated delivery system in Oakland anchors value-based psychiatric care coordination with primary care networks.
Texas
Rural counties below one psychiatrist per 30,000 residents drive telepsychiatry platform expansion through CMS Medicare parity payments. The Texas Medical Board maintains full practice authority for psychiatric nurse practitioners, reducing physician FTE requirements. Houston's Texas Medical Center corridor concentrates academic psychiatry training programs and research trial infrastructure.
Florida
Retiree-dense counties generate disproportionate demand for dementia care coordination and polypharmacy management under Medicare Advantage contracts. The Florida Board of Medicine imposes heightened malpractice insurance requirements that constrain independent practice sustainability. Miami's concierge psychiatry market sustains premium private-pay retainers for guaranteed appointment access.
New York Metro
Manhattan's density of self-insured employers supports direct contracts between clinic networks and benefits administrators. The New York State Office of Mental Health regulates 988 crisis hotline integration with outpatient psychiatric services. Bellevue Hospital's emergency psychiatric services anchor public-sector capacity in the five-borough catchment area.
Massachusetts
MassHealth's behavioral health integration mandates drive psychiatric-primary care co-location in community health centers. The state's Center for Health Information and Analysis enforces network adequacy reporting for commercial insurers. Greater Boston's academic medical centers anchor FDA digital therapeutics trial recruitment for insomnia and substance use disorder protocols.
US Psychiatry Clinic Market Key Industry Players
Global majors compete with regional champions across service-line specialization and payer contract density. The market structures around three tiers: national hospital systems with inpatient psychiatric bed portfolios, regional outpatient clinic networks with telepsychiatry platforms, and specialized residential programs for substance use disorders. Strategic archetypes include integrated health systems leveraging primary care referral pipelines, pure-play behavioral health operators scaling through acquisition, and academic medical centers anchoring research-driven subspecialty services. Dominant competitive moves encompass direct-to-employer contract bypass of traditional payers and interstate licensure compact deployment to access rural psychiatrist shortage areas.
Among national hospital system operators, Universal Health Services and Mayo Clinic exemplify divergent strategic positions. Universal Health Services anchors acute-care psychiatric bed availability across multiple states through its hospital portfolio concentration. Mayo Clinic occupies a research-premium position through integrated psychiatric-neurology protocols that sustain high-value referral volumes. Acadia Healthcare represents the pure-play behavioral health archetype, specializing in residential and partial hospitalization programming for co-occurring disorders.
| Leading Market Players |
|---|
| UCSF Health |
| Bellevue Hospital |
| Universal Health Services |
| Menninger Clinic |
| Manhattan Psychiatric Center |
| Acadia Healthcare |
| Langley Porter Psychiatric Hospital |
| Tucker Psychiatric Clinic |
| Mayo Clinic |
| Others |
Cost & Logistics Intelligence
Employer-sponsored benefits administrators in California, Texas, and Florida concentrate purchasing power through direct contracts with clinic networks, locking in fee-for-service rates that diverge sharply from concierge private-pay models. This buyer concentration forces pricing stratification across insurance-based, government-funded, and out-of-pocket segments.
Pricing Analysis
Service bundling separates comprehensive medication management with pharmacy integration from unbundled telepsychiatry consultations lacking controlled-substance prescribing privileges. Three-tier pricing structure across premium concierge retainers, standard commercial insurance rates, and economy Medicaid schedules reflects psychiatrist credential tier and appointment access guarantees. Cost compression in Medicaid-reimbursed services intensifies because state rate schedules lag workforce inflation. Employer-sponsored segments exhibit lowest price sensitivity; independent practitioners in rural markets face highest.
Supply Chain Analysis
Refurbishment flows for psychiatric EHR systems and telehealth platforms concentrate technical support and hardware redeployment through third-party service networks. Clinical workforce supply draws from US psychiatry residency programs, Caribbean medical school pipelines, and nurse practitioner training expansions in Arizona and Idaho. Psychotropic API manufacturing rests on Indian and Chinese pharmaceutical suppliers. Single-source vulnerability in DEA-licensed controlled-substance distribution creates regulatory chokepoint exposure. Distribution runs through integrated health system formularies, independent pharmacy networks, and direct-to-patient mail-order channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Psychiatrist workforce shortages function as the binding capacity constraint, propping pricing power for credentialed providers while forcing operational redesign around nurse practitioner scope expansion and telepsychiatry deployment.
For Market Incumbents: Anchor inpatient bed availability through acute-care hospital partnerships while consolidating telepsychiatry platforms to capture rural overflow demand. Defensive moves require locking in direct employer contracts before benefits administrators expand vendor panels, and securing DEA registrations for controlled-substance prescribing amid tightening telehealth examination rules. Vertical integration into pharmacy benefit management reduces reimbursement leakage. For New Entrants and Emerging Players: Launch via telepsychiatry-first models targeting rural Texas and Florida counties where psychiatrist density falls below critical thresholds. White-space opportunities concentrate in concierge membership models for affluent urban corridors and FDA digital therapeutics certification for insomnia and substance use disorder protocols. Go-to-market positioning should emphasize guaranteed appointment access and direct physician communication channels unavailable through insurance networks. For Investors and Strategic Acquirers: The window for entry favors platforms with interstate licensure compact deployment capabilities and established Medicare Advantage contracts in retiree-dense geographies. Long-term viability hinges on exposure to workforce-constrained markets with pricing power rather than Medicaid-dependent volume plays. Monitor DEA scheduling decisions for psilocybin and MDMA as inflection indicators for psychedelic-assisted therapy certification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Interstate Licensure Compact Deployment | CMS Medicare parity payments sustain rural health clinic partnerships across state lines. |
| FDA Digital Therapeutics Certification | 510(k) clearance for insomnia algorithms creates bundled reimbursement with psychiatric visit codes. |
| Direct Employer Contracting | Self-insured benefits administrators in California bypass traditional payer intermediaries. |
| Nurse Practitioner Scope Expansion | Full-practice authority legislation in Arizona and Idaho reduces physician FTE requirements. |
| Psychedelic-Assisted Therapy Training | Breakthrough therapy designations for MDMA establish regional competency centers in Oregon and Colorado. |
Research Approach
Independent corroboration across psychiatric clinic operators, benefits administrators, and state medical board officials underwrites the qualitative findings. Primary interviews engaged psychiatric practice executives, telepsychiatry platform operators, hospital system behavioral health directors, and Medicare Advantage plan managers. Secondary validation drew from FDA digital therapeutics guidance documents, CMS telehealth reimbursement rules, state licensure compact ratification records, and DEA controlled-substance prescribing regulations. Bottom-up clinic capacity estimates triangulated against top-down employer benefits spending data.
Comparable historical reference periods anchored the forecast window to pre-pandemic baselines and pandemic-era waiver phases. The analytical framework modeled service type segmentation, payment model distribution, and end-user age cohorts alongside state-level scope-of-practice variations. CAGRs derived from psychiatrist workforce pipeline projections, employer behavioral health mandate expansion rates, and telehealth parity statute adoption patterns. Forecast inputs incorporated residency match rates, interstate licensure compact participation, and DEA scheduling decision timelines.
The model assumes a particular technology adoption path; alternative pathways for AI diagnostic tools and ambient listening documentation would alter the outlook. Forecasts reflect assumptions about FDA digital therapeutics clearance velocity and CMS telehealth reimbursement durability. Practitioners should monitor DEA controlled-substance prescribing rule changes and state nurse practitioner authority legislation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Mental Health Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
North America Maternal Mental Health Market