
 Panic Attack Treatment Market | 2026-2036
Panic Attack Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Panic Attack Treatment Market Analytics
Telehealth distribution is reconfiguring how patients access panic disorder care, bypassing traditional psychiatric referral bottlenecks. Pfizer Inc. leverages its established primary care detailing network to sustain antidepressant prescriptions for panic indications. Eli Lilly and Company anchors its position through long-acting formulations that reduce discontinuation rates in chronic users. Teva Pharmaceutical Industries Ltd. competes aggressively in the generics space, eroding branded pricing for selective serotonin reuptake inhibitors.
Panic attack treatment encompasses pharmacological and non-pharmacological interventions targeting acute sympathetic nervous system hyperarousal, with selective serotonin reuptake inhibitors and cognitive behavioral therapy representing first-line modalities that modulate serotonergic neurotransmission and threat-appraisal pathways. Medications dominate current revenue flows due to reimbursement familiarity, though teletherapy and mobile apps represent the fastest-expanding delivery modes as asynchronous care models reduce per-session overhead. Behavioral health commands the largest therapy area footprint, while emergency intervention protocols are embedding panic-specific triage algorithms in hospital settings.
The FDA oversees prescription drug approvals and digital therapeutics clearances for panic disorder treatments, while HIPAA mandates govern patient data flows across teletherapy platforms. The Drug Enforcement Administration imposes scheduling controls on benzodiazepine prescribing, directly constraining acute intervention options. Stakeholders must monitor evolving payer policies on digital therapeutic reimbursement, as coverage determinations will separate scalable platform providers from reimbursed clinical workflows.
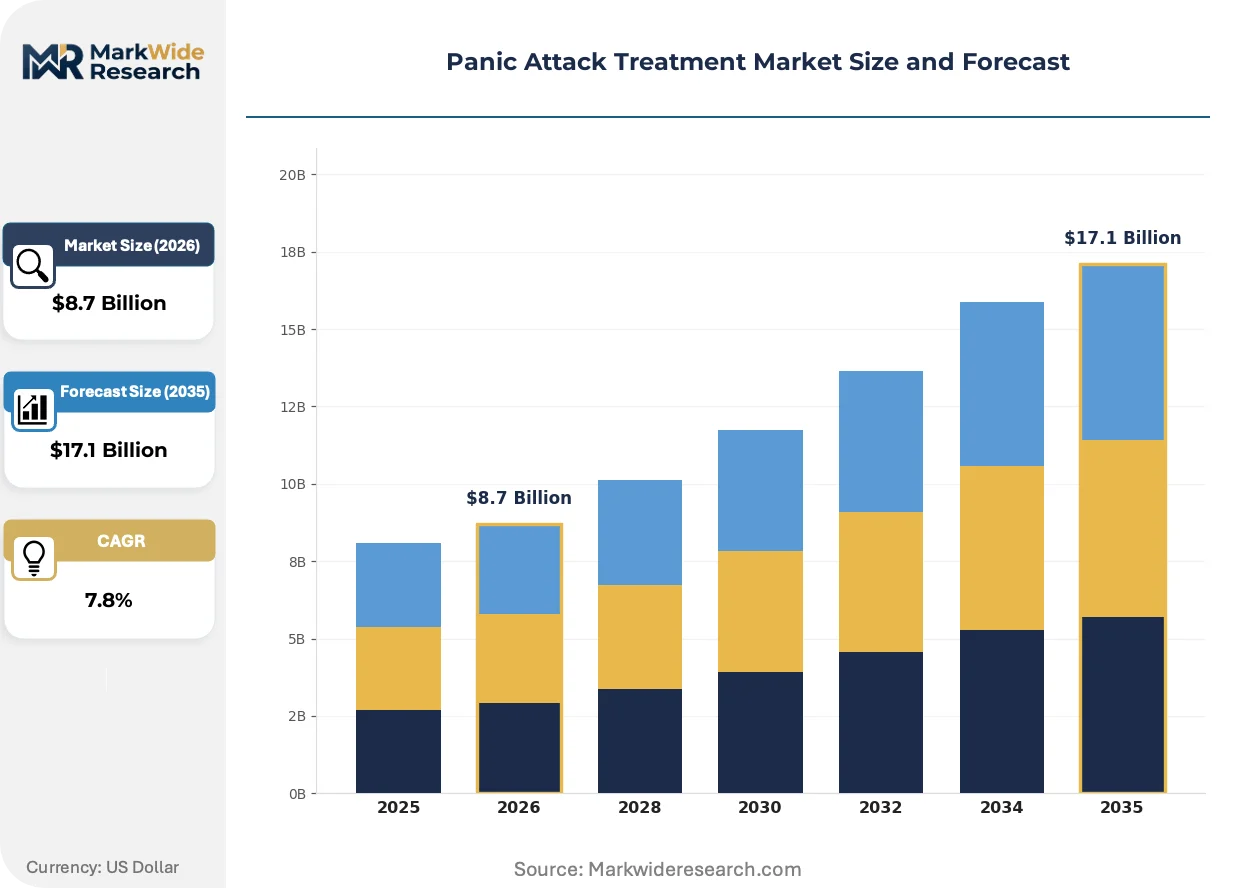
Market Dynamics
Telehealth distribution is reconfiguring patient access pathways, bypassing traditional psychiatric referral bottlenecks that previously delayed treatment initiation by months. The FDA's expanding digital therapeutics pathway accelerates software-based intervention approvals, compressing time-to-market for platform developers while reshaping competitive entry requirements.
Growth Catalysts
- Employer Mental Health Mandates:United States employers now routinely cover panic disorder protocols within sponsored benefits, expanding reimbursable patient pools.
- DEA Scheduling Reforms:Evolving benzodiazepine prescribing controls are redirecting acute intervention demand toward non-controlled alternatives.
- Asynchronous Care Models:Teletherapy platforms reduce per-session overhead, enabling scalable service delivery without proportional clinician expansion.
Market Restraints
- Generics Erosion:Teva Pharmaceutical Industries and peers flood selective serotonin reuptake inhibitor markets, compressing branded pricing power.
- Reimbursement Familiarity Gap:Payer policies on digital therapeutic coverage remain inconsistent, constraining platform revenue predictability.
- Clinician Training Bottlenecks:Cognitive behavioral therapy certification timelines limit workforce scaling relative to patient demand surges.
Strategic Opportunities
- Long-Acting Formulation Development:Chronic user discontinuation reduction represents unaddressed adherence white space.
- Hospital Triage Integration:Emergency intervention protocols embedding panic-specific algorithms create new institutional sales channels.
- HIPAA-Compliant Data Monetization:Patient outcome datasets enable population health contracting with self-insured employers.
Industry Challenges
- Interoperability Friction:Teletherapy platforms face complex electronic health record integration with legacy hospital systems.
- Credentialing Velocity:State-by-state licensure requirements slow clinician onboarding for multi-jurisdictional platform operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panic Attack Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Psychotherapy, Relaxation Techniques, Support Groups Delivery Mode: In-person, Teletherapy, Mobile Apps, Online Support End User: Individuals, Healthcare Providers, Hospitals, Clinics Therapy Area: Behavioral Health, Mental Wellness, Anxiety Disorders, Emergency Intervention |
| Companies Covered | GlaxoSmithKline plc, F. Hoffmann-La Roche Ltd, Pfizer Inc., Eli Lilly and Company, Johnson & Johnson Services, Inc., AstraZeneca, Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb Company, H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panic Attack Treatment Market Evolving Landscape
Software-based interventions are capturing clinical workflows previously reserved for in-person delivery, with asynchronous models compressing cost structures while expanding geographic reach. Three distinct shifts are restructuring how panic disorder care is produced, regulated, and consumed.
Virtual reality exposure therapy is virtualizing graduated exposure protocols that previously required physical presence in anxiety-provoking environments. Working-age adults in metropolitan United States markets adopt these platforms at accelerating rates, seeking discreet care that preserves professional anonymity. The technology is virtualizing the spatial constraints of traditional cognitive behavioral therapy, enabling home-based treatment adherence.
EMA's Medical Device Regulation harmonization with FDA digital therapeutics standards creates dual-approval pathway efficiencies for software developers. European platform providers now design compliance architectures accommodating both jurisdictions simultaneously, reducing redundant validation costs. United States and Germany represent the primary markets where this convergence accelerates product launch timelines.
Subscription-based mental health benefits are displacing traditional fee-for-service psychiatric reimbursement within large employer contracts. Third-party administrators and benefits consultants broker these arrangements, unbundling care episodes into predictable per-member-per-month costs. This restructuring is most visible in United States technology sector employers competing for talent through differentiated health offerings.
Panic Attack Treatment Market Segmentation
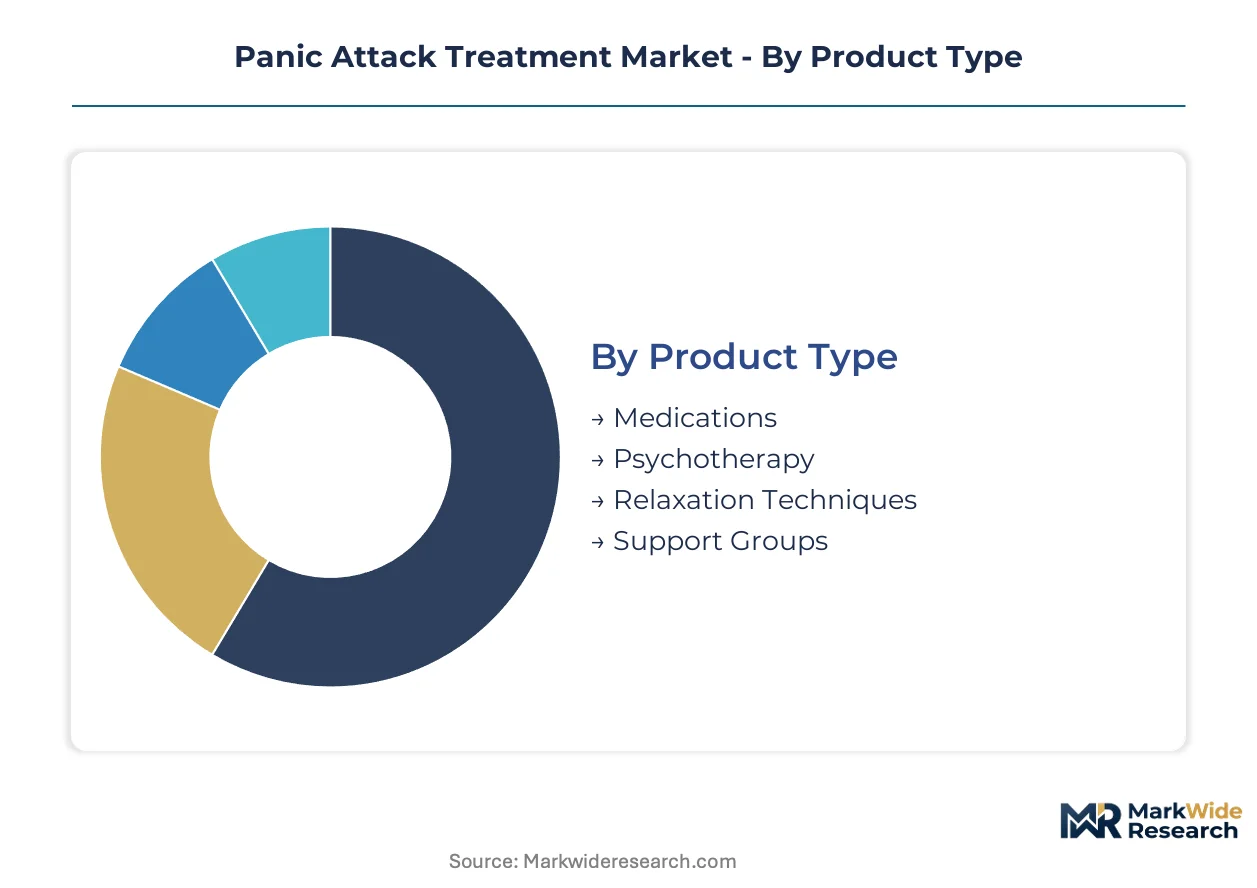
Panic attack treatment markets fragment across intervention modalities and distribution channels, with each segment carrying distinct reimbursement profiles and scaling constraints. Understanding these divisions reveals where capital deployment encounters friction versus acceleration.
Product Type:
Pharmaceutical and non-pharmaceutical interventions span acute symptom management through sustained remission maintenance, with reimbursement familiarity and clinical evidence depth determining commercial prioritization.
- Medications:Selective serotonin reuptake inhibitors and benzodiazepines modulate serotonergic neurotransmission and GABA receptor activity to attenuate sympathetic hyperarousal. United States employer-sponsored benefits sustain prescription volume through pharmacy benefit manager networks, though DEA scheduling constraints on controlled substances redirect acute intervention demand.
- Psychotherapy:Cognitive behavioral therapy targets threat-appraisal pathways through structured exposure and cognitive restructuring protocols. Clinician certification bottlenecks limit workforce scaling relative to patient demand surges in metropolitan United States markets.
- Relaxation Techniques:Biofeedback and breathing interventions provide self-administered sympathetic downregulation without prescription requirements.
- Support Groups:Peer-facilitated modalities offer cost-accessible maintenance care with minimal clinical infrastructure.
The dominant share belongs to Medications, while Psychotherapy is closing the gap fastest.
Delivery Mode:
Care distribution channels stratify by overhead structure and geographic reach, with asynchronous models compressing per-session costs while synchronous formats retain reimbursement premiums.
- In-person:Traditional psychiatric and psychological services delivered through clinical facilities maintain highest reimbursement rates but face capacity constraints from licensed provider availability. United States metropolitan clusters concentrate demand where specialist density supports referral networks.
- Teletherapy:Synchronous video-based clinical encounters bypass geographic barriers and reduce facility overhead. HIPAA-compliant platforms scale across state lines, though credentialing velocity varies by jurisdiction.
- Mobile Apps:Software-based interventions deliver cognitive behavioral therapy modules through FDA-cleared digital therapeutics pathways.
- Online Support:Asynchronous forums and chat-based services provide subclinical engagement at minimal marginal cost.
In-person delivery retains the largest revenue base, yet Teletherapy is expanding most quickly as employer benefits normalize virtual mental health access.
End User:
Demand concentration shifts between direct-to-patient channels and institutional procurement, with each pathway imposing distinct regulatory and contracting requirements.
- Individuals:Direct-pay patients and insured consumers accessing treatment through retail pharmacy and out-of-network reimbursement. United States high-deductible plan structures concentrate out-of-pocket spending in this segment.
- Healthcare Providers:Primary care physicians and psychiatric specialists prescribing interventions within established clinical workflows. Pfizer Inc. leverages detailing networks to sustain antidepressant prescriptions through this channel.
- Hospitals:Emergency departments embedding panic-specific triage algorithms for acute presentations.
- Clinics:Outpatient mental health facilities delivering structured psychotherapy programs.
Healthcare Providers command the dominant procurement volume, while Hospitals are gaining share fastest through emergency protocol integration.
Therapy Area:
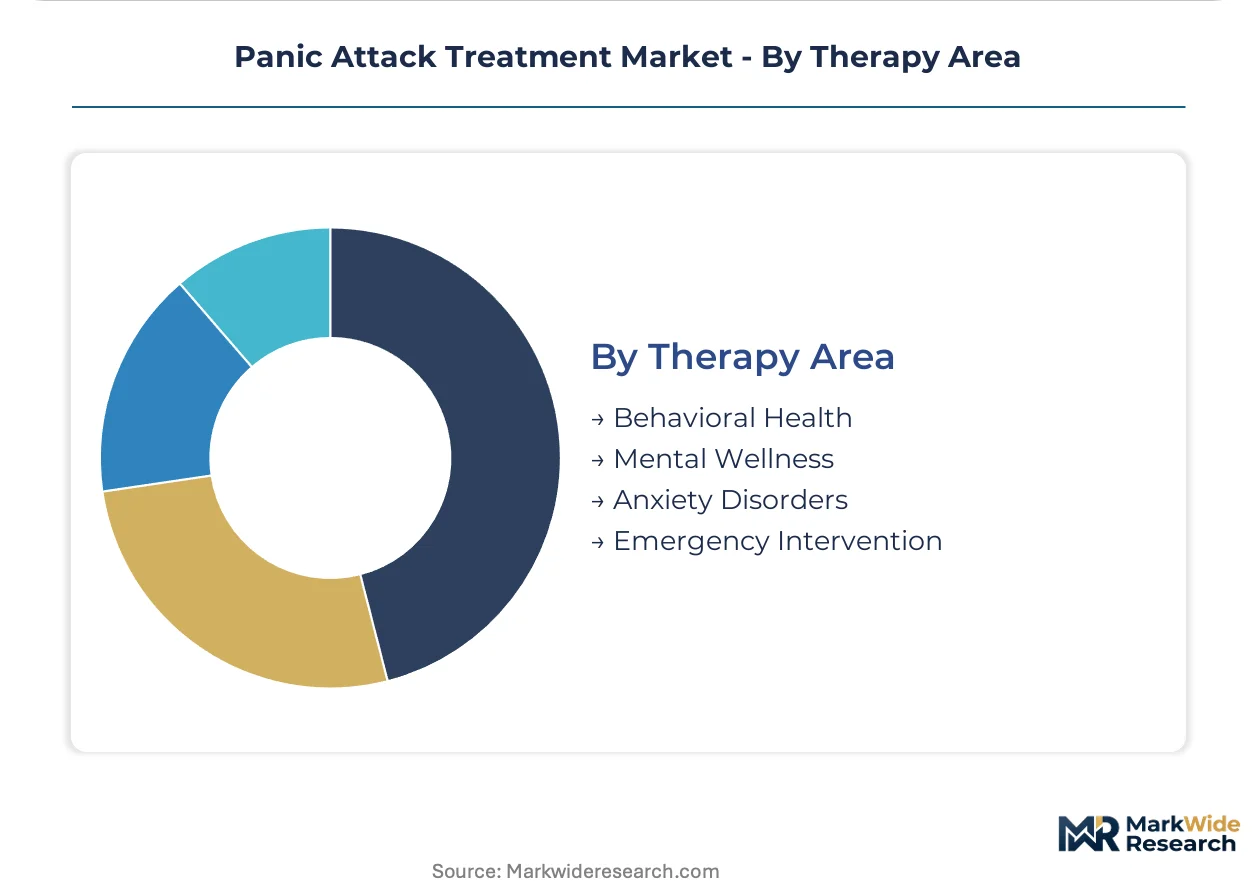
Clinical indication scope determines addressable patient population and regulatory pathway complexity, with generalized anxiety and panic disorder coding driving reimbursement eligibility.
- Behavioral Health:Comprehensive panic disorder management encompassing diagnosis, acute intervention, and maintenance protocols. This segment anchors the largest therapy area footprint through established diagnostic criteria and reimbursement codes.
- Mental Wellness:Subclinical prevention and resilience-building interventions targeting at-risk populations before diagnostic threshold.
- Anxiety Disorders:Comorbid conditions including generalized anxiety and social anxiety with overlapping pharmacological targets.
- Emergency Intervention:Acute panic attack management in hospital and urgent care settings with rapid-acting protocols.
Behavioral Health holds the dominant position, though Emergency Intervention is climbing the fastest as institutional triage algorithms expand deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables and HIPAA-compliant cloud infrastructure underwrite the United States' dominance in teletherapy platform deployment, while dense specialist networks in Germany and Switzerland anchor European pharmaceutical innovation.
United States
Employer-sponsored mental health benefits now routinely cover panic disorder protocols, expanding reimbursable patient pools through pharmacy benefit manager networks. The FDA's expanding digital therapeutics pathway accelerates software-based intervention approvals for platform developers. Metropolitan clusters in Boston and San Francisco concentrate demand where specialist density supports referral networks and telehealth adoption.
Germany
EMA's Medical Device Regulation harmonization with FDA standards creates dual-approval pathway efficiencies for software developers targeting transatlantic markets. The country's statutory health insurance system maintains consistent reimbursement for cognitive behavioral therapy protocols. Berlin and Munich host emerging digital health clusters where platform providers design compliance architectures accommodating both jurisdictions.
Switzerland
Swissmedic maintains rigorous pharmaceutical oversight while supporting innovative drug formulations for anxiety disorders through accelerated review pathways. The country's private healthcare financing structure sustains premium pricing for long-acting antidepressant formulations. Basel and Zurich anchor pharmaceutical R&D concentration where chronic user discontinuation reduction represents unaddressed adherence white space.
United Kingdom
NHS England's Increasing Access to Psychological Therapies program expands cognitive behavioral therapy capacity through stepped-care models targeting panic disorder presentations. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit with FDA digital therapeutics standards to streamline software approvals. London's Harley Street medical district and Manchester's digital health corridor concentrate private and public provision respectively.
India
CDSCO regulatory frameworks support generic manufacturing of selective serotonin reuptake inhibitors serving export markets and domestic demand. The country's central bank monitors foreign direct investment flows into telehealth platforms targeting metropolitan working-age populations. Hyderabad and Mumbai pharmaceutical clusters supply active pharmaceutical ingredients while Bangalore's technology corridor incubates mental health application developers.
Panic Attack Treatment Market Competitive Landscape
On the supply side, the industry is bifurcated between consolidated pharmaceutical manufacturers with established primary care detailing networks and fragmented digital health platform providers competing for employer contract access. Two strategic archetypes dominate: legacy drug developers sustaining antidepressant prescriptions through long-acting formulations, and software-based intervention developers seeking FDA digital therapeutics clearance. Competitive moves concentrate on M&A activity targeting teletherapy capabilities and strategic partnerships brokering subscription-based mental health benefits with large employers.
Within the legacy pharmaceutical tier, Pfizer Inc. and Eli Lilly and Company exemplify established players anchoring positions through formulation innovation and detailing network density. Teva Pharmaceutical Industries Ltd. occupies a distinct archetype as a generics specialist compressing branded pricing power across selective serotonin reuptake inhibitor markets. These three entities collectively represent the competitive tension between innovation-driven premium positioning and volume-driven cost leadership that structures pricing dynamics across pharmacological intervention segments.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Eli Lilly and Company |
| Johnson & Johnson Services, Inc. |
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb Company |
| H. Lundbeck A/S |
| Others |
Value Network & Pricing Analysis
Overcapacity in Indian generic selective serotonin reuptake inhibitor manufacturing is compressing supplier margins and forcing volume-discount tiering across wholesale procurement contracts. This utilization dynamic cascades into branded pharmaceutical pricing posture, where long-acting formulation developers must justify premium positioning through adherence metrics rather than molecule novelty alone.
Pricing Analysis
Volume-discount tiering structures pharmaceutical procurement, with pharmacy benefit managers extracting rebates scaled to prescription volume commitments. Price differentiation hinges on FDA digital therapeutics clearance tier and brand heritage in psychiatric indications. Cost compression in generic SSRI segments is intensifying because Teva Pharmaceutical Industries and peers flood markets with bioequivalent alternatives. Self-insured employers show least price sensitivity for subscription-based mental health benefits, while individual cash-pay patients in high-deductible plans exhibit highest sensitivity.
Supply Chain Analysis
Extended payment terms from United States pharmacy benefit managers strain active pharmaceutical ingredient suppliers in India and China. Raw material dependencies center on escitalopram base, sertraline intermediate compounds, and biofeedback sensor components sourced from Taiwan and South Korea. Single-source vulnerability concentrates in benzodiazepine precursor chemicals subject to DEA import quotas. Distribution runs through pharmacy benefit manager networks and teletherapy platform APIs into employer-sponsored benefit administration systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The panic attack treatment market functions as a service-attach opportunity where recurring-revenue teletherapy subscriptions expand faster than one-time pharmaceutical prescriptions. This shift rewards platform providers who embed clinical outcomes data into employer population health contracts.
For Market Incumbents: Pre-empt generic erosion in SSRI markets by accelerating long-acting formulation pipelines that reduce discontinuation rates among chronic users. Secure FDA digital therapeutics clearance for cognitive behavioral therapy modules before software-based competitors capture employer contract channels. Vertical integration into teletherapy credentialing infrastructure addresses clinician onboarding bottlenecks that constrain platform scaling.
For New Entrants and Emerging Players: Establish a beachhead in hospital emergency department triage algorithm integration, where panic-specific protocols remain underpenetrated relative to outpatient behavioral health saturation. Target metropolitan United States markets with employer concentration exceeding national averages for technology sector employment. Lead with HIPAA-compliant outcome datasets that enable direct contracting with self-insured employers bypassing traditional payer intermediaries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-based intervention development, compressing required upfront investment for FDA clearance pathways relative to traditional pharmaceutical R&D. Acquisition targets should demonstrate existing employer contract relationships with per-member-per-month pricing structures. Monitor DEA scheduling reform announcements as inflection indicators redirecting acute intervention demand toward non-controlled alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Therapeutics Clearance | Software-based CBT modules gain reimbursement eligibility through pharmacy benefit manager networks. |
| Long-Acting Formulation Development | Eli Lilly anchors market position through reduced discontinuation rates in chronic panic disorder patients. |
| Hospital Triage Algorithm Integration | Emergency departments embed panic-specific protocols creating institutional sales channels for platform providers. |
| Employer Subscription Benefit Contracts | Third-party administrators broker per-member-per-month arrangements displacing fee-for-service psychiatric reimbursement. |
| Clinician Credentialing Infrastructure | Multi-jurisdictional platform operators overcome state-by-state licensure velocity constraints through centralized verification systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA digital therapeutics filings, ClinicalTrials.gov panic disorder protocol registrations, and employer benefits consultant white papers. Primary interviews engaged teletherapy platform executives, psychiatric formulary directors at pharmacy benefit managers, hospital emergency department operations leads, and regulatory affairs specialists at digital health developers. Secondary validation drew from CMS Medicare Part D utilization data, SEC 10-K pharmaceutical segment disclosures, and GPO contract databases. Bottom-up prescription volume modeling and top-down employer benefit spending estimates were triangulated against reported platform subscription revenues.
Forecast inputs incorporate treatment modality segmentation, delivery channel mix shifts, and regional regulatory cluster adoption curves across the projection horizon. Modeled dimensions span pharmaceutical versus non-pharmaceutical intervention type, synchronous versus asynchronous care delivery, and individual versus institutional procurement channels. CAGRs were derived from prescription volume trajectories, teletherapy platform subscriber growth rates, and employer benefit penetration curves. Industry-specific inputs include DEA scheduling policy evolution scenarios and FDA digital therapeutics approval velocity assumptions.
Sensitivities concentrate around reimbursement policy shifts for software-based interventions and benzodiazepine prescribing restriction intensification. Forecasts reflect assumptions regarding telehealth regulatory permanence and employer mental health benefit expansion continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market