
 South Korea Dental Devices Market | 2026-2036
South Korea Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Dental Devices Market Analytics
Zirconia is repositioning titanium in anterior implant superstructures across South Korean practices, trimming lab turnaround times and raising patient acceptance rates. Osstem Implant Co. Ltd leverages domestic manufacturing scale to anchor its position in the value-tier implant segment. Straumann Group competes through premium ceramic abutment portfolios, while Dentium specializes in narrow-body implant geometries for Korean mandibular anatomy.
Dental devices encompass precision instruments, prosthetic components, and digital systems engineered to ISO 6871 biocompatibility thresholds and sub-10-micron marginal fit tolerances for permanent restoration seating. Their commercial purpose centers on restoring masticatory function and aesthetic outcomes across elective and therapeutic procedures. Implantology claims the deepest margin pools among product categories, while CAD/CAM technology within digital workflows expands chairside production capacity fastest. Cosmetic dentistry applications concentrate demand in Seoul's premium clinic clusters, whereas restorative dentistry sustains volume across provincial hospital networks.
MFDS enforces medical device QMS certification under Korean Good Manufacturing Practice standards, filtering market access for imported implant systems and intraoral scanners. KFDA biocompatibility testing protocols for long-term implantable materials directly shape R&D allocation between ceramic and metal substrate lines. Stakeholders must monitor how MFDS digital health integration guidelines will reshape software validation requirements for AI-assisted treatment planning platforms.
Market Dynamics
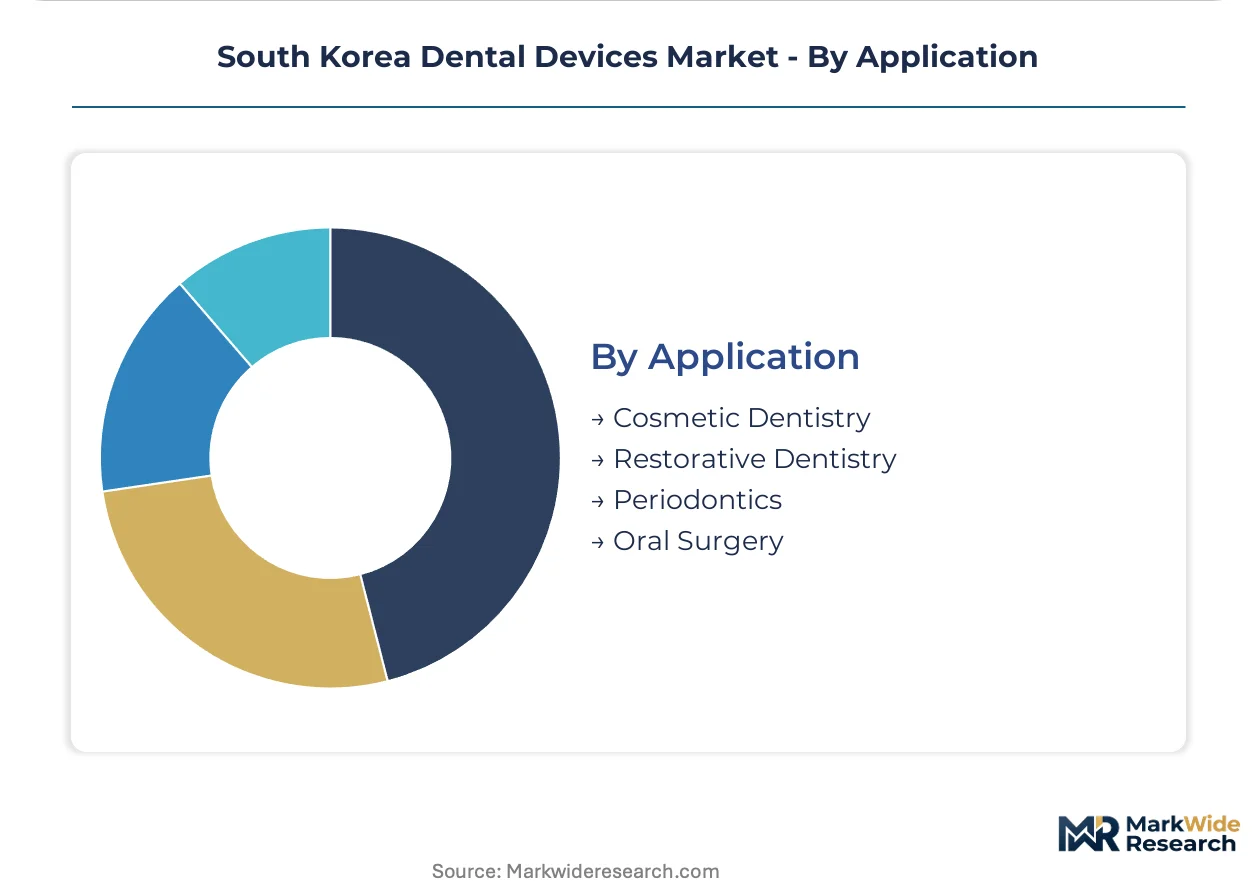
MFDS biocompatibility tightening for implantable devices is compressing supplier margins while accelerating ceramic substrate R&D budgets across Seoul's premium clinic clusters.
Growth Catalysts
- Digital workflow adoption:Private dental clinics are expanding intraoral scanner procurement to reduce lab turnaround times. Chairside CAD/CAM production capacity is rising fastest in Gangnam district cosmetic practices.
- MFDS regulatory clarity:Korean Good Manufacturing Practice certification requirements filter imported implant competition. Domestic manufacturers gain procedural advantage in QMS documentation.
- Zirconia material shift:Anterior implant superstructures increasingly specify ceramic over titanium. Patient acceptance rates improve alongside aesthetic outcome predictability.
Market Restraints
- Import dependency in precision optics:Intraoral scanner sensor modules concentrate among German and Swiss component suppliers. Korean device assemblers face input cost volatility from euro-denominated procurement.
- Biocompatibility testing timelines:KFDA long-term implantable material protocols extend product launch cycles. Ceramic substrate lines require parallel validation tracks against metal alternatives.
- Substitution from medical tourism:Thai and Vietnamese cosmetic dentistry packages attract price-sensitive Korean patients. Domestic premium clinics lose volume to ASEAN same-day procedure offerings.
Strategic Opportunities
- Provincial hospital network penetration:Restorative dentistry volume concentrates outside Seoul in Busan and Daegu metropolitan clusters. Digital equipment vendors face lower competitive density in secondary cities.
- AI-assisted treatment planning:MFDS digital health integration guidelines will reshape software validation requirements. Early movers in algorithmic implant positioning gain regulatory familiarity.
- Narrow-body implant specialization:Korean mandibular anatomy specifications create product differentiation white space. Domestic manufacturers leverage cadaver study data for geometry optimization.
Industry Challenges
- Digital dentistry technician scarcity:CAD/CAM design specialists command wage premiums exceeding general dental lab compensation. Training pipeline expansion lags equipment installation rates.
- Legacy analog integration friction:Chairside milling units require workflow reconfiguration with existing impression-based patient records. Hybrid practices face transitional productivity dips.
- ISO 6871 marginal fit certification:Sub-10-micron tolerance verification demands metrology investment beyond mid-tier lab capabilities. Quality documentation burdens smaller prosthetic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Dental Devices Market |
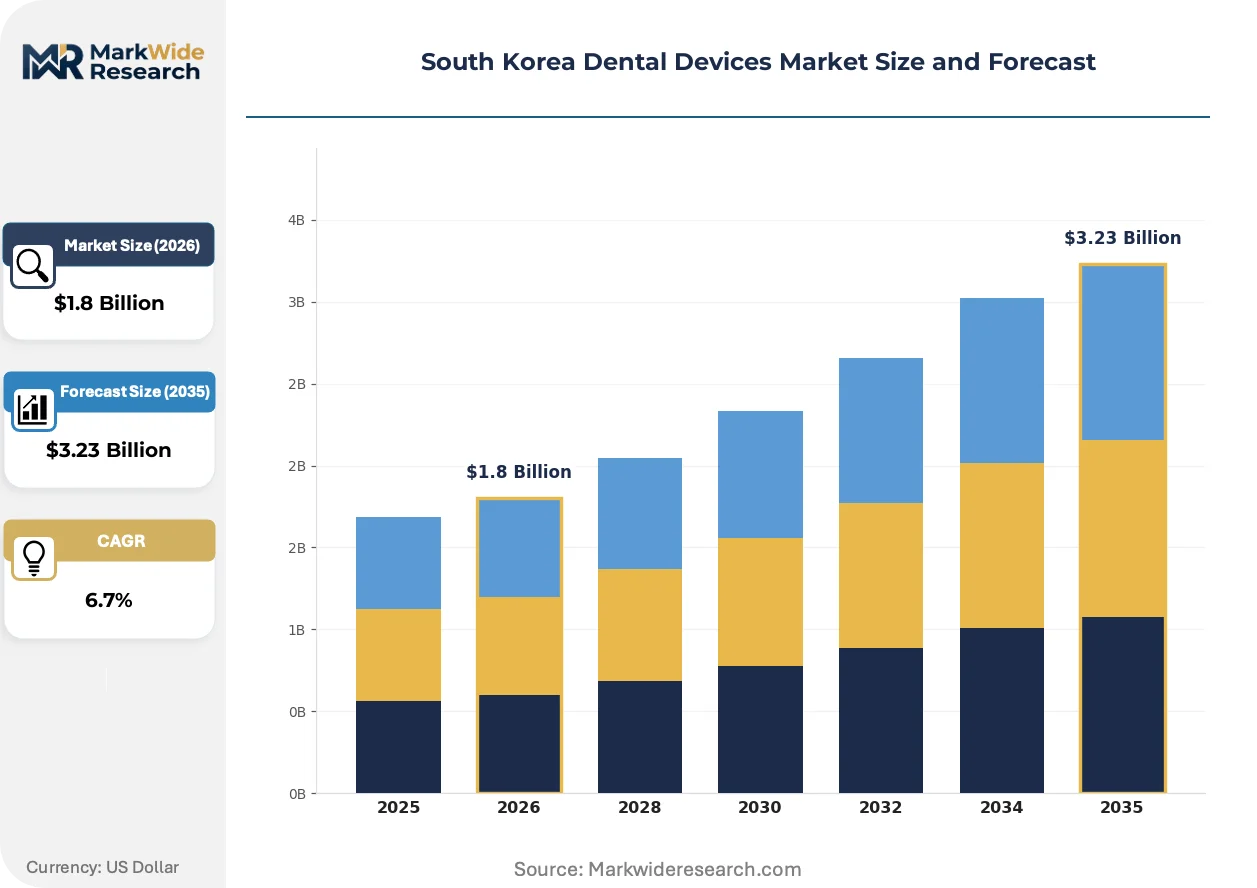
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontics, Prosthetics, Implants, Endodontics Technology: Laser Dentistry, CAD/CAM, 3D Printing, Digital Imaging End User: Dental Clinics, Hospitals, Dental Laboratories, Research Institutions Application: Cosmetic Dentistry, Restorative Dentistry, Periodontics, Oral Surgery |
| Companies Covered | Straumann Group, Zimmer Biomet, Osstem Implant Co. Ltd, Ivoclar Vivadent AG, Shinhung Co Ltd, DIO Corp., Dentsply Sirona, 3M Company, Dentium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Dental Devices Market Evolving Landscape
Digital fabrication methods are compressing traditional lab intermediation while MFDS software guidelines force early compliance investment. Material science advances and procurement pattern shifts complete the transformation vector.
Monolithic zirconia crowns are absorbing anterior restoration volume previously served by porcelain-fused-to-metal alternatives. Gangnam cosmetic clinics specify full-contour zirconia for single-visit anterior cases. The technology is absorbing margin pools from metal-ceramic labs while shortening patient chair time.
MFDS medical device QMS certification under Korean Good Manufacturing Practice standards tightens documentation requirements for imported implant systems. Foreign manufacturers face extended registration timelines versus domestic counterparts. Premium ceramic abutment portfolios from European suppliers encounter procedural friction in Seoul's value-tier implant segment.
Device-as-service contracting is displacing capital purchase models among provincial hospital networks. Subscription-based intraoral scanner access reduces upfront capex barriers for secondary-city clinics. Busan and Daegu metropolitan clusters show fastest uptake of per-procedure equipment leasing arrangements.
South Korea Dental Devices Market Segmentation
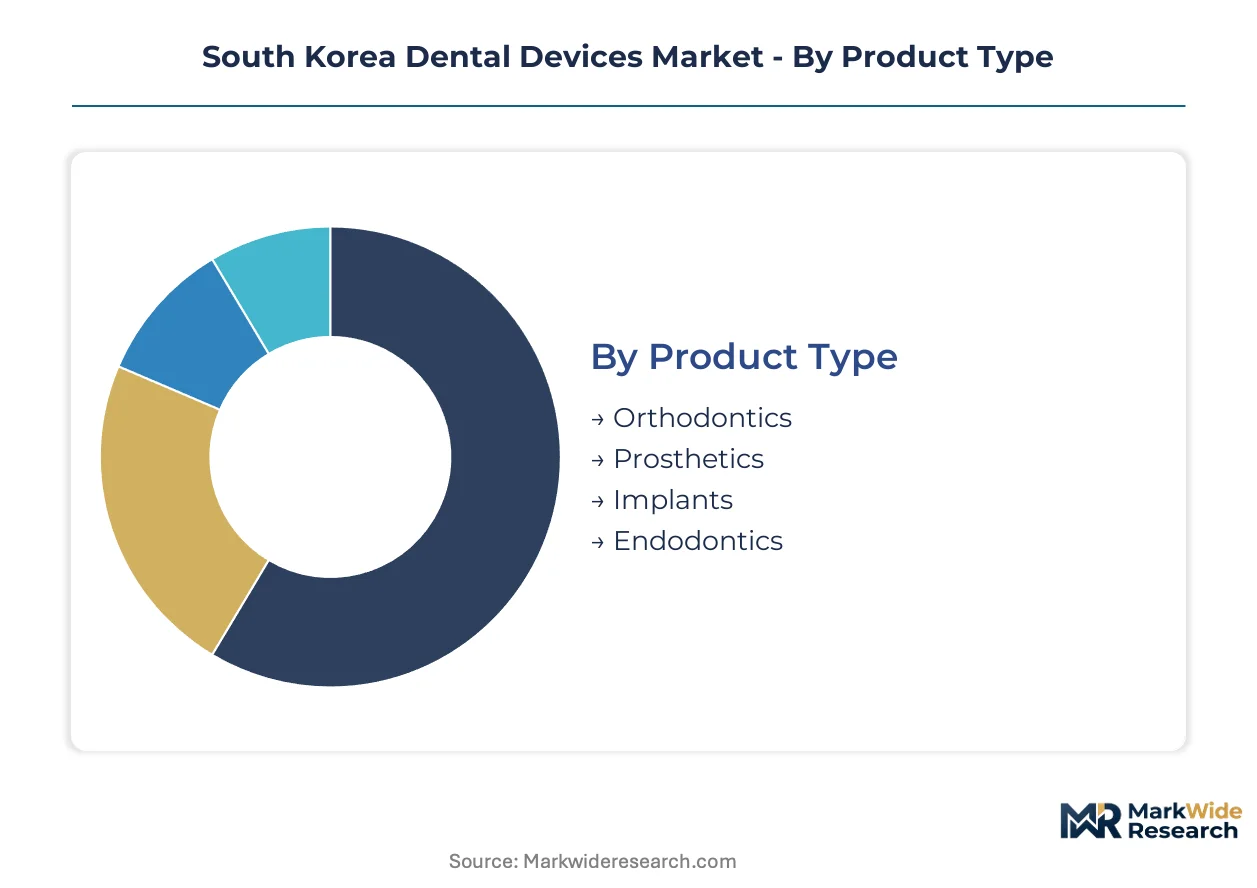
Segmentation in South Korea's dental devices market reveals how MFDS regulatory tiers, digital workflow maturity, and regional demand concentration split procurement patterns across Seoul's premium corridor versus provincial networks.
Product Type:
Cost tier differentiation separates high-margin implantable systems from consumable disposables in Korean procurement budgets.
- Implants:Titanium and zirconia-based fixtures with ceramic abutment options anchor the deepest margin pools. Seoul's Gangnam district cosmetic practices drive demand for premium immediate-load systems, though MFDS biocompatibility tightening compresses supplier margins and extends KFDA validation timelines for new ceramic substrate lines.
- Prosthetics:Crowns, bridges, and denture frameworks fabricated via CAD/CAM or conventional lost-wax methods. Provincial hospital networks in Busan and Daegu sustain volume for standard prosthetic tiers while digital chairside production concentrates in metropolitan premium clinics.
- Orthodontics:Clear aligner systems and fixed bracket appliances with Korean-specific archwire specifications.
- Endodontics:Nickel-titanium rotary files, obturation materials, and apex locators for root canal therapy.
Implants lead volumes today; prosthetics is gaining share fastest through digital workflow adoption.
Technology:
Application intensity varies by whether practices target same-day cosmetic outcomes or high-throughput restorative volume.
- CAD/CAM:Chairside milling units and design software enabling single-visit restorations. Gangnam cosmetic clinics specify these systems for anterior zirconia cases, though digital dentistry technician scarcity creates wage premiums that slow training pipeline expansion.
- Digital Imaging:Intraoral scanners and CBCT systems with sub-10-micron marginal fit verification. Korean device assemblers face euro-denominated input cost volatility from German and Swiss precision optics suppliers.
- Laser Dentistry:Soft-tissue and hard-tissue laser systems for periodontal and surgical applications.
- 3D Printing:Photopolymer and metal powder bed fusion for surgical guides and provisional restorations.
Digital Imaging leads volumes today; CAD/CAM is expanding most quickly through private clinic procurement.
End User:
Customer type determines capital intensity thresholds and regulatory documentation burdens under MFDS QMS certification.
- Dental Clinics:Private practices ranging from single-chair provincial operations to multi-location Seoul premium groups. These buyers are expanding digital equipment budgets fastest, with device-as-service contracting displacing capital purchase models in secondary cities.
- Hospitals:University-affiliated and provincial general hospital dental departments with higher patient throughput and standardized procurement.
- Dental Laboratories:Independent and clinic-captive prosthetic fabrication centers facing ISO 6871 marginal fit certification investments.
- Research Institutions:University dental schools and MFDS-affiliated testing facilities driving cadaver study data for implant geometry optimization.
Dental Clinics lead volumes today; Hospitals are climbing the fastest through provincial network digitization.
Application:
Geography concentration splits premium aesthetic demand from restorative volume across South Korea's urban hierarchy.
- Cosmetic Dentistry:Veneers, whitening, and anterior implant superstructures with full-contour zirconia specifications. Gangnam district concentrates the highest density of demand, though Thai and Vietnamese medical tourism packages attract price-sensitive Korean patients.
- Restorative Dentistry:Crowns, bridges, and implant-supported prostheses for masticatory function recovery. Busan and Daegu metropolitan clusters sustain volume across provincial hospital networks with lower competitive density for digital equipment vendors.
- Oral Surgery:Implant placement, extraction, and bone grafting procedures requiring surgical guide compatibility.
- Periodontics:Soft-tissue management and regenerative therapies for gum disease treatment.
Restorative Dentistry leads volumes today; Cosmetic Dentistry shows the steepest expansion trajectory through Seoul premium clinic investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area dominates South Korean dental device procurement through Gangnam district's premium cosmetic clinic clusters and MFDS regulatory headquarters proximity.
Seoul Capital Area
Gangnam district cosmetic practices drive immediate-load implant demand and chairside CAD/CAM adoption. MFDS Korean Good Manufacturing Practice certification requirements filter foreign competition through documentation burdens. Digital equipment budgets concentrate in multi-location premium clinic groups along Apgujeong and Cheongdam corridors.
Busan-Ulsan
Provincial hospital networks sustain restorative dentistry volume with lower competitive density for equipment vendors. Device-as-service contracting displaces capital purchase models fastest in secondary metropolitan clusters. Ulsan's industrial base supplies precision machining components to domestic implant manufacturers.
Daegu-Gyeongbuk
University-affiliated dental schools generate cadaver study data for narrow-body implant geometry optimization. KFDA biocompatibility testing protocols extend product launch cycles for ceramic substrate lines. Gyeongsan city's medical device industrial complex hosts domestic prosthetic fabrication centers.
Daejeon-Sejong
Government research institutes under MFDS affiliation drive AI-assisted treatment planning algorithm development. Regulatory familiarity with digital health integration guidelines creates early-mover advantages for software vendors. Sejong administrative city's procurement standardization influences provincial hospital network digitization timelines.
Gwangju-Honam
Price-sensitive patient segments respond to Thai and Vietnamese medical tourism substitution pressures. Honam region's lower density of premium clinics sustains analog workflow dependency longer than metropolitan counterparts. Regional dental laboratories face ISO 6871 marginal fit certification investment barriers.
South Korea Dental Devices Market Competitive Landscape
Global majors compete with regional champions across ceramic substrate technology and digital workflow integration. Market structure shows tiered consolidation with premium ceramic abutment portfolios, value-tier implant manufacturing, and narrow-body specialization geometries. Three archetypes dominate: European premium-system suppliers, Korean domestic-scale manufacturers, and digital equipment integrators. Competitive moves center on regulatory QMS documentation advantages and provincial network penetration through leasing arrangements.
Among Korean-based implant specialists, Osstem Implant Co. Ltd and Dentium occupy positions defined by domestic manufacturing scale and mandibular anatomy specialization respectively. Straumann Group represents the premium ceramic abutment archetype competing through aesthetic outcome portfolios. These three companies exemplify how geographic origin and structural form—Co. Ltd versus Group—signal divergent strategic positions across Seoul's value-tier and premium clinic segments.
| Leading Market Players |
|---|
| Straumann Group |
| Zimmer Biomet |
| Osstem Implant Co. Ltd |
| Ivoclar Vivadent AG |
| Shinhung Co Ltd |
| DIO Corp. |
| Dentsply Sirona |
| 3M Company |
| Dentium |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap dental laboratories across Busan and Daegu anchor South Korea's prosthetic fabrication tier, their conservative capital deployment reinforcing stable pricing discipline even as Seoul's premium clinic chains accelerate equipment leasing adoption. This ownership pattern concentrates supply responsiveness in provincial networks while compressing margin pass-through flexibility for imported precision optics.
Pricing Analysis
Euro-denominated sensor module costs from German and Swiss suppliers transmit directly into Korean intraoral scanner pricing, with device-as-service contracting emerging as the dominant model to absorb currency volatility. Price differentiation hinges on MFDS Korean Good Manufacturing Practice certification tier and after-sales calibration bundling. Pricing pressure intensifies in the value-tier implant segment as Osstem Implant Co. Ltd leverages domestic manufacturing scale against imported ceramic abutment portfolios. Provincial hospital networks exhibit highest price sensitivity due to standardized procurement budgets, while Gangnam cosmetic clinics prioritize aesthetic outcome predictability over unit cost.
Supply Chain Analysis
Precision optics supply rests on German and Swiss specialty component producers, with Korean device assemblers drawing from euro-denominated procurement channels for intraoral scanner sensor modules. Zirconia ceramic substrates and titanium alloy feedstock anchor raw material dependencies, alongside nickel-titanium archwire alloys for orthodontic applications. Single-source vulnerability concentrates in high-resolution imaging sensors, where alternative qualified suppliers remain limited. Distribution runs through Seoul-based medical device distributors with provincial branch networks serving Busan-Ulsan and Daegu-Gyeongbuk metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's dental devices market functions as a regulatory compounder, with MFDS biocompatibility tightening for implantable devices creating sustained demand for validated ceramic substrate lines and QMS-certified manufacturing capacity.
For Market Incumbents: To counter substitution from Thai and Vietnamese medical tourism packages, domestic manufacturers should deepen backward integration into zirconia ceramic substrate production and expand device-as-service contracting penetration across provincial hospital networks. MFDS regulatory familiarity becomes a defendable moat against European premium-system suppliers facing extended Korean Good Manufacturing Practice documentation timelines. For New Entrants and Emerging Players: Begin with narrow-body implant specialization targeting Korean mandibular anatomy specifications, leveraging cadaver study partnerships with Daegu-Gyeongbuk university dental schools. The prosthetic fabrication tier in secondary cities offers lowest competitive density, with ISO 6871 marginal fit certification investment creating barrier-filtered white space for qualified entrants. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier CAD/CAM software vendors lacking AI-assisted treatment planning capabilities, as MFDS digital health integration guidelines will reshape software validation requirements and favor early algorithmic positioning. The signal to watch is MFDS publication of finalized AI-assisted implant positioning standards, which will trigger regulatory familiarity premiums for compliant vendors.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS QMS Certification Investment | Korean Good Manufacturing Practice documentation accelerates market access versus imported competitors facing extended timelines. |
| Ceramic Substrate R&D Expansion | Zirconia anterior superstructure development captures margin pools shifting from titanium-based alternatives. |
| Device-as-Service Contracting | Per-procedure leasing reduces provincial hospital network upfront capex barriers and accelerates digital adoption. |
| Narrow-Body Implant Geometry Optimization | Korean mandibular anatomy specialization creates differentiated positioning against global standard geometries. |
| AI-Assisted Treatment Planning Development | Early algorithmic implant positioning compliance with pending MFDS digital health guidelines builds regulatory optionality. |
Research Methodology
Bottom-up dental clinic procurement modeling reconciled against top-down implant system shipment tracking forms the analytical core of this study. Primary interviews with Seoul and provincial clinic operators, biomedical engineers at university-affiliated hospitals, GPO contracts managers, and dental laboratory technical directors combined with secondary validation from MFDS medical device registration databases, Korean customs import records for precision optics, and hospital procurement system disclosures. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map implant fixture production capacity, intraoral scanner installation rates, and prosthetic fabrication throughput against patient procedure volumes across cosmetic and restorative application segments. Segmentation dimensions include product type, technology tier, end-user category, and geographic demand concentration. CAGRs derive from regression analysis of historical procurement patterns and regulatory milestone impacts, with ceramic substrate adoption curves and digital workflow penetration rates serving as key forecast inputs.
Several conditions sit outside the modeled scope, including potential MFDS reimbursement policy shifts for cosmetic dentistry procedures and unanticipated currency movements affecting euro-denominated precision optics procurement. Forecasts reflect documented assumptions about regulatory timeline adherence and technology adoption elasticity. A small set of named triggers warrants ongoing watch: MFDS finalization of AI-assisted treatment planning validation protocols, KFDA acceleration of ceramic biocompatibility testing timelines, and ASEAN medical tourism package pricing adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
South Africa Dental Devices Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Dental Fittings Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Dental Veneers Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental Impression System Market
Dental Devices
Global Endodontics Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Global Dental Burs Market