
 Dental Forceps Market | 2026-2036
Dental Forceps Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Forceps Market Analysis
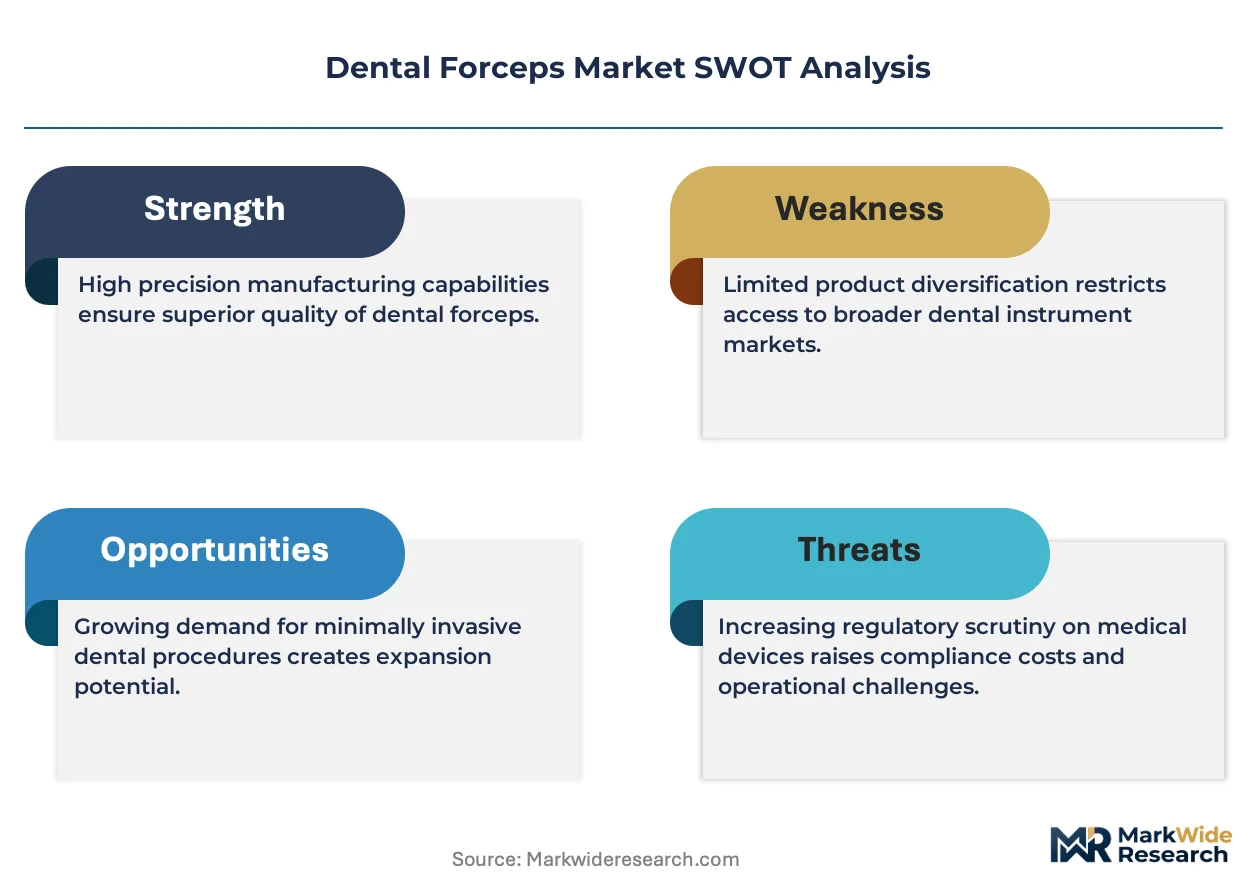
Titanium is hardening its position against traditional stainless steel in premium extraction forceps as instrument longevity and biocompatibility become decisive purchasing criteria. Hu-Friedy leverages its century-old brand equity and direct dental school relationships to sustain loyalty among North American practitioners. Karl Schumacher anchors its competitiveness through German precision manufacturing and specialized orthodontic forceps lines. ASA DENTAL competes aggressively across Southern European public hospital tenders with cost-optimized carbon steel portfolios.
Dental forceps are handheld mechanical instruments designed to grasp, luxate, and remove teeth or root fragments from alveolar bone, typically manufactured from forged alloys with Rockwell hardness between 40-50 HRC to balance edge retention against brittleness. Their primary commercial purpose centers on enabling atraumatic extraction procedures while minimizing bone loss and patient trauma in clinical settings. Extracting forceps command the largest revenue share due to universal applicability across adult dentition, while titanium variants represent the fastest-expanding material segment as practitioners prioritize reduced hand fatigue and enhanced corrosion resistance. Dental clinics dominate end-user consumption through high procedure volumes, though academic institutions concentrate margin pools via premium instrument specifications and training kit bundling.
FDA 510(k) clearance pathways and EU MDR Class I classification govern instrument commercialization, with the latter imposing heightened post-market surveillance and unique device identifier mandates that elevate compliance costs for smaller manufacturers. ISO 13485 quality management certification has become a de facto market access threshold for distributor relationships across both regulated jurisdictions. Stakeholders must monitor how FDA sterilization validation guidance and EUDAMED database integration timelines reshape supplier qualification protocols and inventory documentation burdens.
Market Dynamics
The EU Medical Device Regulation is compressing supplier margins through sterilization validation mandates and traceability infrastructure investments, forcing instrument manufacturers to restructure quality management systems or exit the European market entirely.
Growth Catalysts
- EU MDR Class I reclassification:Heightened post-market surveillance requirements are filtering out low-quality competitors, creating volume concentration among certified suppliers serving German and French dental clinics.
- Titanium alloy substitution:Practitioners in high-volume extraction settings are prioritizing reduced hand fatigue and corrosion resistance, pulling demand toward premium material specifications.
- Aging Western European demographics:Complex multi-rooted extractions among patients over 65 are expanding instrument procurement budgets across academic hospital networks.
Market Restraints
- Nickel and cobalt price volatility:Stainless steel feedstock costs fluctuate with base metal commodity markets, squeezing margin stability for carbon steel portfolio manufacturers.
- German precision manufacturing concentration:Premium orthodontic forceps production clusters around Solingen and Tuttlingen, creating geographic supply vulnerability.
- Single-use instrument substitution:Infection control liability concerns in some jurisdictions are elevating disposable alternatives for specific procedure categories.
Strategic Opportunities
- EUDAMED database integration timeline:Early compliance with unique device identifier mandates creates first-mover advantage in distributor qualification protocols across EU member states.
- Digital dentistry convergence:3D-printed surgical guides paired with extraction forceps are opening bundled training kit opportunities for dental schools.
- Southern European public hospital tenders:Cost-optimized carbon steel portfolios can capture volume in Italy and Spain where procurement prioritizes unit economics over brand equity.
Industry Challenges
- ISO 13485 certification timeline:Smaller manufacturers face 12-18 month quality management system implementation delays, blocking distributor relationships in regulated jurisdictions.
- Legacy instrument sterilization validation:Reusable forceps require documentation of steam sterilization cycle resistance, creating documentation burdens that slow new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Forceps Market |
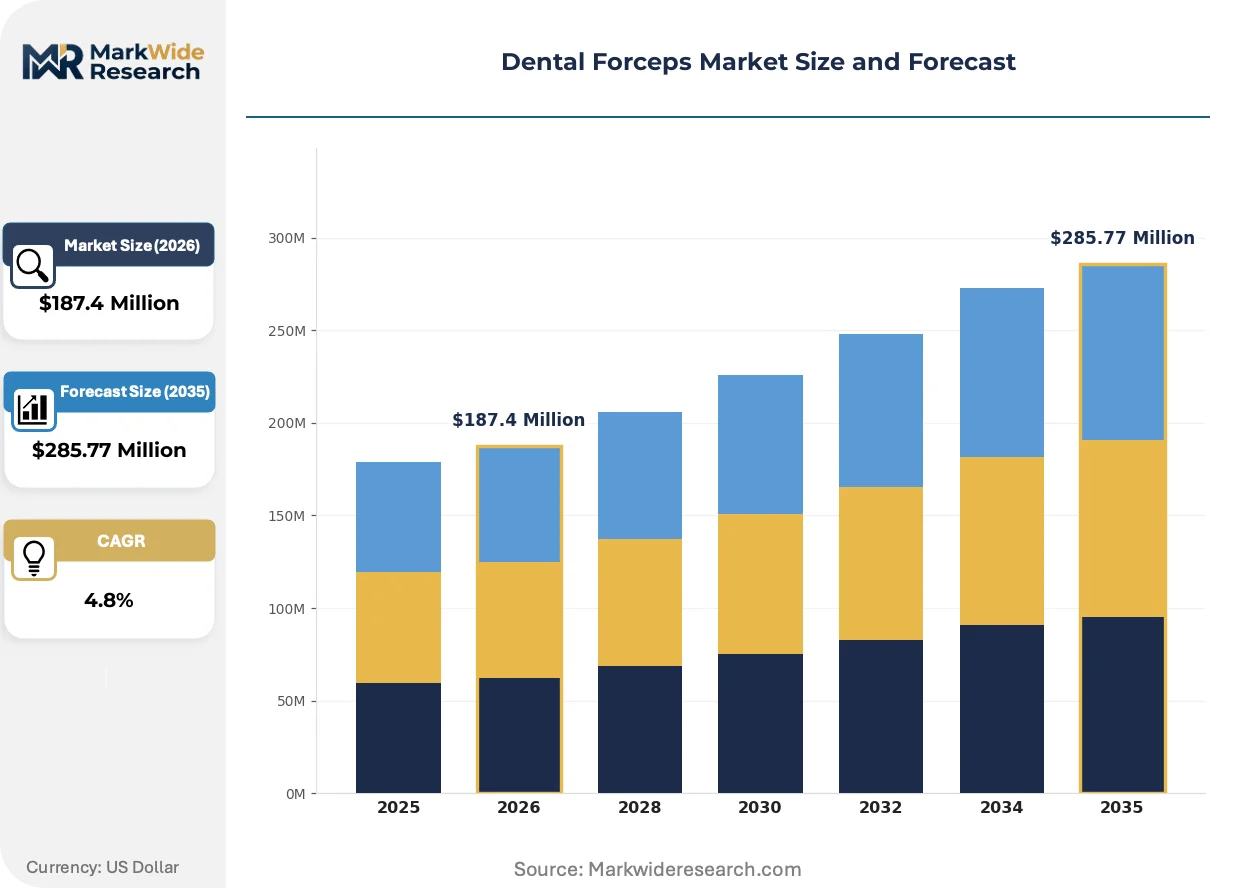
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracting Forceps, Surgical Forceps, Universal Forceps, Cleft Lip Forceps Material: Stainless Steel, Carbon Steel, Plastic, Titanium End User: Dental Clinics, Hospitals, Academic Institutions, Research Laboratories Distribution Channel: Online, Dental Supply Stores, Wholesalers, Direct Sales |
| Companies Covered | Hu-Friedy, Karl Schumacher, ASA DENTAL, Helmut Zepf Medizintechnik, Carl Martin, Otto Leibinger, A. Titan Instruments, Erbrich Instrumente, Kruuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Forceps Market Emerging Trajectories
Material science advances and regulatory digitization are restructuring how dental forceps are specified, procured, and maintained across clinical settings, with durability metrics and traceability infrastructure becoming decisive competitive variables.
Titanium alloys with Rockwell hardness between 40-50 HRC are absorbing market share from traditional stainless steel in premium extraction forceps as practitioners prioritize instrument longevity and reduced hand fatigue during high-volume procedures. German dental clinics are adopting titanium variants at accelerated rates, compressing replacement cycle economics for carbon steel competitors.
EU MDR post-market surveillance mandates are elevating compliance costs for reusable surgical instruments, forcing manufacturers to invest in unique device identifier infrastructure and sterilization validation documentation. Smaller suppliers without existing quality management systems face market access barriers, concentrating volume among ISO 13485-certified producers serving Western European dental networks.
Instrument procurement in French and German academic institutions is consolidating around bundled training kit specifications that pair extraction forceps with educational materials. This behavioral shift is displacing standalone instrument purchasing, channeling margin pools toward suppliers with direct dental school relationships and curriculum integration capabilities.
Dental Forceps Market Segmentation
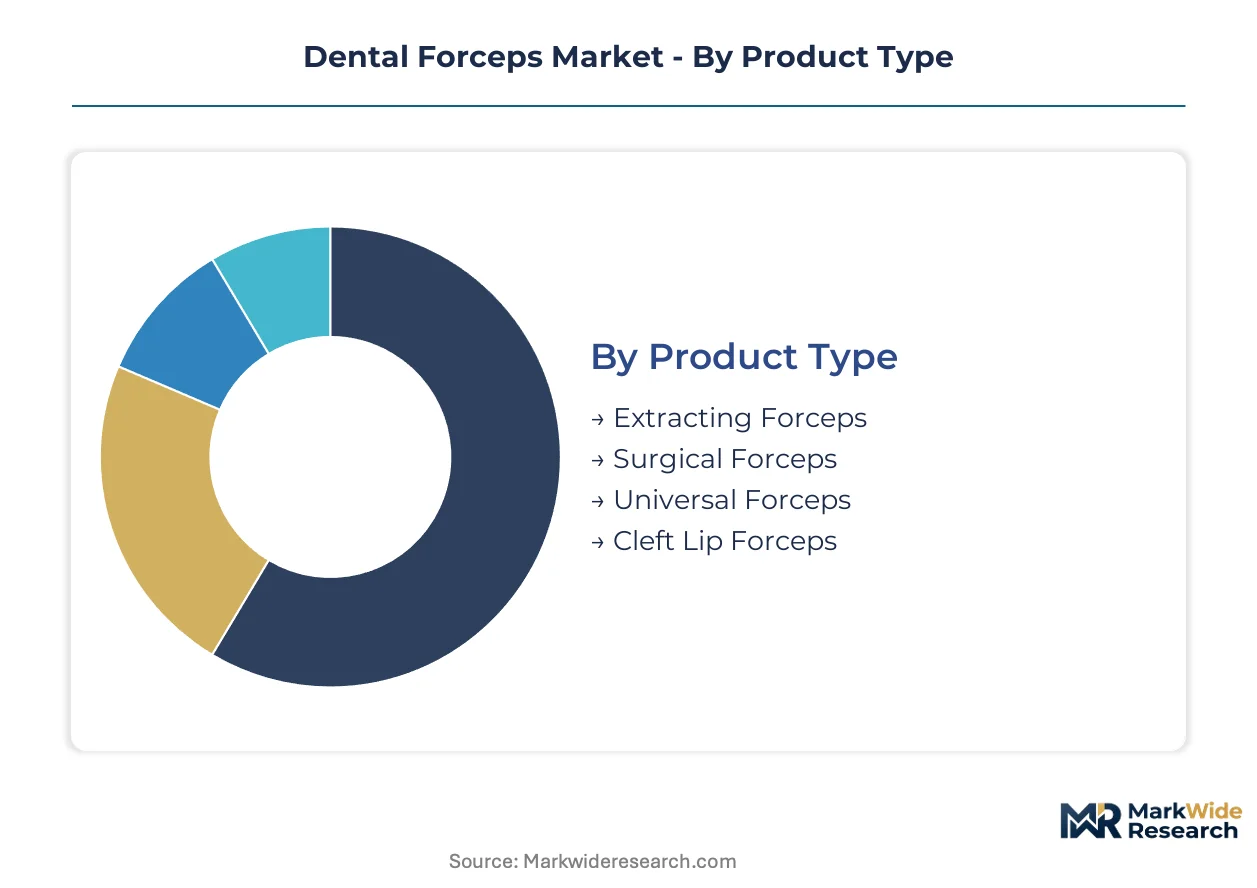
Segmentation in dental forceps reveals divergent margin pools across material grades and procurement channels. Titanium alloys command premium positioning in German clinics while carbon steel dominates Southern European tenders. Understanding these splits enables targeted positioning against EU MDR compliance costs and sterilization validation requirements.
Product Type:
Volume concentrates in universal extraction instruments, while premium margins accrue to specialized surgical variants with orthodontic applications.
- Extracting Forceps:Forged alloy instruments with beak configurations matched to tooth morphology and root anatomy. German and French dental clinics are expanding procurement budgets for these as aging demographics drive complex multi-rooted extractions.
- Surgical Forceps:Precision-engineered variants for impacted third molar and alveolar bone procedures. Academic hospital networks in Western Europe prioritize these for residency training programs, bundling with educational materials.
- Universal Forceps:General-purpose designs adaptable across adult dentition.
- Cleft Lip Forceps:Specialized instruments for pediatric maxillofacial reconstruction.
Today's leader: Extracting Forceps. Tomorrow's challenger: Surgical Forceps.
Material:
Cost tiers separate corrosion-resistant premium alloys from commodity carbon steel, with procurement patterns tracking clinic reimbursement levels and procedure volumes.
- Titanium:Biocompatible alloys with Rockwell hardness between 40-50 HRC, delivering reduced hand fatigue and extended sterilization cycle resistance. German practitioners are adopting these at accelerated rates, compressing replacement economics for stainless steel competitors.
- Stainless Steel:Chromium-nickel alloys balancing edge retention against manufacturing cost. French dental clinics specify these for high-volume extraction settings where instrument longevity outweighs weight considerations.
- Carbon Steel:Cost-optimized feedstock for budget-constrained procurement.
- Plastic:Single-use alternatives for specific infection control protocols.
Titanium is climbing the fastest as practitioners prioritize instrument longevity and reduced operator fatigue.
End User:
Customer type determines specification stringency, with academic institutions driving bundled training kit demand and clinics optimizing for unit economics.
- Dental Clinics:Private practice settings with high procedure throughput and rapid instrument turnover. These facilities dominate consumption volume across Western Europe, prioritizing sterilization durability and ergonomic design.
- Academic Institutions:University dental schools and hospital residency programs. French and German academic networks are consolidating procurement around curriculum-integrated training kits, displacing standalone instrument purchasing.
- Hospitals:Integrated health systems with centralized sterilization services.
- Research Laboratories:Specialized procurement for experimental surgical protocols.
Margin pools concentrate in Academic Institutions. Volume expansion favors Dental Clinics.
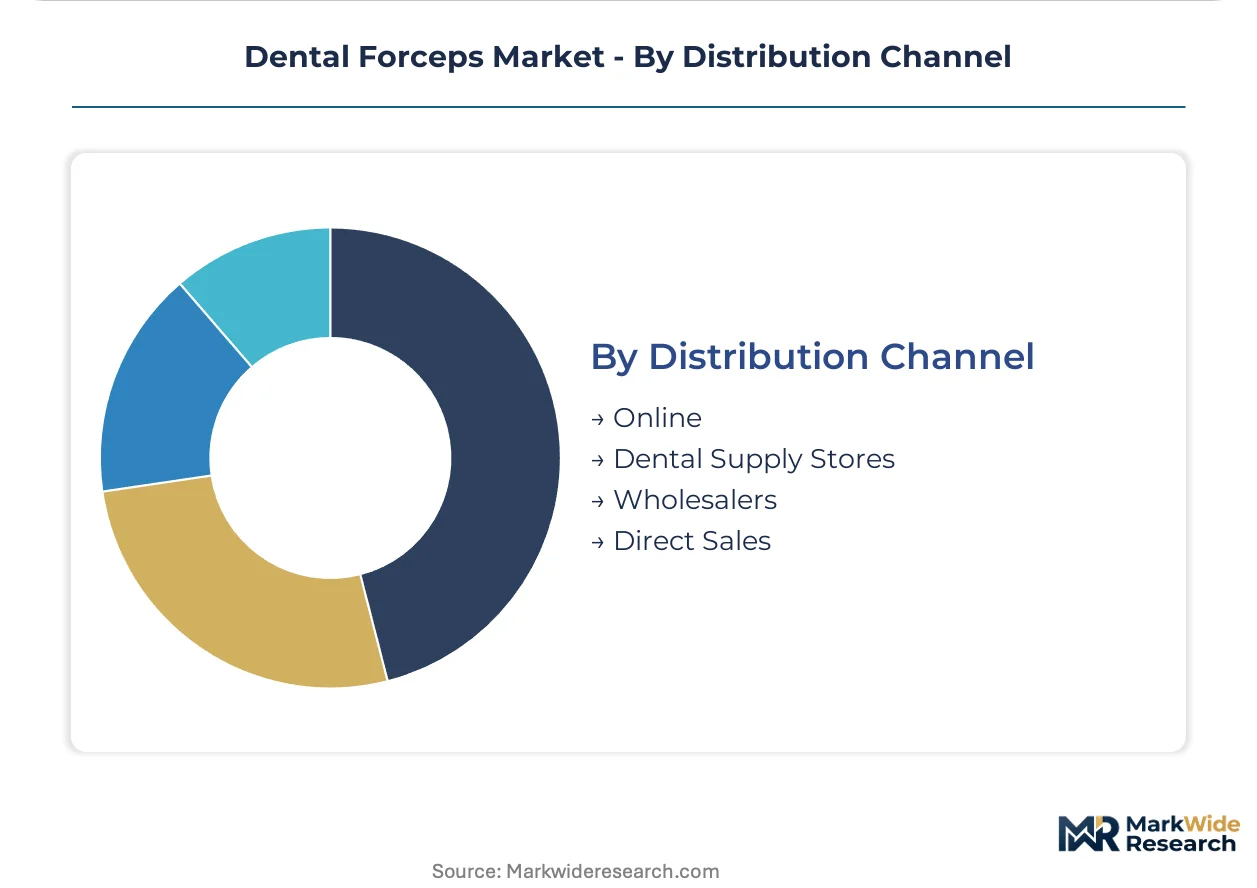
Distribution Channel:
Channel selection reflects procurement scale and regulatory documentation requirements, with direct relationships dominating premium segments.
- Direct Sales:Manufacturer relationships with dental schools and hospital networks. These channels capture bundled training kit specifications in France and Germany, leveraging ISO 13485 certification as a de facto access threshold.
- Dental Supply Stores:Regional distributors serving independent practitioners. Italian and Spanish clinics rely on these for carbon steel portfolios where procurement prioritizes immediate availability over brand equity.
- Online:E-commerce platforms for standardized instrument replacement.
- Wholesalers:Consolidated procurement for multi-clinic health systems.
Direct Sales anchors premium positioning. Dental Supply Stores drive volume in cost-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solingen anchors instrument manufacturing heritage, with Tuttlingen surgical clusters and Paris academic networks driving specification trends across Western Europe. Procurement budgets are expanding in German and French dental clinics as aging populations require complex extractions. Regulatory compliance costs are filtering supplier participation in multiple jurisdictions.
Germany
Baden-Württemberg dental clinics are expanding titanium forceps procurement as practitioner ergonomics gain priority in high-volume extraction settings. The EU MDR Class I reclassification mandates unique device identifiers and sterilization validation documentation that elevate compliance costs for reusable instrument suppliers. Solingen and Tuttlingen manufacturing clusters concentrate precision forging capacity for orthodontic and surgical forceps lines serving academic hospital networks.
France
Île-de-France academic institutions are consolidating procurement around bundled training kits that pair extraction instruments with curriculum materials. ANSM post-market surveillance requirements align with EU MDR traceability mandates, compressing margins for manufacturers without established quality management systems. Lyon and Marseille dental clinic networks prioritize stainless steel specifications where instrument longevity outweighs weight considerations in high-throughput settings.
Italy
Lombardy and Veneto public hospital tenders are channeling volume toward cost-optimized carbon steel portfolios where unit economics dominate procurement decisions. The Ministry of Health procurement frameworks emphasize immediate availability and price competitiveness over brand equity for standardized extraction instruments. Milan-based distributors serve independent practitioners across Northern Italy with regional supply chain configurations.
Spain
Catalonia and Madrid dental clinics are expanding instrument replacement cycles as procedure volumes recover across private practice networks. Spanish autonomous community health procurement regulations emphasize centralized sterilization services that favor durable alloy specifications with extended cycle resistance. Barcelona academic medical centers are piloting curriculum-integrated instrument specifications for residency training programs.
Switzerland
Zurich and Geneva dental schools are specifying premium titanium variants for research and training applications where instrument precision is paramount. Swissmedic maintains alignment with EU MDR requirements while imposing additional documentation burdens for cross-border instrument distribution. Basel pharmaceutical and medical device clusters influence adjacent dental instrument specification standards through shared quality management practices.
Dental Forceps Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers balance premium titanium positioning against cost-optimized carbon steel volume plays. The vendor base stratifies across three tiers: century-old heritage brands with dental school relationships, German precision manufacturers anchored in Solingen-Tuttlingen clusters, and Southern European cost competitors serving public tender markets. Strategic archetypes include curriculum-integrated training kit bundlers, sterilization-validated compliance specialists, and carbon steel volume suppliers. Geographic expansion into EU MDR-compliant markets and backward integration into forged alloy production represent the dominant competitive moves reshaping supplier positioning.
Among heritage-tier specialists, Hu-Friedy and Karl Schumacher exemplify divergent geographic anchoring strategies within premium forceps positioning. ASA DENTAL occupies a position within the Southern European cost-optimized segment. Helmut Zepf Medizintechnik and Carl Martin represent German GmbH-structured precision manufacturers concentrated in Baden-Württemberg industrial clusters. Otto Leibinger, A. Titan Instruments, and Erbrich Instrumente sit within specialized orthodontic and surgical forceps niches. Kruuse anchors Scandinavian veterinary and dental crossover positioning. These named entities collectively illustrate how brand equity, manufacturing geography, and regulatory compliance capacity segment competitive access across Western European procurement channels.
| Leading Market Players |
|---|
| Hu-Friedy |
| Karl Schumacher |
| ASA DENTAL |
| Helmut Zepf Medizintechnik |
| Carl Martin |
| Otto Leibinger |
| A. Titan Instruments |
| Erbrich Instrumente |
| Kruuse |
| Others |
Supply Flow & Price Mechanics
EU MDR sterilization validation mandates gate qualified supply access and premium-tier pricing power, compressing margins for uncertified manufacturers while concentrating margin pools among ISO 13485-compliant producers serving German and French dental networks. This regulatory filter reshapes procurement economics across material grades and distribution channels.
Pricing Analysis
Input-cost pass-through from nickel and cobalt commodity volatility squeezes carbon steel portfolio margins, while titanium alloy premiums harden against feedstock pressure through practitioner willingness to pay for reduced hand fatigue. Three-tier pricing structure across premium titanium, standard stainless steel, and economy carbon steel levels tracks certification grade and sterilization cycle durability. Pricing pressure stems from Southern European public tender unit economics, with Italian and Spanish procurement frameworks prioritizing immediate availability over brand equity. Academic institutions in France and Germany exhibit lowest price sensitivity, bundling curriculum-integrated training kits at premium specifications.
Supply Chain Analysis
ISO 13485 certification gates distributor relationships across EU member states, filtering supplier participation toward quality-managed producers concentrated in German Solingen-Tuttlingen clusters and Italian precision manufacturing regions. Forged alloy feedstock draws from German and Austrian steel mills, with titanium billet sourcing anchored in Japanese and Russian primary production. Single-source vulnerability concentrates in Solingen precision forging capacity for orthodontic forceps lines. Distribution runs through direct manufacturer relationships with dental schools and hospital networks, supplemented by regional dental supply stores serving independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with practitioner demand shifting toward titanium specifications that reward certified manufacturers with pricing power and replacement cycle compression.
For Market Incumbents: Lock in dental school curriculum relationships through bundled training kit specifications that displace standalone instrument purchasing. Deepen backward integration into forged alloy production to secure feedstock cost stability against nickel and cobalt volatility. Prioritize EUDAMED database integration timelines to capture first-mover distributor qualification advantages across EU member states. For New Entrants and Emerging Players: EU MDR Class I reclassification in Germany and France opens a window for ISO 13485-certified specialists to capture volume concentration among filtered-out low-quality competitors. Target Southern European public hospital tenders in Italy and Spain where procurement prioritizes unit economics over brand equity. Lead with cost-optimized carbon steel portfolios distributed through regional dental supply store relationships. For Investors and Strategic Acquirers: Roll-up economics work for German GmbH-structured precision manufacturers because geographic supply concentration in Baden-Württemberg creates scarcity value for orthodontic and surgical forceps capabilities. Five-to-ten year viability hinges on regulatory compliance capacity rather than scale alone. Target acquisition candidates with existing dental school direct relationships and EUDAMED-ready traceability infrastructure. Watch titanium alloy adoption rates among German high-volume extraction practitioners as inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management certification unlocks distributor access across EU member states under MDR requirements. |
| EUDAMED Database Integration | Early unique device identifier compliance creates qualification priority in French and German procurement channels. |
| Titanium Alloy Portfolio Expansion | Biocompatible specifications capture practitioner preference for reduced hand fatigue in high-volume settings. |
| Curriculum-Integrated Training Kit Development | Bundled educational materials displace standalone purchasing in academic hospital networks. |
| Backward Integration into Forged Alloy Production | In-house forging capacity insulates margin stability from nickel and cobalt commodity volatility. |
Methodological Framework
Multiple input streams — primary interviews with dental school procurement directors, hospital purchasing committee members, and biomedical equipment specialists; secondary validation against EUDAMED registration data, ANSM post-market surveillance filings, and German dental clinic procurement frameworks; plus customs records and ISO certification databases — were reconciled through bottom-up instrument shipment analysis and top-down dental procedure volume triangulation.
Historical procurement patterns were cross-referenced against expert panel inputs to construct analytical framework across material grade, product type, end-user category, and distribution channel dimensions throughout the forecast period. CAGRs were derived from procedure volume elasticity models incorporating aging demographic projections and oral surgery utilization rates. Forecast inputs included EU MDR implementation timeline assumptions and titanium alloy substitution curves among German practitioner panels.
Revisions become necessary when sterilization validation guidance shifts, base metal commodity volatility exceeds modeled bands, or EUDAMED integration timelines accelerate. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and practitioner material preference evolution. A model refresh is warranted upon material change in EU MDR enforcement intensity or German dental clinic reimbursement frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Regeneration Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental CAD Market
Dental Devices
China Dental Implants Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Global Dentures Market