
 Dental Compressors Market | 2026-2036
Dental Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Compressors Market Intelligence
Modular compressor configurations bundled with sterilization and vacuum systems is rebalancing procurement patterns across dental practices. Midmark Corporation leverages integrated delivery system expertise to anchor its position in clinic infrastructure. Dürr Dental sustains technology leadership through precision engineering of oil-free compression platforms. Air Techniques competes on channel control across North American dental distribution networks.
Dental compressors are pressurized air generation systems engineered to deliver oil-free, dry, and microbiologically clean air at pressures typically ranging from 5 to 8 bar for powering handpieces, scalers, and suction equipment. Reciprocating technology occupies the largest installed base due to proven reliability and lower capital requirements, though scroll technology is displacing legacy systems in premium clinic environments where noise reduction and energy efficiency command priority. Oil-free compressors dominate new procurement as end users prioritize patient safety and ISO air quality compliance over first-cost economics.
ISO 8573-1 Class 0 certification requirements and FDA device quality system regulations are elevating barriers for compressor suppliers seeking access to clinical settings. The EU Medical Device Regulation imposes additional conformity obligations on equipment marketed to European dental practices. Stakeholders must monitor evolving compressor efficiency standards and air purity thresholds as regulatory frameworks tighten across major dental equipment markets.
Market Dynamics
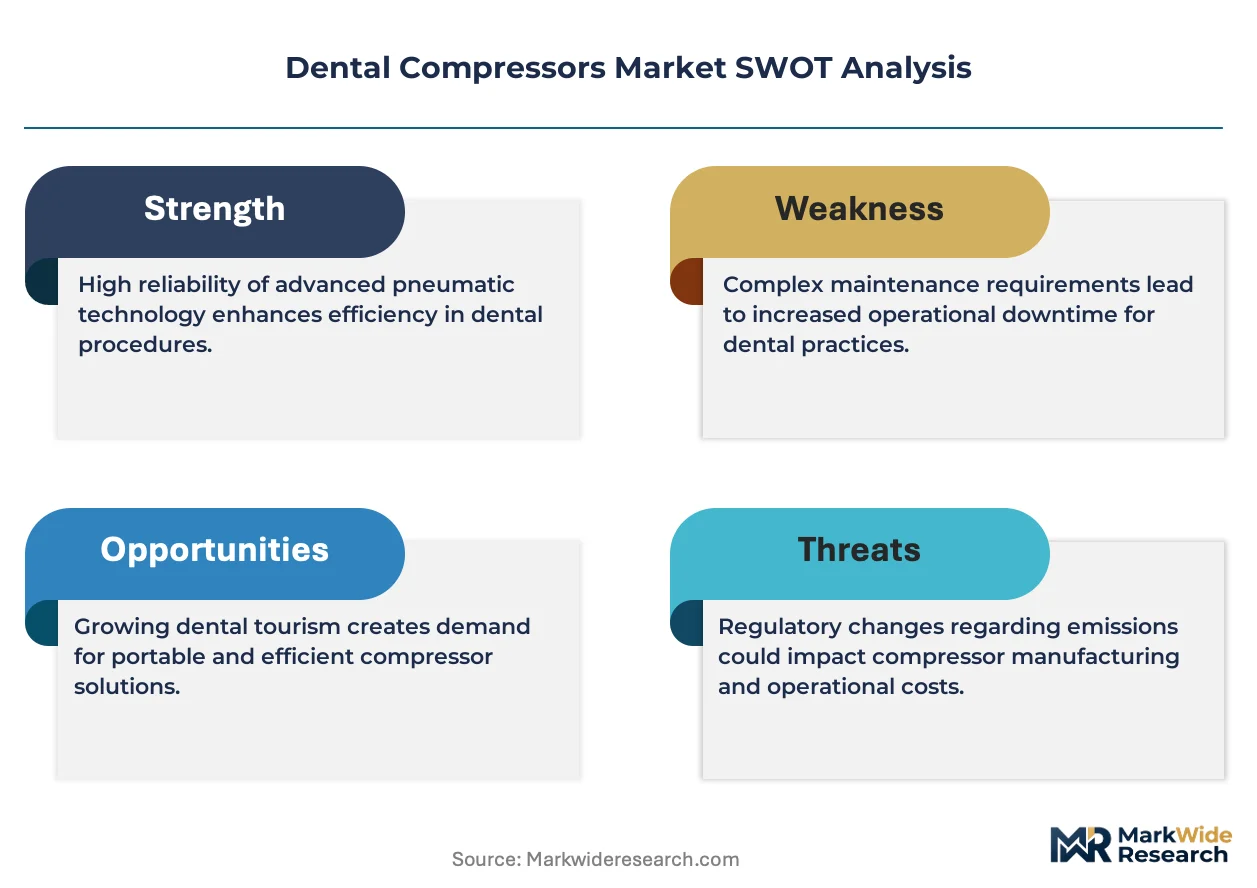
ISO 8573-1 Class 0 certification mandates are compressing product lifecycles and forcing compressor architecture redesigns across dental equipment supply chains. Oil-free air quality standards now function as non-negotiable procurement filters in clinic infrastructure decisions.
Growth Catalysts
- Procedural volume expansion:Rising patient throughput in ambulatory dental clinics is expanding compressor deployment density per treatment room. United States clinic chains are standardizing on redundant compressor configurations to minimize downtime.
- EU Medical Device Regulation:MDR conformity obligations are accelerating replacement cycles for legacy compressor systems in European dental practices. Compliance deadlines are compressing procurement timelines.
- Scroll technology maturation:Noise reduction and energy efficiency gains are displacing reciprocating systems in premium clinic environments. German engineering standards are setting performance benchmarks.
Market Restraints
- Precision manufacturing concentration:Oil-free compression component supply concentrates among German and Japanese precision engineering specialists. Geographic concentration creates vulnerability to logistics disruption.
- Copper and rare earth input costs:Electric motor windings and permanent magnet materials face commodity price volatility. Compressor OEMs struggle to pass through input cost fluctuations.
- Technical limitation in ultra-quiet operation:Sub-55 dB compressor designs require acoustic engineering trade-offs that compromise service accessibility. Maintenance intervals compress as sound dampening enclosures restrict technician access.
Strategic Opportunities
- China dental infrastructure modernization:Tier-2 and Tier-3 city clinic expansion is creating demand for mid-range oil-free compressors. Domestic certification pathways are streamlining for qualified suppliers.
- Remote monitoring convergence:IoT sensor integration with predictive maintenance algorithms is enabling service revenue unbundling. Compressor-as-a-service models are emerging in North American group practices.
- India PLI scheme alignment:Production-linked incentives for medical device manufacturing are reducing landed cost disadvantages for domestic assembly. Compressor OEMs are evaluating local production partnerships.
Industry Challenges
- Compressed air purity validation:Microbiological testing protocols for dental compressor output lack harmonization across notified bodies. Certification timeline variability disrupts product launch schedules.
- Legacy system integration:Retrofit compatibility with existing clinic air distribution networks requires custom manifold adaptations. Field engineering capacity constraints extend installation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Compressors Market |
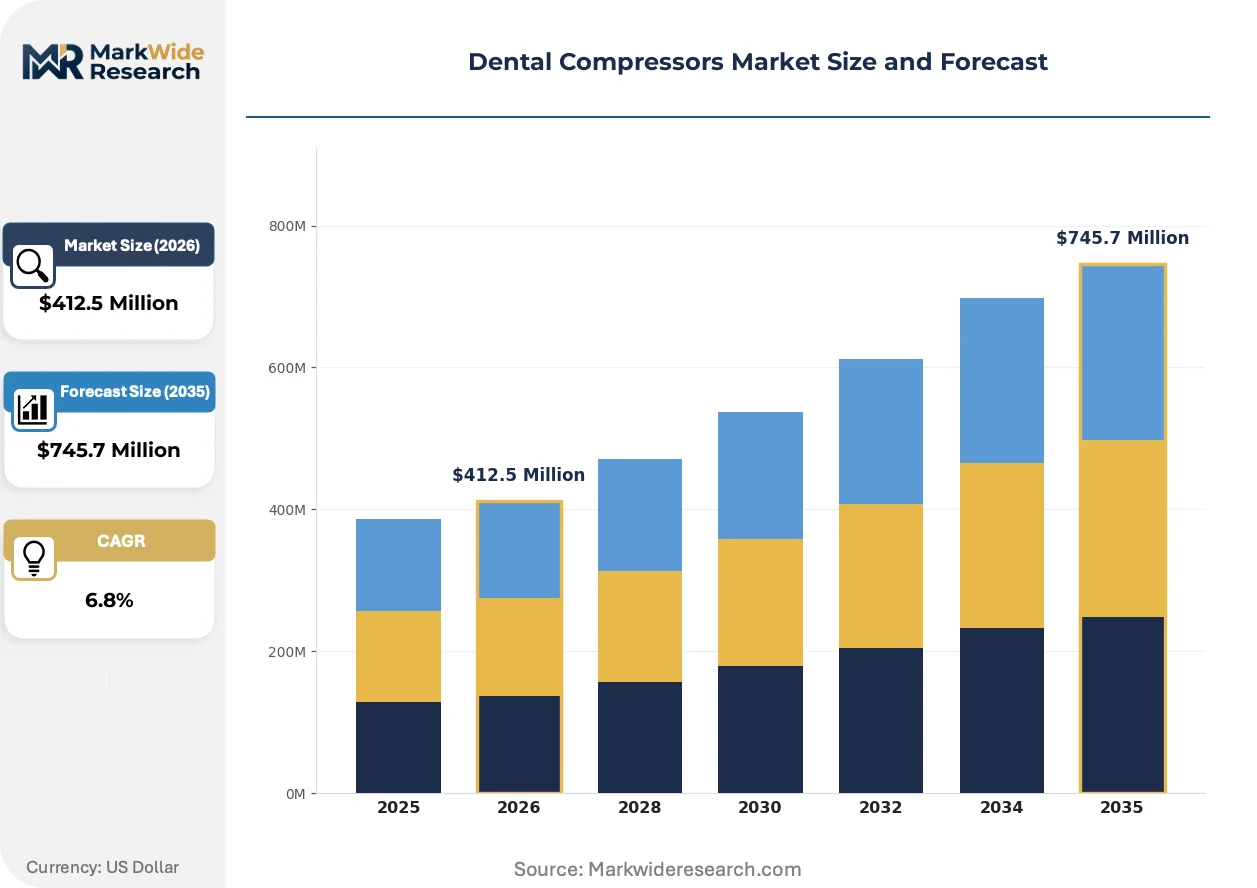
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Free Compressors, Oiled Compressors, Portable Compressors, Centralized Compressors End User: Dental Clinics, Hospitals, Dental Labs, Research Institutions Technology: Reciprocating Technology, Rotary Technology, Scroll Technology, Diaphragm Technology Capacity: Small Capacity, Medium Capacity, Large Capacity, Others |
| Companies Covered | Midmark Corporation, Dürr Dental, Air Techniques, Kaeser Dental, Quincy Compressors, General Air Products, Gnatus, Aixin Medical Equipment Co., DENTALEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Compressors Market Strategic Shifts & Innovations
Digital compressor control architectures are converging with clinic management software, enabling real-time air quality monitoring and predictive maintenance scheduling. This integration is redefining equipment lifecycle economics and supplier value propositions.
Variable speed drive technology is automating compressor output modulation to match real-time handpiece demand rather than cycling on fixed pressure bands. Premium dental groups in Germany and the United States are specifying VSD-equipped systems for energy cost reduction. This automation is compressing the total cost of ownership gap between scroll and legacy reciprocating platforms.
REACH substance restrictions and F-Gas Regulation phase-down schedules are eliminating certain refrigerant and lubricant chemistries from compressor cooling circuits. European OEMs are reformulating thermal management systems to maintain performance under constrained material palettes. Oil-free scroll compressors with air-cooled architectures are gaining preference as compliance-safe alternatives in EU markets.
Group purchasing organizations are consolidating compressor procurement decisions across multi-site dental practices, compressing vendor negotiation cycles and standardizing specification requirements. Independent equipment dealers are losing share to direct manufacturer relationships and integrated delivery system contracts. This concentration is most visible in United States dental service organization networks exceeding fifty locations.
Dental Compressors Market Segmentation
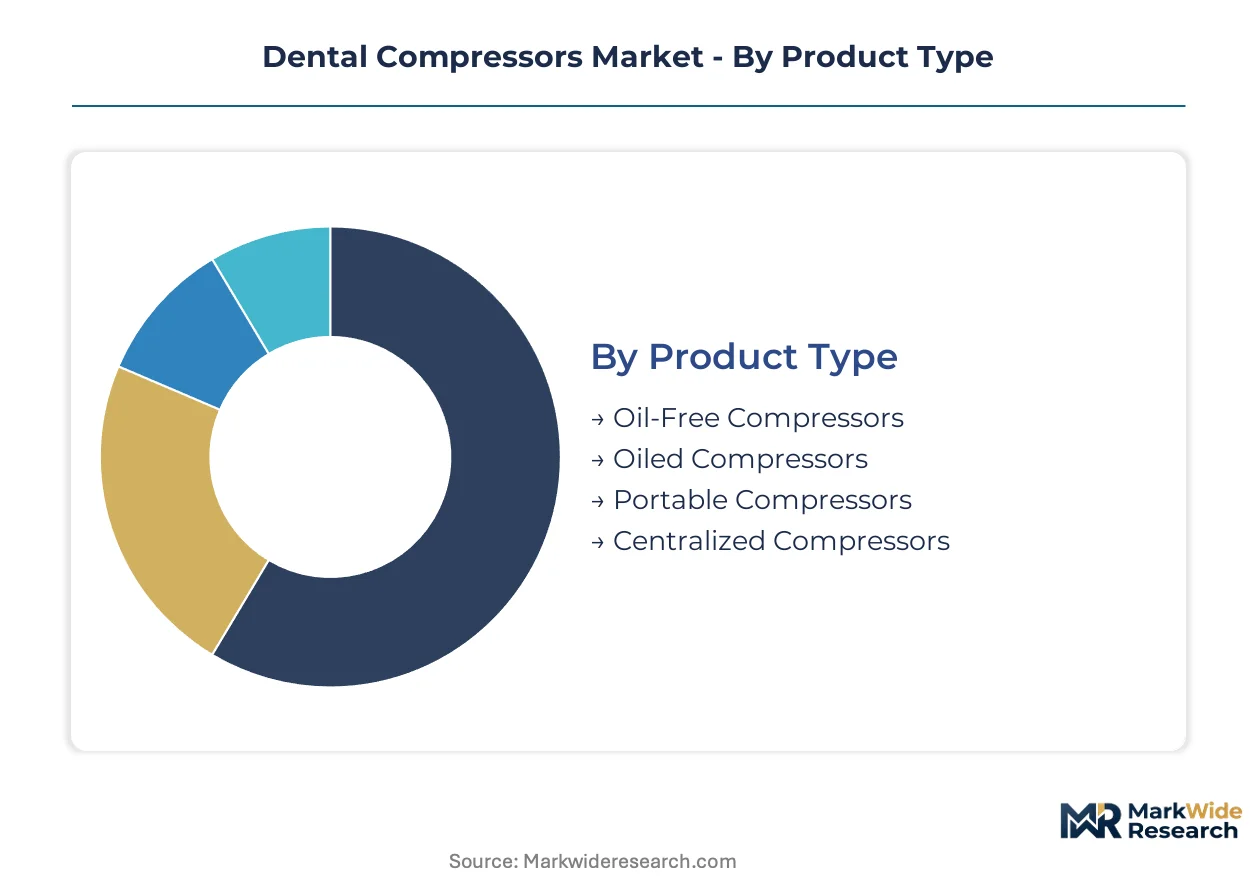
Dental compressor procurement patterns diverge sharply across clinical settings, with ISO 8573-1 Class 0 compliance and treatment room density dicting specification requirements. Technology selection and capacity sizing determine lifecycle economics and maintenance burden for practice operators.
Product Type:
Oil-free architectures dominate specification sheets as clinics prioritize patient safety over acquisition cost differentials.
- Oil-Free Compressors:These systems eliminate hydrocarbon contamination risk through PTFE-coated pistons or scroll mechanisms, delivering ISO 8573-1 Class 0 certified air. German and United States dental service organizations mandate oil-free specifications across all new clinic builds to satisfy liability protocols.
- Oiled Compressors:Lubricated reciprocating designs persist in cost-sensitive installations where legacy equipment standards apply. Maintenance intervals compress as oil carryover risks force more frequent filter replacement and air quality testing.
- Portable Compressors:Mobile units serve field dentistry and temporary clinic setups with reduced output capacity. Battery-powered variants are penetrating rural health programs in India under PLI scheme subsidies.
- Centralized Compressors:Multi-outlet systems power large dental schools and hospital departments through ring-main distribution. Redundant compressor configurations minimize single-point failure risk in high-throughput United States academic medical centers.
Oil-Free Compressors leads on scale; Portable Compressors leads on momentum.
End User:
Procurement authority concentrates differently across customer types, with group purchasing organizations reshaping vendor access patterns.
- Dental Clinics:Ambulatory practices generate the largest installed base, with multi-site chains standardizing on scroll technology for noise compliance. United States dental service organizations exceeding fifty locations negotiate direct manufacturer contracts, bypassing traditional equipment dealers.
- Hospitals:Integrated delivery systems specify medical-grade compressors with enhanced monitoring capabilities. FDA device quality system regulations elevate documentation requirements for hospital procurement committees.
- Dental Labs:Prosthetic manufacturing facilities prioritize consistent pressure delivery for CAD/CAM milling operations. Medium-capacity oil-free units dominate lab infrastructure in Germany's dental technology cluster.
- Research Institutions:University dental schools require compressors supporting both clinical training and experimental protocols. Dual-output systems separating instrument-grade from laboratory-grade air quality are gaining specification in United States academic settings.
Dental Clinics leads on scale; Dental Labs leads on momentum.
Technology:
Compression mechanism selection determines acoustic profile, energy consumption, and maintenance accessibility.
- Reciprocating Technology:Piston-driven designs occupy the largest legacy installed base through proven reliability and lower capital requirements. German manufacturers are phasing reciprocating production in favor of scroll platforms as EU energy efficiency standards tighten.
- Rotary Technology:Vane and screw compressors deliver continuous output for high-demand environments with moderate noise characteristics. Rotary systems are displacing reciprocating units in medium-capacity European hospital installations.
- Scroll Technology:Orbiting scroll mechanisms achieve sub-60 dB operation without oil lubrication, commanding premium positioning. Scroll compressors are displacing legacy alternatives in premium United States and German clinic environments where patient experience metrics influence technology selection.
- Diaphragm Technology:Membrane compression isolates air path from mechanical components, delivering the highest purity grades. Limited flow rates restrict diaphragm systems to specialized research and pharmaceutical compounding applications.
Reciprocating Technology leads on scale; Scroll Technology leads on momentum.
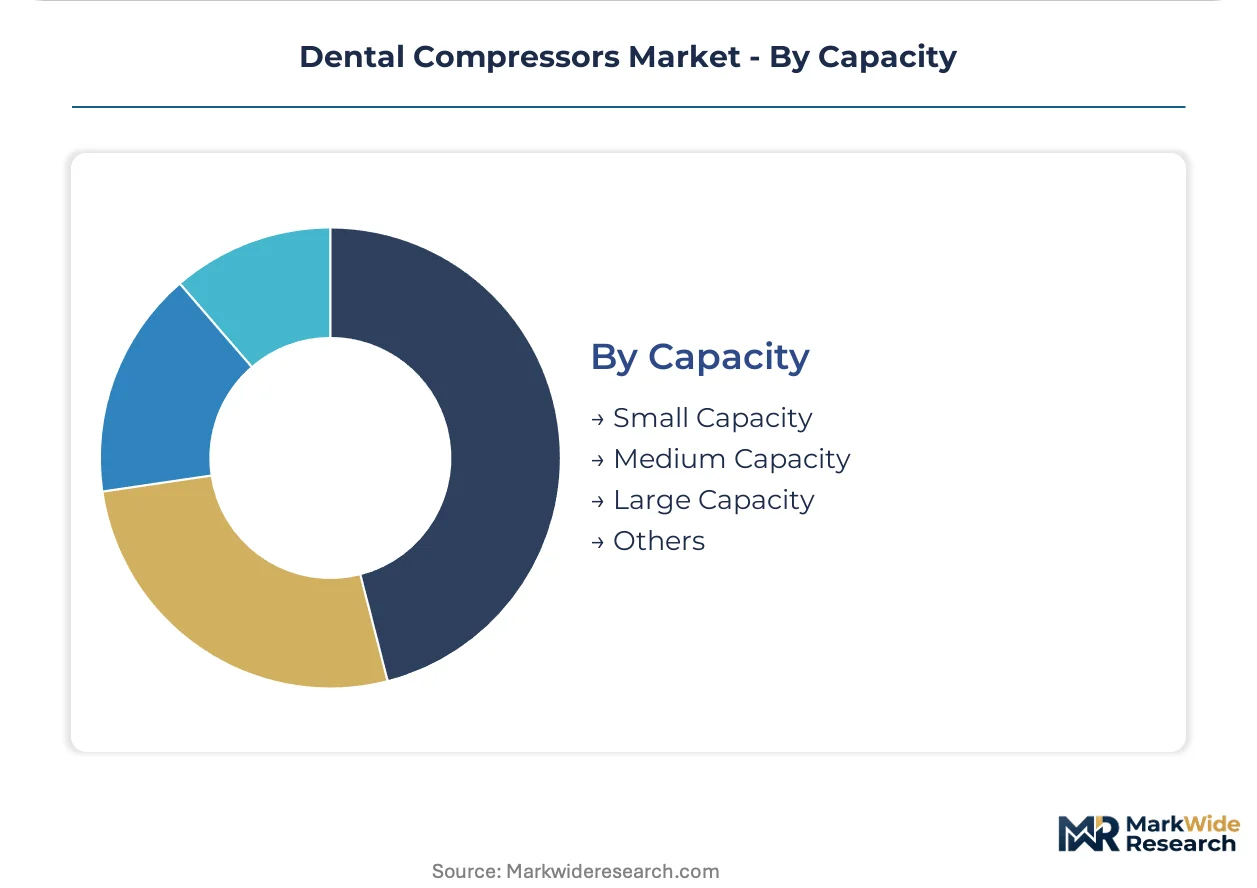
Capacity:
Treatment room count and simultaneous handpiece operation dictate sizing calculations for practice engineers.
- Small Capacity:Single-chair installations and mobile units utilize compressors below 50 liters per minute output. Solo practitioner clinics in China's Tier-3 cities are driving small-capacity oil-free demand as dental infrastructure expands.
- Medium Capacity:Two-to-four chair practices specify 50-150 LPM systems balancing redundancy with capital efficiency. Medium-capacity scroll compressors are gaining preference in German group practice formations.
- Large Capacity:Centralized systems exceeding 150 LPM serve academic facilities and large clinic chains through manifold distribution. United States dental schools are specifying variable-speed drive large-capacity units to match demand fluctuations across teaching schedules.
- Others:Custom-engineered solutions address atypical pressure or purity requirements outside standard product ranges. Specialty configurations support hyperbaric dental medicine and aerospace dentistry applications.
Medium Capacity leads on scale; Large Capacity leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dental compressor manufacturing traces its industrial lineage to German precision engineering traditions established in the mid-20th century, with subsequent scaling in United States clinic infrastructure and more recent capacity expansion across Chinese medical device clusters.
United States
Dental service organizations exceeding fifty locations drive centralized procurement of redundant compressor configurations to minimize treatment room downtime. FDA device quality system regulations elevate documentation requirements for hospital procurement committees. The Greater Boston and Pacific Northwest medical device corridors host compressor distribution networks serving academic dental centers.
Germany
Group practice formations in Bavaria and North Rhine-Westphalia specify scroll compressors for noise compliance in premium clinic environments. EU Medical Device Regulation conformity deadlines compress replacement cycles for legacy systems. The Baden-Württemberg precision engineering cluster anchors oil-free compression component supply chains serving European OEMs.
China
Tier-2 and Tier-3 city clinic expansion generates demand for mid-range oil-free compressors as dental infrastructure modernizes. NMPA streamlined certification pathways reduce regulatory friction for qualified suppliers. The Yangtze River Delta medical device manufacturing belt concentrates domestic assembly partnerships for international compressor brands.
India
Solo practitioner clinics in Maharashtra and Gujarat drive small-capacity oil-free demand as rural dental access programs expand. Production-linked incentive schemes for medical device manufacturing reduce landed cost disadvantages for domestic assembly. The Karnataka medical technology corridor hosts emerging compressor component fabrication capacity.
Japan
Academic medical centers in Tokyo and Osaka specify large-capacity variable-speed drive systems to match demand fluctuations across teaching schedules. METI energy efficiency standards tighten requirements for compressor cooling circuit thermal management. The Nagoya precision machinery cluster supplies permanent magnet materials for premium scroll compressor motors.
Dental Compressors Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and noise-performance dimensions in dental compressor supply. The vendor base organizes into three tiers: integrated delivery system specialists commanding group purchasing organization contracts, precision engineering houses dominating oil-free scroll technology, and regional fabricators serving cost-sensitive replacement demand. Consolidation pressure intensifies as dental service organization networks centralize procurement authority. Two dominant competitive moves define current positioning: direct manufacturer relationships bypassing traditional equipment dealers, and predictive maintenance service revenue unbundling through IoT-enabled compressor-as-a-service models.
Within the integrated delivery system tier, Midmark Corporation anchors North American clinic infrastructure positioning. Among German precision engineering houses, Dürr Dental GmbH & Co. KG exemplifies oil-free compression platform leadership. Air Techniques, Inc. occupies a position in United States dental distribution network control. These three entities represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Midmark Corporation |
| Dürr Dental |
| Air Techniques |
| Kaeser Dental |
| Quincy Compressors |
| General Air Products |
| Gnatus |
| Aixin Medical Equipment Co. |
| DENTALEZ |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between ISO 8573-1 Class 0 oil-free systems and legacy oiled compressors manifests in divergent pricing architectures and supply chain footprints. Premium scroll compressors command substantial markups through German precision engineering while commodity reciprocating units face margin compression from Asian fabricators, with procurement patterns splitting between direct manufacturer relationships for high-end clinic infrastructure and dealer networks for replacement demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates scroll-based oil-free systems from rotary alternatives and legacy reciprocating units. Price differentiation hinges on ISO 8573-1 certification grade and acoustic performance thresholds, with sub-55 dB specifications carrying substantial premiums. Cost compression in the economy tier is intensifying because copper and rare earth input volatility erodes fabricator margins. Dental service organizations with fifty-plus locations exhibit lowest price sensitivity, while solo practitioners in emerging markets drive hard bargaining on small-capacity units.
Supply Chain Analysis
India's PLI scheme and China's NMPA localization incentives are reshaping component sourcing patterns for compressor OEMs targeting Asian markets. Precision manufacturing concentrates in Germany, Japan, and the United States, with Baden-Württemberg and Nagoya clusters supplying PTFE-coated pistons and permanent magnet motor assemblies. Supply chain risk centers on single-source vulnerability for rare earth magnet feedstock from concentrated extraction zones. Distribution runs through group purchasing organizations for multi-site clinic chains and traditional dental equipment dealers for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental compressors market functions as a stable compounder anchored by irreversible clinic infrastructure modernization and non-negotiable air quality regulatory thresholds that sustain replacement cycles.
For Market Incumbents: Extend predictive maintenance service capabilities through IoT sensor integration to capture recurring revenue streams as hardware margins compress. Deepen backward integration into oil-free scroll component fabrication to reduce exposure to German and Japanese precision engineering supply bottlenecks. Fortify group purchasing organization relationships before dental service organization procurement centralization eliminates dealer intermediaries entirely.
For New Entrants and Emerging Players: Direct-to-practitioner digital platforms bypass entrenched distribution networks and enable rapid penetration of India's Tier-2 and Tier-3 city expansion. Target China's mid-range oil-free segment where NMPA streamlined certification reduces incumbent regulatory moats. Pursue compressor-as-a-service subscription models in North American group practices to displace capital purchase decisions with operational expenditure frameworks.
For Investors and Strategic Acquirers: Consolidation pressure builds where dental service organization networks exceed fifty locations and procurement authority concentrates. The five-to-ten year viability window favors precision engineering specialists with captive ISO 8573-1 certification capabilities over commodity fabricators. Monitor scroll compressor patent expiration schedules as inflection indicators for technology diffusion and margin normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Predictive Maintenance Platform | Transforms capital equipment economics into recurring service revenue for GPO-affiliated practices. |
| Backward Integration into Scroll Component Manufacturing | Reduces dependency on Baden-Württemberg precision engineering clusters for oil-free mechanisms. |
| ISO 8573-1 Class 0 Certification Investment | Establishes non-negotiable procurement filters for EU MDR-compliant clinic infrastructure. |
| Direct Manufacturer Contracting with Dental Service Organizations | Bypasses traditional dealer networks as procurement authority concentrates in fifty-plus location chains. |
| India PLI Scheme Alignment for Domestic Assembly | Reduces landed cost disadvantages against emerging local fabricators in Maharashtra and Gujarat markets. |
Research Approach
Bottom-up clinic infrastructure modeling reconciled against top-down compressor manufacturing tracking forms the analytical core of this study. Primary interviews with dental equipment procurement managers, biomedical engineers at academic medical centers, GPO contracts specialists, and aftermarket service technicians combined with secondary validation against FDA 510(k) filings, EU MDR notified body certifications, NMPA registration databases, and dental trade association shipment statistics. This dual approach enables cross-verification of installation base estimates against production volumes reported by German and Asian OEMs.
Input-output matrices map compressor deployment density per treatment room against procedural volume projections across the analysis window. Segmentation dimensions include technology mechanism, capacity tier, end-user setting, and regional regulatory cluster. CAGRs derive from installed base turnover rates and new clinic build-out schedules rather than extrapolated trend lines. Forecast inputs incorporate scroll technology displacement curves and variable-speed drive penetration assumptions for premium clinic environments.
The model assumes a particular technology adoption path; alternative pathways for oil-free scroll compression would alter the outlook if reciprocating efficiency improvements or novel diaphragm architectures disrupt current substitution patterns. Forecasts reflect assumptions regarding EU MDR enforcement intensity and China dental infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Dental Engine Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Digital Dental Equipment Market