
 Europe Data Center Power Market | 2026-2036
Europe Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Power Market Analysis
Copper busbar systems is hardening as the preferred conductor material over traditional aluminum in high-density power distribution, reducing resistive losses in megawatt-scale facilities. Schneider Electric leverages integrated microgrid architectures to anchor its position across Nordic and Western European deployments. ABB sustains technology leadership through its solid-state circuit breaker portfolio designed for direct current data center topologies. Eaton competes on modular UPS platforms that enable rapid capacity scaling without full facility shutdowns.
Europe data center power encompasses the generation, conditioning, distribution, and backup infrastructure that ensures continuous electrical supply to server halls, with systems typically operating at voltages from 400V AC up to 1500V DC in next-generation designs and requiring redundancy tiers from N+1 to 2N per Uptime Institute standards. UPS systems dominate current procurement volumes as facility operators prioritize ride-through capacity during grid instability events across Continental Europe. Generator sets represent the fastest-growing power type segment as diesel-to-hydrotreated vegetable oil conversion programs accelerate under national decarbonization timelines. Power distribution units command concentrated margin pools in colocation environments where tenants demand granular metering and remote switching capabilities.
The EU Green Deal and F-Gas Regulation are tightening permissible refrigerants and energy efficiency thresholds for cooling-dependent power infrastructure, while CE marking and the EU AI Act establish conformity requirements for autonomous energy management systems. Germany's KBA and national building codes in the Netherlands enforce specific standby power duration mandates that shape generator sizing specifications. Stakeholders must monitor evolving carbon border adjustment mechanisms and national renewable energy certificate schemes that will determine locational cost competitiveness for new hyperscale investments.
Market Dynamics
Hyperscale cloud operators in Northern Europe are compressing deployment timelines from 36 months to 18 months, forcing power infrastructure suppliers to pre-validate modular architectures before site selection concludes. This acceleration is compressing supplier qualification windows and rewiring procurement relationships across the value chain.
Growth Catalysts
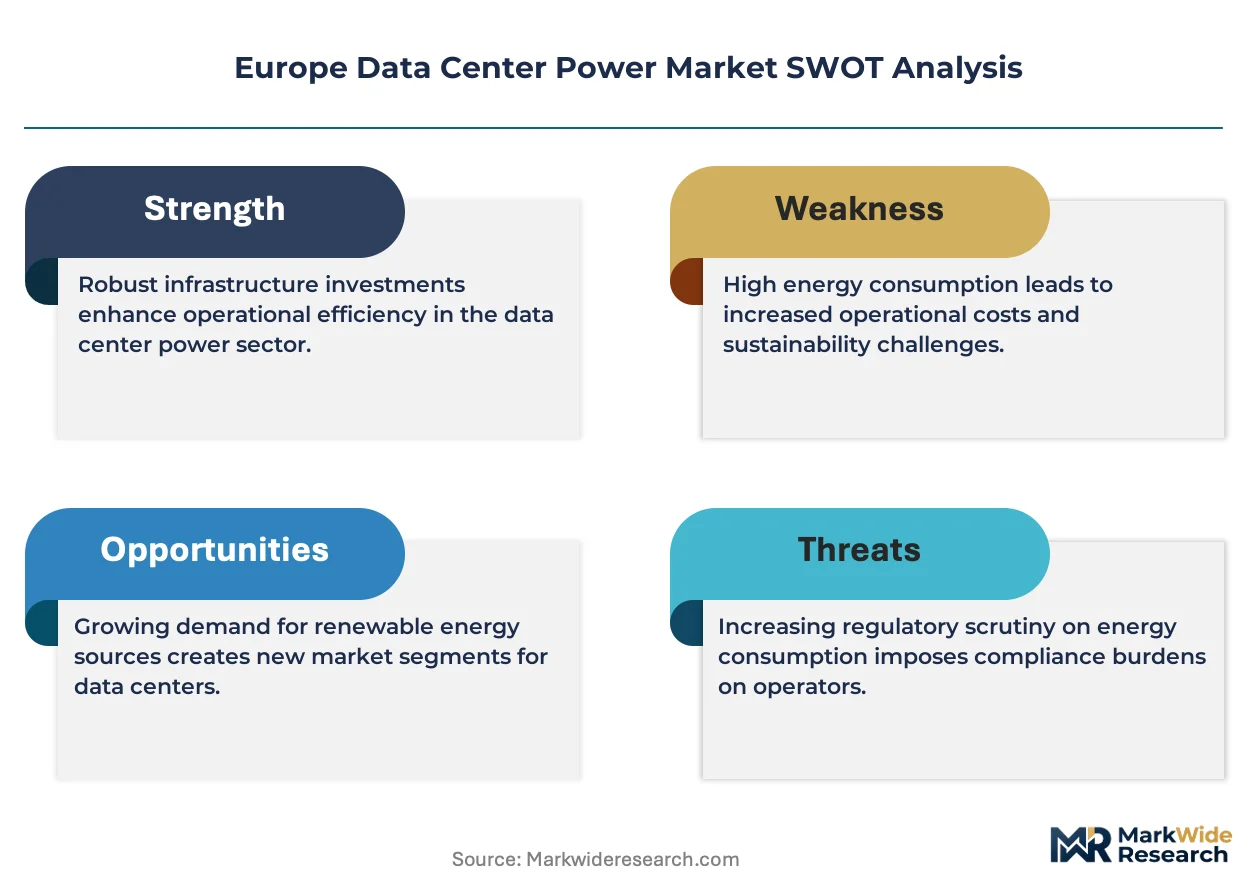
- EU Green Deal carbon neutrality mandates:National deadlines for net-zero data center operations in Ireland and the Netherlands are accelerating liquid cooling retrofits and renewable power purchase agreements.
- Hydrotreated vegetable oil conversion programs:Germany's KBA standby power duration requirements are driving diesel-to-HVO generator set upgrades across Frankfurt and Berlin metro facilities.
- Fiber connectivity clusters:Dense fiber landing points in Amsterdam, Dublin, and Frankfurt are concentrating hyperscale investment and pulling specialized medium-voltage switchgear demand.
Market Restraints
- Copper price volatility:Resistive loss advantages of copper busbar systems are eroding as LME copper price swings compress margins on fixed-price infrastructure contracts.
- CE marking delays for DC topologies:Solid-state circuit breakers operating above 1000V DC face extended conformity assessment timelines under evolving LV directive interpretations.
- Grid interconnection queues:Transmission system operator backlogs in Germany and the Netherlands are extending energization timelines for new facilities beyond 24 months.
Strategic Opportunities
- Nordic subsea cable expansion:New fiber routes into Norway and Sweden are opening greenfield sites with access to stranded hydroelectric capacity and favorable cooling economics.
- EU AI Act autonomous energy management:Conformity requirements for AI-driven load balancing are creating first-mover advantages for suppliers with pre-certified control platforms.
- Colocation tenant metering granularity:Power distribution units with circuit-level monitoring are capturing margin pools as multi-tenant facilities unbundle energy costs from rack rates.
Industry Challenges
- Medium-voltage technician scarcity:Specialized commissioning expertise for 10-35kV switchgear is concentrated among aging contractor networks across Continental Europe.
- Legacy AC-DC conversion retrofit complexity:Existing facilities designed around 400V AC distribution face structural barriers to 1500V DC topology upgrades without full hall decommissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Power Market |
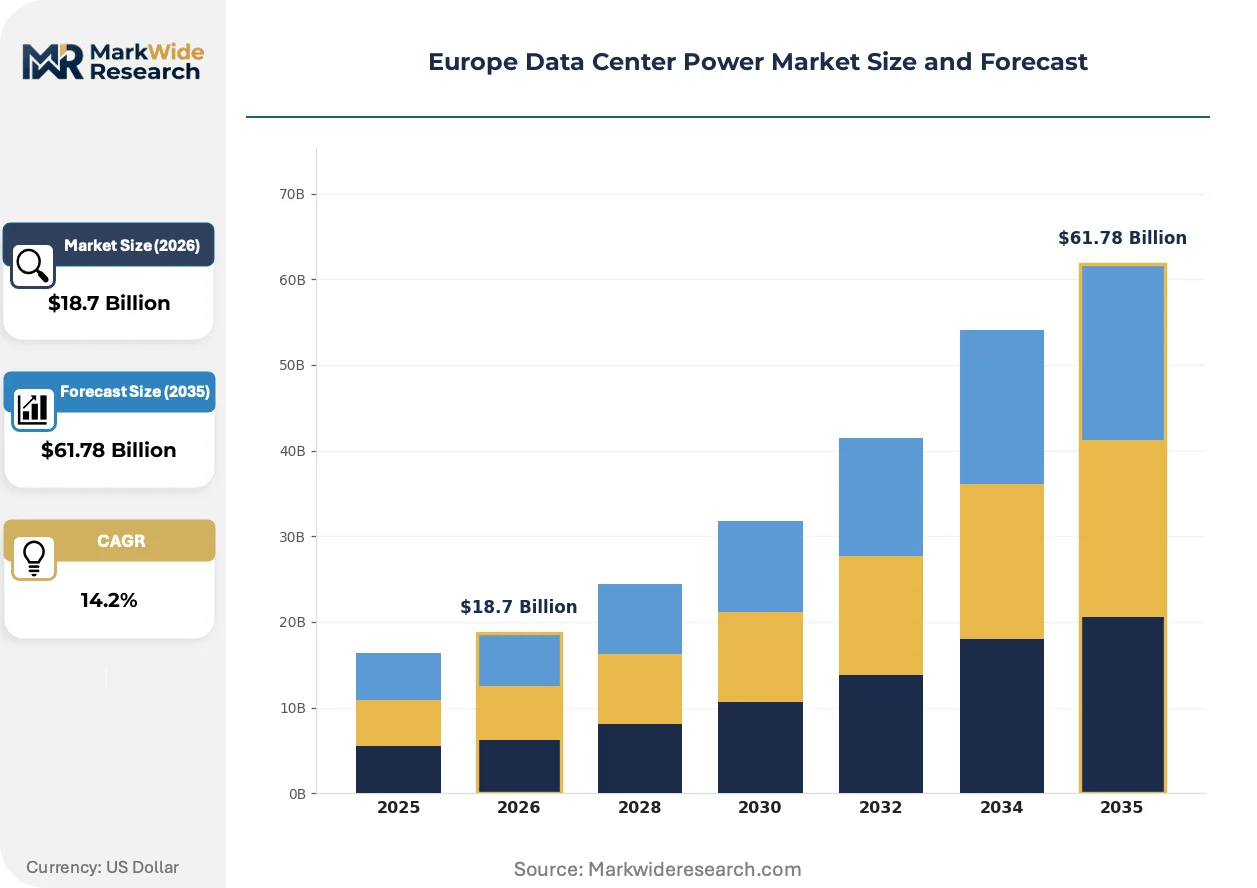
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS, Generator, Power Distribution Unit, Power Processor End User: Telecom, Cloud Service Providers, Colocation Providers, Enterprise Installation Type: On-Premises, Hybrid, Modular, Edge Power Capacity: High, Medium, Low, Variable |
| Companies Covered | Schneider Electric, ABB, Eaton, Vertiv, Legrand, Delta Electronics, Siemens, Cummins, nVent Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Power Market Emerging Trajectories
Power distribution architecture is fragmenting from centralized UPS halls toward rack-integrated energy storage, compressing fault domains and rewiring vendor competitive boundaries. This shift is redistributing value capture from traditional electrical infrastructure suppliers toward battery and power semiconductor specialists.
Direct current microgrids are decentralizing power conversion from facility-scale to rack-scale, embedding solid-state transformers within server rows. Hyperscale operators in Ireland and the Netherlands are piloting 380V DC bus architectures that eliminate double-conversion losses. This topology is decentralizing UPS redundancy from N+1 facility blocks to N+1 rack-level modules, reducing stranded capacity in partially loaded halls.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cooling-dependent power infrastructure, forcing thermal design recalibration for generator set enclosures and switchgear rooms. Equipment suppliers are redesigning heat rejection systems around CO2 and propane alternatives. German and Dutch facilities face the tightest compliance timelines, with 2027 service bans accelerating replacement cycles for aging infrastructure.
Colocation buyers are consolidating vendor relationships around integrated power-cooling-monitoring stacks, displacing best-of-breed component procurement. This bundling is compressing supplier count per facility from 8-12 to 3-4 primary contractors. The Netherlands and Frankfurt markets exhibit the most pronounced consolidation, as operators seek single-skin accountability for PUE guarantees and carbon reporting.
Europe Data Center Power Market Segmentation
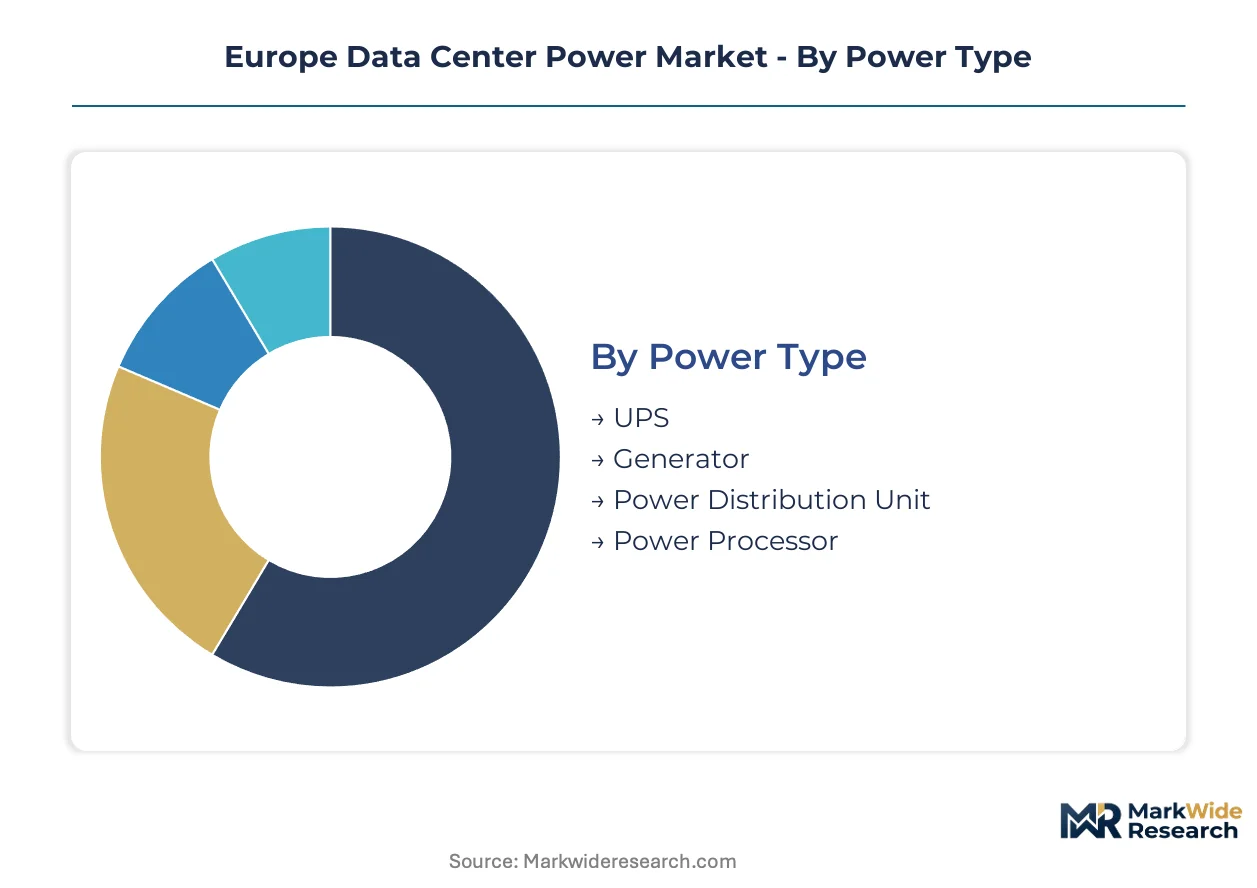
Power infrastructure procurement in Europe diverges sharply by operational criticality and facility scale. Hyperscale operators prioritize modular architectures with rapid deployment cycles, while enterprise buyers emphasize legacy compatibility over efficiency gains.
Power Type:
Capital allocation intensity and redundancy tier requirements determine supplier selection across this dimension.
- UPS:Double-conversion and line-interactive topologies dominate facility-scale deployments across Frankfurt and Amsterdam clusters. Ride-through capacity during grid instability events drives procurement volumes in Germany and the Netherlands where transmission congestion is most acute.
- Generator:Diesel-to-hydrotreated vegetable oil conversion programs accelerate replacement cycles under Germany's KBA standby power duration mandates. HVO-compatible generator sets are capturing upgrade budgets across Berlin and Frankfurt metro facilities facing national decarbonization timelines.
- Power Distribution Unit:Circuit-level metering granularity captures margin pools in multi-tenant colocation environments.
- Power Processor:Solid-state transformer integration enables rack-level DC microgrid architectures in pilot Irish facilities.
Volume sits with UPS systems; growth tilts toward generator sets.
End User:
Tenant density and power density requirements fragment procurement specifications across buyer categories.
- Cloud Service Providers:Hyperscale operators compress deployment timelines from 36 months to 18 months, forcing pre-validated modular architectures. Northern Europe capacity expansion concentrates demand for medium-voltage switchgear with factory acceptance testing completed before site selection concludes.
- Colocation Providers:Multi-tenant facilities unbundle energy costs from rack rates, driving circuit-level monitoring integration. Amsterdam and Frankfurt markets exhibit the most pronounced vendor consolidation around integrated power-cooling-monitoring stacks.
- Telecom:Edge computing deployments pull distributed UPS requirements across rural fiber extension routes.
- Enterprise:Legacy 400V AC compatibility constraints slow DC topology adoption in financial services clusters.
Cloud service providers command the largest absolute spend; colocation providers are expanding most quickly.
Installation Type:
Real estate constraints and energization timelines shape architecture selection across European markets.
- Modular:Prefabricated electrical skids enable parallel construction tracks, compressing facility commissioning in grid-constrained German markets. Factory-built power modules with integrated testing reduce on-site commissioning risk where medium-voltage technician scarcity is most acute.
- Hybrid:On-premises generation paired with grid interconnection balances reliability against carbon reporting requirements in Dutch facilities.
- On-Premises:Traditional build-out persists in enterprise-owned facilities with long asset depreciation schedules.
- Edge:Sub-1MW deployments proliferate along Nordic subsea cable landing extensions.
Hybrid installations hold current volume leadership; modular architectures are gaining share fastest.
Power Capacity:
Density gradients and cooling economics determine capacity tier distribution across facility types.
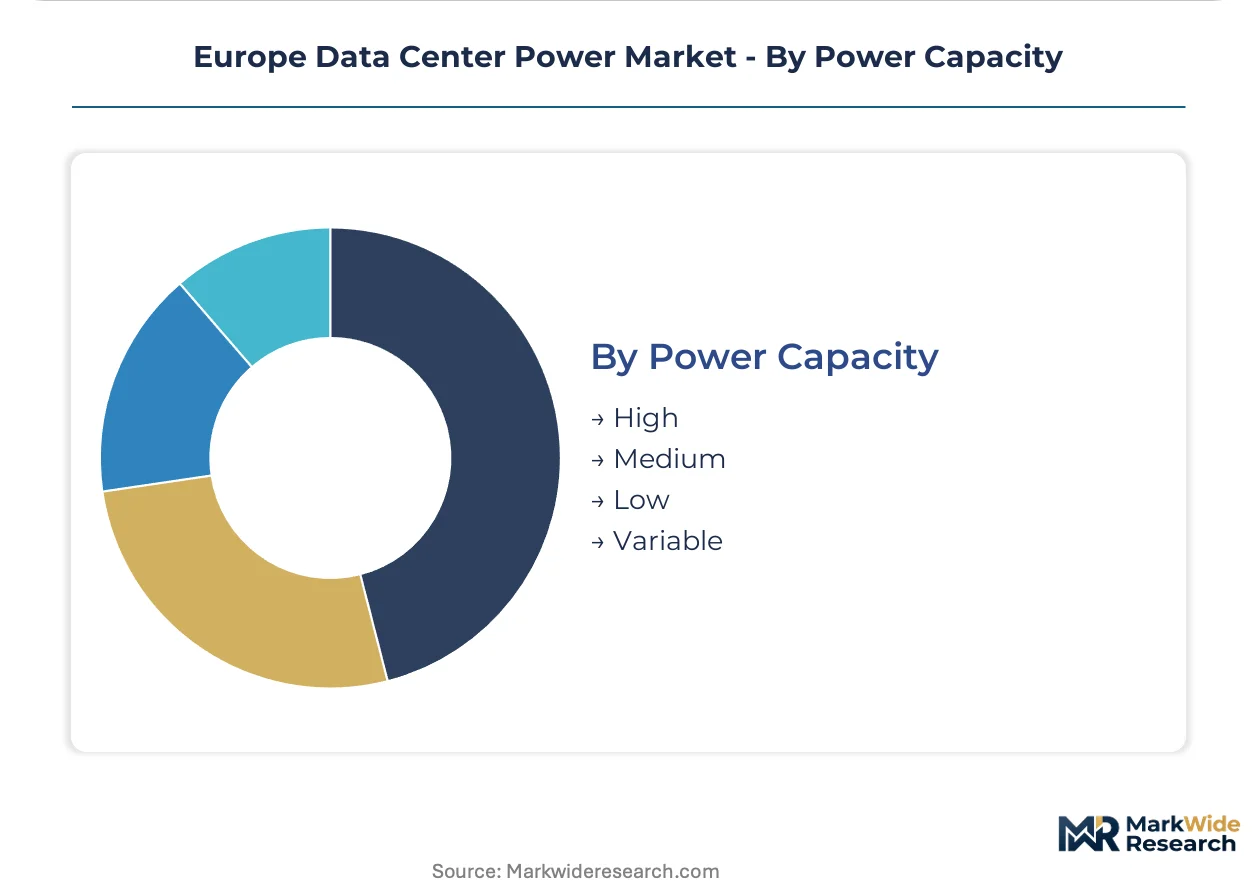
- High:Megawatt-scale halls above 10MW dominate hyperscale construction in Ireland and the Netherlands. Liquid cooling integration enables rack densities exceeding 50kW, rewiring power distribution from centralized UPS halls toward rack-integrated energy storage.
- Medium:2-10MW facilities serve regional cloud availability zones and wholesale colocation in Frankfurt secondary markets.
- Low:Sub-2MW enterprise and edge deployments concentrate in secondary Nordic cities with stranded hydroelectric access.
- Variable:Dynamic scaling architectures accommodate AI training workload fluctuations in pilot Dutch facilities.
High-capacity facilities absorb the majority of capital deployment; variable capacity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amsterdam's freeport zone status and Dublin's 12.5% corporate tax rate have concentrated hyperscale investment across Northern Europe, rewiring power infrastructure demand toward modular architectures with rapid deployment cycles.
Germany
Frankfurt's dense fiber landing points and KBA standby power mandates are driving diesel-to-HVO generator conversions. The EU Green Deal carbon neutrality deadlines accelerate liquid cooling retrofits across Berlin metro facilities. Bavarian data centers face extended grid interconnection queues exceeding 24 months.
Ireland
Dublin's favorable tax regime has attracted hyperscale cloud operators compressing deployment timelines to 18 months. National net-zero mandates for data center operations by 2030 force renewable power purchase agreement structures. Cork and Limerick secondary markets absorb overflow capacity with stranded wind access.
Netherlands
Amsterdam's fiber connectivity clusters concentrate medium-voltage switchgear demand from multi-tenant colocation operators. National building codes enforce specific standby power duration requirements shaping generator specifications. Eindhoven and Rotterdam secondary markets exhibit pronounced vendor consolidation around integrated power-cooling stacks.
Sweden
Stranded hydroelectric capacity in northern regions enables sub-1MW edge deployments along subsea cable extensions. Favorable cooling economics attract pilot 380V DC microgrid architectures. Stockholm's emerging cluster faces medium-voltage technician scarcity during commissioning phases.
United Kingdom
London's financial services clusters maintain legacy 400V AC compatibility constraints slowing DC topology adoption. Slough and Docklands data center concentrations prioritize ride-through UPS capacity during grid instability. National grid decarbonization targets pull renewable-backed colocation procurement.
Europe Data Center Power Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated stack providers capturing colocation relationships while component specialists defend position in hyperscale direct procurement. The supplier base concentrates around three strategic archetypes: diversified electrical conglomerates with microgrid capabilities, power semiconductor specialists enabling DC topology transitions, and modular UPS fabricators with factory pre-validation programs. Competitive moves center on geographic expansion into Nordic greenfield sites and portfolio diversification toward rack-integrated energy storage.
Among diversified electrical conglomerates, Schneider Electric, ABB, and Eaton exemplify the integrated infrastructure archetype. Schneider Electric anchors its position through microgrid architectures across Nordic and Western European deployments. ABB occupies a position representing solid-state circuit breaker technology for emerging DC topologies. Eaton sits within the modular UPS tier enabling rapid capacity scaling without facility shutdowns.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Vertiv |
| Legrand |
| Delta Electronics |
| Siemens |
| Cummins |
| nVent Electric |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between CE-marked DC-ready architectures and legacy AC systems splits both procurement budgets and supplier qualification pathways across European data center developments. Hyperscale operators in Ireland and the Netherlands pay premiums for pre-validated modular skids with factory acceptance testing completed, while enterprise buyers in Germany absorb longer lead times for custom-configured switchgear assemblies.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent apply to medium-voltage switchgear with factory acceptance testing pre-completed before site selection concludes. Project-based long-term contracting dominates hyperscale procurement, with price differentiation anchored in CE marking tier and renewable energy certificate bundling. Cost compression in standard-tier UPS modules intensifies as Chinese manufacturers expand European distribution. Enterprise financial services clusters in London exhibit highest price sensitivity due to legacy depreciation schedules, while Dutch colocation operators show lowest sensitivity given PUE guarantee penalties.
Supply Chain Analysis
Reverse-logistics flows for generator set refurbishment concentrate in Germany and the Netherlands where KBA-mandated HVO conversion programs extend equipment lifecycles. Manufacturing concentration rests on Germany, France, and China for power semiconductor components and copper busbar assemblies. Raw material dependencies center on LME copper, silicon carbide substrates, and rare-earth magnetic materials. Single-source vulnerability persists for solid-state circuit breaker IGBT modules above 1000V DC. Distribution runs through direct OEM relationships for hyperscale procurement and electrical wholesale channels for enterprise retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a cost-of-compliance moat that favors incumbent suppliers with pre-certified thermal management platforms and refrigerant transition roadmaps already validated.
For Market Incumbents: Anticipate margin compression in standardized UPS modules as modular fabricators from Asia expand European distribution networks. Defensive consolidation should prioritize backward integration into power semiconductor sourcing and captive production of rack-integrated battery systems. CE marking pre-certification for 1500V DC topologies represents a critical capability lever against emerging solid-state transformer specialists. For New Entrants and Emerging Players: EU AI Act conformity requirements in the Netherlands open a window for autonomous energy management software vendors with pre-certified control platforms. White-space targets include circuit-level metering integration for Amsterdam colocation facilities and stranded hydroelectric site development in northern Sweden. A direct-to-hyperscale technical sales model with factory pre-validation programs offers the most penetrable go-to-market angle against entrenched electrical conglomerates. For Investors and Strategic Acquirers: Re-rating potential sits with power semiconductor specialists enabling DC topology transitions given hyperscale pilot deployments accelerating across Ireland. Long-term viability favors acquisition targets with solid-state circuit breaker portfolios and existing CE marking above 1000V DC. Monitor Nordic subsea cable energization announcements as inflection indicators for stranded renewable capacity absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive sourcing of silicon carbide substrates reduces exposure to single-source IGBT module constraints from German suppliers. |
| CE Marking Pre-Certification for 1500V DC | Early conformity assessment completion accelerates hyperscale procurement cycles in Netherlands and Ireland pilot facilities. |
| HVO-Compatible Generator Set Portfolio | Germany's KBA standby power mandates drive replacement demand across Frankfurt and Berlin metro facilities. |
| Rack-Integrated Battery Storage Development | Distributed energy architecture captures value migration from centralized UPS halls toward fault-domain compression. |
| Nordic Subsea Cable Landing Partnerships | Stranded hydroelectric access in Sweden and Norway enables greenfield site development with favorable cooling economics. |
Methodological Framework
Multi-period observation of hyperscale capex disclosures, grid interconnection queue data, and renewable power purchase agreement registrations anchored the trend analysis, supplemented by interviews with data center engineering directors, electrical infrastructure procurement managers, EPC contractors, and medium-voltage commissioning technicians. Secondary validation drew from EU F-Gas Regulation implementation reports, CE marking databases, transmission system operator filings, and facility permitting records across Germany, Ireland, the Netherlands, and Sweden. Bottom-up facility-level capacity aggregation and top-down supplier revenue analysis were triangulated for cross-verification.
Input-output matrix modeling connected power capacity deployment schedules to component procurement volumes across the projection horizon. Segmentation dimensions included power type, end user category, installation architecture, and capacity tier, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from fitted growth curves applied to validated base-year estimates, incorporating stranded renewable capacity absorption rates and liquid cooling retrofit penetration as forecast inputs.
Caveats apply where grid interconnection queue extensions beyond twenty-four months or copper price volatility spikes could materially shift the outlook for facility energization timelines. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and national carbon neutrality deadline adherence. Practitioners should monitor Nordic subsea cable construction milestones and F-Gas Regulation refrigerant phase-down compliance for early signals of supply chain constraint or demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Global Data Center Rack Server Market