
 Data Center in Japan Market | 2026-2036
Data Center in Japan Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center in Japan Market Insights
The F-Gas Regulation is decoupling legacy cooling infrastructure from viable facility economics, forcing operators to absorb capital costs for refrigerant transition or face stranded asset risk. NTT Ltd leverages its domestic fiber network to anchor hyperscale developments across Greater Tokyo. Equinix Inc. competes through interconnection density at its Osaka and Tokyo International Business Exchange campuses. Digital Realty Trust Inc. sustains global account consistency by extending standardized design protocols into its Narita and Osaka facilities.
A data center in Japan constitutes a dedicated facility housing servers, storage systems, and networking equipment with redundant power distribution, precision cooling maintaining NEMA or JIS temperature bands, and physical security protocols serving enterprise and cloud workloads. These installations process domestic transaction flows, host sovereign cloud instances, and enable low-latency delivery of financial and media content across East Asia. Colocation services dominate revenue generation among service type segments as enterprises retreat from owned infrastructure. Edge computing deployments within the technology dimension are expanding fastest, driven by 5G latency requirements and factory automation networks in Aichi and Fukuoka prefectures. Hyperscale capacity additions command disproportionate capital allocation despite representing a minority of facility count, reflecting margin concentration at scale.
METI enforces energy efficiency standards through facility certification programs that constrain power usage effectiveness ratios for new construction. JIS standards govern fire suppression and electrical infrastructure specifications, while local prefectural ordinances in Tokyo and Osaka impose additional seismic resilience requirements beyond national building codes. Stakeholders must weigh land scarcity in primary metro zones against METI incentives for regional dispersal when committing to decade-long capacity planning cycles.
Market Dynamics
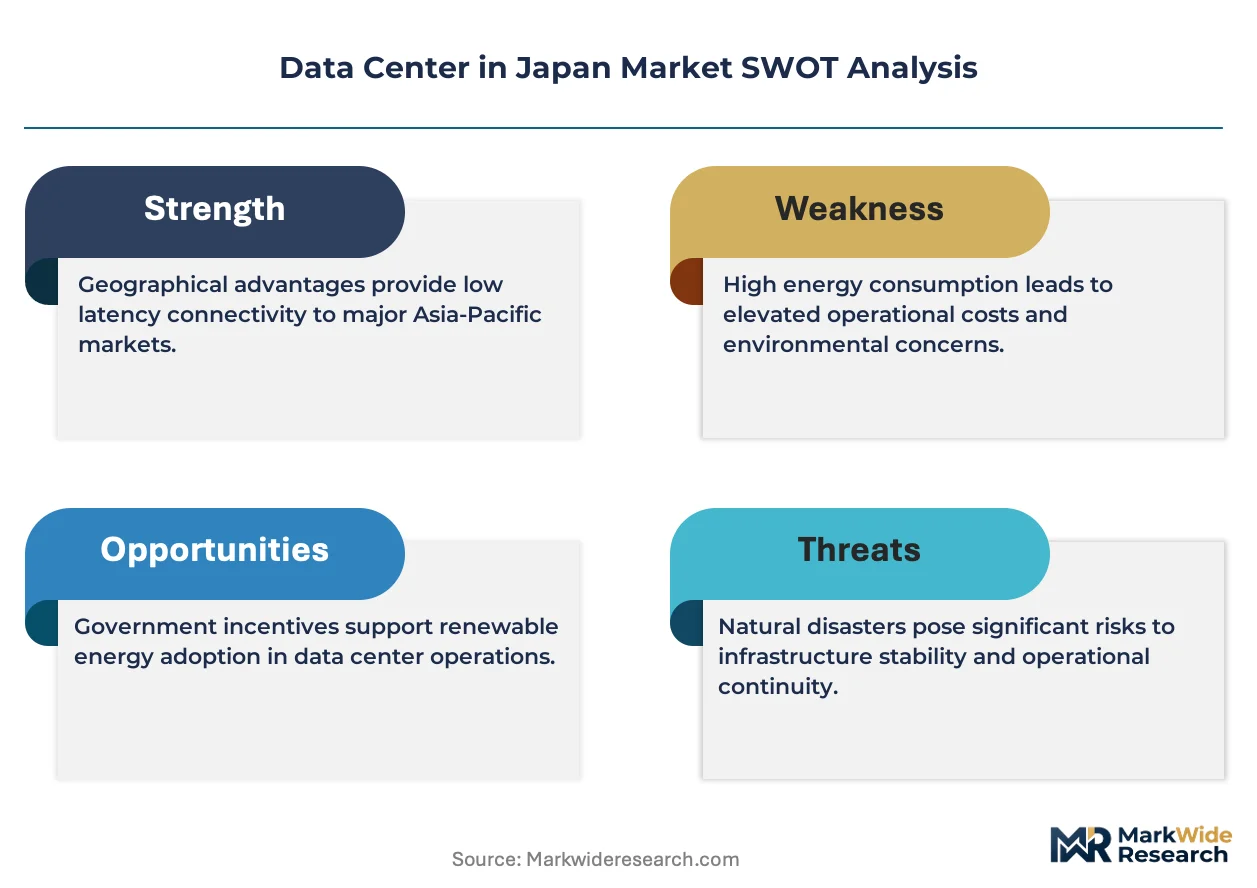
Japan's data center sector faces a structural squeeze between METI's Green Transformation mandates and the concentration of viable development land in Chiba and Saitama prefectures, forcing operators to choose between retrofitting legacy cooling or accepting stranded asset exposure.
Growth Catalysts
- Hyperscale Demand:Financial services firms are expanding colocation footprints as cloud migration accelerates transaction processing requirements. Sovereign cloud deployments for government workloads add incremental capacity absorption.
- 5G Edge Requirements:Factory automation networks in Aichi and Fukuoka prefectures are driving low-latency edge computing deployments. Manufacturing IoT clusters require localized processing to meet sub-10 millisecond response thresholds.
- METI Efficiency Incentives:Regional dispersal subsidies encourage facility development outside power-constrained Greater Tokyo zones. Certified green buildings receive accelerated permitting for renewable energy interconnection.
Market Restraints
- F-Gas Compliance Costs:The EU F-Gas Regulation's extraterritorial impact on imported cooling equipment forces refrigerant transition investments. Legacy chiller replacement cycles compress to avoid stranded infrastructure.
- Seismic Construction Premiums:Tokyo and Osaka prefectural ordinances impose resilience requirements beyond national building codes. Reinforced foundation specifications add 15-25% to structural capital expenditure.
- Land Scarcity Concentration:Developable parcels with adequate substation capacity cluster in Chiba and Saitama, creating bidding competition among operators. Central Tokyo sites face absolute power availability ceilings.
Strategic Opportunities
- Osaka-Kansai Expansion:Underpenetrated capacity relative to Tokyo creates arbitrage for disaster recovery and secondary site deployment. Kansai Electric Power offers more favorable industrial rate structures than TEPCO zones.
- Liquid Cooling Convergence:Direct-to-chip and immersion technologies address density constraints in existing floorplates. Heat reuse integration with district heating networks unlocks municipal partnership revenue.
- Submarine Cable Anchoring:New transpacific cable landings at Shima and Maruyama create interconnection monetization potential. Cable station adjacency commands premium cross-connect pricing.
Industry Challenges
- Specialized Technician Scarcity:Precision cooling and high-voltage electrical certification programs produce insufficient graduates. Experienced facility engineers command compensation premiums that compress operating margins.
- Legacy System Integration:Enterprise migration from owned infrastructure to colocation requires hybrid architecture management. Mainframe connectivity and bespoke storage protocols extend onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center in Japan Market |
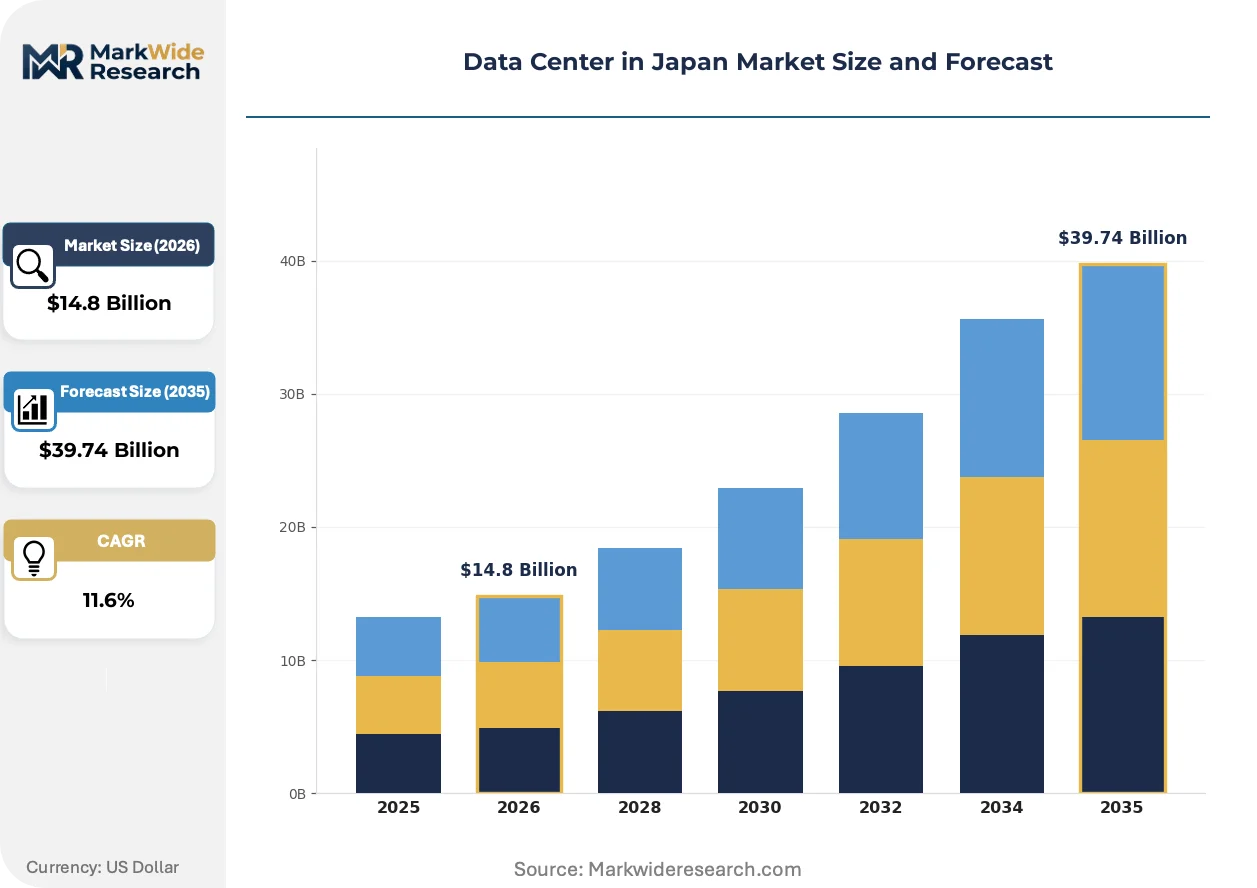
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Co-location, Cloud Services, Managed Hosting, Disaster Recovery Technology: Virtualization, Containerization, Hyperconverged Infrastructure, Edge Computing End User: Financial Services, IT & Telecom, Government, Healthcare Capacity: Small Scale, Medium Scale, Large Scale, Hyperscale |
| Companies Covered | NTT Ltd, Equinix Inc., Digital Realty Trust Inc., IDC Frontier Inc., NEC Corporation, NTT Communications, Colt Technology Services, AirTrunk, ST Telemedia Global Data Centres, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center in Japan Market Trends and Innovations
Japanese data center architecture is pivoting from air-cooled standard designs toward liquid-cooled and AI-optimized infrastructure, driven by thermal density limits and METI efficiency enforcement.
Liquid cooling technology is absorbing heat loads exceeding 30 kilowatts per rack that traditional CRAC units cannot evacuate. Hyperscale operators in Saitama and Chiba are deploying direct-to-chip cold plates at pace, with immersion trials underway for GPU-intensive training clusters. This thermal architecture shift is absorbing capital that would otherwise flow to additional square footage, compressing facility expansion timelines.
METI's Green Transformation initiative mandates power usage effectiveness certification for new construction permits. Facility operators must demonstrate PUE ratios below national thresholds to qualify for grid interconnection priority. Tokyo-based developments face the strictest enforcement, accelerating adoption of free cooling and waste heat recovery systems.
Enterprise procurement of data center services is consolidating under master service agreements with standardized design protocols. Financial services buyers are unbundling real estate from managed services, selecting operators based on interconnection density rather than geographic proximity alone. This specification shift is most visible among Tokyo-headquartered securities firms establishing secondary processing sites in Osaka.
Data Center in Japan Market Segmentation
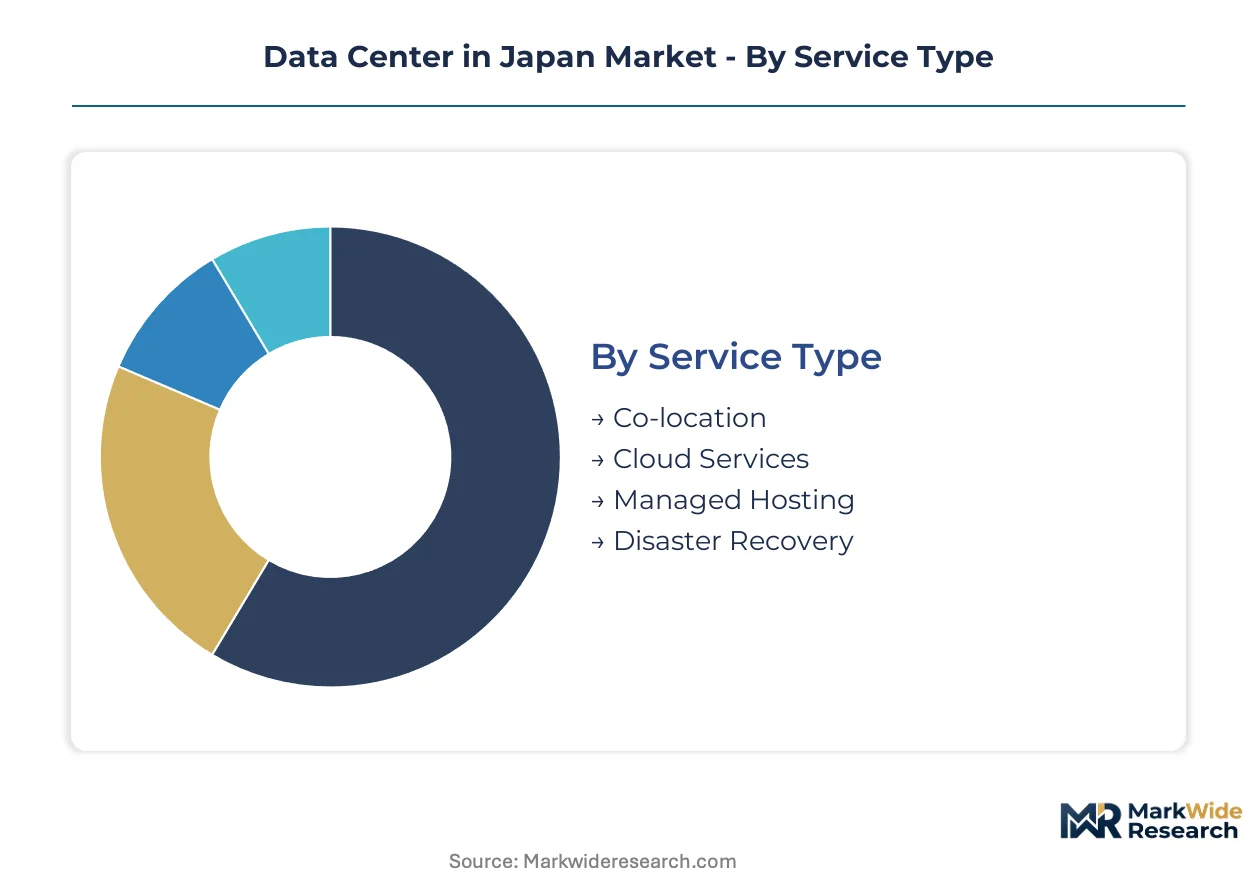
Segmentation in Japan's data center market reveals how METI certification requirements and regional power constraints reshape procurement priorities across service tiers. Buyers align infrastructure choices with specific compliance burdens and latency thresholds.
Service Type:
Colocation services require METI Green Transformation certification for facilities above certain power thresholds, while cloud and managed offerings face lighter direct facility obligations but heavier data sovereignty compliance.
- Co-location:Physical space leasing with power and cooling guarantees dominates revenue generation as financial services firms retreat from owned infrastructure. Tokyo-headquartered securities firms prioritize Chiba and Saitama facilities for primary workloads, driven by land availability and TEPCO grid access.
- Cloud Services:Sovereign cloud deployments for government workloads absorb incremental capacity under strict data localization mandates. METI incentives for regional dispersal encourage cloud operators to establish presence outside power-constrained Greater Tokyo zones.
- Managed Hosting:Operational outsourcing combining infrastructure with technical administration serves mid-market enterprises lacking in-house facility engineering expertise.
- Disaster Recovery:Secondary site replication services concentrate in Osaka-Kansai to exploit underpenetrated capacity and Kansai Electric Power's favorable industrial rate structures.
Co-location sits at the top of the volume ranking, with cloud services climbing the fastest.
Technology:
Technology choices stratify by thermal density tolerance and JIS electrical infrastructure compatibility, with edge and containerized workloads demanding distinct certification pathways from traditional virtualization stacks.
- Edge Computing:Distributed micro-facilities processing factory automation networks in Aichi and Fukuoka prefectures require sub-10 millisecond response thresholds. 5G latency requirements and manufacturing IoT clusters drive deployment fastest outside Tokyo's core congestion.
- Containerization:Kubernetes-orchestrated workloads enable rapid scaling for cloud-native financial applications. Osaka-based secondary processing sites favor container density over legacy virtualization for securities trading platforms.
- Virtualization:VMware and Hyper-V-based server consolidation remains prevalent in enterprise-owned infrastructure migration scenarios.
- Hyperconverged Infrastructure:Integrated compute-storage-networking appliances suit mid-scale deployments seeking operational simplicity without hyperscale engineering overhead.
Virtualization maintains the largest installed base, though edge computing gains share fastest among new deployments.
End User:
End user segments diverge sharply on seismic resilience requirements and data sovereignty obligations, with government workloads facing the strictest JIS fire suppression and prefectural ordinance compliance.
- Financial Services:Securities firms and banks drive colocation expansion as cloud migration accelerates transaction processing requirements. Unbundling of real estate from managed services shifts procurement toward interconnection density metrics rather than geographic proximity alone.
- Government:Sovereign cloud mandates and classified workload hosting impose the most stringent physical security protocols and METI efficiency certification requirements.
- IT & Telecom:Carrier-neutral facilities and content delivery networks prioritize submarine cable adjacency at Shima and Maruyama landing stations.
- Healthcare:Patient data hosting under domestic privacy frameworks requires specialized compliance architecture beyond standard enterprise colocation.
Financial services occupies the top volume position, with government workloads expanding most quickly under sovereign cloud initiatives.
Capacity:
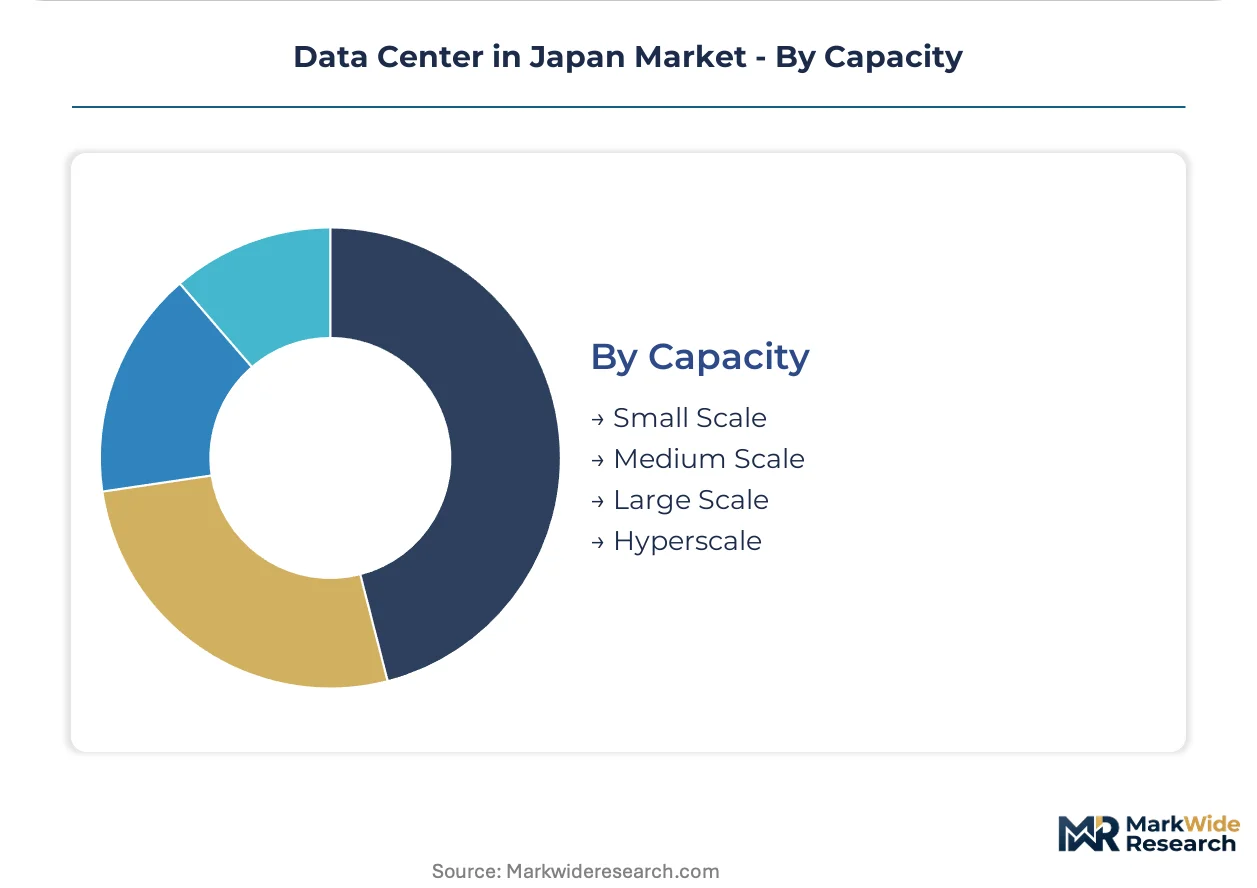
Capacity tiers map directly to capital intensity and PUE certification difficulty, with hyperscale developments facing the strictest METI power usage effectiveness thresholds for grid interconnection priority.
- Hyperscale:Single-tenant facilities exceeding 50 megawatts command disproportionate capital allocation despite minority facility count. Direct-to-chip liquid cooling deployment in Saitama and Chiba addresses thermal loads exceeding 30 kilowatts per rack.
- Large Scale:Multi-tenant buildings between 10-50 megawatts serve cloud service providers and consolidated enterprise footprints with standardized design protocols.
- Medium Scale:Regional and secondary city deployments qualify for METI regional dispersal subsidies encouraging development outside Greater Tokyo power constraints.
- Small Scale:Edge micro-facilities and legacy enterprise server rooms face stranded asset risk from F-Gas Regulation compliance costs on imported cooling equipment.
Large scale facilities lead by deployment count, while hyperscale capacity additions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's data center workforce clusters heavily in Greater Tokyo's engineering corridors, with facility technicians and network specialists concentrated across Chiba and Saitama prefectures where hyperscale construction accelerates.
Greater Tokyo
Financial services firms from Marunouchi and Nihonbashi drive colocation absorption as securities trading platforms migrate from owned infrastructure. METI enforces power usage effectiveness certification for new construction permits above 10 megawatts. Chiba and Saitama prefectures host the majority of greenfield hyperscale development due to TEPCO grid access and available substation capacity.
Kansai/Osaka
Disaster recovery procurement from Tokyo-headquartered enterprises creates secondary site demand with favorable Kansai Electric Power industrial rates. Osaka prefectural ordinances impose seismic resilience requirements beyond national building codes. The Osaka International Business Exchange campus anchors interconnection density for financial services buyers unbundling real estate from managed services.
Chubu/Nagoya
Factory automation networks in Aichi prefecture generate edge computing demand for sub-10 millisecond manufacturing IoT response. Toyota Motor Corporation's supplier ecosystem requires localized processing capacity for predictive maintenance analytics. Nagoya-based facilities qualify for METI regional dispersal subsidies encouraging development outside power-constrained Greater Tokyo zones.
Kyushu
Fukuoka prefecture's semiconductor fabrication plants drive low-latency edge deployments for process control systems. Kyushu Electric Power offers competitive industrial electricity rates compared to TEPCO zones. Fukuoka City's startup ecosystem attracts cloud service providers establishing presence under sovereign cloud localization mandates.
Tohoku
Sendai and surrounding municipalities compete for disaster recovery site selection given geographic separation from Pacific seismic risks. METI incentives for renewable energy interconnection favor wind-rich coastal zones in Miyagi and Iwate prefectures. Cooler ambient temperatures reduce free cooling infrastructure costs for facilities serving Tokyo failover workloads.
Data Center in Japan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's data center sector, creating a tiered structure where telecommunications heritage anchors scale advantages. NTT Ltd leverages domestic fiber network density to secure hyperscale land positions ahead of focused competitors. Three archetypes dominate: integrated telecom operators with captive fiber assets, global REITs deploying standardized design protocols, and regional specialists exploiting local permitting relationships. Capacity expansion and interconnection density investments constitute the primary competitive moves, with operators racing to secure substation-adjacent land in Chiba and Saitama.
Within the integrated operator tier, NTT Ltd and NTT Communications exemplify telecommunications-derived scale advantages through captive fiber infrastructure. Equinix Inc. and Digital Realty Trust Inc. represent the global REIT archetype, extending standardized facility designs from Narita and Osaka campuses. Among Asia-Pacific specialists, AirTrunk and ST Telemedia Global Data Centres occupy positions emphasizing rapid deployment capabilities and regional customer relationships. IDC Frontier Inc. and NEC Corporation anchor the domestic specialist segment with deep local regulatory navigation expertise.
| Leading Market Players |
|---|
| NTT Ltd |
| Equinix Inc. |
| Digital Realty Trust Inc. |
| IDC Frontier Inc. |
| NEC Corporation |
| NTT Communications |
| Colt Technology Services |
| AirTrunk |
| ST Telemedia Global Data Centres |
| Others |
Pricing and Supply Chain Analysis
Financial services firms from Tokyo's Marunouchi and Nihonbashi districts concentrate procurement power through master service agreements that unbundle real estate from managed services, anchoring a contract-based pricing structure where interconnection density commands premium positioning over geographic proximity.
Pricing Analysis
Bundled colocation packages combining power, cooling, and physical security dominate enterprise procurement, though hyperscale operators increasingly negotiate unbundled rates for bare-metal space with self-managed infrastructure. Price differentiation rests on METI Green Transformation certification status and TEPCO grid access tier, with certified facilities in Chiba and Saitama commanding structural premiums. Cost compression in legacy air-cooled facilities is intensifying because F-Gas Regulation compliance forces refrigerant transition investments. Mid-market enterprises lacking in-house engineering expertise exhibit highest price sensitivity, while securities firms prioritize latency performance over rate negotiation.
Supply Chain Analysis
Dual-sourcing requirements for critical infrastructure components mandate multi-supplier qualification for precision cooling systems and uninterruptible power supply units, compressing procurement timelines for hyperscale deployments. Manufacturing concentrates in Japan, Germany, and the United States for precision chillers, while electrical switchgear draws from domestic producers and South Korean specialists. Supply chain risk centers on single-source vulnerability for direct-to-chip liquid cooling components amid GPU cluster expansion. Distribution runs through equipment vendor-direct relationships with engineering-procurement-construction contractors, bypassing traditional distributor networks for facility-scale transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's data center sector functions as a stable compounder underpinned by sovereign cloud mandates and financial services migration patterns that sustain absorption regardless of cyclical tech investment swings.
For Market Incumbents: Deploy liquid cooling engineering capabilities to capture hyperscale GPU cluster demand before specialized technicians become fully scarce. NTT Ltd and Equinix Inc. should accelerate land positions in Chiba and Saitama substation corridors to preempt emerging fiber-rich competitors. METI efficiency certification investments will defend pricing power as uncertified legacy assets face stranded risk from grid interconnection priority rules. For New Entrants and Emerging Players: Regional electric utilities represent the most accessible channel partnership for bypassing TEPCO rate disadvantages in Osaka and Fukuoka markets. Disaster recovery site selection in Tohoku offers white-space penetration given geographic separation premiums and renewable energy incentives. Municipal district heating partnerships unlock heat reuse revenue streams that incumbent operators have underdeveloped. For Investors and Strategic Acquirers: Telecommunications operators with captive fiber assets are the most active acquirer in this space, seeking data center platforms to monetize latent network capacity. Long-term viability frames around decade-long power purchase agreements and land lease structures that outlast current construction cycles. Facility operators with JIS-certified seismic resilience and METI efficiency credentials signal acquisition readiness as regulatory compliance costs rise.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Deployment | Direct-to-chip systems address 30+ kilowatt rack densities that CRAC units cannot evacuate. |
| Regional Dispersal Expansion | Osaka and Fukuoka facilities exploit Kansai Electric and Kyushu Electric rate advantages over TEPCO zones. |
| Submarine Cable Anchoring | Proximity to Shima and Maruyama landing stations commands premium cross-connect pricing from content networks. |
| Heat Recovery Integration | Municipal district heating partnerships transform waste thermal output into incremental revenue streams. |
| METI Certification Investment | Green Transformation compliance secures grid interconnection priority and accelerated permitting timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility engineers, TEPCO and Kansai Electric grid planning officers, financial services infrastructure procurement leads, and METI certification program administrators with secondary validation against METI energy efficiency filings, JIS standard documentation, prefectural building ordinance records, and hyperscaler capital expenditure disclosures. Bottom-up facility capacity tallies and top-down sector revenue estimates were triangulated to anchor market sizing.
Segment-weighting approaches modeled service type, technology deployment, end-user vertical, and capacity tier dimensions across the projection horizon. CAGRs were derived from facility pipeline tracking and power demand forecasting. Industry-specific inputs included substation interconnection queue data, F-Gas Regulation implementation timelines, and 5G base station rollout schedules affecting edge computing demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to METI mandate enforcement intensity and TEPCO grid expansion timelines. Forecasts reflect documented assumptions about sovereign cloud procurement continuity and financial services colocation migration rates. Deviation in F-Gas Regulation extraterritorial scope or seismic ordinance amendments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Netherlands Data Center Market