
 Chicago Data Center Market | 2026-2036
Chicago Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Chicago Data Center Market Insights
Project finance partnerships with utility-backed offtake agreements is reshaping competitive entry in Chicago's data center sector. Digital Realty leverages its global platform to secure long-term power contracts with ComEd. CyrusOne anchors its position through purpose-built hyperscale campuses in the northern suburbs. Equinix competes via interconnection density at its downtown Chicago International Business Exchange facility.
A data center constitutes a dedicated facility housing compute, storage, and networking infrastructure with redundant power feeds, precision cooling maintaining 18-27°C, and sub-15ms latency connectivity to major internet exchanges. Colocation services generate the deepest revenue pools in Chicago as enterprises shed owned assets. Managed services represent the fastest-expanding segment as financial and healthcare buyers outsource operational complexity. Cooling systems technology commands disproportionate capital allocation given Midwest summer humidity loads and rising rack densities.
Illinois Commerce Commission rate structures and ComEd economic development riders directly shape site selection economics for new entrants. Chicago Department of Planning and Development zoning overlays for industrial corridors constrain expansion paths in built-up areas. Stakeholders must monitor interconnection pricing at 350 East Cermak and power transmission upgrade timelines along the PJM grid before committing to long-term capacity contracts.
Market Dynamics
Hyperscale cloud providers are compressing deployment timelines from 24 months to 14 months, forcing incumbent operators to renegotiate power offtake structures with ComEd before substation capacity locks.
Growth Catalysts
- Edge computing deployments:Financial services firms in Chicago's Loop district are demanding sub-5ms latency for algorithmic trading. This pulls distributed infrastructure into the metro core.
- Illinois Data Center Tax Incentive Program:The state exemption on sales tax for construction materials reduces project capex by 8-12 percentage points versus neighboring Wisconsin.
- Liquid cooling adoption:GPU-dense AI training clusters now exceed 50kW per rack. Traditional air handlers cannot maintain thermal thresholds, accelerating retrofit demand.
Market Restraints
- ComEd transmission queue congestion:New substation interconnect requests face 18-24 month backlogs in the West Loop corridor. Developers cannot secure firm power without pre-leased anchor tenants.
- Copper and electrical steel price volatility:Switchgear and busbar components constitute 15-20% of electrical infrastructure spend. Tariff exposure on Chinese copper rod compresses EPC margins.
- Zoning overlay restrictions:Chicago's Industrial Corridor System Plan blocks data center development in 12 designated manufacturing zones. Available land concentrates in Elk Grove Village and Aurora.
Strategic Opportunities
- DeKalb County greenfield expansion:ComEd's planned 345kV transmission loop opens 400+ acres of previously power-constrained land. First-movers secure 100MW+ scalable plots.
- Carbon-free energy matching:Illinois' renewable portfolio standard requires 40% clean generation by 2030. Operators signing virtual PPAs with Invenergy wind farms capture sustainability-minded enterprise tenants.
- Cross-connect density arbitrage:350 East Cermak maintains 50+ on-net carriers. Suburban campuses lacking this fiber depth can deploy dark fiber backhaul to capture wholesale interconnection revenue.
Industry Challenges
- Critical facilities engineering talent scarcity:Chicago's construction pipeline requires 400+ certified Uptime Institute ATDs annually. Local university programs graduate fewer than 80.
- Legacy building envelope retrofits:1990s-era industrial warehouses in the I-90 corridor need structural reinforcement for 250+ lb/sf floor loading. Asbestos abatement adds 6-8 weeks to permitting.
- PJM capacity market volatility:Forward capacity auction prices swung 340% between planning years 2023/2024 and 2024/2025. Long-term power hedging requires specialized commodity structuring expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicago Data Center Market |
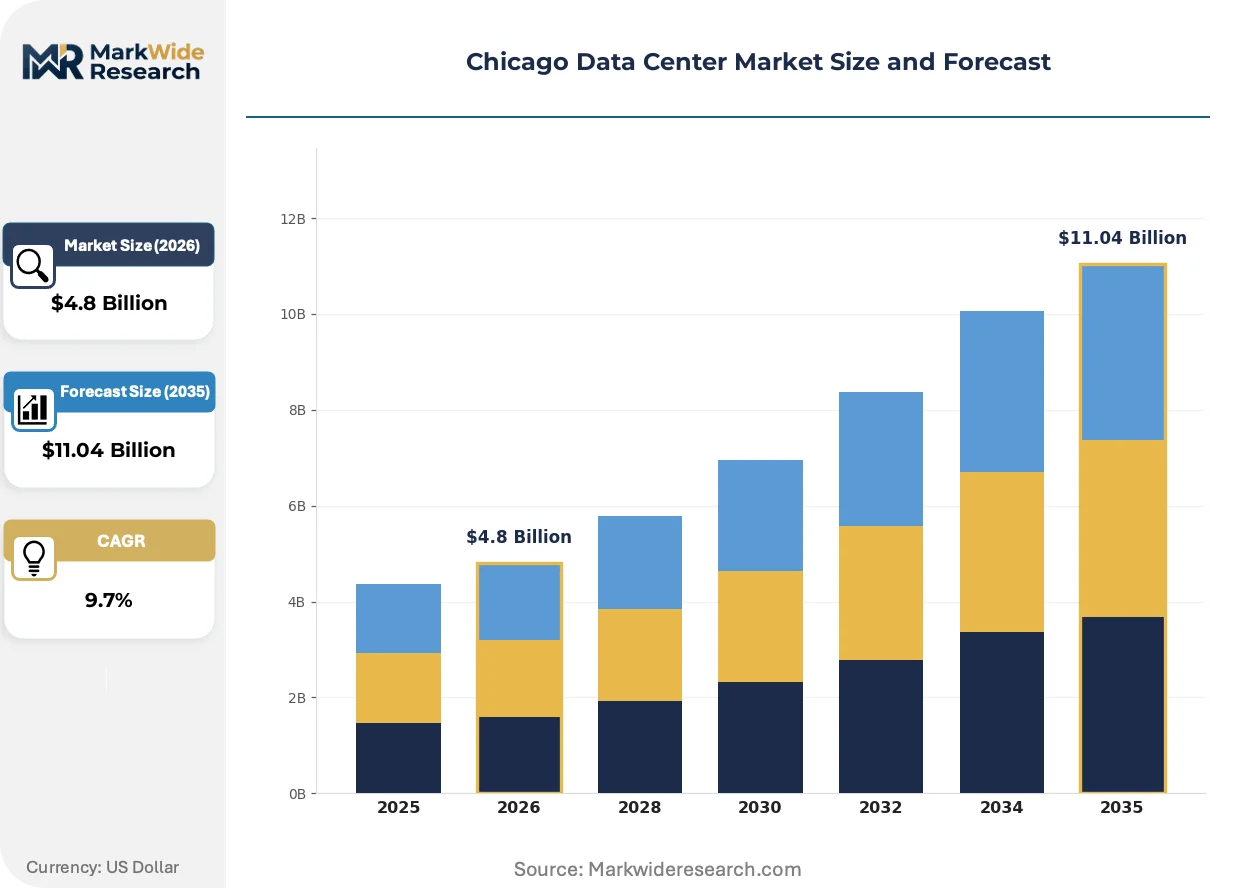
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Technology: Cooling Systems, Power Distribution, Fire Suppression, Rack Infrastructure End User: Financial Services, Healthcare, E-Commerce, Government Agencies Deployment: On-Premise, Hybrid, Multi-Cloud, Internet Exchange |
| Companies Covered | Digital Realty, Equinix, CyrusOne, CoreSite, QTS Realty Trust, Stack Infrastructure, NTT Global Data Centers, TierPoint, Prime Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicago Data Center Market Trends and Innovations
Direct liquid cooling and high-voltage busbar distribution are converging to redefine mechanical and electrical infrastructure specifications for Chicago's next generation of facilities.
Immersion cooling systems using dielectric fluids are collapsing the traditional separation between IT and mechanical engineering disciplines. CyrusOne and STACK Infrastructure pilots in Elk Grove Village now submerge entire server racks in engineered fluorocarbon baths. Financial services and genomics buyers are specifying immersion-ready white space in new RFPs. The technology is collapsing PUE targets from 1.35 to 1.08, eliminating the need for raised-floor air handlers in high-density zones.
Illinois Commerce Commission rate case reforms are accelerating time-of-use pricing granularity. ComEd's proposed dynamic peak pricing pilot would expose data centers to real-time wholesale rate exposure during PJM scarcity events. Hyperscale operators with battery-backed load shifting capability gain arbitrage opportunities. Colocation providers without storage assets face margin compression during summer peak hours.
Enterprise procurement teams are consolidating vendor relationships from 12-15 regional suppliers to 3-4 national platforms with Chicago presence. Johnson & Johnson and Abbott Laboratories recently issued unified RFPs covering primary and disaster recovery capacity. This buyer concentration rewards operators with dual-campus redundancy across the metro. Subscale single-facility operators lose access to Fortune 500 contracts without geographic diversification.
Chicago Data Center Market Segmentation
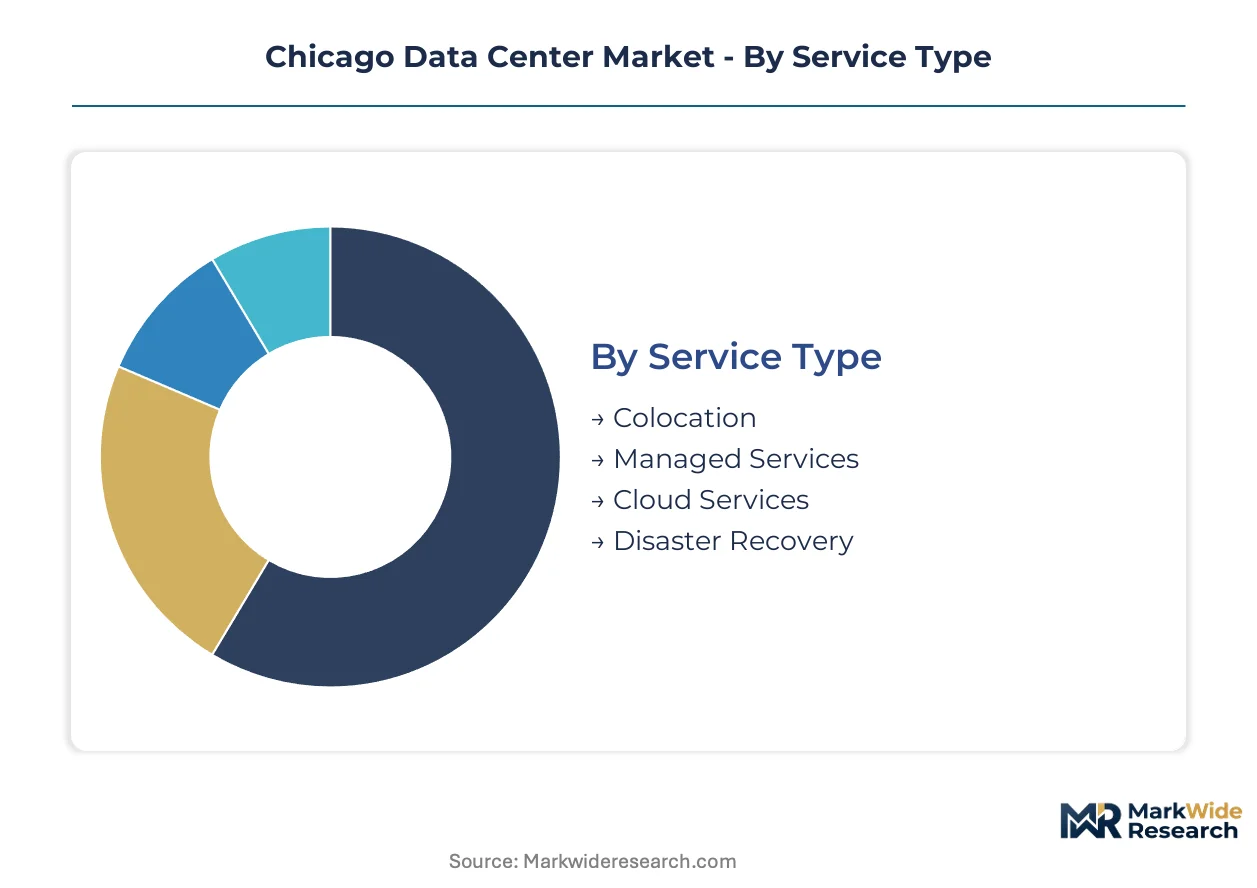
Segmentation in Chicago's data center market reveals how tax incentives, power constraints, and latency requirements reshape procurement patterns across buyer categories. Understanding these divides exposes where ComEd capacity allocations and Illinois Commerce Commission rate structures create competitive moats for operators with aligned infrastructure.
Service Type:
Cost tier differentiation separates capex-heavy ownership models from operational expenditure structures that dominate enterprise decision-making.
- Colocation:Enterprises lease rack space, power, and cooling within multi-tenant facilities while retaining hardware ownership. Financial services firms in Chicago's Loop district concentrate demand here for proximity to 350 East Cermak's interconnection density. The Illinois Data Center Tax Incentive Program reduces tenant-effective pricing versus self-build alternatives.
- Managed Services:Providers assume operational responsibility for infrastructure monitoring, patching, and capacity planning. Healthcare systems across Cook County outsource complexity to meet HIPAA technical safeguard requirements without expanding internal IT headcount. This segment climbs fastest as buyers prioritize operational leverage over capital deployment.
- Cloud Services:Hyperscale providers deliver compute and storage via API-driven consumption models. Demand concentrates among SaaS startups and mid-market enterprises seeking elastic scaling without physical infrastructure commitment.
- Disaster Recovery:Secondary site replication and failover orchestration services protect against primary facility outages. Regional banks and insurance carriers mandate 40-mile minimum separation from production sites, pulling demand toward Aurora and DeKalb County.
Colocation commands the established base. The steepest expansion runs through Managed Services.
Technology:
Application-specific infrastructure requirements divide capital allocation between thermal management, electrical distribution, and physical containment systems.
- Cooling Systems:Precision air handlers, chilled water loops, and emerging liquid cooling technologies maintain thermal thresholds for IT equipment. GPU-dense AI training clusters exceeding 50kW per rack in Elk Grove Village campuses now require immersion cooling retrofits that traditional CRAC units cannot support.
- Power Distribution:Medium-voltage switchgear, UPS systems, and rack-level PDUs deliver conditioned electricity with 99.999% availability targets. ComEd substation access constraints in the West Loop corridor concentrate premium power infrastructure investment in northern suburban developments.
- Fire Suppression:Clean agent systems and pre-action sprinklers protect equipment without water damage risk. Illinois state fire marshal regulations mandate dual-system redundancy for facilities above 10MW critical load.
- Rack Infrastructure:Cabinet enclosures, cable management, and physical security enclosures organize IT equipment deployment. Standard 42U cabinets dominate, though 52U extended-height units gain share in high-density zones.
Cooling Systems absorb the largest capital share. Power Distribution shows the tightest supply constraints.
End User:
Customer type determines latency sensitivity, compliance burden, and contract structure preferences across the metro.
- Financial Services:Algorithmic trading firms, exchanges, and payment processors demand sub-5ms latency to downtown matching engines. This pulls infrastructure investment into expensive West Loop real estate despite power queue backlogs.
- Healthcare:Hospital systems, payers, and health IT vendors require HIPAA-compliant environments with audit-ready documentation. Managed services penetration runs highest here as clinical IT teams lack data center operations expertise.
- E-Commerce:Retail platforms and logistics technology providers scale capacity seasonally around holiday demand peaks. Hybrid deployment models allow burst capacity into cloud during November traffic surges.
- Government Agencies:State of Illinois and municipal entities procure through formal RFP processes with prevailing wage and minority contracting requirements. FedRAMP authorization gates federal workload placement.
Financial Services anchors premium pricing. Healthcare drives the fastest managed services adoption.
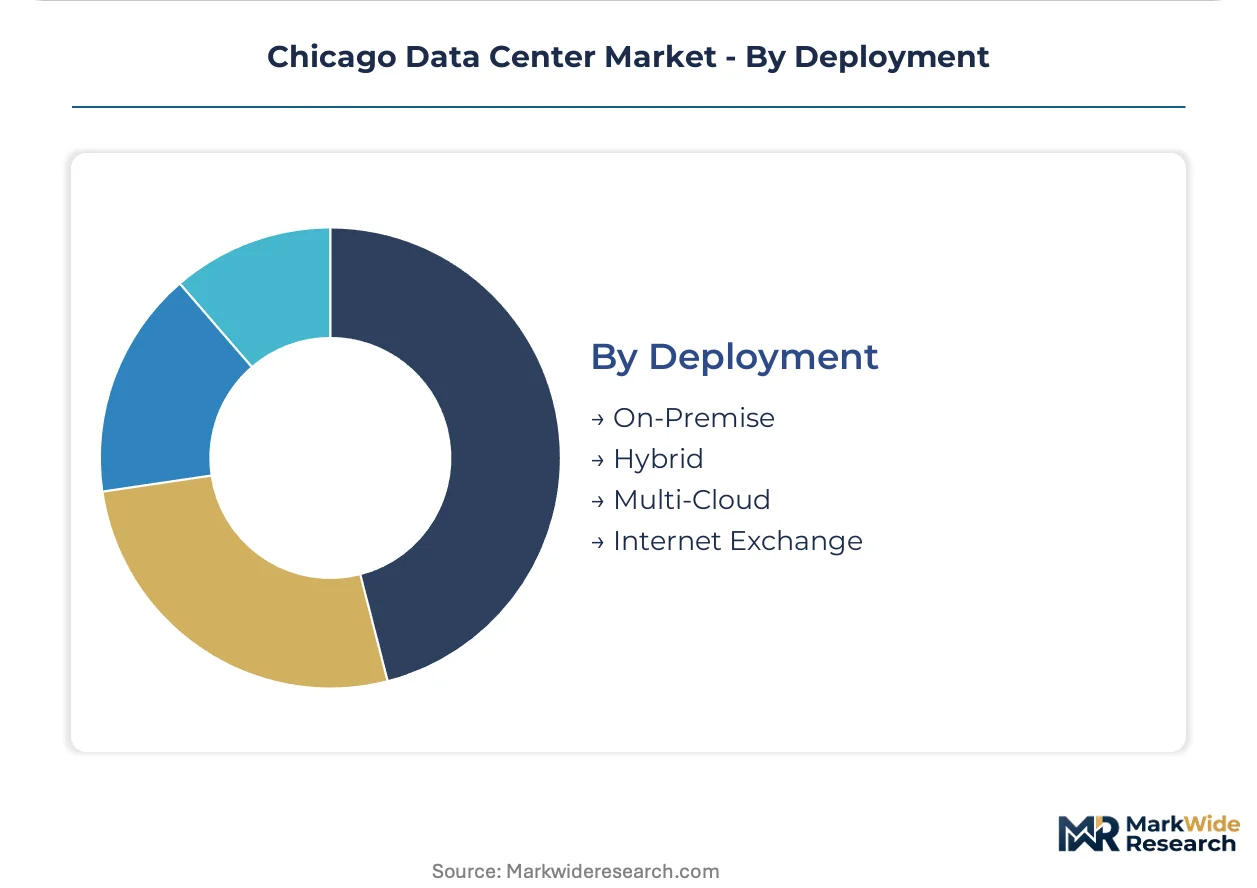
Deployment:
Volume and control trade-offs separate fully owned infrastructure from distributed architectures spanning multiple environments.
- On-Premise:Enterprises own and operate dedicated facilities with full hardware and software control. Legacy manufacturing firms along the I-90 corridor retain this model despite higher TCO versus colocation alternatives.
- Hybrid:Workloads split between owned infrastructure and third-party cloud based on sensitivity and scaling requirements. Abbott Laboratories and Johnson & Johnson consolidated RFPs favor operators offering dual-campus redundancy across this deployment mode.
- Multi-Cloud:Portability across AWS, Azure, and Google Cloud platforms prevents vendor lock-in. Container orchestration and Kubernetes standardization enable workload migration based on regional pricing arbitrage.
- Internet Exchange:Direct peering at 350 East Cermak reduces transit costs and latency for content-heavy applications. Video streaming and gaming platforms prioritize this deployment for last-mile performance.
Hybrid deployment captures the largest committed pipeline. Multi-Cloud expands most quickly among cloud-native enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms, healthcare systems, and hyperscale cloud providers drive capacity procurement across Chicagoland sub-markets. Each cluster exhibits distinct latency sensitivity, power availability, and tax incentive exposure.
West Loop
Algorithmic trading firms demand sub-5ms latency to downtown matching engines. Chicago Department of Planning and Development zoning overlays constrain new construction, limiting supply expansion. 350 East Cermak anchors interconnection density with 50-plus on-net carriers serving financial exchange proximity requirements.
Elk Grove Village
Hyperscale cloud providers compress deployment timelines to 14 months here. Illinois Data Center Tax Incentive Program exemptions on construction materials reduce project capex versus Wisconsin alternatives. CyrusOne and STACK Infrastructure operate liquid cooling pilots for GPU-dense AI training clusters exceeding 50kW per rack.
Aurora
Regional banks and insurance carriers mandate 40-mile minimum separation from primary production sites. ComEd substation capacity remains more accessible than West Loop corridors. Disaster recovery demand concentrates here as enterprises seek geographic redundancy without leaving the metro.
DeKalb County
ComEd's planned 345kV transmission loop unlocks 400-plus acres of previously power-constrained land. First-movers secure 100MW-plus scalable plots with direct renewable energy matching potential. Illinois' renewable portfolio standard requiring 40% clean generation by 2030 shapes virtual PPA negotiations with wind developers.
Chicago Data Center Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Global platform operators leverage interconnection density and long-term power contracts to secure anchor tenants. Purpose-built hyperscale specialists capture cloud-provider demand through rapid deployment capabilities. Regional colocation providers defend share via managed services depth and healthcare compliance expertise. Dominant competitive moves include substation capacity pre-leasing and liquid cooling infrastructure differentiation.
Within the global platform tier, Digital Realty and Equinix occupy positions defined by scale and interconnection assets. Digital Realty leverages its global footprint to secure ComEd economic development riders. Equinix anchors downtown presence through its Chicago International Business Exchange facility. CyrusOne represents the purpose-built hyperscale archetype with northern suburban campuses engineered for rapid cloud-provider deployment.
| Leading Market Players |
|---|
| Digital Realty |
| Equinix |
| CyrusOne |
| CoreSite |
| QTS Realty Trust |
| Stack Infrastructure |
| NTT Global Data Centers |
| TierPoint |
| Prime Data Centers |
| Others |
Pricing and Supply Chain Analysis
Copper and electrical steel tariff exposure determines both pricing tier spreads and supply chain shape in Chicago's data center sector. Switchgear and busbar components anchor cost-plus contracts to commodity indices, forcing tiered pricing separation between hyperscale anchor tenants and mid-market colocation buyers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate electrical infrastructure procurement. Pricing stratifies across hyperscale, enterprise, and retail colocation tiers based on power density commitments and interconnection depth. Cost compression in the retail tier intensifies because ComEd transmission queue congestion forces smaller operators into premium substation access arrangements. Financial services firms show the least price sensitivity given sub-5ms latency requirements, while regional healthcare systems negotiate hardest on managed services bundles.
Supply Chain Analysis
Extended payment terms from EPC contractors to Chinese copper rod suppliers now stretch 90-120 days, straining working capital across the electrical infrastructure tier. Manufacturing concentrates in China, Germany, and Mexico for switchgear assemblies, with domestic panel fabrication in Texas and Ohio. Supply chain risk rests on single-source dependency for medium-voltage transformers from a consolidated vendor base. Distribution runs through authorized distributor networks serving the Chicago metro, with direct OEM relationships reserved for 100MW-plus hyperscale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chicago's data center market sits in early-cycle expansion driven by GPU-dense AI training cluster deployments that exceed legacy thermal design limits. Penetration of liquid cooling infrastructure remains below 15% of installed base, creating runway for technology differentiation.
For Market Incumbents: Build substation capacity moats through pre-leasing arrangements with ComEd before 345kV transmission loop completion. CyrusOne and Digital Realty should accelerate DeKalb County land aggregation ahead of greenfield competition. Defensive moves require liquid cooling retrofit capabilities to capture AI training RFPs specifying immersion-ready white space. Threat substitution from edge computing micro data centers in the Loop district demands downtown interconnection density reinforcement.
For New Entrants and Emerging Players: Pursue DeKalb County greenfield positions with direct renewable energy matching to differentiate against incumbent carbon footprints. The most penetrable segment sits in managed services for Cook County healthcare systems lacking internal critical facilities expertise. Go-to-market positioning should emphasize HIPAA technical safeguard documentation and 24/7 remote hands capabilities rather than competing on colocation price alone.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors platform operators with ComEd relationship depth and multi-campus redundancy. Long-term viability hinges on 5-10 year power contract structures that outlast PJM capacity market volatility cycles. Acquisition targets should display certified Uptime Institute ATD engineering benches and established virtual PPA pipelines with Invenergy or comparable wind developers. The signal to watch is ComEd transmission queue resolution timelines, which would unlock suppressed development capacity and compress entry multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Substation Capacity Pre-leasing | ComEd economic development riders secure 18-24 month queue priority for anchor tenants. |
| Liquid Cooling Infrastructure Deployment | Immersion cooling pilots at CyrusOne and STACK collapse PUE targets from 1.35 to 1.08. |
| Virtual Renewable PPA Execution | Illinois renewable portfolio standard compliance attracts sustainability-minded enterprise tenants. |
| Multi-Campus Redundancy Construction | Johnson & Johnson and Abbott unified RFPs favor operators with Aurora-West Loop dual presence. |
| Certified Engineering Bench Expansion | Uptime Institute ATD scarcity limits Chicago construction pipeline to 80 annual graduates versus 400 required. |
Research Methodology
Operator-level perspectives from data center development executives, ComEd interconnection planners, EPC contractors, and enterprise IT procurement officers anchored the qualitative base. Secondary validation drew from PJM interconnection queue filings, Illinois Commerce Commission rate case dockets, ComEd economic development rider documentation, and Uptime Institute certification records. Bottom-up facility-level capacity tracking triangulated against top-down metro market sizing from hyperscaler capex disclosures and colocation provider SEC filings.
Scenario-bracketing around PJM capacity market volatility and ComEd transmission upgrade timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, cooling technology tier, end-user vertical, and deployment architecture. CAGRs derived from facility absorption rates, power density trajectories, and tax incentive program utilization curves. Industry-specific inputs encompassed GPU server shipment forecasts and Illinois renewable portfolio standard compliance pathways.
Sensitivities concentrate around PJM capacity auction price swings, ComEd substation queue resolution speed, and liquid cooling technology adoption curves. Forecasts reflect assumptions on hyperscale deployment timeline compression and Illinois tax incentive program renewal. Macroeconomic deviation in commodity markets, regulatory shifts in Commerce Commission rate structures, or technological disruption in thermal management would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Europe Data Center Physical Security Market