
 Thailand Data Center Physical Security Market | 2026-2036
Thailand Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Physical Security Market Insights
Tier-three and tier-four certified facility standards are rotating through Thailand's data center development pipeline, forcing security architecture upgrades across new builds. Hikvision leverages its domestic manufacturing footprint to supply AI-enhanced video analytics for these high-availability environments. Schneider Electric anchors the integrated infrastructure segment by bundling physical access with power and cooling monitoring. Bosch Security Systems differentiates through European-certified intrusion detection systems that meet insurer requirements for premium colocation clients.
Data center physical security encompasses perimeter barriers, access control layers, surveillance networks, and intrusion countermeasures engineered to protect computing infrastructure from unauthorized entry, environmental sabotage, and equipment theft. Biometric authentication systems and multi-factor credentialing now constitute baseline specifications for facilities processing financial and government workloads. Surveillance cameras lead product type revenue due to mandatory 90-day retention rules under national cybersecurity directives, while software solutions represent the fastest-expanding technology segment as operators centralize security operations centers across distributed campuses. Managed services within installation type capture expanding margin pools as foreign operators entering Thailand outsource facility hardening to local specialists.
Thailand's Personal Data Protection Commission enforces facility-level access auditing, while the National Cyber Security Agency mandates critical infrastructure protection standards for data centers hosting government cloud services. The National Broadcasting and Telecommunications Commission coordinates submarine cable landing station security with facility operators, creating overlapping compliance obligations. Stakeholders must monitor whether proposed amendments to the Cybersecurity Act expand classified infrastructure designations to commercial colocation facilities, as this would trigger mandatory security clearance requirements for vendor personnel and reshape procurement criteria across the supply base.
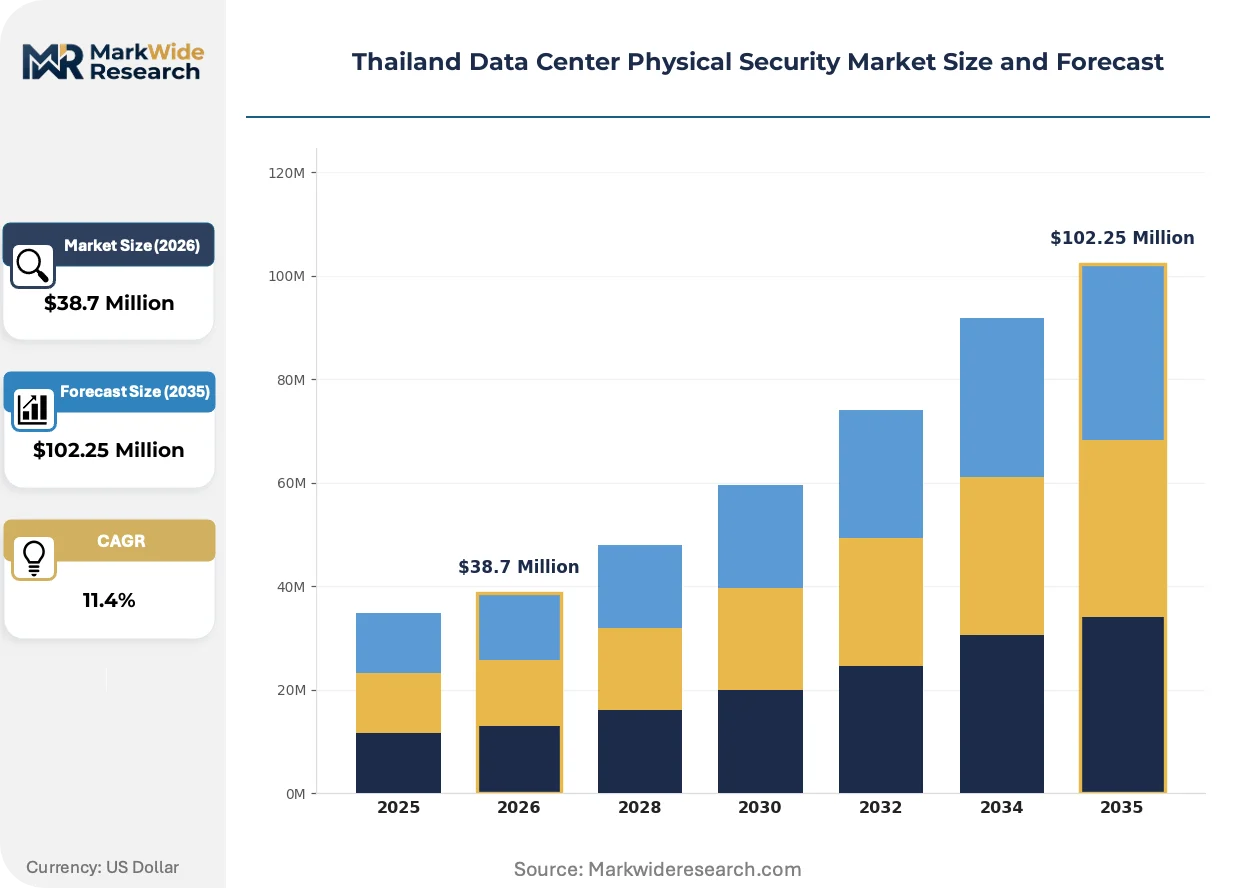
Market Dynamics
Thailand's Personal Data Protection Act B.E. 2562 enforcement is compressing upgrade timelines for biometric authentication systems across colocation facilities, forcing operators to reallocate capex from expansion budgets toward compliance-driven security architecture retrofits.
Growth Catalysts
- Hyperscale Campus Clustering:Cloud service providers are expanding colocation footprints across Greater Bangkok, generating concentrated demand for multi-layered perimeter protection systems at new build sites.
- PDPA B.E. 2562 Mandates:Stricter facility access logging requirements compel operators to upgrade biometric authentication systems, creating replacement cycles across existing infrastructure.
- Eastern Economic Corridor Development:Submarine cable landing station proximity is attracting hyperscale campuses to the EEC, concentrating security procurement in this corridor.
Market Restraints
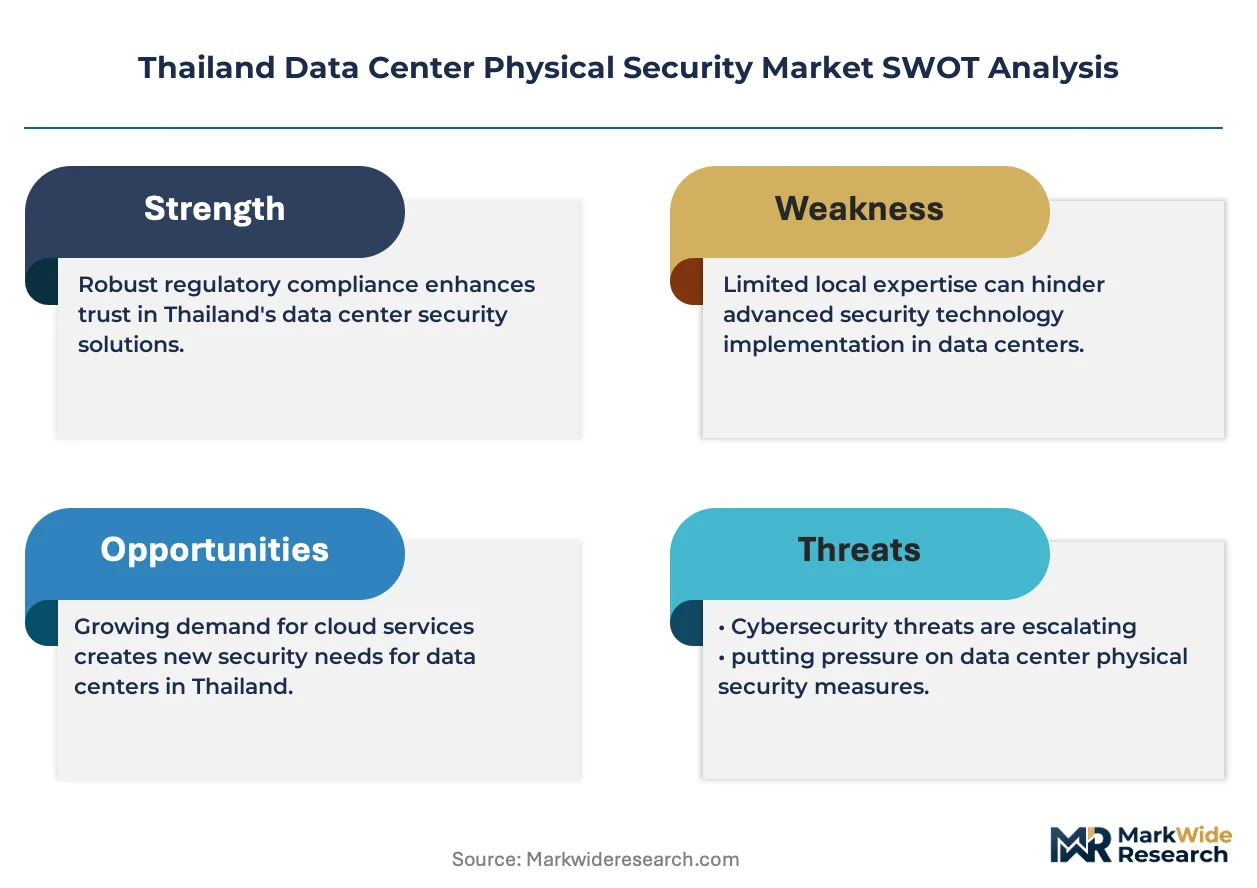
- Specialized Labor Scarcity:Certified security systems integrators capable of Tier-IV facility hardening remain concentrated in Bangkok, limiting deployment velocity in secondary provinces.
- Import Dependency for Core Components:High-availability biometric sensors and European-certified intrusion detection modules rely on overseas supply chains, exposing operators to extended lead times.
- Interoperability Limitations:Legacy access control protocols in older facilities resist seamless integration with AI-enhanced video analytics platforms, complicating phased upgrades.
Strategic Opportunities
- Managed Security Services White Space:Foreign operators entering Thailand lack local facility hardening expertise, creating margin pools for domestic specialists offering outsourced security operations.
- AI-Video Convergence:Machine learning-enhanced video analytics bundled with power and cooling monitoring platforms enable integrated infrastructure positioning.
- Government Cloud Security Tier:National Cyber Security Agency critical infrastructure protection standards for state-hosted workloads are expanding the addressable market for high-assurance security vendors.
Industry Challenges
- Multi-Regulatory Compliance Burden:Operators must simultaneously satisfy PDPC facility-level access auditing, NBTC submarine cable landing station security coordination, and potential Cybersecurity Act amendments requiring personnel clearances.
- Certification Timeline Compression:Tier-III and Tier-IV certification requirements are rotating through the development pipeline faster than security architecture design cycles can adapt.
- Centralized Operations Integration:Distributed campus operators struggle to consolidate security operations centers while maintaining 90-day video retention compliance across geographically separated sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Physical Security Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Surveillance Cameras, Intrusion Detection Systems, Alarm Systems End User: Telecommunications, Financial Services, IT Services, Government Agencies Technology: CCTV, Biometric Systems, RFID, Software Solutions Installation Type: On-site Installation, Remote Monitoring, Managed Services, Consulting |
| Companies Covered | Hikvision, Dahua Technology, Bosch Security Systems, Honeywell, Axis Communications, Johnson Controls, Securitas, Schneider Electric, Genetec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Physical Security Market Trends and Innovations
Thailand's data center physical security market is experiencing technology convergence between surveillance networks and infrastructure monitoring platforms, with regulatory compliance acting as the primary adoption accelerator rather than pure risk mitigation.
AI-enhanced video analytics with behavioral recognition capabilities is supplanting rule-based motion detection in perimeter protection deployments. Tier-III and Tier-IV certified facilities in Greater Bangkok are adopting these platforms at accelerated paces to satisfy insurer requirements for premium colocation clients. This technology compression is enabling centralized security operations across distributed Eastern Economic Corridor campuses while reducing headcount requirements at individual sites.
Thailand's Personal Data Protection Commission enforcement of facility-level access auditing is mandating biometric authentication system upgrades across financial and government workload hosts. The industrial consequence is a procurement preference for integrated credentialing platforms that combine fingerprint, facial recognition, and multi-factor authentication within single vendor relationships. Colocation operators processing cross-border data transfers are most affected, responding by consolidating vendor relationships to simplify compliance documentation.
Security procurement patterns among foreign cloud entrants are gravitating toward outcome-based facility hardening contracts with local managed services providers. Traditional equipment resale channels are losing share to specialists offering bundled installation, monitoring, and compliance reporting. This shift is most visible in the Eastern Economic Corridor, where hyperscale entrants prioritize speed-to-operation over direct vendor management of Thai regulatory requirements.
Thailand Data Center Physical Security Market Segmentation
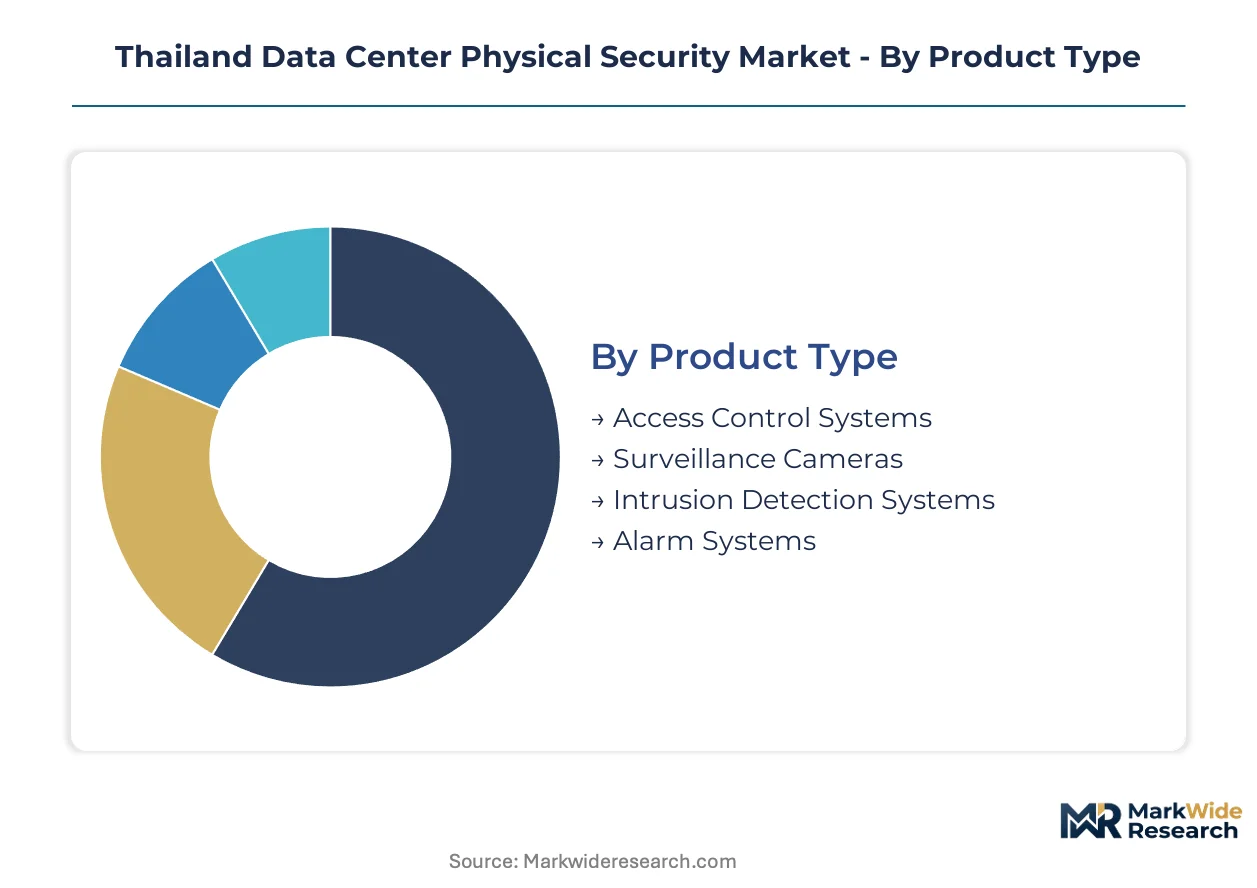
Thailand's data center physical security market fragments across hardware, software, and service layers that respond differently to PDPA B.E. 2562 mandates and hyperscale campus buildouts. Procurement patterns diverge sharply between domestic colocation operators upgrading legacy facilities and foreign cloud entrants demanding integrated turnkey solutions.
Product Type:
Domestic manufacturing capabilities concentrate in surveillance equipment, while biometric sensors and European-certified intrusion modules remain import-dependent, stretching lead times for Tier-IV facility deployments.
- Surveillance Cameras:AI-enhanced video analytics platforms with behavioral recognition capabilities now dominate perimeter protection specifications. Demand clusters in Greater Bangkok hyperscale campuses where 90-day retention rules under National Cyber Security Agency directives mandate high-capacity storage integration.
- Access Control Systems:Multi-factor biometric authentication combining fingerprint, facial recognition, and credentialing constitutes baseline for financial and government workload hosts. Eastern Economic Corridor operators prioritize these systems to satisfy PDPC facility-level access auditing requirements.
- Intrusion Detection Systems:European-certified modules from specialist manufacturers meet insurer requirements for premium colocation tiers.
- Alarm Systems:Integrated notification platforms linking perimeter breaches to centralized security operations centers.
Surveillance cameras hold the largest share; momentum sits with access control systems as PDPA retrofit cycles accelerate.
End User:
Customer concentration follows submarine cable landing station proximity, with workload sensitivity determining security architecture investment intensity.
- IT Services:Colocation and cloud service providers drive the steepest expansion trajectory as foreign hyperscalers expand Eastern Economic Corridor footprints. These operators outsource facility hardening to local managed security specialists to compress speed-to-operation timelines.
- Financial Services:Banks and payment processors face the most stringent PDPC access logging mandates, forcing biometric authentication upgrades across existing infrastructure. Cross-border data transfer requirements compel vendor consolidation for simplified compliance documentation.
- Telecommunications:Carrier-neutral facilities require coordinated perimeter protection with NBTC submarine cable landing station security protocols.
- Government Agencies:National Cyber Security Agency critical infrastructure protection standards for state-hosted workloads expand the addressable market for high-assurance vendors.
IT services commands the dominant revenue position; financial services exhibits the fastest compliance-driven replacement cycle.
Technology:
Technology procurement patterns reveal a shift from standalone hardware toward integrated platforms that bundle physical security with power and cooling monitoring.
- Software Solutions:Centralized security operations platforms enabling distributed campus management represent the most rapidly expanding segment. These systems aggregate video analytics, access logs, and environmental monitoring across geographically separated Eastern Economic Corridor sites while maintaining 90-day retention compliance.
- Biometric Systems:Integrated credentialing platforms combining multiple authentication modalities now constitute standard specification for Tier-III and Tier-IV certified facilities in Greater Bangkok.
- CCTV:Conventional video surveillance networks persist in legacy facility retrofits where AI upgrade paths face interoperability constraints.
- RFID:Card-based access control remains prevalent in older facilities resisting seamless integration with modern analytics platforms.
Software solutions is gaining share fastest; biometric systems maintains the installed base leadership.
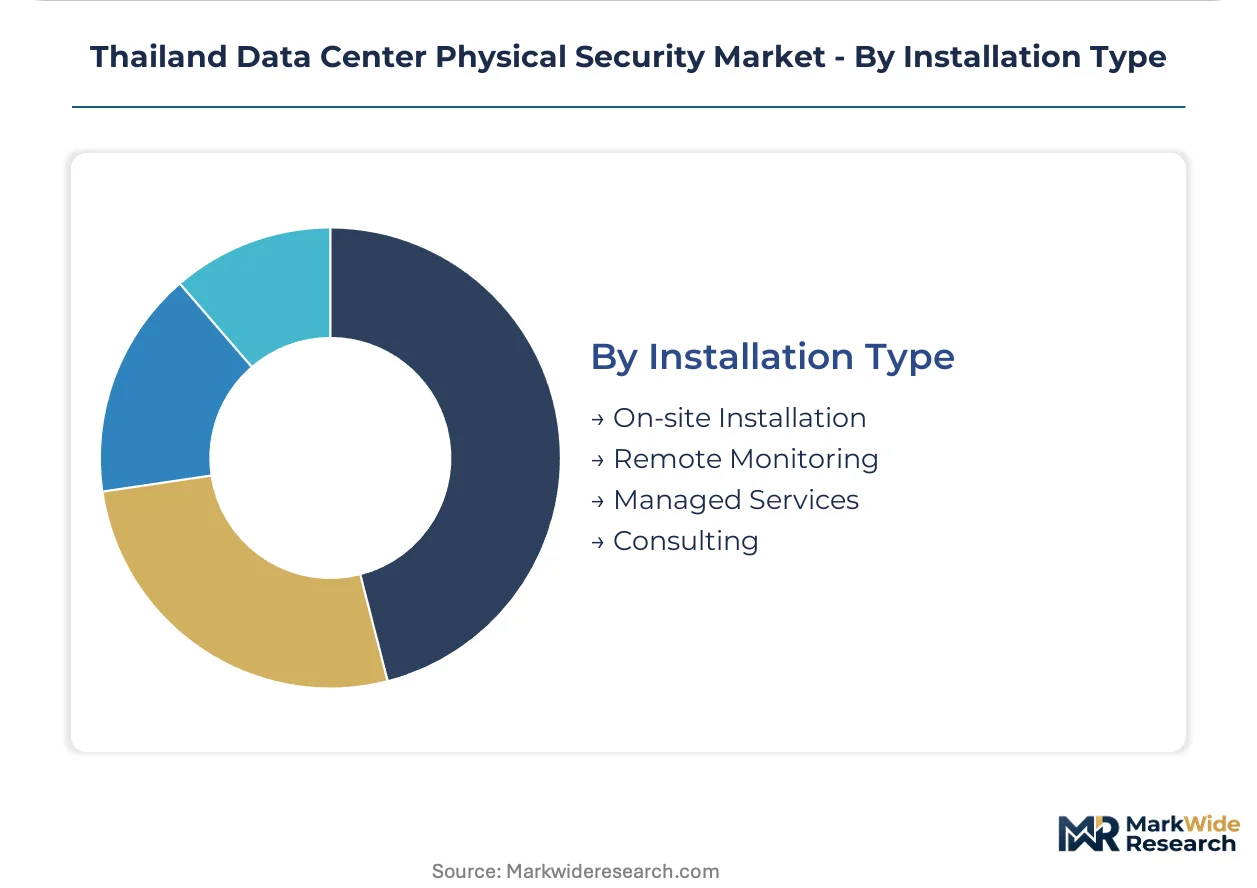
Installation Type:
Service procurement diverges between established operators with in-house security teams and foreign entrants lacking Thai regulatory expertise.
- Managed Services:Outcome-based facility hardening contracts bundle installation, monitoring, and compliance reporting for foreign cloud operators entering Thailand. This model captures expanding margin pools as hyperscale entrants prioritize operational speed over direct vendor management of PDPA and NBTC requirements.
- On-site Installation:Traditional project-based deployment persists among domestic operators upgrading single facilities, though labor scarcity for Tier-IV certified integrators limits velocity outside Bangkok.
- Remote Monitoring:Centralized surveillance operations reduce headcount requirements at individual distributed campus locations.
- Consulting:Regulatory compliance advisory services address multi-jurisdictional obligations spanning PDPC, NBTC, and potential Cybersecurity Act amendments.
On-site installation retains the largest current share; managed services demonstrates the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports data center security expertise and integrated infrastructure solutions throughout Southeast Asia, with Malaysian and Indonesian operators sourcing Thai system integrators for Tier-IV facility hardening projects.
Greater Bangkok Metropolitan Region
Hyperscale cloud campuses cluster along the Bang Na-Trat corridor and Lat Krabang industrial zones, driving concentrated procurement for multi-layered perimeter protection. The National Cyber Security Agency enforces critical infrastructure protection standards for government cloud workloads hosted in these facilities. Ratchada-Rama IX sub-markets attract financial services colocation operators upgrading biometric authentication systems to satisfy PDPC access logging mandates.
Eastern Economic Corridor
Chonburi and Rayong provinces host submarine cable landing stations that anchor hyperscale campus development, creating security procurement gravity in this corridor. The Eastern Economic Corridor Office coordinates infrastructure investment incentives that accelerate facility buildouts. Amata City and WHA industrial estates concentrate Tier-III and Tier-IV certified developments requiring European-certified intrusion detection systems for insurer compliance.
Chiang Mai and Northern Secondary Markets
Cool climate advantages attract disaster recovery and backup facility operators seeking lower cooling costs than Bangkok alternatives. The Digital Economy Promotion Agency extends investment privileges to northern provinces for data center developments. Mae Rim and Hang Dong districts host emerging facilities where labor scarcity for certified security integrators limits deployment velocity compared to capital-region projects.
Phuket and Southern Tourism Corridor
Hospitality and tourism technology infrastructure drives modest demand for localized data processing and edge computing facilities. The Tourism Authority of Thailand promotes digital infrastructure investment alongside traditional hospitality development. Kathu and Thalang districts concentrate small-scale colocation facilities serving regional hospitality chains with baseline surveillance and access control specifications.
Border Economic Zones
Mae Sot and Mukdahan special economic zones position facilities for cross-border data connectivity with Myanmar and Laos respectively. The National Economic and Social Development Board prioritizes digital infrastructure in these corridors for regional trade facilitation. These zones attract security procurement focused on perimeter hardening against higher physical risk profiles than interior markets.
Thailand Data Center Physical Security Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth and regulatory compliance expertise. The vendor base organizes into three discernible tiers: integrated infrastructure conglomerates bundling security with power and cooling monitoring, pure-play security technology manufacturers supplying AI-enhanced video analytics, and domestic managed services specialists offering outsourced facility hardening. Strategic moves concentrate on M&A to capture managed services capabilities and geographic expansion into secondary provinces where certified integrator scarcity creates white space.
Within the integrated infrastructure tier, Schneider Electric anchors bundled physical access and environmental monitoring positioning. Hikvision and Bosch Security Systems occupy distinct technology specialization positions—Chinese manufacturing scale versus European-certified intrusion detection expertise respectively. These three exemplify how competitive positioning separates on compliance certification depth rather than hardware specifications alone.
| Leading Market Players |
|---|
| Hikvision |
| Dahua Technology |
| Bosch Security Systems |
| Honeywell |
| Axis Communications |
| Johnson Controls |
| Securitas |
| Schneider Electric |
| Genetec |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for European-certified intrusion detection modules concentrate pricing power with specialist distributors serving Tier-IV facility deployments, compressing margins for domestic integrators unable to forward-position inventory against PDPA-mandated upgrade cycles.
Pricing Analysis
Foreign cloud operators anchor project-based pricing for integrated facility hardening contracts, with three-tier pricing structure across premium, standard, and economy levels separating Tier-IV certified installations from retrofits of legacy access control systems. Price differentiation hinges on certification grade and after-sales compliance reporting depth. Pricing pressure stems from hyperscale entrants prioritizing speed-to-operation over equipment margin capture. Domestic colocation operators exhibit highest price sensitivity due to capex reallocation toward PDPA retrofit obligations.
Supply Chain Analysis
Just-in-time inventory strategies dominate domestic surveillance equipment procurement, while strategic stockpiling of high-availability biometric sensors mitigates single-source vulnerability from Chinese and South Korean component manufacturers. The supply chain draws from specialized production clusters in China for AI-enhanced video analytics hardware, Germany for European-certified intrusion modules, and Taiwan for advanced sensor components. Tariff exposure on semiconductor inputs creates procurement risk for biometric authentication system integrators. Distribution runs through Bangkok-based system integrators with Tier-IV certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's data center physical security market exhibits cyclical recovery characteristics as PDPA enforcement compresses replacement cycles and hyperscale campus buildouts concentrate procurement waves in the Eastern Economic Corridor.
For Market Incumbents: Compound defensive positioning through backward integration into managed security services capabilities, capturing margin pools from foreign operators lacking Thai regulatory expertise. Prioritize certification investment for Tier-IV facility hardening credentials to differentiate against labor-constrained competitors in secondary provinces. Channel control over Eastern Economic Corridor project pipelines offers the strongest lever against emerging domestic specialists. For New Entrants and Emerging Players: Tier-III certification fast-tracks for financial services colocation operators create immediate addressable market entry. White space concentrates in Chiang Mai and northern secondary markets where certified integrator scarcity limits incumbent deployment velocity. Government cloud security tier procurement represents the most penetrable segment given National Cyber Security Agency critical infrastructure protection standard expansion. Outcome-based facility hardening contracts with bundled compliance reporting offer the strongest go-to-market angle against equipment-resale incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate security divisions lacking integrated infrastructure positioning. Long-term viability favors specialists combining AI-video convergence capabilities with power and cooling monitoring platform integration. Acquisition focus should center on domestic managed services providers with established PDPC and NBTC regulatory relationships. Watch for Cybersecurity Act amendment passage as the inflection signal triggering mandatory personnel clearance requirements and reshaping procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Services Capability Buildout | Captures margin pools from foreign hyperscalers outsourcing Thai regulatory compliance. |
| Tier-IV Certification Investment | Enables premium positioning for insurer-mandated intrusion detection specifications. |
| AI-Video Platform Integration | Bundles behavioral analytics with environmental monitoring for centralized operations. |
| Eastern Economic Corridor Expansion | Positions near submarine cable landing stations attracting hyperscale campus clustering. |
| Regulatory Compliance Advisory Services | Addresses multi-jurisdictional obligations spanning PDPC, NBTC, and Cybersecurity Act amendments. |
Research Methodology
Operator-level perspectives from data center facility managers, security systems integrators, colocation procurement leads, and National Cyber Security Agency compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through NBTC submarine cable security protocols, PDPC enforcement guidelines, Eastern Economic Corridor Office investment disclosures, and customs import records for biometric sensor shipments. Bottom-up facility deployment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory amendment timing and hyperscale entry velocity assumptions. Segmentation modeling incorporated product type, end user vertical, technology layer, and installation type dimensions alongside geographic concentration patterns across Greater Bangkok and Eastern Economic Corridor sub-markets. CAGRs derived from facility pipeline tracking and replacement cycle analysis. Industry-specific inputs included PDPA retrofit obligation schedules and Tier-III/Tier-IV certification pipeline data.
Decision-makers should treat outputs as directional under sustained PDPA enforcement intensity and hyperscale campus commitment continuity; material deviation would warrant model refresh. Forecasts reflect these base assumptions alongside import lead time stability and certified integrator labor availability. Revision becomes warranted when Cybersecurity Act amendment passage crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Virtual Infrastructure Manager Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Canada Data Center Storage Market