
 India Home Textile Market | 2026-2036
India Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Textile Market Outlook
Market Context
Digital weaving and AI-driven design-to-manufacture workflows are reshaping how Indian home textile producers respond to custom orders and shorter fashion cycles. Welspun Living Ltd leverages its integrated spinning-to-retail infrastructure to control quality across global private-label contracts. Trident Group anchors its position through captive energy and in-house recycled fiber production, insulating margins from raw cotton volatility. Indo Count Industries Ltd differentiates via specialized bed linen collections targeting North American hospitality chains, while Vardhman Textiles Ltd sustains broad fabric supply relationships across tier-one and tier-two domestic brands.
Technical Definition and Segment Structure
India home textiles encompass woven, knitted, and non-woven fabric articles designed for interior residential and commercial environments, with thread counts typically ranging from 180 to 1,000 per square inch and finishes including mercerization, sanforization, and antimicrobial treatments for durability and hygiene performance. Bed linens dominate value generation within the product type dimension, though curtains command higher per-unit margins in premium cotton and silk grades. Cotton retains volume leadership across the material split, while polyester blends are gaining share in institutional hospitality procurement due to lower lifecycle maintenance costs. Online retail channels are expanding fastest among distribution pathways, though wholesale still controls bulk contract flow to hotel developers and corporate furnishing programs.
Regulatory Framework and Outlook
BIS certification requirements for textile fiber content labeling and the PLI scheme administered by the Ministry of Textiles together enforce quality transparency and capital investment discipline across the sector. FSSAI-adjacent hygiene protocols for hospitality-supply textiles, plus state-level pollution control mandates in Tamil Nadu and Gujarat, are elevating compliance costs for unorganized dyeing and finishing units. Stakeholders must monitor how BIS standards evolve for recycled content claims and whether the PLI scheme's technical eligibility thresholds consolidate capacity among the largest integrated mills.
Market Dynamics
Digital weaving and AI-driven design-to-manufacture workflows are compressing production cycles for Indian home textile mills, forcing capital upgrades across Gujarat and Tamil Nadu clusters to retain contract viability against Bangladeshi and Vietnamese competitors.
Growth Catalysts
- PLI scheme incentives:The Ministry of Textiles' production-linked incentive scheme subsidizes large-scale manufacturing upgrades, concentrating capacity expansion among integrated spinners in Tamil Nadu and Gujarat.
- Hospitality procurement:North American hotel chains are diversifying sourcing away from China, directing bed linen and towel contracts toward Indian mills with BIS-certified quality systems.
- Digital printing adoption:Reactive and pigment inkjet systems are displacing rotary screen methods, enabling 500-unit minimum order runs for custom residential décor.
Market Restraints
- Cotton price volatility:Raw fiber costs swing with monsoon-dependent domestic harvests and ICE futures speculation, squeezing margin predictability for unhedged mid-scale weavers.
- Dyeing compliance costs:Tamil Nadu Pollution Control Board zero-liquid-discharge mandates require effluent treatment investments that fragment processing capacity between compliant clusters and informal units.
- Polyester blend substitution:Institutional hospitality buyers are migrating toward lower-lifecycle-cost synthetic-cotton mixes, eroding pure cotton volume premiums in contract segments.
Strategic Opportunities
- Recycled fiber integration:Trident Group's captive recycled polyester production demonstrates a replicable model for margin insulation against virgin cotton volatility.
- Direct-to-retail channels:Urban millennial demand for curated residential décor is bypassing traditional wholesale layers, opening branded e-commerce positions for quality-certified mills.
- Antimicrobial finish specialization:Post-pandemic hygiene protocols in healthcare and premium hospitality are creating specification premiums for silver-ion and quaternary ammonium treatments.
Industry Challenges
- Design-to-delivery talent scarcity:Mills struggle to recruit technicians fluent in both jacquard programming and ERP workflow management, slowing digital transformation timelines.
- BIS certification bottlenecks:Fiber content labeling verification queues at Bureau of Indian Standards regional labs delay export shipment schedules by 4-8 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Textile Market |
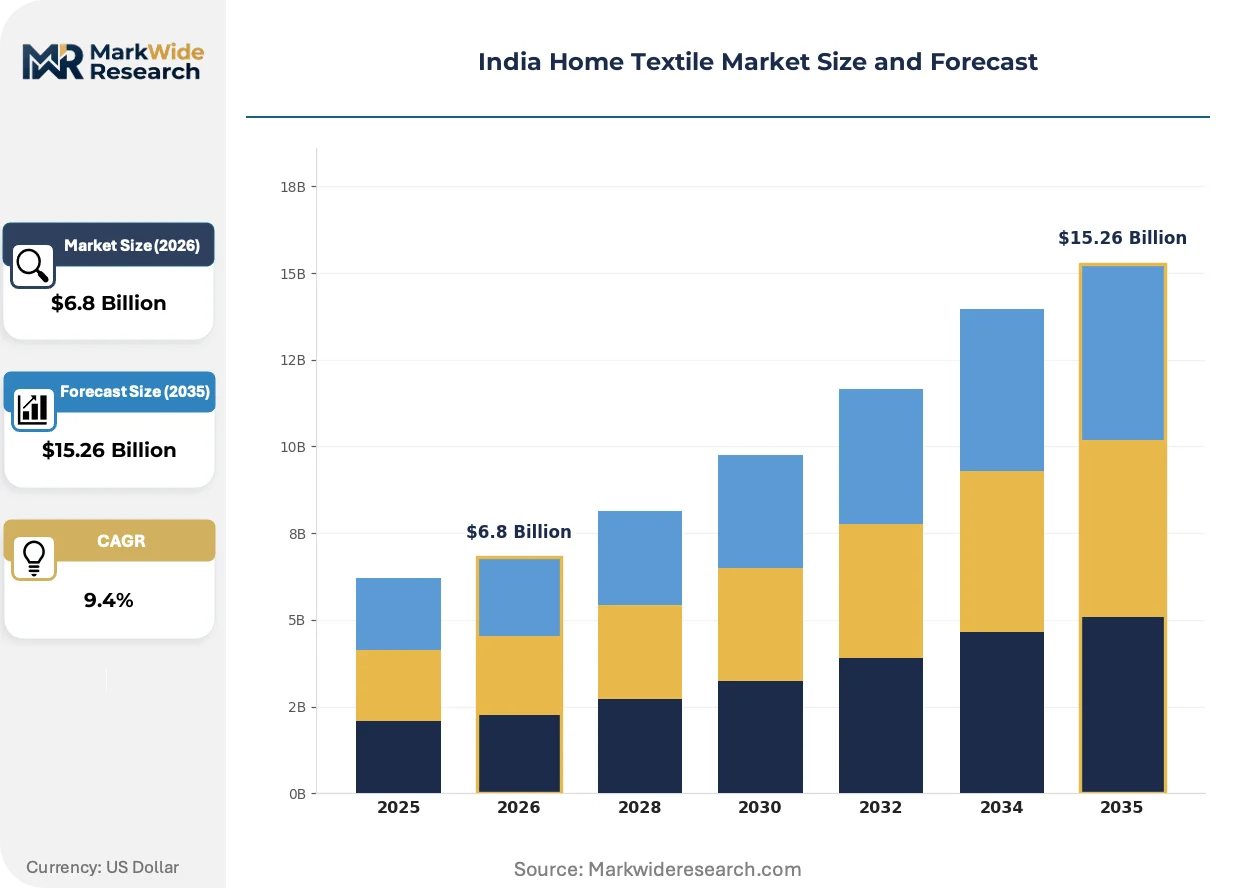
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cushions, Curtains, Bed Linens, Table Covers Material: Cotton, Polyester, Linen, Silk Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale Customer Type: Residential, Hospitality, Commercial, Institutional |
| Companies Covered | Himatsingka Seide Ltd., Welspun Living Ltd, Welspun Group, Vardhman Textiles Ltd, Alok Industries Ltd, Trident Group, GHCL Ltd., Jaipur Rugs, Indo Count Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Textile Market Strategic Shifts
Automation and sustainability certification are rewriting competitive rules for Indian home textile producers, compressing the viable scale threshold and fragmenting procurement relationships across residential and institutional channels.
Digital jacquard weaving is migrating from large-batch hotel contract production toward micro-batch residential customization. Mumbai and Pune-based interior designers now specify 50-unit runs with photographic pattern fidelity. This capability compression is collapsing the traditional 1,000-unit minimum viable order threshold for complex woven designs.
BIS certification requirements for textile fiber content labeling are tightening enforcement transparency across Maharashtra and Gujarat processing clusters. The Ministry of Textiles coordinates with customs authorities to block mislabeled shipments at Nhava Sheva and Mundra ports. Export-oriented mills in Tamil Nadu are accelerating in-house testing laboratory investments to preempt detention risks.
Millennial residential buyers now research thread count claims and finish certifications through mobile channels before store visits, collapsing the information asymmetry that historically favored wholesale intermediaries. Direct brand engagement via Instagram and curated marketplaces is displacing distributor relationships in premium cotton bedding segments across tier-one Indian cities.
India Home Textile Market Segmentation
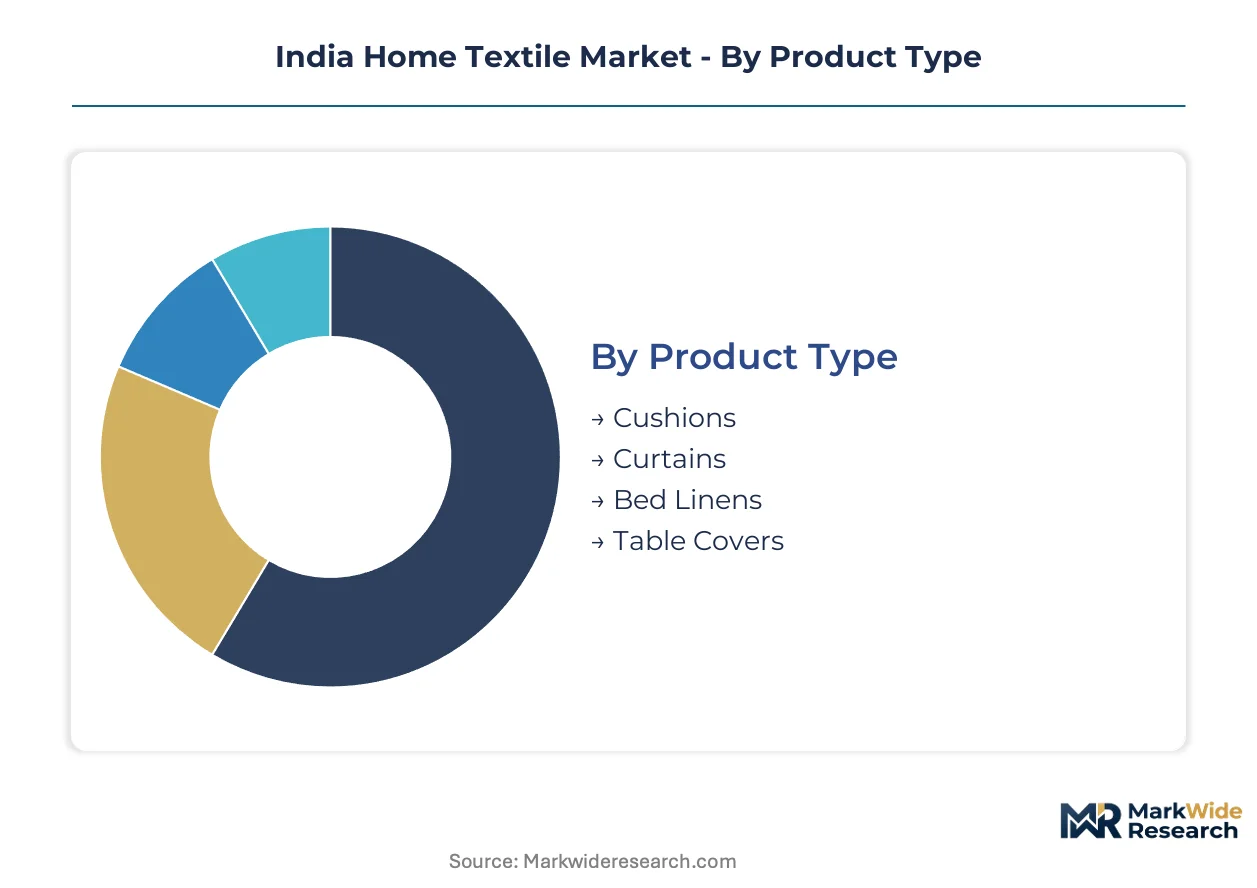
Segmentation in the India home textile market reveals how procurement patterns diverge across institutional buyers seeking lifecycle cost efficiency and residential consumers prioritizing tactile quality. Each dimension exposes distinct margin structures and compliance thresholds that shape supplier positioning.
Product Type:
Home textile articles span functional utility objects through decorative statement pieces, with thread count specifications and finish treatments varying sharply across the use-case spectrum.
- Bed Linens:Woven cotton and cotton-blend sheeting with thread counts from 180 to 1,000 per square inch dominates contract value. Maharashtra's hospitality project pipeline in Mumbai and Pune concentrates procurement for premium fitted and flat sheet collections.
- Curtains:Heavier GSM fabrics with blackout lining and thermal interlinings command elevated per-unit margins. Tamil Nadu's integrated mills capture specification-driven demand from commercial office developers seeking fire-retardant certifications.
- Cushions:Decorative accent pieces with digital-printed covers and varied fill materials target urban millennial refresh cycles.
- Table Covers:Stain-resistant treated cotton and polyester blends serve institutional catering procurement with standardized sizing.
The dominant share belongs to Bed Linens, while Curtains is closing the gap fastest.
Material:
Raw fiber selection determines processing route, dyeing chemistry, and end-use certification eligibility across Gujarat and Tamil Nadu manufacturing clusters.
- Cotton:Natural fiber retaining volume leadership across residential channels, with long-staple varieties from Gujarat commanding premium positioning. Monsoon-dependent harvest volatility and ICE futures speculation constrain margin predictability for unhedged processors.
- Polyester:Synthetic fiber gaining procurement share in hospitality and institutional segments where lifecycle maintenance costs outweigh tactile preferences. Lower water absorption rates reduce laundering energy consumption.
- Linen:Bast fiber from flax cultivation delivering superior moisture wicking and thermal regulation for premium residential bedding.
- Silk:Protein fiber reserved for luxury decorative applications with restricted scale due to mulberry cultivation constraints and hand-processing requirements.
Cotton maintains the largest installed base, though Polyester is expanding most quickly in contract segments.
Distribution Channel:
Channel structure reflects the tension between curated brand experience and bulk contract efficiency, with digital penetration reshaping residential access patterns.
- Online Retail:Direct-to-consumer platforms collapsing information asymmetry through thread count transparency and finish certification display. Urban millennial research behavior via mobile channels precedes purchase decisions.
- Wholesale:Bulk contract channel controlling flow to hotel developers and corporate furnishing programs with volume-based pricing and BIS certification documentation.
- Specialty Stores:Tactile retail environments enabling fabric handle assessment for premium cotton and silk grades.
- Department Stores:Mid-tier positioned multi-brand aggregators serving standardized residential replacement cycles.
Wholesale retains the deepest contract penetration, yet Online Retail is climbing the fastest among residential buyers.
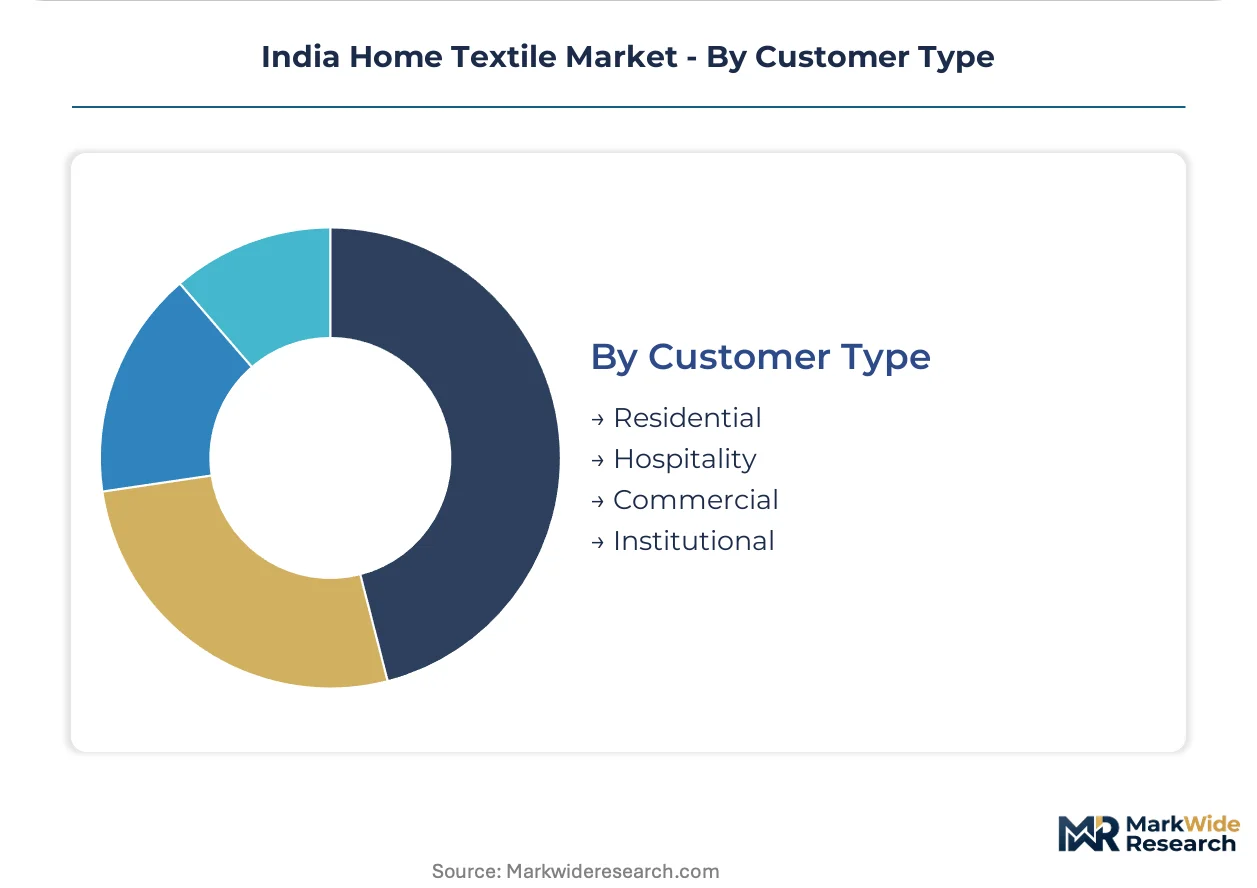
Customer Type:
End-user categories impose divergent specification regimes, with institutional procurement prioritizing durability certification and residential buyers emphasizing aesthetic curation.
- Hospitality:Hotel and resort operators sourcing bed linens and towels with antimicrobial finishes and commercial laundering durability. North American chains diversifying from China direct contract flow toward BIS-certified Indian mills.
- Residential:Individual consumers and interior designers specifying custom jacquard weaves and digital-printed decorative textiles with shortened fashion cycles.
- Commercial:Office and retail space developers procuring flame-retardant curtains and acoustic-dampening panels with standardized lifecycle replacement schedules.
- Institutional:Healthcare and educational facilities requiring hygiene-protocol compliance and bulk procurement efficiency with lower per-unit quality thresholds.
Hospitality anchors the highest-value contract segment, while Residential is gaining share fastest through direct brand engagement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian home textile exports flow predominantly toward North American hospitality chains and European retail distributors, with containerized shipments departing from Mundra and Nhava Sheva ports serving contract buyers seeking BIS-certified quality documentation.
Maharashtra
Mumbai and Pune host India's densest retail and hospitality project pipelines, driving procurement for premium fitted sheet collections and custom jacquard weaves. The state's urban millennial population researches thread count claims via mobile channels before store visits, collapsing traditional wholesale information asymmetry. Maharashtra's interior designers now specify 50-unit micro-batch runs with photographic pattern fidelity from Tamil Nadu-based digital weaving clusters.
Gujarat
Long-staple cotton varieties from Gujarat's agricultural belt command premium positioning in residential bedding segments. The Ministry of Textiles' PLI scheme subsidizes large-scale manufacturing upgrades across Surat and Ahmedabad spinning-to-finishing corridors. Captive energy installations and in-house recycled fiber production insulate integrated mills from raw cotton price volatility driven by monsoon-dependent harvest fluctuations.
Tamil Nadu
Tiruppur and Coimbatore processing clusters face Tamil Nadu Pollution Control Board zero-liquid-discharge mandates requiring effluent treatment investments that fragment capacity between compliant units and informal dyeing operations. BIS certification verification queues at regional labs delay export shipment schedules, accelerating in-house testing laboratory investments among export-oriented mills. Digital jacquard weaving capability compresses minimum viable order thresholds for complex residential customization.
Karnataka
Bengaluru's technology workforce generates demand for curated residential décor through direct brand engagement channels, bypassing traditional wholesale layers. The state's e-commerce logistics infrastructure supports same-day delivery promises for premium cotton bedding segments. Karnataka-based mills specialize in antimicrobial finish applications targeting post-pandemic healthcare and hospitality hygiene protocols.
Delhi-NCR
The National Capital Region serves as a distribution hub for North Indian hospitality and institutional procurement, with Ghaziabad and Noida warehousing clusters consolidating bulk shipments from Gujarat and Tamil Nadu production centers. Delhi-based corporate furnishing programs demand standardized lifecycle replacement schedules with BIS-certified fiber content labeling. The region's pollution control mandates elevate compliance costs for dyeing and finishing subcontractors.
India Home Textile Market Competitive Environment
On the supply side, the industry is consolidating around integrated spinners with captive energy and in-house testing laboratories, while mid-scale weavers face margin compression from unhedged cotton exposure and compliance cost fragmentation. Three strategic archetypes dominate: vertically integrated conglomerates controlling spinning-to-retail infrastructure, specialized bed linen exporters targeting North American hospitality chains, and regional rug specialists leveraging hand-processing heritage. Competitive intensity manifests through capacity expansion in Tamil Nadu and Gujarat PLI-eligible zones, plus strategic partnerships between mills and direct-to-consumer platforms.
Among integrated textile conglomerates, Welspun Living Ltd and Trident Group exemplify the capital-intensive archetype with backward integration into spinning and finishing operations. Vardhman Textiles Ltd occupies a position bridging broad fabric supply relationships across domestic tier-one and tier-two brands. These three entities represent contrasting strategic postures: one emphasizing global private-label contract control, one demonstrating recycled fiber margin insulation, and one sustaining diversified channel presence across wholesale and retail segments.
| Leading Market Players |
|---|
| Himatsingka Seide Ltd. |
| Welspun Living Ltd |
| Welspun Group |
| Vardhman Textiles Ltd |
| Alok Industries Ltd |
| Trident Group |
| GHCL Ltd. |
| Jaipur Rugs |
| Indo Count Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Tamil Nadu's dyeing clusters compresses margin recovery for mid-scale weavers while simultaneously forcing compliant mills toward premium positioning. This utilization asymmetry drives bifurcated pricing behavior across Gujarat and Maharashtra procurement corridors.
Pricing Analysis
The technology-generation pricing gap separates rotary screen legacy systems from reactive inkjet digital platforms and emerging AI-driven jacquard weaving. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and volume scale, with hospitality contract buyers showing lowest price sensitivity due to lifecycle cost framing. Cost compression in the economy tier intensifies because polyester blend substitution erodes pure cotton premiums. Residential millennial segments exhibit highest price sensitivity through mobile-enabled transparency on thread count claims and finish certifications.
Supply Chain Analysis
Extended payment terms from North American hospitality chains strain working capital for non-integrated weavers, accelerating supply-chain finance facility adoption among Tamil Nadu processors. Raw material sourcing draws from Gujarat long-staple cotton, Tamil Nadu recycled polyester, and imported linen bast fiber. Single-source vulnerability concentrates in monsoon-dependent domestic cotton harvests tethered to ICE futures volatility. Distribution runs through Mundra and Nhava Sheva port consolidation for export contract flow, with e-commerce logistics bypassing wholesale layers for residential direct-to-retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against Bangladeshi and Vietnamese low-cost weaving capacity that is capturing standardized hospitality contract share. Incumbents must differentiate through certification depth and digital customization capability that offshore competitors cannot replicate at scale.
For Market Incumbents: Build captive testing laboratory moats to preempt BIS certification bottlenecks that delay export shipments by 4-8 weeks. Invest in backward integration into recycled fiber production to insulate margins from virgin cotton volatility driven by monsoon harvest fluctuations. Defend against polyester blend substitution threat by developing antimicrobial finish specialization for healthcare and premium hospitality specification premiums. For New Entrants and Emerging Players: Pursue micro-batch digital jacquard customization for Mumbai and Pune interior designers specifying 50-unit runs with photographic pattern fidelity. Target Karnataka's technology workforce through direct brand engagement channels bypassing traditional wholesale intermediaries. Leverage same-day delivery infrastructure in Bengaluru to establish curated residential décor positioning with urban millennial research behavior. For Investors and Strategic Acquirers: Capital is best deployed toward integrated spinners with captive energy and in-house testing laboratories that consolidate capacity under PLI scheme eligibility thresholds. Long-term viability across the analysis window favors mills demonstrating replicable recycled fiber margin insulation models. Watch for BIS standards evolution on recycled content claims as inflection indicator for compliance cost consolidation among largest integrated mills.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Production | Trident Group's captive polyester model insulates margins from ICE cotton futures speculation. |
| Direct-to-Consumer Platform Launch | Welspun Living Ltd leverages integrated spinning-to-retail infrastructure for private-label contract control. |
| BIS Certification Preemption Investment | In-house testing laboratories at Tamil Nadu mills bypass regional lab queues delaying export schedules. |
| Antimicrobial Finish Specialization | Silver-ion and quaternary ammonium treatments command specification premiums in post-pandemic healthcare procurement. |
| Digital Jacquard Capability Expansion | AI-driven design-to-manufacture workflows compress minimum order thresholds for residential customization. |
Study Parameters
Desk research of customs export records, Ministry of Textiles PLI scheme disclosures, and BIS certification databases preceded structured interviews with plant managers at integrated spinning mills, procurement leads at North American hospitality chains, Tamil Nadu Pollution Control Board compliance officers, and category buyers at Mumbai-based interior design studios. Bottom-up volume modeling across product type, material, distribution channel, and customer type segments was cross-validated through top-down expenditure analysis and trade flow triangulation.
Assumptions held fixed include PLI scheme continuation through the projection horizon and BIS enforcement intensity at current Nhava Sheva and Mundra port inspection rates. Variables included monsoon-dependent cotton harvest yields, polyester blend substitution velocity in institutional procurement, and digital printing adoption curves across Tamil Nadu and Gujarat clusters. CAGRs were derived from segment-level volume build-ups validated against macroeconomic expenditure elasticity. Forecast inputs incorporated hospitality project pipeline data for Maharashtra and Karnataka e-commerce logistics infrastructure expansion.
Sensitivities concentrate around PLI scheme technical eligibility threshold revisions and Tamil Nadu Pollution Control Board zero-liquid-discharge mandate enforcement fragmentation. Forecasts reflect these documented assumptions; monsoon failure frequency escalation, BIS recycled content standard acceleration, or Bangladeshi capacity expansion beyond current hospitality contract diversion rates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Germany Home Textile Market
Home Textiles
Latin America Home Textiles Market
Home Textiles
France Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Home Textiles Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
China Home Textiles Market
Home Textiles
Japan Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Australia Home Textiles Market
Home Textiles
Asia-Pacific Home Textile Market