
 Asia-Pacific Offshore Energy Market | 2026-2036
Asia-Pacific Offshore Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Offshore Energy Market Outlook
The divergence between premium floating-platform projects and commodity fixed-bottom installations is hardening across the Asia-Pacific basin. Ørsted leverages its European floating expertise to compete for Japanese and Korean tenders requiring water depths exceeding sixty meters. Ming Yang Smart Energy Group Ltd anchors its position through cost-competitive fixed-bottom turbines purpose-built for China's shallow coastal shelves. Siemens Gamesa specializes in next-generation direct-drive generators that differentiate performance in typhoon-prone zones.
Asia-Pacific offshore energy encompasses hydrocarbon extraction and renewable electricity generation from seabed-fixed or floating infrastructure operating in marine environments with salinity corrosion, wave loading, and subsea pressure constraints; its primary purpose is delivering baseload or intermittent power to coastal demand centers while exploiting untapped seabed resource frontiers. Floating platform technology captures the fastest expansion trajectory as developers target depths beyond fifty meters where fixed foundations prove uneconomical. Subsea infrastructure remains the most mature margin pool, though hybrid solutions combining offshore wind with green hydrogen electrolysis are attracting new capital commitments from utilities and independent producers seeking integrated output streams.
Japan's METI enforces stringent domestic content requirements that reshape supply chain localization for foreign entrants bidding on offshore wind auctions. China's MIIT coordinates GB standards for turbine certification and grid interconnection that dictate product specifications for equipment suppliers across the regional market. Australia's TGA-equivalent offshore petroleum safety framework and South Korea's renewable portfolio standards together create a multi-jurisdictional compliance burden that stakeholders must map before committing capital to cross-border project pipelines.
Market Dynamics
Floating platform maturation is compressing the economic viability gap between deep-water and shallow-water developments, redirecting capital flows toward previously inaccessible seabed zones across the Asia-Pacific basin.
Growth Catalysts
- Japan METI Feed-in Tariff:The ministry's price guarantee mechanism for offshore wind output stabilizes revenue forecasting for developers targeting Pacific-facing prefectures with challenging bathymetry.
- Green Hydrogen Electrolysis:Hybrid configurations combining turbine arrays with subsea hydrogen production are unlocking integrated offtake agreements with industrial buyers in Korea and Australia seeking decarbonized feedstocks.
- Jiangsu and Guangdong Clusters:Provincial competition to anchor manufacturing ecosystems is accelerating localized supply chain formation and specialized vessel fabrication capacity.
Market Restraints
- Specialized Installation Vessel Scarcity:Heavy-lift jack-up vessel availability concentrates among European and Korean yards, creating bottleneck risk for project timelines across the region.
- Typhoon-Resistant Design Costs:Reinforced nacelle and blade engineering for Category 4+ wind zones adds material cost premiums that compress project IRRs in subtropical development zones.
- Subsea Cable Manufacturing Concentration:High-voltage DC cable production clusters in European and Japanese facilities, exposing projects to extended lead times and currency exposure.
Strategic Opportunities
- Vietnam Unlicensed Zone Auctions:The government's emerging offshore wind licensing framework offers first-mover positioning in shallow Gulf of Tonkin waters with favorable capacity factors.
- Floating-Platform Technology Convergence:Integration of semi-submersible hull designs with dynamic cable systems is opening depths beyond sixty meters where seabed leases face limited competition.
- Australia Offshore Petroleum Safety Framework Adaptation:Regulatory harmonization between oil and gas safety protocols and renewable installations is streamlining permitting for hybrid hydrocarbon-wind operators.
Industry Challenges
- Marine Electrical Technician Shortage:Specialized skills for high-voltage subsea terminations and converter platform maintenance outpace regional training pipeline output.
- GB Standard Certification Timelines:China's MIIT turbine certification protocols create extended validation periods for foreign equipment suppliers seeking grid interconnection approval.
- Domestic Content Requirement Mapping:Japan's local sourcing mandates force supply chain reconfiguration mid-project, complicating procurement planning for integrated developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Offshore Energy Market |
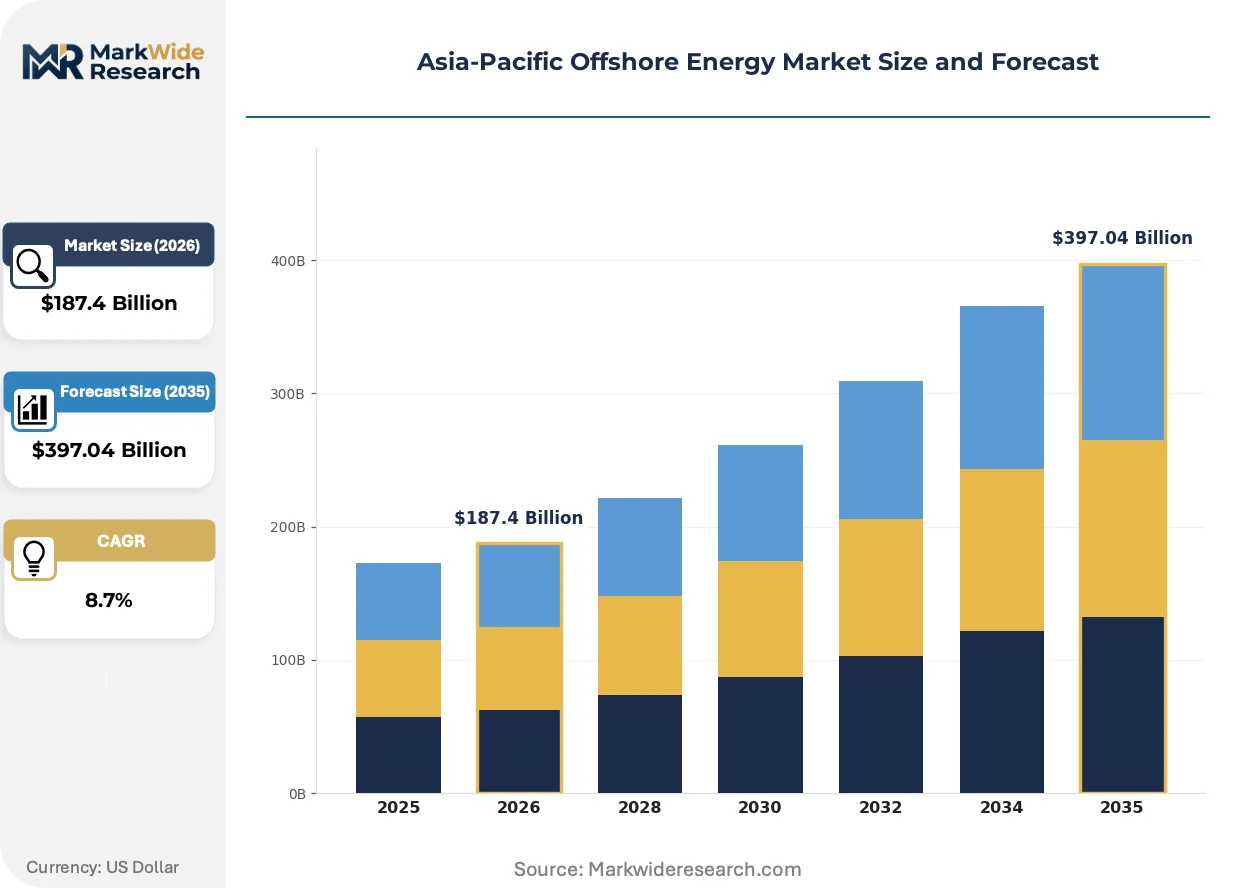
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Oil, Gas, Wind, Solar Service Type: Exploration, Production, Decommissioning, Consulting Technology: Subsea, Floating Platforms, Renewable Systems, Hybrid Solutions End User: Utilities, Independent Producers, Government Agencies, Contractors |
| Companies Covered | Xinjiang Goldwind Science & Technology Co., Ltd, Ming Yang Smart Energy Group Ltd, Suzlon Energy Ltd, Envision Group, Mitsubishi Heavy Industries Ltd, Shanghai Electric, Ørsted, Siemens Gamesa, MHI Vestas, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Offshore Energy Market Strategic Shifts
Technology convergence and regulatory adaptation are compressing development cycles while expanding addressable water depths across the Asia-Pacific offshore energy corridor.
Direct-drive generator architectures are unifying power conversion efficiency with reduced mechanical complexity in typhoon-exposed installations. Chinese and Korean utilities are specifying these systems for new tenders in the East China Sea. The technology is unifying operational reliability targets with lower maintenance access requirements in remote offshore environments.
South Korea's renewable portfolio standards are mandating offshore wind procurement quotas for major power utilities, forcing KEPCO and regional generation subsidiaries into accelerated project origination. The policy is compressing development timelines and intensifying competition for seabed leases in the Yellow Sea. Domestic vessel fabrication requirements embedded in the framework are redirecting capital toward Korean shipyard partnerships.
Integrated service contracts covering turbine supply, installation, and long-term O&M are displacing fragmented procurement across Asia-Pacific utility buyers. State-owned power companies in China and Vietnam are consolidating vendor relationships to reduce interface risk. This pattern is most visible in Guangdong province, where provincial energy groups are negotiating decade-spanning performance guarantees with single-source suppliers.
Asia-Pacific Offshore Energy Market Segmentation
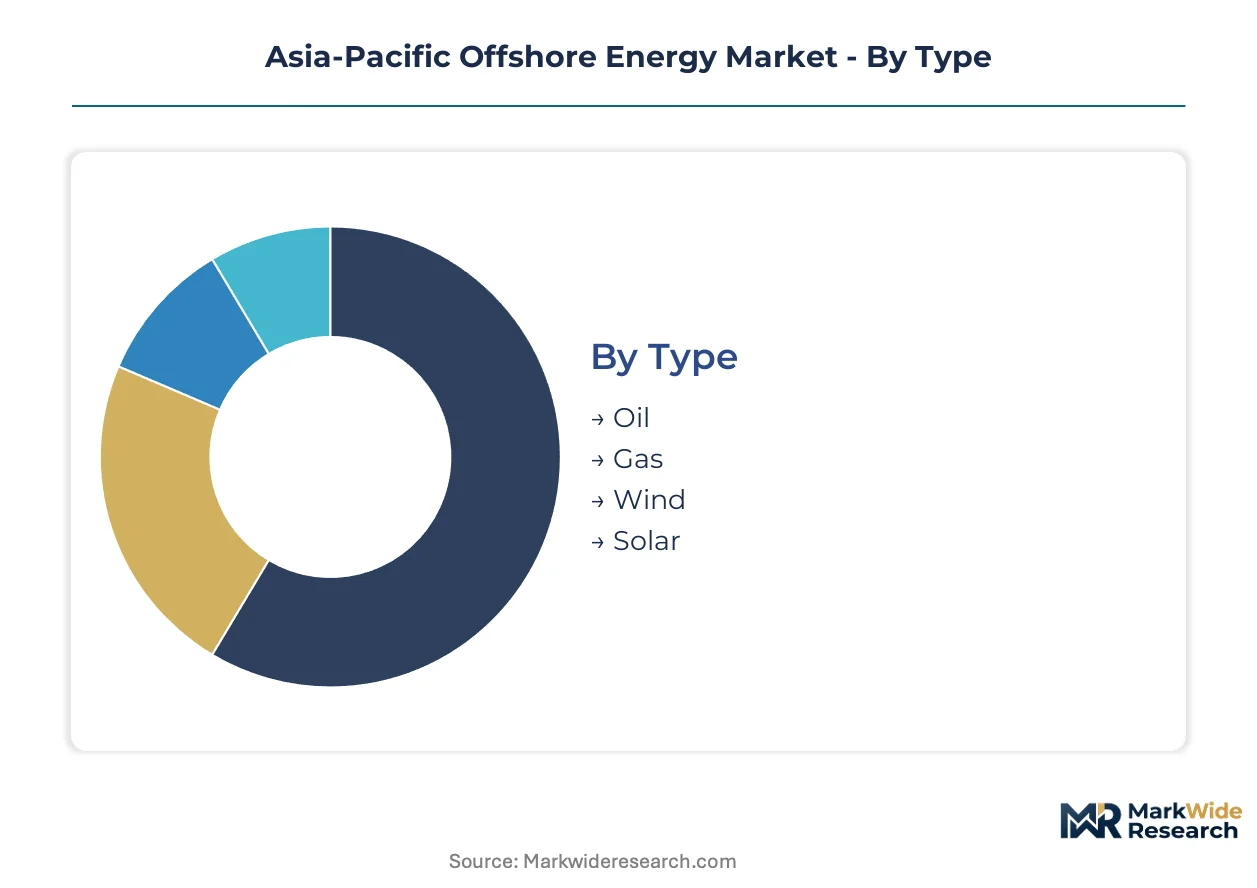
Segmentation in the Asia-Pacific offshore energy market reveals divergent capital allocation patterns between mature hydrocarbon basins and emerging renewable installations. Understanding these divisions enables stakeholders to align technical capabilities with specific regulatory and bathymetric requirements across coastal jurisdictions.
Type:
Upgrade cycles differ sharply between hydrocarbon assets requiring decommissioning planning and renewable installations demanding next-generation turbine replacements. China's provincial energy groups are driving the fastest replacement schedules in offshore wind arrays.
- Oil:Subsea extraction infrastructure in the South China Sea and Australia's North West Shelf operates at declining reservoir pressures, requiring enhanced recovery investments. Operators in Indonesia's Natuna basin face mature field economics that compress maintenance budgets.
- Gas:Deep-water LNG feedstock developments off Myanmar and Malaysia anchor regional liquefaction capacity expansions. Demand concentrates in East Asian import terminals where spot pricing volatility shapes field development timelines.
- Wind:Fixed-bottom arrays dominate Jiangsu and Guangdong coastal zones. Floating platforms gain traction in Japan's Pacific-facing prefectures where water depths exceed sixty meters.
- Solar:Floating photovoltaic installations on inland reservoirs and near-shore lagoons in Vietnam and Thailand provide distributed generation alternatives to seabed-fixed infrastructure.
Wind sits at the top of the volume ranking, with floating platform developments climbing the fastest.
Service Type:
Cost tier differentiation separates integrated full-field contractors from specialized niche operators. Premium service providers command pricing power through proprietary geophysical datasets and proprietary installation methodologies.
- Exploration:Seismic surveying and reservoir characterization services concentrate among European and North Asian contractors with proprietary 4D imaging capabilities. Australia's offshore petroleum safety framework mandates specific survey protocols that reshape procurement specifications.
- Production:Subsea tieback engineering and floating production system operations generate recurring revenue streams. Chinese yards are capturing fabrication contracts for FPSO hulls and topside modules through cost-competitive bidding.
- Decommissioning:Rig removal and well plugging obligations are accelerating in Southeast Asia's mature basins. Japan's METI guidelines for offshore wind end-of-life protocols are creating new regulatory compliance categories.
- Consulting:Regulatory navigation and environmental impact assessment services support cross-border project origination. Domestic content requirement mapping across multiple jurisdictions drives demand for localized advisory capacity.
Production commands the largest revenue share, with decommissioning services expanding most quickly as first-generation offshore assets reach end-of-life.
Technology:
Application-specific engineering requirements dictate vendor selection across divergent marine environments. Typhoon exposure and water depth constraints filter technology choices in subtropical development zones.
- Subsea:Manifold and pipeline infrastructure for hydrocarbon transport remains the most mature installed base. Corrosion-resistant metallurgy and pressure-rated equipment specifications dominate procurement criteria in high-salinity environments.
- Floating Platforms:Semi-submersible hull designs and tension-leg platforms enable production in depths exceeding five hundred meters. South Korean shipyards and Chinese fabrication yards are competing for hull construction contracts.
- Renewable Systems:Direct-drive generators and typhoon-resistant nacelle designs address reliability requirements in East Asian wind zones. China's MIIT certification protocols create validation bottlenecks for foreign equipment suppliers.
- Hybrid Solutions:Integrated offshore wind with green hydrogen electrolysis is attracting utility capital in Korea and Australia. Subsea hydrogen pipeline routing and converter platform engineering remain nascent technical domains.
Subsea infrastructure retains the largest installed base, with hybrid solutions gaining share fastest through integrated offtake agreements.
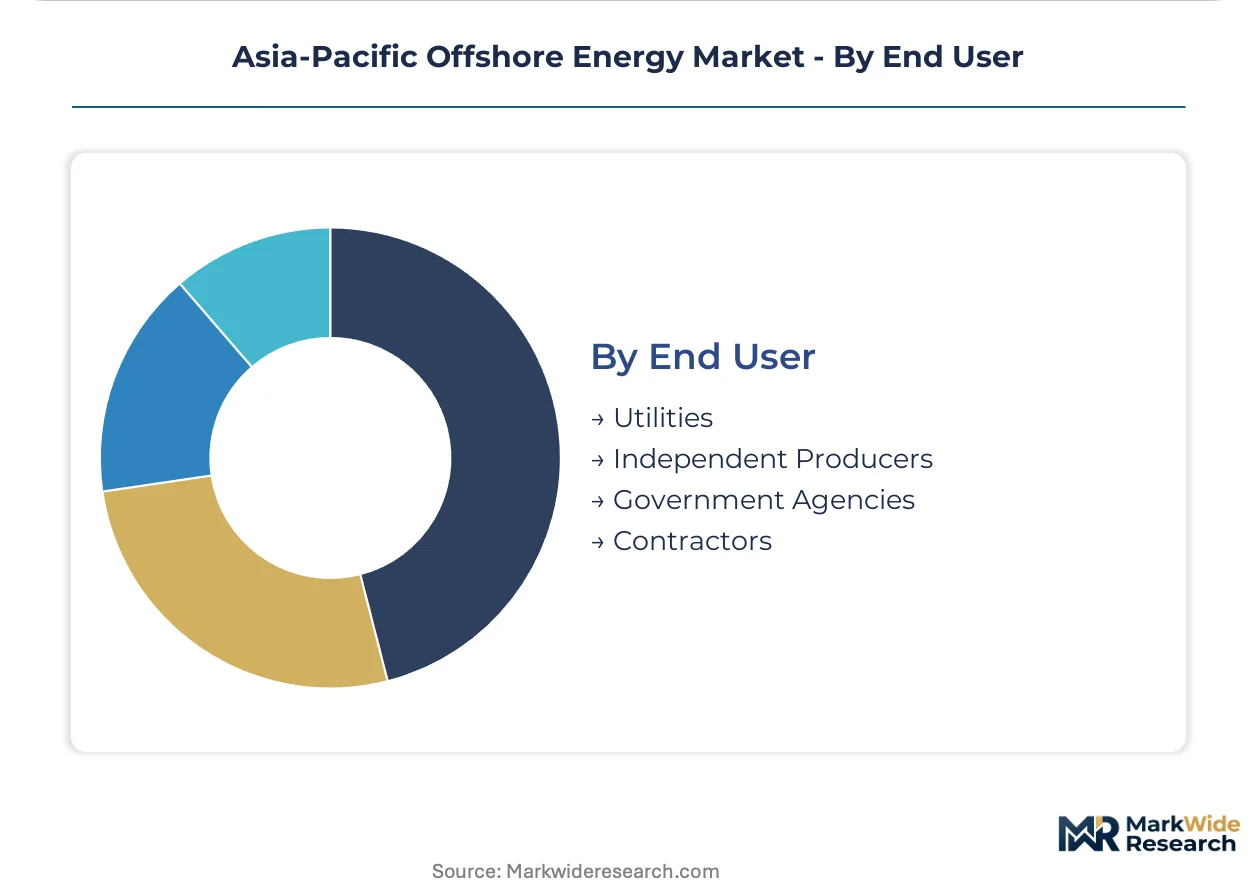
End User:
Customer type determines contracting structures and risk allocation mechanisms. State-backed entities prioritize supply security and local content compliance over pure commercial returns.
- Utilities:KEPCO and China's provincial grid companies are mandating offshore wind procurement quotas under renewable portfolio standards. Long-term power purchase agreements with industrial offtakers stabilize project finance structures.
- Independent Producers:Oil and gas specialists and renewable developers operate without guaranteed rate-base recovery. These entities concentrate in Vietnam's emerging licensing framework and Australia's offshore petroleum adaptation zones.
- Government Agencies:Japan's METI and China's NDRC administer auction mechanisms and feed-in tariff regimes that reshape competitive dynamics. Direct equity participation in strategic projects is increasing across coastal jurisdictions.
- Contractors:Engineering, procurement, and construction firms execute integrated service contracts covering turbine supply through long-term O&M. State-owned power companies in Vietnam are consolidating vendor relationships to reduce interface risk.
Utilities dominate capital deployment, with independent producers climbing fastest in Vietnam's unlicensed zone auctions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine electrical technicians and floating platform engineers concentrate in Japan's Pacific prefectures and China's coastal manufacturing belts. These talent pools anchor project execution capacity across the region's most active development zones. Workforce mobility between hydrocarbon and renewable sectors accelerates knowledge transfer.
China
Jiangsu and Guangdong provinces drive fixed-bottom turbine demand through provincial manufacturing cluster competition. MIIT coordinates GB standards for turbine certification and grid interconnection that dictate equipment specifications. Specialized vessel fabrication yards in Nantong and Zhuhai anchor supply chain localization for domestic and export markets.
Japan
Pacific-facing prefectures target deep-water floating platforms as fixed foundations prove uneconomical beyond sixty meters. METI feed-in tariff regimes stabilize revenue forecasting for developers in challenging bathymetry. Domestic content requirements force supply chain reconfiguration for foreign entrants bidding on auction rounds.
South Korea
KEPCO and regional generation subsidiaries face accelerated procurement quotas under renewable portfolio standards. Domestic vessel fabrication requirements redirect capital toward Korean shipyard partnerships for heavy-lift installation capacity. The Yellow Sea seabed lease competition intensifies as utilities compress development timelines.
Vietnam
Shallow Gulf of Tonkin waters attract first-mover positioning in unlicensed zone auctions with favorable capacity factors. Provincial governments compete to anchor turbine manufacturing clusters near existing port infrastructure. State-owned power companies consolidate vendor relationships to reduce interface risk in integrated service contracts.
Australia
Hybrid hydrocarbon-wind operators seek regulatory harmonization between offshore petroleum safety frameworks and renewable installations. Green hydrogen electrolysis integration attracts utility capital seeking decarbonized feedstock offtake agreements. Subsea infrastructure expertise from mature LNG developments transfers to floating platform engineering.
Asia-Pacific Offshore Energy Market Competitive Environment
Capital-heavy turbine manufacturers compete with asset-light project developers and specialized service providers across the Asia-Pacific basin. Market structure tilts toward consolidation as state-backed utilities mandate long-term performance guarantees and single-source procurement. Three archetypes dominate: integrated European developers with floating platform expertise, Chinese equipment suppliers with cost-competitive fixed-bottom offerings, and hybrid industrial conglomerates spanning hydrocarbon and renewable segments. Competitive moves center on supply chain localization partnerships and technology licensing agreements to satisfy domestic content mandates.
Among China-based fabricators, Xinjiang Goldwind Science & Technology Co., Ltd and Ming Yang Smart Energy Group Ltd occupy positions within the cost-optimized equipment tier, while Ørsted represents the European floating platform specialist archetype in regional tender competitions. These entities exemplify divergent strategic positioning between standardized turbine manufacturing for shallow-water markets and premium technology deployment in deep-water jurisdictions.
| Leading Market Players |
|---|
| Xinjiang Goldwind Science & Technology Co., Ltd |
| Ming Yang Smart Energy Group Ltd |
| Suzlon Energy Ltd |
| Envision Group |
| Mitsubishi Heavy Industries Ltd |
| Shanghai Electric |
| Ørsted |
| Siemens Gamesa |
| MHI Vestas |
| Others |
Value Chain & Pricing Dynamics
Steel plate price indices from East Asian commodity exchanges cascade through turbine tower fabrication costs, compressing margins for fixed-bottom installations while floating platform projects absorb premiums through specialized semi-submersible hull engineering. China's MIIT certification timelines and Japan's METI domestic content requirements reshape procurement arbitrage between standardized and customized supply tiers.
Pricing Analysis
Bundled integrated service contracts covering turbine supply through long-term O&M command premium pricing over unbundled component procurement. Price differentiation rests on certification grade under GB standards and volume scale of provincial utility buyers. Cost compression in fixed-bottom arrays intensifies because Chinese fabricators expand Nantong and Zhuhai yard capacity. State-owned power companies in Guangdong exhibit lowest price sensitivity; independent producers in Vietnam's auction rounds show highest.
Supply Chain Analysis
Regional distribution centers in Nantong, Ulsan, and Yokohama anchor hub-and-spoke patterns for heavy-lift components and specialized vessels. Manufacturing concentrates in China, South Korea, and Japan for turbine assembly and floating platform hull fabrication. Critical inputs draw from rare earth magnet suppliers, high-voltage cable producers, and corrosion-resistant alloy foundries. Single-source vulnerability concentrates in European and Japanese high-voltage DC cable facilities. Distribution runs through port-centric consolidation points serving Pacific-facing development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Japan's METI feed-in tariff regime and South Korea's renewable portfolio standards generate durable procurement mandates that outlast commodity price cycles.
For Market Incumbents: To counter specialized installation vessel scarcity, secure multi-year charter agreements with Korean and Chinese yards before tender deadlines compress availability. Deepen backward integration into typhoon-resistant nacelle engineering to defend margin position against Ming Yang and Goldwind cost leadership in shallow-water segments.
For New Entrants and Emerging Players: Launch via integrated service contracts targeting Vietnam's unlicensed zone auctions where state-owned power companies consolidate vendor relationships to reduce interface risk. White-space opportunity concentrates in floating-platform dynamic cable systems and subsea hydrogen pipeline routing for Korean and Australian hybrid projects.
For Investors and Strategic Acquirers: Asymmetric upside sits with semi-submersible hull fabricators and marine electrical technician training platforms serving Japan's Pacific prefectures. Long-term viability favors entities with captive vessel access and METI-compliant supply chain localization. Monitor KEPCO procurement quota acceleration as inflection indicator for Yellow Sea lease competition intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Technology Licensing | Enables deep-water access beyond sixty meters where METI tariffs stabilize returns. |
| Domestic Content Partnership Formation | Satisfies Japan's local sourcing mandates and accelerates grid interconnection approval timelines. |
| Heavy-Lift Vessel Charter Securement | Resolves bottleneck risk as European and Korean yard capacity concentrates among incumbents. |
| Green Hydrogen Electrolysis Integration | Unlocks industrial offtake agreements with Korean and Australian decarbonization buyers. |
| GB Standard Certification Investment | Reduces validation periods for foreign equipment suppliers seeking Chinese grid access. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from IEA reports, EIA data, FERC filings, and project development databases. Bottom-up capacity installation tracking and top-down regulatory framework analysis triangulated market sizing across the analysis window.
Segment-weighting approaches applied differential growth assumptions to fixed-bottom versus floating platform technologies, hydrocarbon extraction versus renewable generation, and provincial versus national regulatory clusters. CAGRs derived from modeled capacity deployment curves and tariff regime stability assessments. Forecast inputs incorporated vessel fabrication lead times and MIIT certification pipeline backlogs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under METI auction schedule delays and typhoon damage frequency excursions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Offshore Contract Drilling Market