
 Oil and Gas Asset Integrity Management Services Market | 2026-2036
Oil and Gas Asset Integrity Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Asset Integrity Management Services Market Analytics
The gap between premium risk-based integrity programs and commodity inspection schedules is rebalancing as operators prioritize predictive maintenance over calendar-driven compliance. DNV AS leverages its classification heritage to anchor high-complexity offshore contracts across the North Sea and Gulf of Mexico. Bureau Veritas competes through its laboratory network and certification authority in corrosion monitoring protocols. Baker Hughes differentiates by integrating sensor hardware with proprietary data analytics platforms for real-time pipeline wall-thickness tracking.
Oil and Gas Asset Integrity Management Services encompass systematic evaluation, maintenance, and risk mitigation of hydrocarbon production infrastructure using non-destructive testing, corrosion monitoring, and reliability-centered maintenance protocols to prevent unplanned shutdowns and ensure regulatory compliance. These services apply ultrasonic thickness measurement, radiographic inspection, and finite element analysis to assess pressure vessel integrity, subsea riser fatigue life, and pipeline coating degradation under operating stress. Inspection Services currently dominates revenue as regulatory mandates compel periodic asset evaluation across downstream refineries and upstream platforms. Data Analytics represents the fastest-expanding technology segment as operators deploy machine learning models to predict equipment failure modes from historical sensor streams. Remote Sensing applications in offshore environments command premium pricing due to the operational complexity of unmanned aerial and underwater vehicle deployment.
The US PHMSA enforces pipeline integrity management rules under CFR Part 195, compelling operators to conduct baseline assessments and periodic reassessments of high-consequence areas. Norway's Petroleum Safety Authority and the UK Health and Safety Executive impose facility-specific safety case requirements that mandate independent verification of barrier integrity for offshore installations. These regulatory frameworks elevate demand for third-party inspection and consulting services while creating barriers for uncertified local providers. Stakeholders must monitor the divergence between prescriptive inspection intervals and performance-based regulatory models as jurisdictions evaluate risk-based alternatives.
Market Dynamics
The transition from calendar-based inspection schedules to predictive, condition-based maintenance protocols is compressing service provider margins while elevating technical barriers to entry across upstream and downstream segments.
Growth Catalysts
- CFR Part 195 pipeline integrity mandates:PHMSA's high-consequence area reassessment requirements compel interstate operators to triple inspection frequency on aging steel infrastructure.
- Subsea robotics deployment:Autonomous underwater vehicles equipped with ultrasonic testing arrays now penetrate depths exceeding 3,000 meters in the Gulf of Mexico and North Sea basins.
- Corrosion under insulation detection:Pulsed eddy current technology addresses the dominant failure mode in offshore platform piping systems, driving replacement of radiographic methods.
Market Restraints
- Specialized inspection labor scarcity:Certified API 510/570 pressure vessel and piping inspectors command 40% wage premiums over general NDT technicians, constraining service scaling.
- Equipment import dependence:Advanced phased-array ultrasonic testing systems concentrate manufacturing in Germany and Japan, exposing operators to currency volatility and lead-time extensions.
- Prescriptive regulatory lag:Jurisdictions maintaining fixed inspection intervals prevent operators from realizing full cost savings from predictive analytics investments.
Strategic Opportunities
- Brazil pre-salt basin expansion:Petrobras's floating production storage and offloading vessel additions create demand for integrated integrity management covering 25+ new hull systems.
- Hydrogen infrastructure adaptation:Existing natural gas pipeline networks require embrittlement assessment protocols, opening adjacent service lines for established corrosion monitoring providers.
- Drone-based thermal imaging:Unmanned aerial systems penetrate flare stack and atmospheric storage tank inspection markets previously served by manned helicopter services.
Industry Challenges
- Digital twin calibration complexity:Finite element models require continuous sensor data validation against physical inspection findings, creating validation backlogs.
- Multi-standard certification burden:Service providers operating across the US, Norway, and UK must maintain parallel ASME, NORSOK, and HSE qualification schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Asset Integrity Management Services Market |
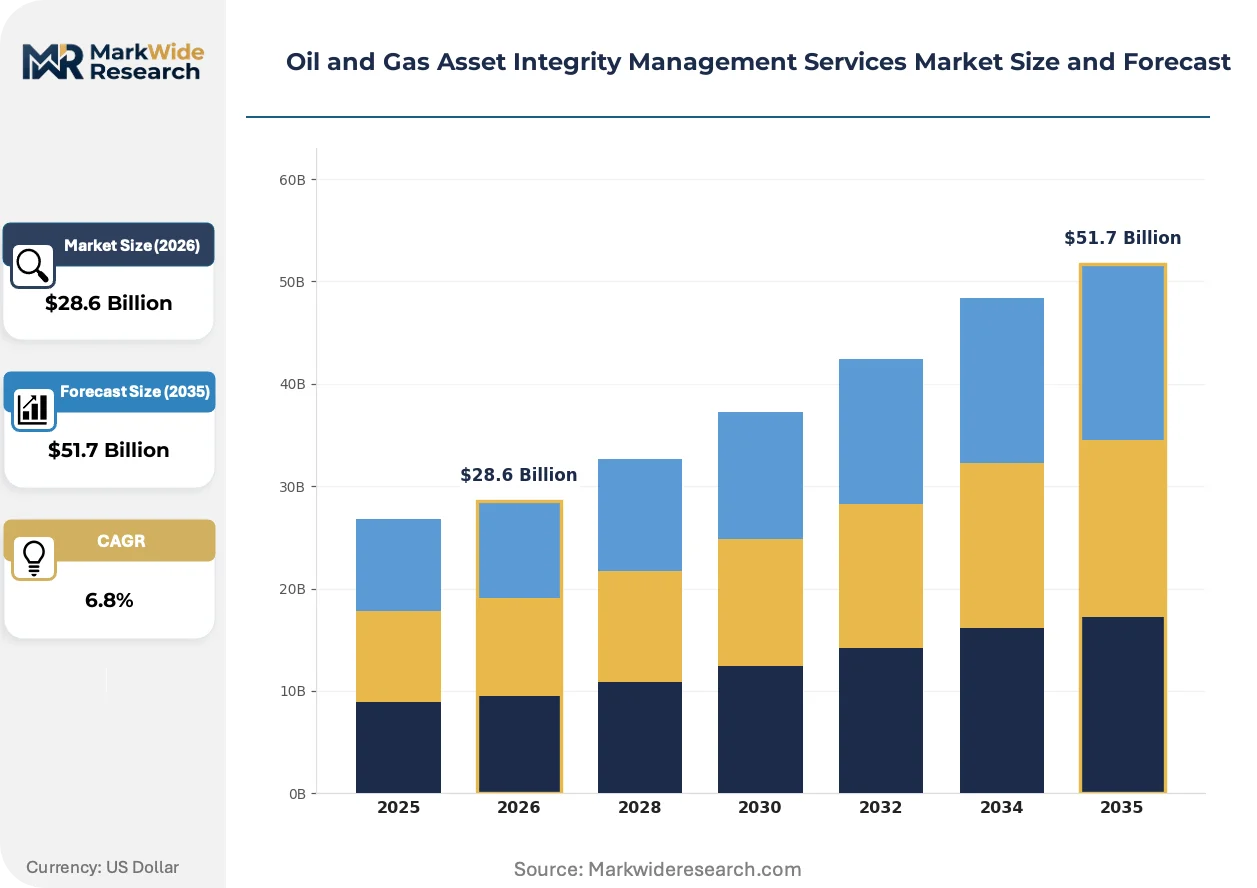
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection Services, Risk Management, Maintenance Services, Consulting Services Application: Pipeline Management, Facility Integrity, Equipment Maintenance, Environmental Safety Technology: Corrosion Monitoring, Non-Destructive Testing, Data Analytics, Remote Sensing End User: Operators, Contractors, Regulators, Asset Owners |
| Companies Covered | Aker Solutions, Fluor Corporation, Bureau Veritas, DNV AS, John Wood Group PLC, SGS Société Générale de Surveillance SA, Oceaneering International, Inc., Baker Hughes Company, TechnipFMC plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Asset Integrity Management Services Market Evolving Landscape
Edge computing architectures and machine learning inference at the sensor level are collapsing the latency between data acquisition and maintenance decision-making across distributed asset networks.
Digital twin platforms are decentralizing integrity assessment workflows by embedding physics-based simulation capabilities directly at offshore facility control systems. Major operators in the North Sea and Gulf of Mexico now deploy localized compute nodes that process vibration and pressure data without satellite uplink dependency. This architecture compresses response time from anomaly detection to work order generation from days to hours.
REACH corrosion inhibitor authorization protocols are forcing reformulation of legacy chemical treatment programs across European downstream assets. The restriction of chromate-based compounds in cooling water systems mandates adoption of molybdate and phosphonate alternatives. Refinery operators in Rotterdam and Antwerp clusters accelerate testing cycles to validate alternative chemistries under operating stress.
Buyer consolidation among supermajors is concentrating procurement authority into centralized technical standards teams that unbundle inspection services from integrated maintenance contracts. National oil companies in Saudi Arabia and the UAE now issue separate tenders for data acquisition, analysis, and remediation execution. This fragmentation pressures mid-tier service providers to specialize in discrete workflow segments rather than full-scope delivery.
Oil and Gas Asset Integrity Management Services Market Segmentation
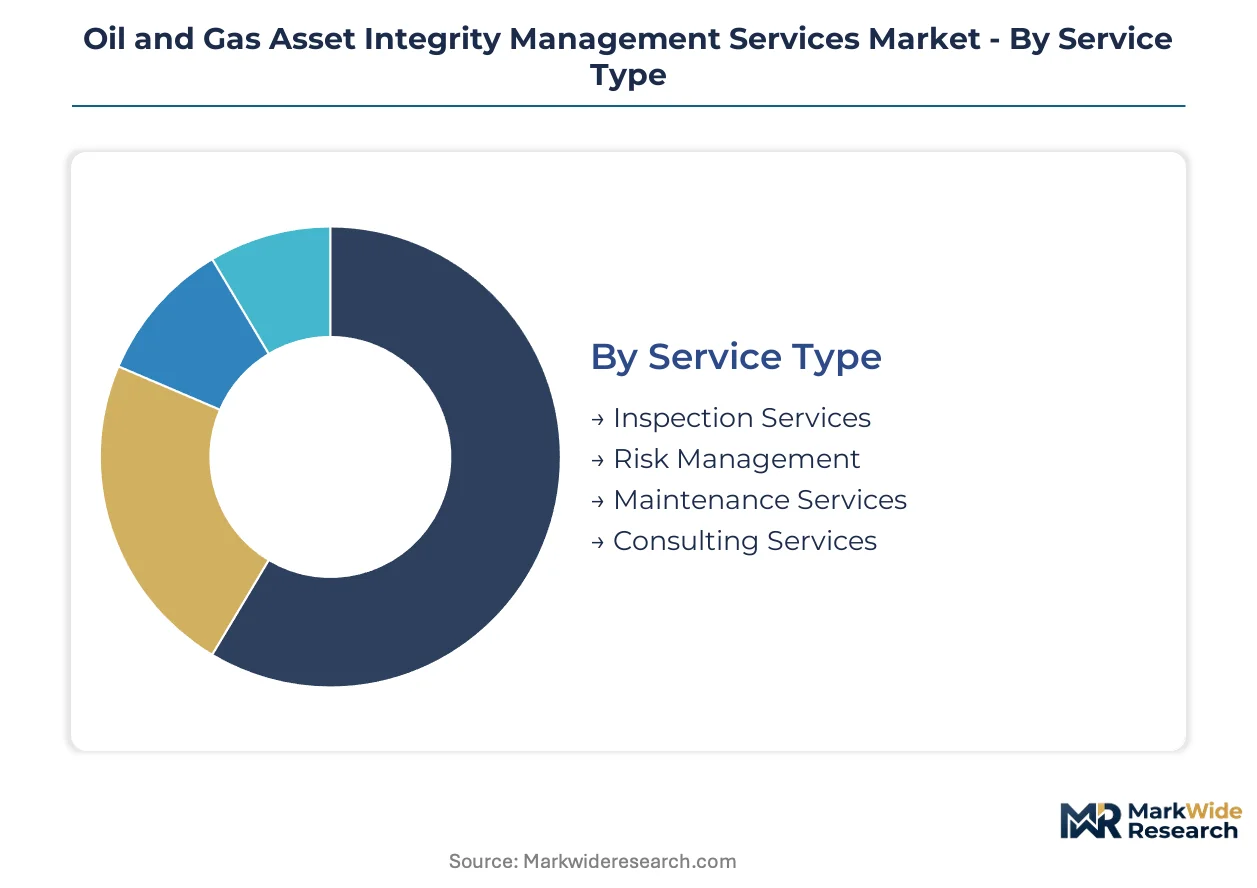
Asset integrity programs vary sharply in technical intensity and procurement structure across service lines, creating distinct margin profiles and competitive dynamics. Operators increasingly unbundle inspection, analysis, and remediation into separate contract vehicles, fragmenting vendor relationships.
Service Type:
Upgrade cycles differ materially across service categories, with predictive technology investments displacing calendar-driven inspection contracts.
- Inspection Services:Ultrasonic thickness measurement, radiographic testing, and magnetic flux leakage surveys dominate current procurement volumes. Gulf of Mexico operators drive demand as deepwater facility counts expand and PHMSA mandates intensify reassessment frequency on aging steel infrastructure.
- Data Analytics:Machine learning models processing historical sensor streams predict equipment failure modes before physical degradation manifests. North Sea operators deploy these capabilities fastest, embedding algorithms directly at offshore facility control systems to compress response latency.
- Risk Management:Quantitative risk assessment protocols evaluate probability-weighted failure consequences across pressure vessel networks.
- Maintenance Services:Reliability-centered maintenance execution spans corrective repairs through preventive replacement scheduling.
- Consulting Services:Independent verification of barrier integrity and safety case preparation supports regulatory submission requirements.
Volume placements concentrate in Inspection Services; the faster expansion belongs to Data Analytics.
Application:
Cost tier stratification separates high-complexity subsea work from standardized above-ground facility programs.
- Pipeline Management:Integrity assessment of interstate transmission lines and subsea export systems under CFR Part 195 and analogous regulatory frameworks. The US Gulf Coast corridor generates concentrated demand as operators triple inspection frequency on high-consequence area segments.
- Facility Integrity:Structural assessment of offshore platforms, floating production systems, and onshore processing complexes. Brazil's pre-salt basin expansion creates integrated integrity requirements across 25-plus new floating production storage and offloading hull systems.
- Equipment Maintenance:Rotating machinery, pressure vessels, and heat exchanger reliability programs.
- Environmental Safety:Spill prevention, emission monitoring, and containment system verification.
Procurement volumes favor Pipeline Management; Facility Integrity climbs the fastest as deepwater development accelerates.
Technology:
Application context determines technology selection, with offshore complexity commanding premium deployment modes.
- Non-Destructive Testing:Phased-array ultrasonic and pulsed eddy current methods displace legacy radiographic approaches for corrosion under insulation detection. Advanced system manufacturing concentrates in Germany and Japan, creating import dependence and currency exposure for operators.
- Remote Sensing:Autonomous underwater vehicles with ultrasonic testing arrays now penetrate depths exceeding 3,000 meters. Unmanned aerial systems capture flare stack and atmospheric storage tank thermal signatures, displacing manned helicopter services in the Gulf of Mexico and North Sea.
- Corrosion Monitoring:Electrochemical impedance spectroscopy and linear polarization resistance track inhibitor effectiveness.
- Data Analytics:Edge computing architectures process vibration and pressure data without satellite uplink dependency.
Deployment frequency peaks with Non-Destructive Testing; Remote Sensing gains share fastest through robotics maturation.
End User:
Customer type shapes contract structure, with consolidated supermajor procurement teams fragmenting integrated service packages.
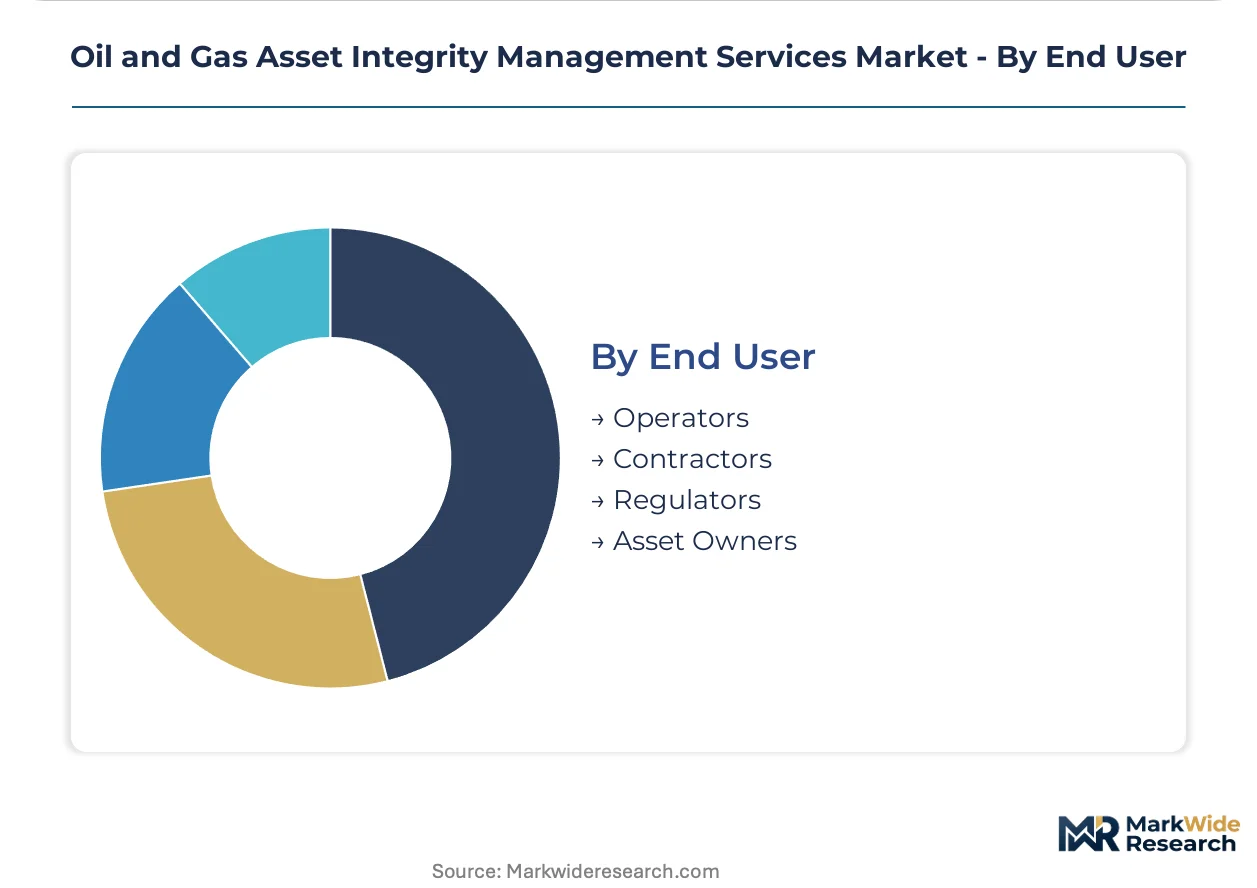
- Operators:Integrated oil companies and independent producers with direct asset ownership. Saudi Aramco and ADNOC now issue separate tenders for data acquisition, analysis, and remediation execution, unbundling previously integrated contracts.
- Asset Owners:Infrastructure funds and lease-holding entities without operational capabilities.
- Contractors:Engineering, procurement, and construction firms subcontracting specialized integrity scope.
- Regulators:Government agencies procuring independent verification and safety case assessment.
Contract concentration sits with Operators; Regulators expand procurement most quickly as performance-based frameworks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors global demand for offshore asset integrity services as Gulf of Mexico deepwater facility counts expand and PHMSA enforcement intensifies on aging pipeline infrastructure.
United States
PHMSA's CFR Part 195 mandates triple inspection frequency on high-consequence area pipeline segments. The US Gulf Coast corridor generates concentrated procurement volumes as operators reassess interstate transmission lines. Deepwater developments in the Gulf of Mexico basin drive subsea robotics deployment for riser and flowline assessment.
Norway
The Petroleum Safety Authority imposes facility-specific safety case requirements mandating independent verification of barrier integrity. Stavanger and Bergen clusters host specialized inspection contractors serving North Sea offshore platforms. Norwegian operators deploy machine learning models at facility control systems to compress anomaly response latency.
United Kingdom
The Health and Safety Executive requires quantitative risk assessment protocols for offshore installation integrity. Aberdeen's energy corridor concentrates service providers offering reliability-centered maintenance execution. UK North Sea asset aging accelerates demand for corrosion under insulation detection using pulsed eddy current methods.
Brazil
ANVISA and the national petroleum regulator enforce prescriptive inspection intervals on floating production systems. Petrobras's pre-salt basin expansion creates integrated integrity requirements across 25-plus new FPSO hull systems. Rio de Janeiro and Macaé service hubs support subsea equipment assessment for ultra-deepwater fields.
United Arab Emirates
ADNOC's centralized procurement teams unbundle inspection services into separate data acquisition and analysis tenders. Dubai and Abu Dhabi clusters attract international contractors for refinery turnaround inspection programs. The country's pipeline network expansion drives demand for automated ultrasonic testing deployment.
Oil and Gas Asset Integrity Management Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical complexity tiers, with offshore specialists commanding pricing power over onshore generalists. The vendor base concentrates around classification heritage firms, laboratory network operators, and integrated equipment-data providers. Three archetypes dominate: heritage classification societies with offshore anchor positions, certification-authority laboratories with corrosion protocol authority, and sensor-hardware integrators with proprietary analytics platforms. Competitive moves center on unbundling integrated contracts into discrete service segments and embedding edge computing architectures at facility control systems.
Within the heritage classification tier, DNV AS and Bureau Veritas exemplify premium positioning through offshore safety case verification authority. Baker Hughes occupies a position at the hardware-software integration vector, representing the sensor-to-analytics archetype. These three anchors illustrate how technical specialization and regulatory certification create defensive moats against commodity inspection pricing pressure.
| Leading Market Players |
|---|
| Aker Solutions |
| Fluor Corporation |
| Bureau Veritas |
| DNV AS |
| John Wood Group PLC |
| SGS Société Générale de Surveillance SA |
| Oceaneering International, Inc. |
| Baker Hughes Company |
| TechnipFMC plc |
| Others |
Value Network & Pricing Analysis
Steel price indices for high-grade pressure vessel alloys cascade through inspection equipment manufacturing into three-tier pricing structures across premium, standard, and economy service levels. PHMSA compliance mandates amplify cost pass-through to operators in high-consequence area segments.
Pricing Analysis
Outcome-linked contracts anchoring pricing to pipeline uptime guarantees dominate premium offshore engagements. Certification grade under API 510/570 protocols and NORSOK qualification status create sharp price differentiation between heritage classification societies and commodity inspection shops. Cost compression in standard-tier radiographic services is intensifying because unbundled procurement allows operators to pit regional contractors against one another. National oil companies with centralized technical standards teams exhibit lowest price sensitivity; independent shale operators drive hardest bargain on per-mile pipeline assessment rates.
Supply Chain Analysis
Brazil's local-content mandates for pre-salt basin operations reshape sourcing patterns for subsea robotics and pressure vessel inspection systems. Advanced phased-array ultrasonic testing equipment concentrates manufacturing in Germany and Japan; corrosion inhibitor feedstock draws from Belgian and Dutch chemical clusters. Single-source vulnerability runs through Japanese sensor array suppliers exposed to currency volatility. Distribution runs through Stavanger, Houston, and Rio de Janeiro technical service hubs that coordinate multinational deployment teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHMSA's CFR Part 195 integrity mandates erect a cost-of-compliance barrier that filters out uncertified local providers and entrenches accredited incumbents with established regulatory relationships.
For Market Incumbents: Hedge against predictive analytics commoditization by embedding edge computing architectures directly at client facility control systems. Deepen API 570 inspector certification pipelines to defend against specialized labor scarcity. Acquire distressed corrosion monitoring laboratories in the UK North Sea corridor to consolidate barrier verification authority.
For New Entrants and Emerging Players: Engineering, procurement, and construction contractors represent the most accessible channel partner type for unbundled data acquisition contracts. Drone-based thermal imaging for flare stack inspection offers the most penetrable white-space target, displacing manned helicopter incumbents. Lead with pay-per-inspection pricing to bypass capital-intensive subscription barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-hardware integrators with proprietary analytics platforms in the Gulf of Mexico basin. Long-term viability hinges on regulatory certification moats rather than equipment depreciation cycles. Watch for jurisdictions shifting from prescriptive to performance-based integrity frameworks as the inflection signal for analytics-heavy target premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Compresses anomaly-to-work-order latency from satellite-dependent days to facility-local hours. |
| API 570 Inspector Pipeline Expansion | Addresses 40% wage premiums constraining service scaling across Gulf of Mexico operators. |
| Drone Thermal Imaging Capability | Penetrates flare stack inspection markets previously served by manned helicopter services. |
| Hydrogen Pipeline Embrittlement Protocols | Opens adjacent service lines for corrosion monitoring providers adapting natural gas infrastructure. |
| Multi-Jurisdiction Certification Parallel Maintenance | Enables seamless cross-border contracting across ASME, NORSOK, and HSE qualification schemes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with integrity management directors, PHMSA compliance officers, subsea robotics procurement leads, and refinery turnaround planners combined with PHMSA enforcement databases, Bureau of Safety and Environmental Enforcement incident reports, Norwegian Petroleum Directorate production statistics, and API certification rosters. Bottom-up service provider revenue aggregation triangulated against top-down operator expenditure surveys.
Granularity-level modeling disaggregated projections across service type, application context, deployment technology, and end-user procurement structure. CAGRs derived from regression against historical inspection frequency mandates and deepwater facility count trajectories. Forecast inputs incorporated subsea robotics penetration curves and machine learning adoption rates at North Sea control systems.
Several conditions sit outside the modeled scope, including abrupt regulatory regime shifts, commodity price collapse-triggered capex freezes, and breakthrough non-destructive testing modalities displacing ultrasonic arrays. Forecasts reflect documented assumptions regarding inspection interval enforcement continuity and labor certification pipeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Frac Services Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Drilling Fluids Market