
 Cryptocurrency Hardware Wallet Market | 2026-2036
Cryptocurrency Hardware Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptocurrency Hardware Wallet Market Analysis
Institutional treasury departments are rotating toward self-custody hardware solutions as exchange counterparty risks reshape procurement priorities. Ledger SAS leverages its secure-element chip supply chain to dominate European enterprise deployments. SatoshiLabs s.r.o. sustains open-source firmware credibility that appeals to privacy-focused developers. Tangem AG differentiates through card-form-factor NFC wallets that occupy retail banking partnership channels in Asia.
A cryptocurrency hardware wallet is a dedicated physical device that generates and stores private keys in an isolated secure element or trusted execution environment, operating without persistent internet connectivity to eliminate remote attack surfaces. The primary purpose is to sign blockchain transactions while keeping cryptographic material physically segregated from internet-exposed hosts. USB wallet and multi-currency wallet segments lead current volume, with Bluetooth connectivity wallets recording the fastest expansion as mobile-first traders reject cable-tethered workflows. Pin protection and biometric access layers now define margin pools, as vendors compete on certification depth rather than token support counts alone.
SEC custody rule proposals and the EU MiCA framework are forcing regulated entities toward certified hardware segregation, while Singapore's MAS licensing conditions mandate cold-storage ratios for digital payment token service providers. ISO 27001 and Common Criteria EAL5+ certifications increasingly gate institutional procurement, filtering vendors without audited secure-element architectures. Stakeholders must monitor whether emerging quantum-resistant signature standards trigger hardware replacement cycles before current device lifecycles expire.
Market Dynamics
Regulatory mandates for certified cold-storage segregation are compressing procurement timelines across institutional custody departments, forcing asset managers to replace exchange-hosted hot wallets with hardware-backed key management before compliance deadlines.
Growth Catalysts
- MiCA framework obligations:European licensed custodians must demonstrate air-gapped key management to national financial regulators, accelerating enterprise hardware deployments.
- Institutional treasury rotation:Asset managers and crypto-native funds are expanding cold-storage procurement faster than retail collectors as counterparty risk reshapes priorities.
- Singapore MAS licensing:The central bank mandates cold-storage ratios for digital payment token service providers, creating structural demand for certified hardware.
Market Restraints
- Secure-element supply concentration:Fabrication capacity for EAL5+ certified chips concentrates among a handful of semiconductor foundries, creating procurement bottlenecks.
- ISO 27001 audit timelines:Certification cycles for institutional procurement gates can extend 12-18 months, delaying vendor qualification.
- Mobile wallet substitution:Software-based multi-signature solutions with hardware security module integration threaten standalone device categories for sub-institutional holdings.
Strategic Opportunities
- United Arab Emirates licensing:Dubai's VARA framework creates demand for air-gapped custody among virtual asset service providers seeking full market licenses.
- Biometric-NFC convergence:Fingerprint-authenticated card-form-factor wallets open retail banking partnership channels in Asian markets.
- Quantum-resistant signature standards:NIST post-quantum cryptography finalists will trigger hardware replacement cycles before current device lifecycles expire.
Industry Challenges
- Firmware security engineering talent:Vendors compete for cryptographers capable of formal verification for secure-element operating systems.
- Common Criteria EAL5+ certification costs:Laboratory evaluation fees and timeline uncertainty strain mid-cap vendor R&D budgets.
- Legacy exchange integration:Institutional clients demand seamless API connectivity with existing custody workflows, complicating air-gapped architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptocurrency Hardware Wallet Market |
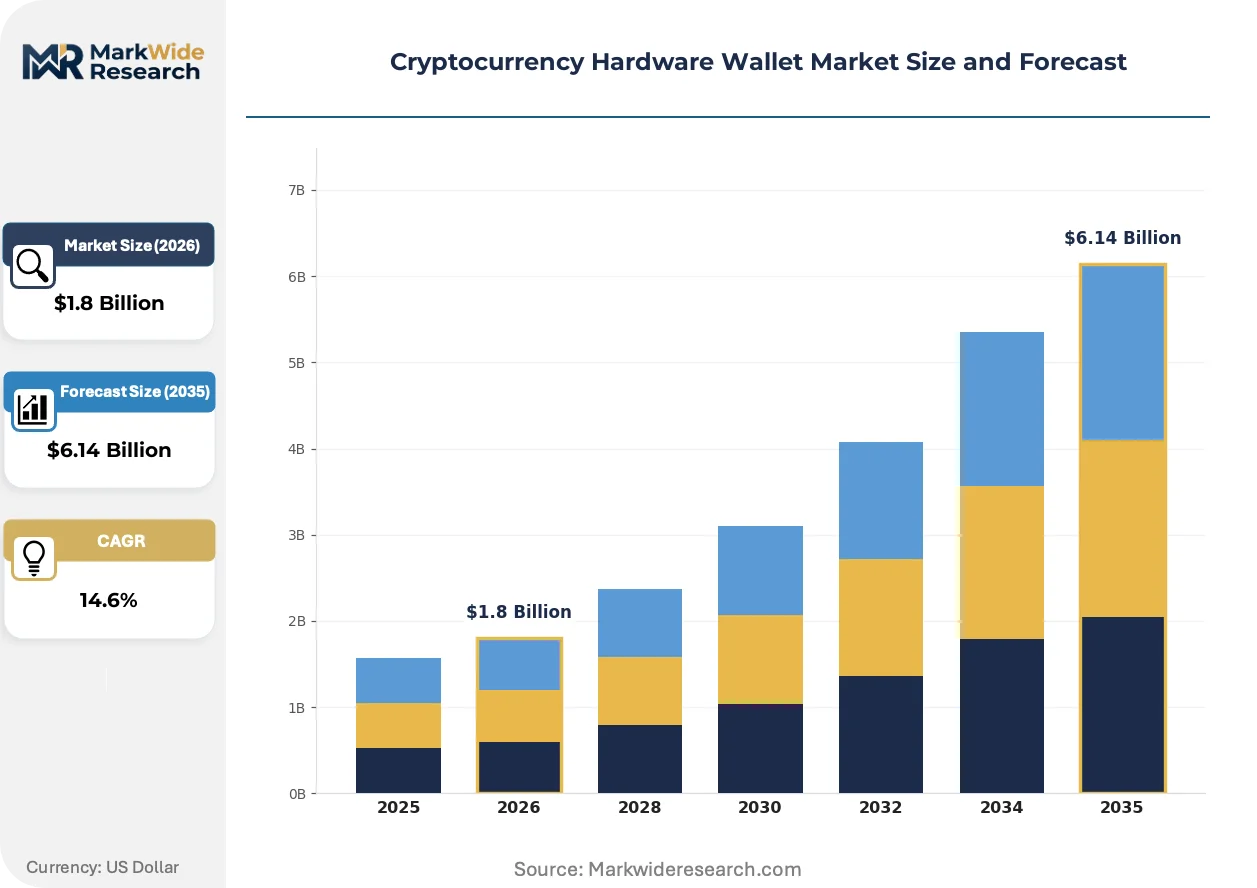
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Wallet, Mobile Wallet, Desktop Wallet, Multi-Currency Wallet Connectivity: Bluetooth, USB-C, NFC, Wi-Fi End User: Retail Investors, Cryptocurrency Traders, Institutions, Miners Security Features: Pin Protection, Biometric Access, Encryption, Recovery Seed |
| Companies Covered | Ledger SAS, SatoshiLabs s.r.o., ARCHOS S.A., ELLIPAL Ltd., CoolBitX Technology Ltd., Coinkite Inc., ShapeShift AG, Tangem AG, SafePal Technology Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptocurrency Hardware Wallet Market Emerging Trajectories
Hardware wallet architecture is splitting between ultra-secure institutional appliances and consumer-friendly mobile peripherals, with connectivity protocols and certification depth becoming the primary axes of differentiation rather than token support breadth.
Secure-element technology is bifurcating the market into EAL6+ certified modules for regulated custodians and consumer-grade trusted execution environments for retail self-custody. Sovereign wealth funds and asset servicers in Germany and Singapore are specifying the higher certification tier for treasury operations. This split is compressing margin pools for vendors caught between tiers without clear positioning.
EU MiCA framework obligations are forcing virtual asset service providers to segregate client assets in certified hardware by the end of 2024. The regulation requires demonstrable air-gapped key generation and transaction signing. Custody departments at European banks are responding by pre-qualifying vendors with existing EAL5+ Common Criteria certifications rather than waiting for MiCA-specific guidance.
Mobile-first traders are rejecting cable-tethered USB workflows in favor of Bluetooth and NFC connectivity for on-the-go signing. This behavioral shift is most visible in Asian retail markets where exchange-integrated wallet apps dominate daily transaction volume. Hardware vendors are responding with companion devices that pair with smartphones without exposing private keys to the host operating system.
Cryptocurrency Hardware Wallet Market Segmentation
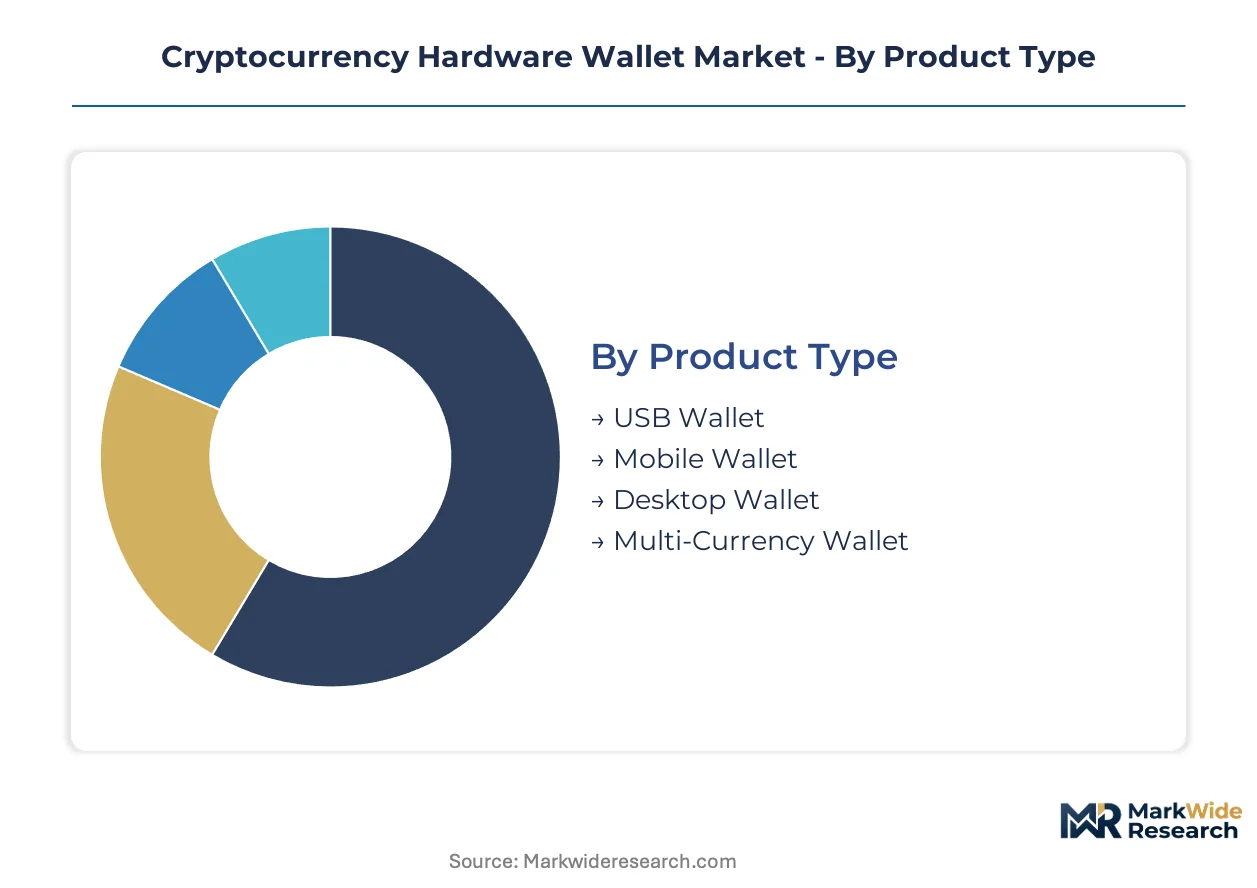
Hardware wallet segmentation reveals how procurement priorities diverge between institutional compliance mandates and retail convenience preferences. Certification depth and connectivity protocols now drive vendor positioning more than token support breadth.
Product Type:
Margins pool most heavily in segments where secure-element certification costs create procurement barriers for mid-tier competitors.
- USB Wallet:Cable-tethered devices with isolated secure elements dominate institutional deployments in Germany and Singapore where air-gapped signing satisfies regulatory mandates. Treasury departments at asset managers specify USB workflows for high-value transfers despite slower transaction speeds.
- Multi-Currency Wallet:Native support for heterogeneous blockchain architectures appeals to cryptocurrency traders managing diversified portfolios across Ethereum, Solana, and Bitcoin ecosystems. Demand concentrates among retail collectors seeking single-device consolidation rather than multiple single-chain appliances.
- Mobile Wallet:Smartphone-integrated applications with trusted execution environments serve on-the-go signing workflows. NFC and Bluetooth pairings dominate Asian retail banking partnerships.
- Desktop Wallet:PC-tethered solutions with dedicated hardware interfaces persist among privacy-focused developers. Open-source firmware credibility sustains niche procurement.
USB Wallet holds installed capacity. Multi-Currency Wallet is rotating up the share rankings.
Connectivity:
Volume flows toward protocols that eliminate cable friction without sacrificing air-gapped isolation.
- Bluetooth:Wireless pairing with smartphones enables mobile-first traders to sign transactions without exposing private keys to host operating systems. Singapore's MAS-licensed custodians increasingly specify Bluetooth companion devices for operational staff requiring portable access.
- NFC:Near-field communication supports card-form-factor wallets that slip into physical banking card slots. Tangem AG leverages this protocol for retail banking distribution channels across Asian markets.
- USB-C:Universal connector standard maintains backward compatibility with legacy institutional infrastructure. Procurement departments favor this protocol for standardization across device fleets.
- Wi-Fi:Persistent connectivity remains rare due to attack surface expansion concerns. Experimental deployments appear only in multi-signature enterprise configurations with hardware security module integration.
USB-C maintains legacy share dominance. Bluetooth is climbing the fastest as mobile workflows displace cable-tethered alternatives.
End User:
Procurement scale and certification requirements fragment the customer base into distinct service tiers.
- Institutions:Asset managers and crypto-native funds mandate EAL5+ Common Criteria certifications and ISO 27001 audit trails. MiCA framework deadlines compress European procurement timelines.
- Cryptocurrency Traders:High-frequency participants prioritize transaction signing speed and multi-chain support. Bluetooth and NFC connectivity dominate this segment's feature requirements.
- Retail Investors:Self-custody collectors balance security against convenience and price accessibility. Card-form-factor wallets with biometric layers gain traction.
- Miners:Block reward recipients require cold-storage solutions for accumulated holdings. Less frequent transaction needs favor air-gapped USB workflows over connected alternatives.
Institutions command premium pricing tiers. Cryptocurrency Traders are expanding fastest as exchange counterparty risks reshape self-custody priorities.
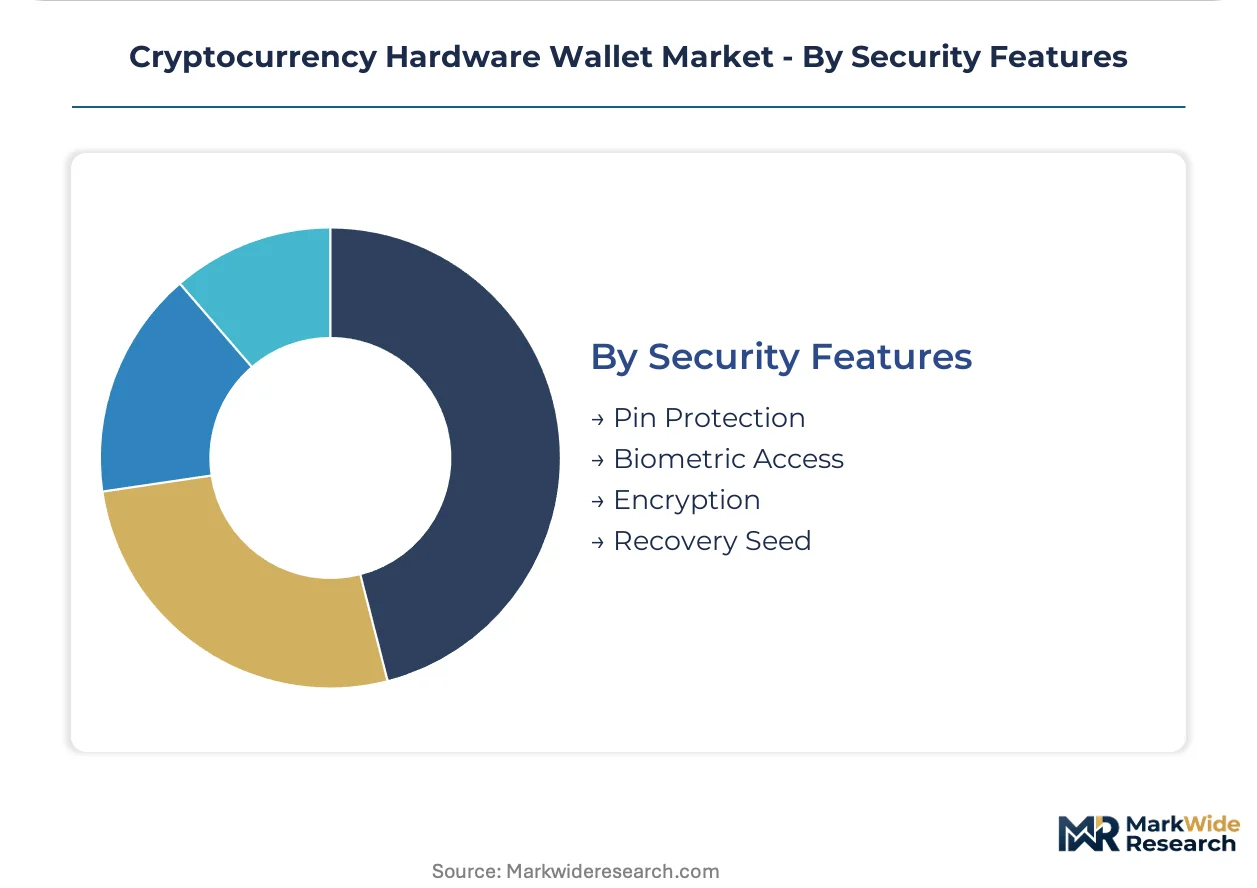
Security Features:
Certification depth and biometric integration now differentiate margin pools more than encryption algorithm variety.
- Biometric Access:Fingerprint authentication layers eliminate PIN memorization failure modes while maintaining physical possession requirements. Asian retail banking partnerships increasingly specify this feature for consumer-facing deployments.
- Pin Protection:Numeric entry remains the baseline authentication standard across all price tiers. Brute-force protection through secure-element rate limiting distinguishes certified implementations.
- Encryption:AES-256 and comparable standards are table stakes rather than differentiators. Formal verification of cryptographic implementations separates enterprise-grade from consumer offerings.
- Recovery Seed:BIP-39 mnemonic backup procedures create user experience friction points. Shamir secret sharing schemes emerge for institutional multi-party custody configurations.
Pin Protection retains universal deployment. Biometric Access is gaining share fastest as vendors compete on convenience without sacrificing certification depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-London financial corridor anchors European institutional custody flows, while Singapore's Changi datacenter cluster underwrites Asia-Pacific digital asset infrastructure. Dubai's DMCC crypto hub and Seoul's blockchain district complete the geographic foundation.
Germany
BaFin-licensed crypto custodians in Frankfurt and Berlin drive enterprise hardware procurement for institutional treasury operations. The German Banking Act amendments mandate qualified wallet segregation for virtual asset service providers. Munich's fintech cluster hosts secure-element testing laboratories serving EAL5+ certification workflows.
Singapore
MAS-licensed digital payment token service providers concentrate procurement for cold-storage ratios in the Marina Bay financial district. Singapore's Payment Services Act enforcement creates structural demand for certified air-gapped key management. The island's semiconductor packaging facilities supply trusted execution environment components to regional wallet manufacturers.
United Arab Emirates
Dubai's VARA framework compels virtual asset service providers toward certified custody hardware for full market licensing. The Abu Dhabi Global Market crypto regulations align with international standards for institutional key segregation. DMCC's crypto center hosts custody infrastructure deployments serving Gulf sovereign wealth funds.
United States
SEC custody rule deliberations reshape procurement priorities for asset managers in New York and Chicago. State-level money transmitter licenses in Wyoming and Texas create regulatory arbitrage for crypto-native funds seeking favorable custody frameworks. Silicon Valley secure-element design houses supply chip architectures to domestic wallet vendors.
Switzerland
FINMA banking license requirements for crypto custodians in Zug and Zurich mandate hardware-backed key segregation. The Swiss blockchain ordinance creates compliance templates adopted across European institutional markets. Geneva's private banking cluster integrates hardware wallets into multi-generational wealth structuring for crypto holdings.
Cryptocurrency Hardware Wallet Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and supply chain control, creating a tiered structure where Common Criteria EAL5+ credentials filter market access. The vendor base separates into secure-element chip architects, open-source firmware specialists, and retail form-factor innovators. Three archetypes dominate: European certification-heavy incumbents, Asian mobile-first peripherals makers, and privacy-focused open-source developers. Strategic moves concentrate on semiconductor supply agreements and banking partnership channels rather than direct product rivalry.
Within the European secure-element tier, Ledger SAS and Tangem AG exemplify divergent positioning strategies. Ledger SAS anchors institutional deployment through its French secure-element supply chain relationships. Tangem AG occupies the card-form-factor NFC niche through Asian retail banking distribution. SatoshiLabs s.r.o. represents the open-source firmware archetype appealing to privacy-conscious developers. These three patterns—certification dominance, retail convenience, and transparency credibility—structure competitive differentiation.
| Leading Market Players |
|---|
| Ledger SAS |
| SatoshiLabs s.r.o. |
| ARCHOS S.A. |
| ELLIPAL Ltd. |
| CoolBitX Technology Ltd. |
| Coinkite Inc. |
| ShapeShift AG |
| Tangem AG |
| SafePal Technology Ltd. |
| Others |
Supply Flow & Price Mechanics
EAL6+ certified secure-element modules replacing EAL5+ consumer-grade chips in German and Singaporean institutional deployments simultaneously concentrates supply geography around French and Taiwanese semiconductor foundries and compresses pricing economics for mid-tier vendors caught between certification tiers without clear positioning.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise certification depth, retail convenience features, and economy-grade basic security. Price differentiation hinges on Common Criteria EAL5+ or EAL6+ laboratory evaluation costs and ISO 27001 audit trail completeness. Cost compression in the mid-tier is intensifying because MiCA framework deadlines force rapid vendor pre-qualification without margin recovery time. Retail investors exhibit highest price sensitivity while institutions accept premium tiers for regulatory defensibility.
Supply Chain Analysis
Inventory lead-times for EAL5+ certified secure elements extend 16-24 weeks due to fabrication queue concentration. Supply concentrates in France, Taiwan, and South Korea for secure-element wafer production. Component dependencies include ARM Cortex-M secure cores, tamper-resistant packaging substrates, and NFC antenna arrays. Single-source vulnerability pervades EAL6+ evaluation laboratory capacity. Distribution runs through direct enterprise procurement teams for institutional tiers and retail banking partnerships for consumer card-form-factor wallets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as regulatory mandates splinter procurement requirements across certification tiers, connectivity protocols, and geographic compliance frameworks.
For Market Incumbents: Fortify secure-element supply agreements with French and Taiwanese foundries before fabrication queue congestion worsens. Deepen backward integration into firmware formal verification capabilities to offset cryptographer talent scarcity. MiCA framework acceleration threatens margin recovery timelines for vendors without pre-qualified EAL5+ certifications. For New Entrants and Emerging Players: Common Criteria evaluation fast-tracks through Singapore MAS-recognized laboratories open regulatory arbitrage for virtual asset service providers seeking rapid licensing compliance. White-space concentrates in biometric-NFC card wallets for Asian retail banking channels and quantum-resistant signature hardware pre-positioning. Go-to-market leverage rests on white-label partnerships with licensed custodians rather than direct consumer brand building. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors vendors with existing EAL5+ certifications and established semiconductor supply relationships. Long-term viability across the next decade hinges on post-quantum cryptography readiness and banking channel integration depth. Acquisition targets with Shamir secret sharing firmware implementations and VARA framework pre-qualification signal inflection capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Supply Agreement | French and Taiwanese foundry relationships anchor EAL5+ certification pipelines for MiCA-compliant deployments. |
| Biometric-NFC Product Launch | Fingerprint-authenticated card wallets unlock retail banking distribution in Singapore and UAE markets. |
| Post-Quantum Cryptography R&D | NIST finalist algorithm implementations trigger hardware replacement cycles before device obsolescence. |
| MAS Licensing Partnership | Singapore cold-storage ratio mandates create structural demand for certified air-gapped key management. |
| Firmware Formal Verification Investment | Mathematical proof of secure-element operating systems differentiates enterprise procurement tiers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hardware wallet procurement officers at asset managers, regulatory compliance leads at virtual asset service providers, secure-element chip architects, and firmware security engineers. Secondary validation drew from MiCA framework implementation guidance, MAS licensing condition documents, Common Criteria certification registers, and semiconductor trade flow data. Bottom-up vendor shipment estimates triangulated against top-down institutional custody asset growth projections.
Across the analysis window, forecasts modeled connectivity protocol adoption curves, certification tier migration rates, and end-user segment procurement scale. Segmentation dimensions included product architecture, security certification depth, geographic regulatory cluster, and institutional versus retail buyer archetype. CAGRs derived from fitted adoption S-curves anchored to compliance deadline impacts and secure-element supply elasticity.
Decision-makers should treat outputs as directional under assumptions of sustained MiCA enforcement timelines and stable semiconductor fabrication capacity; material deviation in regulatory implementation pace or secure-element supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market