
 Global Cryptocurrency Market | 2026-2036
Global Cryptocurrency Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryptocurrency Market Analysis
Institutional treasury desks is rotating toward direct cryptocurrency custody and spot allocation, displacing earlier retail-driven volume patterns. BlackRock sustains dominance through its Bitcoin ETF infrastructure and institutional distribution channels. Coinbase Global anchors the regulated exchange landscape with deep compliance investments across multiple jurisdictions. MicroStrategy differentiates through its leveraged Bitcoin treasury strategy, converting operating cash flows into long-dated digital asset positions.
Cryptocurrency denotes cryptographically secured digital tokens operating on distributed ledger networks, with Bitcoin utilizing SHA-256 proof-of-work consensus and Ethereum employing proof-of-stake validation with smart contract programmability, functioning primarily as programmable value transfer mechanisms and decentralized settlement layers. The type dimension shows Bitcoin commanding the largest capital base while Ethereum captures developer activity through smart contract programmability. Within application segments, trading generates the highest transaction velocity though institutional investment flows are shifting toward custody and staking services. The deployment architecture reveals public blockchain networks securing the majority of settled value, while hybrid configurations gain traction among enterprise consortia seeking selective transparency.
The SEC enforces securities classification tests that determine which tokens fall under registration requirements, while the EU MiCA framework establishes uniform licensing standards for crypto-asset service providers across member states. Japan's FSA maintains granular exchange auditing protocols that shape product availability for retail participants. Stakeholders must monitor how jurisdictional arbitrage between regulatory regimes influences capital formation venues and operational licensing costs.
Market Dynamics
Institutional capital rotation into spot Bitcoin custody is compressing retail-driven volume patterns and rewiring exchange revenue models toward custody fees and staking yields.
Growth Catalysts
- EU MiCA Licensing:The Markets in Crypto-Assets framework establishes uniform authorization standards across member states, reducing cross-border operational friction for compliant service providers.
- Proof-of-Stake Validation:Ethereum's consensus transition enables institutional staking participation with yield-bearing structures that attract treasury allocation from family offices.
- Singapore:Regulatory clarity from the Monetary Authority of Singapore draws licensed exchange operators and concentrated family office capital seeking compliant jurisdictional bases.
Market Restraints
- Energy Input Volatility:Bitcoin mining operations face margin compression from fluctuating electricity costs and carbon pricing mechanisms in jurisdictions with aggressive decarbonization mandates.
- Securities Classification Uncertainty:The SEC's enforcement of the Howey test against token issuers creates compliance overhead and delisting risk for assets deemed unregistered securities.
- Concentrated Hashrate Geography:Mining capacity clusters in specific jurisdictions with subsidized energy, creating geopolitical exposure to export controls or operational shutdowns.
Strategic Opportunities
- Tokenized Treasury Instruments:Convergence of stablecoin infrastructure with yield-bearing government securities creates new on-chain collateral categories for DeFi protocols.
- India:Underpenetrated retail access combined with RBI's central bank digital currency pilot presents first-mover positioning for compliant fiat-to-crypto onramps.
- Institutional Custody Services:Cold storage and insurance-backed custody solutions address fiduciary requirements from pension funds and endowments entering direct allocation.
Industry Challenges
- Smart Contract Auditing Talent:Scarcity of qualified security researchers capable of formal verification creates vulnerability exposure for protocols deploying unaudited code.
- Cross-Chain Interoperability Integration:Fragmented liquidity across Layer-1 and Layer-2 networks forces complex bridging architectures that introduce custody risk and latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryptocurrency Market |
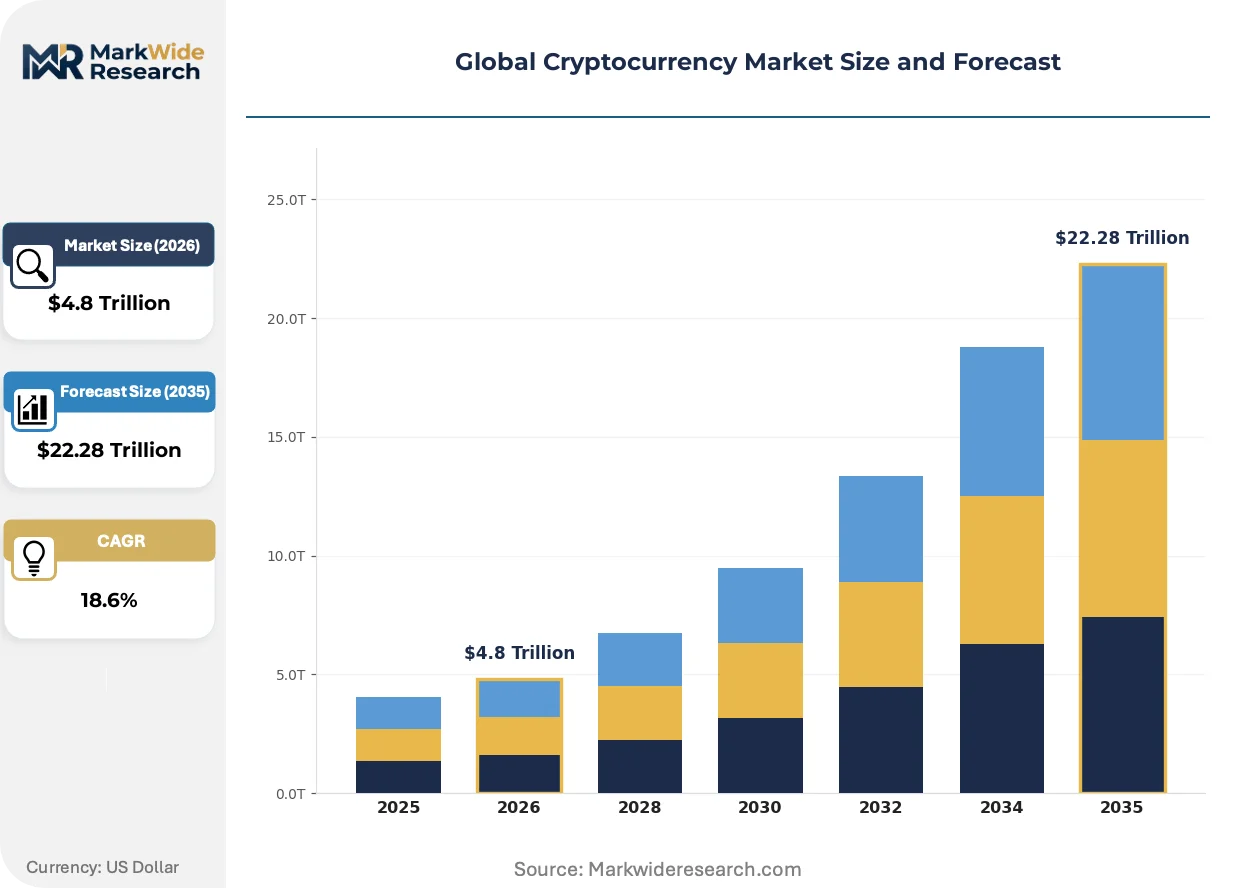
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $22.28 Trillion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bitcoin, Ethereum, Ripple, Litecoin Application: Payments, Trading, Investment, Remittances End User: Retail Investors, Institutional Investors, Miners, Exchanges Deployment: Public Blockchain, Private Blockchain, Hybrid Blockchain, Centralized Solutions |
| Companies Covered | Consensys, Core Scientific, Coinbase Global, BlackRock, BitGo, Binance, MicroStrategy, Tether, Kraken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryptocurrency Market Emerging Trajectories
Three vectors are restructuring competitive positioning: consensus mechanism evolution, jurisdictional regulatory arbitrage, and institutional-grade infrastructure maturation.
Zero-knowledge proof systems are displacing traditional audit and compliance workflows by enabling private transaction validation without revealing underlying data. Institutional custodians in Switzerland and Singapore are integrating zk-SNARK verification into their attestation processes. This compression of trust overhead is reducing operational costs for cross-border settlement while maintaining regulatory auditability.
The EU's Markets in Crypto-Assets regulation is mandating segregated custody and reserve transparency for stablecoin issuers operating across member states. Issuers must maintain 1:1 liquid reserves with daily publication requirements. Circle and compliant European banks are restructuring treasury operations to meet these standards ahead of the 2024 implementation deadline.
Family office direct custody is replacing fund-of-funds exposure as the dominant institutional entry pattern. Single-family offices in Dubai and Geneva are hiring dedicated digital asset officers and deploying hardware security modules for self-custody. This behavioral shift is visible most acutely in Swiss private banking jurisdictions where traditional wealth managers are losing allocation mandates to specialized custody boutiques.
Global Cryptocurrency Market Segmentation
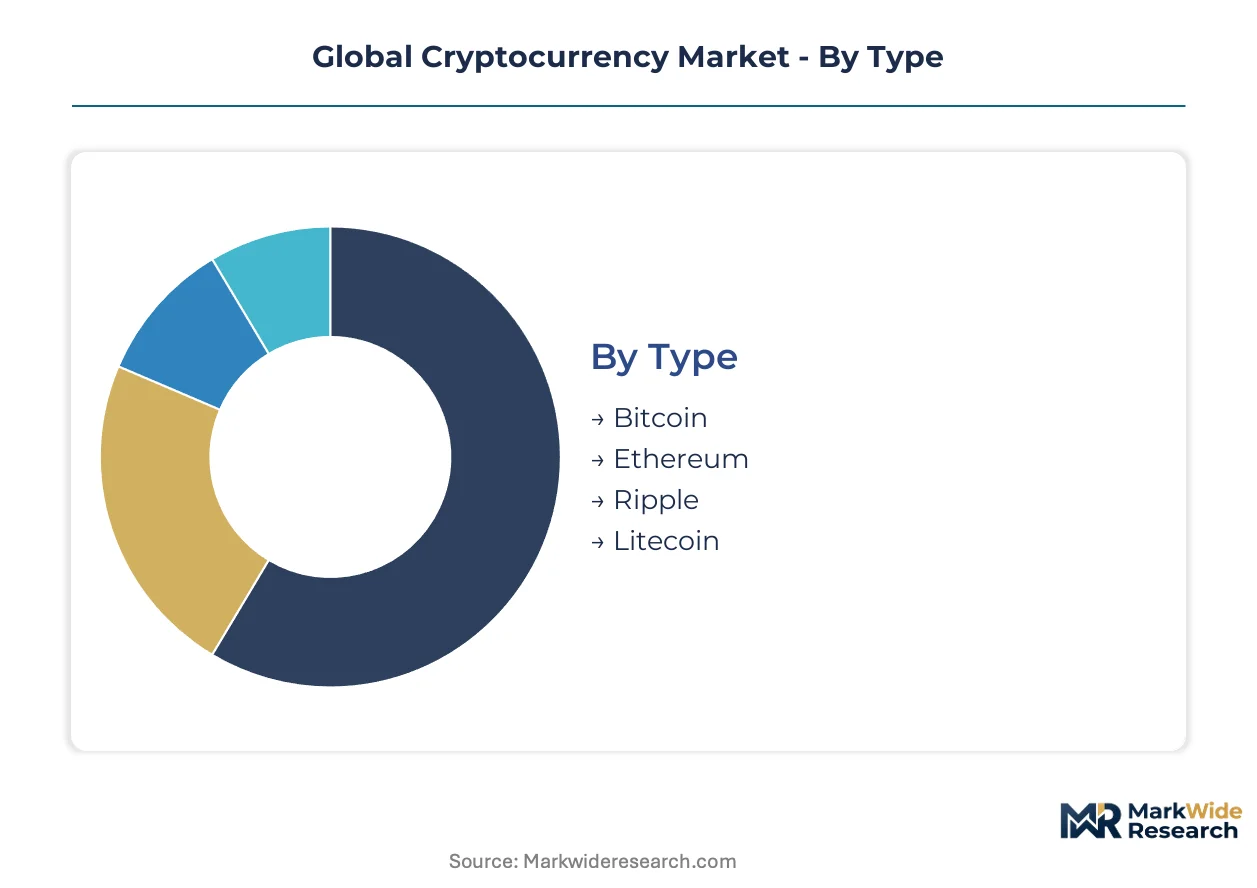
Segmentation in cryptocurrency markets reveals how capital formation, transaction velocity, and infrastructure requirements diverge across token architectures and user profiles. These distinctions determine custody solutions, regulatory exposure, and revenue model viability for service providers.
Type:
Bitcoin and Ethereum dominate cross-border capital flows and institutional treasury allocations, while Ripple and Litecoin concentrate in payment corridors and retail exchange listings respectively.
- Bitcoin:SHA-256 proof-of-work consensus secures the network with energy-intensive mining operations. Family offices in Singapore and Switzerland are directing operating cash flows into cold storage custody, displacing earlier fund-of-funds exposure patterns.
- Ethereum:Proof-of-stake validation enables programmable smart contracts with staking yield mechanisms. Developer activity clusters around decentralized finance protocols in the EU and UAE, where MiCA licensing provides regulatory clarity for institutional participation.
- Ripple:Consensus ledger optimized for correspondent banking settlements with rapid finality. Cross-border remittance demand concentrates in Southeast Asian corridors from licensed operators in Singapore.
- Litecoin:Scrypt-based hashing delivers faster block confirmation than Bitcoin. Retail exchange volume in Japan and South Korea sustains liquidity for payment-oriented use cases.
Bitcoin commands the established base. The steepest expansion runs through Ethereum.
Application:
Trading generates the highest transaction velocity, though staking yields and custody fees are rewiring exchange revenue models as institutional participation deepens.
- Payments:Merchant acceptance and peer-to-peer settlement utilize Lightning Network channels and Layer-2 rollups. Regulatory clarity in El Salvador and the Central African Republic anchors governmental adoption experiments.
- Trading:Spot and derivatives markets concentrate liquidity on regulated exchanges in the US, EU, and Singapore. MiCA licensing requirements are compressing unregulated venue market share ahead of full implementation.
- Investment:Treasury allocation and long-dated holding patterns dominate institutional entry. Pension funds in Switzerland and endowments in Canada are mandating qualified custody and insurance-backed storage.
- Remittances:Cross-border worker transfers leverage stablecoin rails and low-fee Layer-1 networks. Corridors from UAE to India and Philippines show concentrated volume through licensed exchange onramps.
Trading generates the dominant transaction volume. Investment allocation is climbing the fastest as fiduciary standards mature.
End User:
Institutional investors and exchanges drive infrastructure investment, while retail participation patterns shift from speculation toward self-custody and staking participation.
- Retail Investors:Individual holders utilizing exchange wallets, mobile applications, and hardware security modules. Japanese FSA auditing protocols shape product availability and leverage limits for this cohort.
- Institutional Investors:Family offices, hedge funds, and corporate treasuries with fiduciary custody requirements. Direct allocation in Dubai and Geneva is displacing traditional wealth manager mandates.
- Miners:Proof-of-work validation operations securing Bitcoin and similar networks. Energy cost arbitrage concentrates hashrate in jurisdictions with subsidized electricity or stranded renewable resources.
- Exchanges:Licensed trading venues and custody providers bridging fiat and digital asset markets. Singapore MAS licensing draws concentrated operator establishment and family office capital deployment.
Exchanges anchor the infrastructure layer. Institutional investors are expanding most quickly as compliance frameworks crystallize.
Deployment:
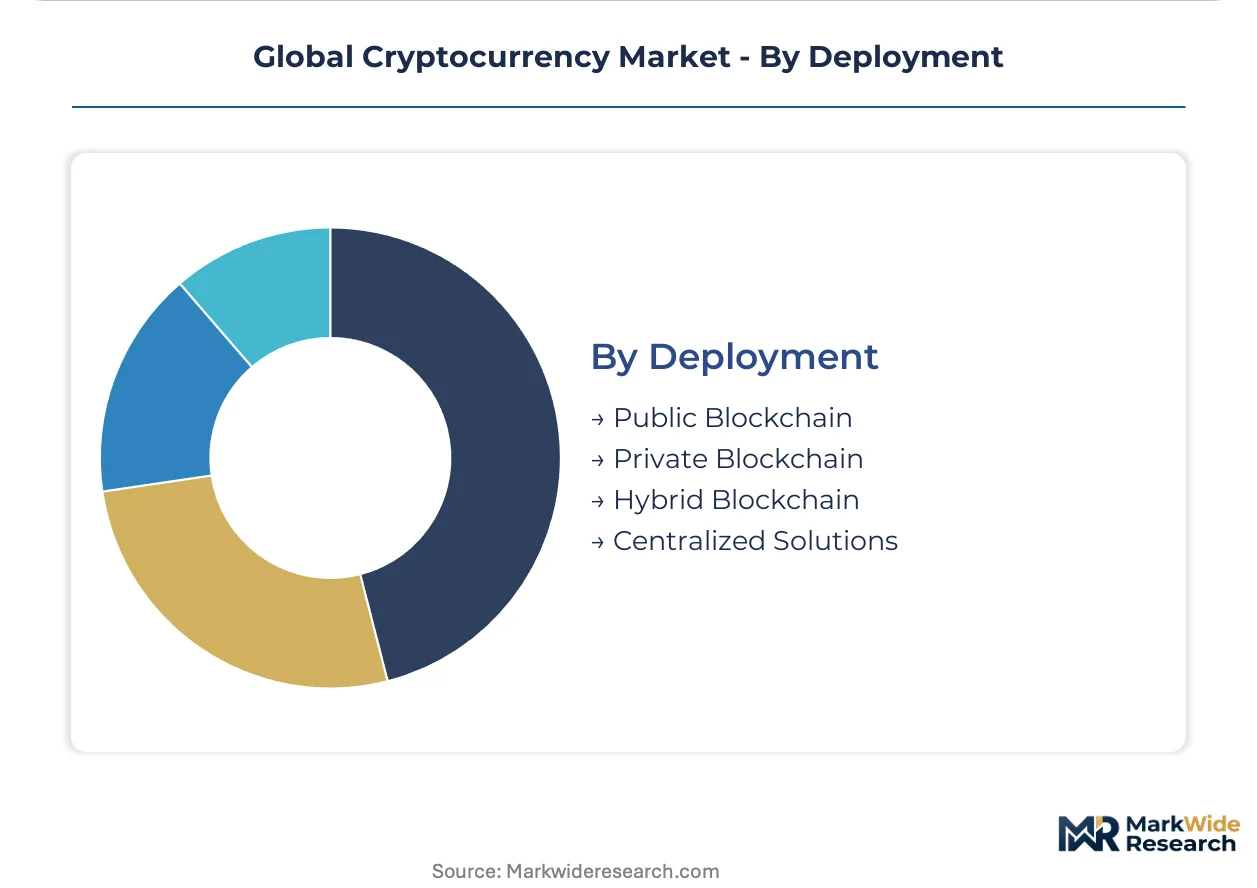
Public networks secure the majority of settled value, though enterprise consortia are piloting hybrid configurations for selective transparency in regulated industries.
- Public Blockchain:Permissionless networks with open validation and transparent settlement. Bitcoin and Ethereum mainnets settle the preponderance of institutional value transfer globally.
- Private Blockchain:Restricted access networks for enterprise consortia with known validators. Banking syndicates in Switzerland and trade finance groups in Singapore pilot these for confidential settlement.
- Hybrid Blockchain:Configurations combining public anchoring with private transaction processing. EU supply chain consortia utilize these for selective disclosure under CSRD reporting requirements.
- Centralized Solutions:Exchange-hosted wallets and custodial services with operational control retained by providers. Regulatory licensing in Japan and Singapore mandates segregated custody and reserve transparency.
Public blockchain commands the established base. Hybrid configurations are gaining share fastest among enterprise consortia seeking regulatory auditability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hashrate clustering concentrates in jurisdictions with subsidized electricity and permissive regulatory postures, while institutional capital flows toward licensed custody venues in Singapore and Switzerland. Regulatory arbitrage between the SEC's enforcement posture and the EU's MiCA framework is fragmenting operational licensing strategies.
United States
Corporate treasury adoption and spot ETF inflows drive institutional demand concentration. The SEC applies the Howey test to token classification, creating compliance overhead for issuers and delisting risk for unregistered securities. Texas hosts mining operations leveraging stranded renewable energy, while New York enforces BitLicense requirements that filter exchange participation.
Singapore
Family office capital and licensed exchange operators concentrate demand in this jurisdiction. The Monetary Authority of Singapore mandates segregated custody and reserve transparency for digital payment token service providers. Marina Bay financial district anchors custody infrastructure development as wealth managers establish dedicated digital asset desks.
Switzerland
Private banking integration and self-custody hardware deployment characterize institutional entry patterns. FINMA guidelines distinguish between payment tokens, asset tokens, and utility tokens for licensing purposes. Zug's Crypto Valley hosts protocol development clusters and custody boutiques displacing traditional wealth manager mandates.
Germany
Institutional staking participation and BaFin-licensed custody providers expand fiduciary-grade infrastructure. BaFin classifies cryptocurrencies as financial instruments under the Banking Act, requiring licensing for proprietary trading and custody services. Frankfurt anchors regulated exchange operations serving pension fund and insurance treasury allocations.
United Arab Emirates
Single-family office direct custody and free zone licensing attract operational migration from restrictive jurisdictions. VARA in Dubai and ADGM in Abu Dhabi issue comprehensive frameworks for virtual asset service providers. Dubai International Financial Centre concentrates custody infrastructure and protocol development talent from departing European operators.
Global Cryptocurrency Market Vendor Landscape
Concentration sits with asset managers and regulated exchanges that bridge institutional capital to on-chain infrastructure. Market structure divides between vertically integrated custody-trading platforms and specialized infrastructure providers. Strategic archetypes include ETF sponsors with distribution dominance, exchange operators with compliance depth, and treasury-strategy corporates with leveraged Bitcoin positions. Competitive moves center on jurisdictional licensing expansion and custody insurance capacity acquisition.
Among asset manager archetypes, BlackRock anchors institutional distribution through ETF infrastructure. Within the regulated exchange tier, Coinbase Global exemplifies compliance-first positioning across multiple jurisdictions. On the corporate treasury vector, MicroStrategy occupies a distinctive position converting operating cash flows into long-dated digital asset allocations.
| Leading Market Players |
|---|
| Consensys |
| Core Scientific |
| Coinbase Global |
| BlackRock |
| BitGo |
| Binance |
| MicroStrategy |
| Tether |
| Kraken |
| Others |
Supply Flow & Price Mechanics
Proof-of-stake validation replacing energy-intensive proof-of-work consensus simultaneously redistributes mining geography toward jurisdictions with low-cost renewable infrastructure and compresses operational cost structures for network participants. This substitution dynamic rewires both supply chain positioning and pricing economics across custody and staking service tiers.
Pricing Analysis
Volume-discount tiering structures separate institutional custody mandates from retail exchange fees and wholesale staking yields. Pricing stratifies across premium fiduciary-grade custody with insurance backing, standard regulated exchange execution, and economy self-custody hardware solutions. Cost compression in economy tiers is intensifying because retail users migrate toward hardware wallet purchases and decentralized exchange aggregation. Pension funds and endowments exhibit the lowest price sensitivity due to fiduciary liability concerns, while retail traders in emerging markets demonstrate acute sensitivity to transaction fee differentials.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time liquidity provisioning over strategic token stockpiles due to settlement finality risks and regulatory delisting exposure. Mining hardware fabrication concentrates in Taiwan, Malaysia, and China, while cold storage device manufacturing clusters in South Korea and Switzerland. Raw material dependencies include semiconductor-grade silicon, rare earth magnets for cooling systems, and specialized ASIC chip designs. Single-source vulnerability runs through TSMC's advanced node capacity for mining rig processors. Distribution runs through licensed exchange onramps in Singapore, Switzerland, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
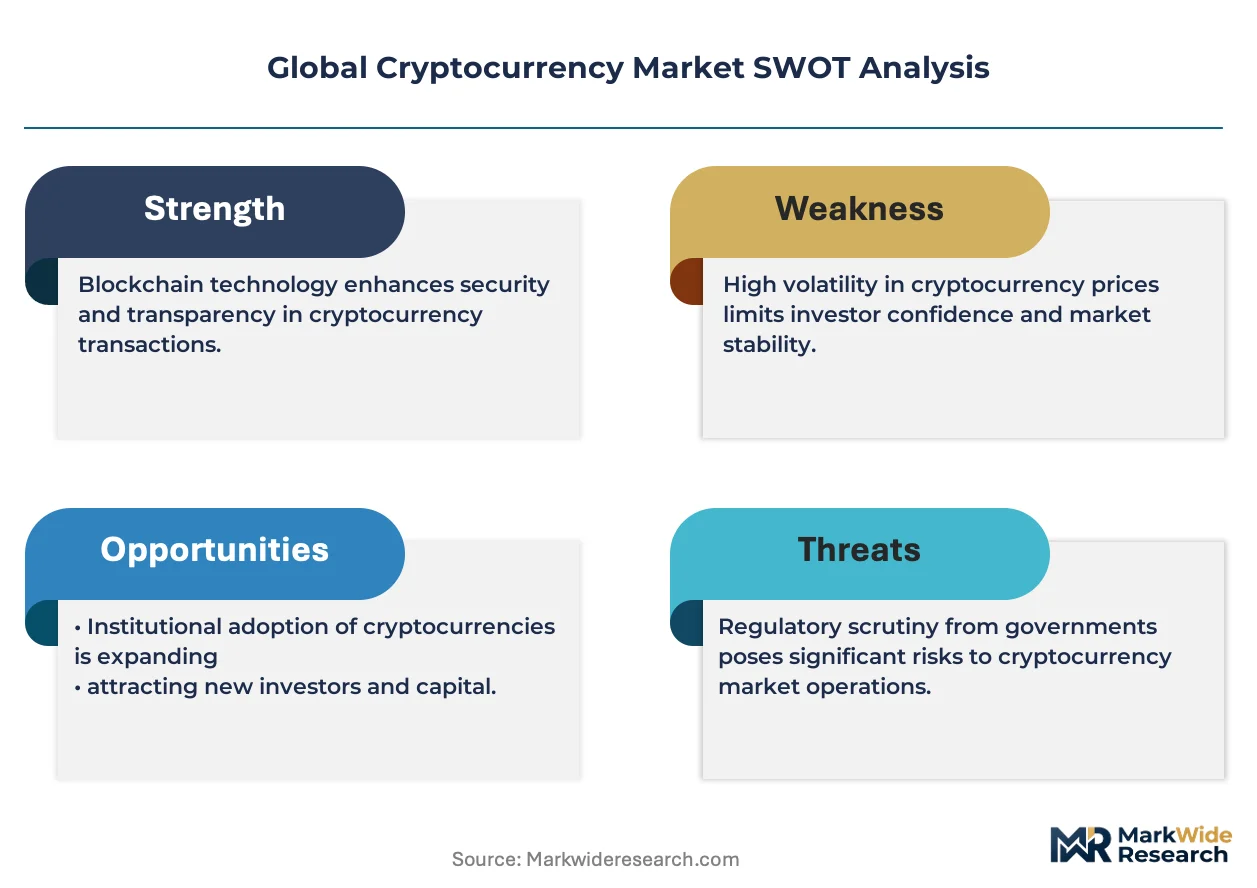
The Global Cryptocurrency Market represents a high-growth disruption justified by the EU MiCA regulatory inflection that mandates uniform licensing standards and reserve transparency across member states.
For Market Incumbents: Consolidate custody insurance capacity and jurisdictional licensing depth to defend against specialized boutiques capturing family office mandates. Acquire cold storage infrastructure operators in Switzerland and Singapore to anchor geographic diversification. Deepen backward integration into staking node operations to capture yield compression before margin erosion accelerates.
For New Entrants and Emerging Players: Anchor in India's underpenetrated retail access corridor where RBI's central bank digital currency pilot creates compliant fiat-to-crypto onramp white space. Target institutional custody services for pension funds and endowments requiring fiduciary-grade infrastructure. Pursue partnership-first go-to-market with established wealth managers seeking digital asset capability without proprietary buildout.
For Investors and Strategic Acquirers: The market sits at a regulatory-clarification phase that favors compliance-first infrastructure providers over speculative token ventures. Long-term viability centers on custody and staking service providers with multi-jurisdictional licensing and insurance backing. Monitor SEC enforcement posture against unregistered securities as the primary inflection signal for capital formation venue viability.
| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Completion | Circle and European banks restructure treasury operations to meet segregated custody mandates ahead of implementation deadlines. |
| Institutional Custody Expansion | Cold storage boutiques in Geneva and Dubai displace traditional wealth manager mandates through direct family office relationships. |
| Staking Infrastructure Buildout | BaFin-licensed German providers expand fiduciary-grade validation services for pension fund treasury allocations. |
| Zero-Knowledge Verification Integration | Swiss and Singaporean custodians compress trust overhead through zk-SNARK attestation for cross-border settlement workflows. |
| Hardware Security Module Deployment | Single-family offices hire dedicated digital asset officers and deploy HSMs for self-custody in Zug and Marina Bay clusters. |
Methodological Framework
Desk research of regulatory filings from the SEC, BaFin, and MAS preceded structured interviews with exchange compliance officers, custody infrastructure engineers, and family office digital asset officers. Secondary validation drew from MiCA implementation guidance, FINMA token classification guidelines, and FSA exchange auditing protocols. Bottom-up exchange volume modeling and top-down institutional allocation surveys were triangulated against mining hashrate distribution data.
Variance decomposition across consensus mechanism types, application segments, and deployment architectures shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include token type, end-user archetype, and jurisdictional regulatory cluster. CAGRs were derived from institutional allocation velocity patterns and custody fee compression trajectories. Forecast inputs incorporated staking yield spreads and electricity cost arbitrage differentials across mining jurisdictions.
Decision-makers should treat outputs as directional under assumptions of continued regulatory clarity progression and institutional custody standardization; material deviation would warrant model refresh. Revision becomes warranted when securities classification enforcement crosses thresholds that trigger mass delisting events or when hashrate geography concentrates beyond single-jurisdiction vulnerability tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Crypto Wallet Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market