
 Marine Cargo Insurance Market | 2026-2036
Marine Cargo Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Cargo Insurance Market Analysis
Steel hull construction is hardening premium calculations for high-value cargo routes as underwriters reassess corrosion-risk exposure. Allianz Commercial leverages its London marine market heritage to sustain leadership in complex project-cargo placements. Falvey Insurance Group anchors its portfolio in North American fishing and towing fleets, competing through specialized underwriting expertise. AXA XL differentiates via integrated cargo and logistics liability programs for multinational manufacturers.
Marine cargo insurance is a specialized risk-transfer instrument covering physical loss or damage to goods during ocean, air, or inland transit, with policies typically specifying per-voyage or open-coverage terms, deductible structures, and Institute Cargo Clauses A, B, or C coverage levels. Its primary commercial purpose is to protect balance sheets against supply chain interruptions and to satisfy trade-finance requirements. All Risk coverage dominates premium volume among coverage types, though Named Perils policies retain strong uptake in bulk-commodity trades where loss causation is more predictable. Open Policy structures lead policy-structure demand among large importers and exporters seeking administrative efficiency, while Single Shipment placement grows fastest among small and medium enterprises entering cross-border e-commerce.
The International Maritime Organization's mandatory container-weight verification rules shape underwriting accuracy, while the EU's Insurance Distribution Directive governs broker placement standards across European trading corridors. The US Federal Maritime Commission monitors carrier liability limits that indirectly affect cargo-insurance attachment points. Underwriters must decide whether to deepen predictive-analytics investment or cede marine-cargo profitability to reinsurance panels as climate-loss volatility intensifies.
Market Dynamics
The International Maritime Organization's mandatory container-weight verification rules are compressing underwriting cycles as carriers and shippers synchronize data streams for risk assessment accuracy.
Growth Catalysts
- IMO Safety Verification:The International Maritime Organization's revised container-weight protocols are mandating precise cargo documentation, forcing shippers to purchase comprehensive coverage as carrier liability limits tighten.
- E-commerce Volume Concentration:Asian manufacturing hubs in Shenzhen and Shanghai are generating concentrated risk pools that require specialized open-policy structures for high-frequency cross-border shipments.
- Steel Hull Underwriting:Advanced corrosion-risk modeling for steel-hulled vessels is expanding addressable premium pools on high-value cargo routes previously deemed uninsurable.
Market Restraints
- Climate Loss Volatility:Intensifying weather patterns in Pacific shipping lanes are compressing reinsurance capacity and elevating retrocession costs for primary underwriters.
- Single-Point Carrier Dependency:Concentration of container traffic through the Suez and Panama canals creates catastrophic accumulation exposure that capital markets are reluctant to backstop.
- Liability Limit Friction:The US Federal Maritime Commission's carrier liability ceilings constrain attachment-point flexibility, forcing cargo owners to bridge coverage gaps with supplemental policies.
Strategic Opportunities
- Indian Port Expansion:Jawaharlal Nehru Port and Mundra Port clusters are developing specialized marine cargo ecosystems with regulatory support from the country's central shipping authority.
- Predictive Analytics Convergence:Integration of satellite vessel-tracking with Internet-of-Things container sensors is enabling real-time premium adjustment models for perishable and high-value cargo.
- SME Single-Shipment Channel:Digital broker platforms are capturing small and medium enterprises entering cross-border e-commerce with transactional coverage replacing annual open policies.
Industry Challenges
- Marine Actuarial Talent Scarcity:Specialized underwriting expertise in project cargo and fishing fleet risk is concentrating at a shrinking pool of Lloyd's syndicates and London market carriers.
- Legacy System Integration:Incumbent insurers face data architecture friction when embedding API-connected cargo sensors into decades-old policy administration platforms.
- Multi-Jurisdiction Compliance Timelines:The EU's Insurance Distribution Directive, the US Federal Maritime Commission rules, and the International Maritime Organization protocols create overlapping certification requirements for multinational programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Cargo Insurance Market |
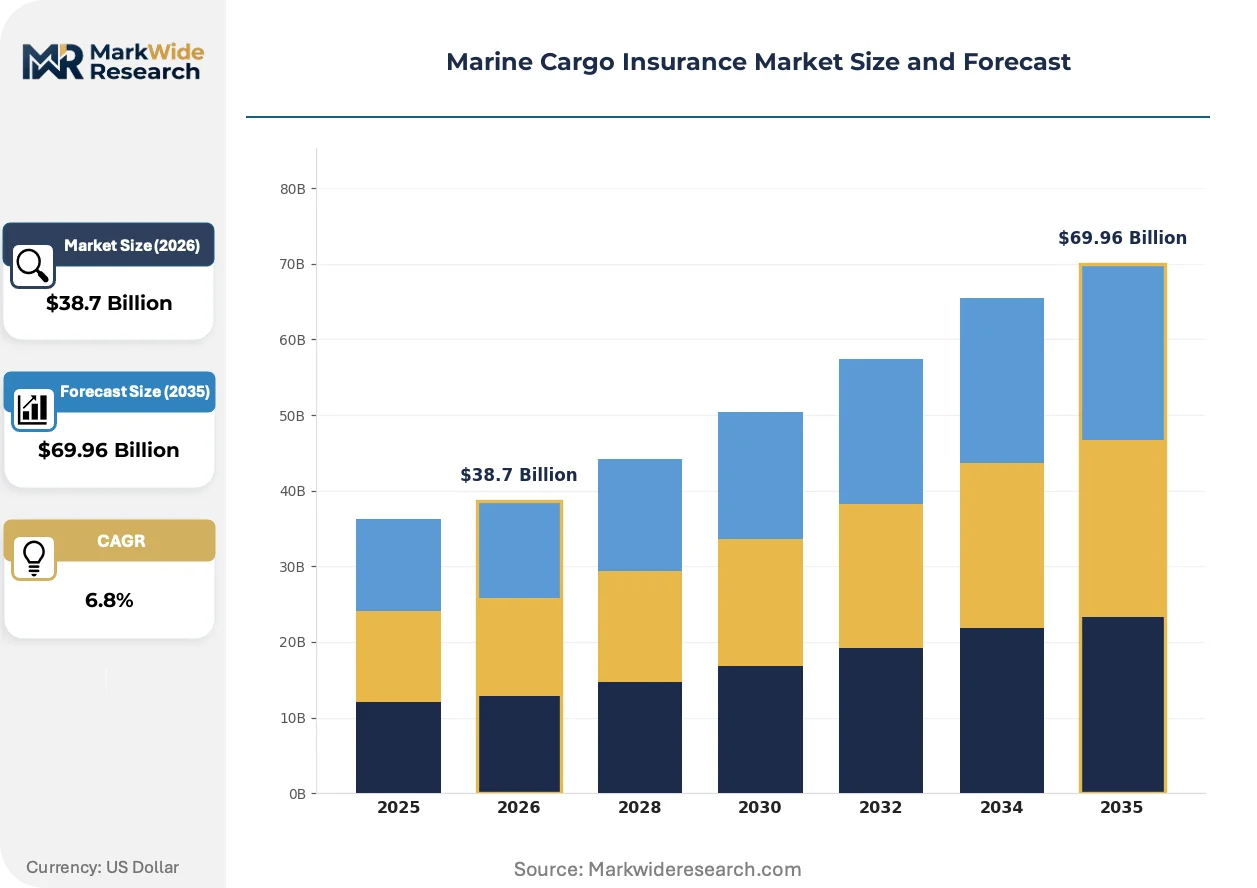
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: All Risk, Total Loss, Named Perils, Specific Cargo Policy Structure: Open Policy, Single Shipment, Annual Policy, Specific Voyage End User: Importers, Exporters, Logistics Providers, Freight Forwarders Premium Type: Flat Rate, Variable Rate, Risk-Based, Discounted Rate |
| Companies Covered | Progressive, PURE Insurance, Allianz Commercial, Falvey Insurance Group, Global Marine Insurance Agency, AXA XL, Nationwide, AXIS Specialty, Great American Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Cargo Insurance Market Emerging Trajectories
Telematics-enabled cargo monitoring is compressing the information asymmetry between underwriters and insureds, while regulatory fragmentation across maritime jurisdictions is forcing modular policy architecture.
Blockchain-based bill-of-lading verification is expanding into marine cargo underwriting workflows as a fraud-prevention layer. Large commodity traders and agricultural exporters are piloting distributed-ledger documentation to accelerate claims settlement. This technology is expanding into premium financing arrangements where trade-finance banks require immutable cargo provenance.
The EU's Insurance Distribution Directive is tightening broker disclosure standards across European trading corridors. Underwriters must now document policy comparison rationale and commission transparency, elevating compliance overhead. German and Dutch industrial importers are responding by consolidating placements with vertically integrated insurers offering bundled cargo and logistics liability programs.
Cross-border e-commerce sellers are unbundling annual open policies in favor of transaction-embedded coverage at digital checkout. Chinese and Southeast Asian platform merchants are driving this shift, purchasing single-shipment protection through integrated logistics marketplaces. This pattern concentrates among small electronics and fashion exporters serving European and North American consumer markets.
Marine Cargo Insurance Market Segmentation
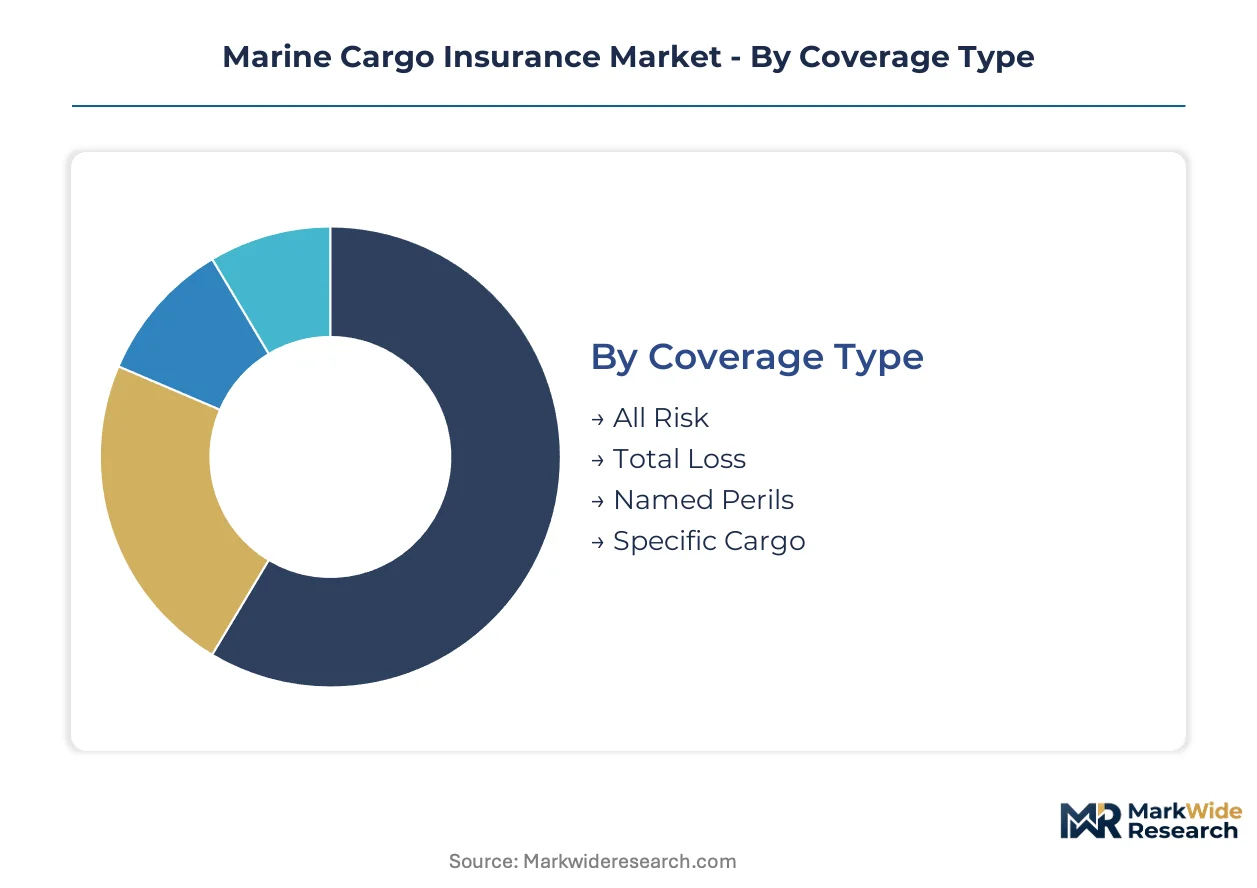
Marine cargo insurance segmentation reflects divergent risk appetites across trade finance requirements and operational complexity. Shippers select coverage tiers based on cargo value concentration, route predictability, and documentary compliance burdens imposed by international regulators.
Coverage Type:
Replacement-cycle dynamics in coverage selection follow cargo-value appreciation and carrier liability compression, with shippers upgrading from minimal protection as supply chain financing requirements tighten.
- All Risk:Institute Cargo Clauses A coverage indemnifies against all external causes of loss except enumerated exclusions, commanding premium concentration among electronics and pharmaceutical exporters. German and Dutch industrial importers favor this tier for project cargo moving through Rotterdam and Hamburg port clusters where financing covenants mandate comprehensive protection.
- Named Perils:Institute Cargo Clauses B and C specify enumerated risks including fire, vessel stranding, and jettison, attracting bulk-commodity traders with predictable loss causation. Agricultural exporters from Brazil and Australia select this tier for grain and mineral shipments where per-tonne premium efficiency outweighs coverage breadth.
- Total Loss:Catastrophic-only coverage attaches solely for complete vessel or cargo destruction, serving niche applications in distressed-route trades. The structure appeals to speculative commodity traders accepting retention of partial damage exposure.
- Specific Cargo:Bespoke wording addresses singular exposures including fine art, live animals, or temperature-sensitive pharmaceuticals. Swiss and Belgian specialty underwriters dominate placement for these risks.
All Risk sits at the top of the volume ranking, with Specific Cargo climbing the fastest.
Policy Structure:
Administrative cost tiers separate multinational programs from transactional coverage, with digital platforms collapsing the traditional efficiency gap between annual and per-shipment placement.
- Open Policy:Continuous coverage for all shipments within declared parameters eliminates per-transaction placement overhead. Shenzhen and Shanghai manufacturing clusters generate concentrated demand from high-frequency cross-border e-commerce exporters requiring administrative streamlining.
- Single Shipment:Transaction-specific coverage attaches at digital checkout for SMEs entering international trade. Southeast Asian platform merchants drive expansion through integrated logistics marketplaces serving European consumer markets.
- Annual Policy:Fixed-term contracts with declared value limits serve mid-size importers with predictable volume patterns. The structure retains stronghold among Japanese automotive component suppliers.
- Specific Voyage:One-off placement for project cargo or irregular trades addresses non-recurring exposures. Offshore energy contractors favor this structure for rig mobilization and decommissioning movements.
Open Policy dominates premium volume, though Single Shipment is expanding most quickly.
End User:
Customer-type stratification follows control over cargo custody, with liability retention driving coverage purchase decisions across the transport chain.
- Importers:Buyers securing coverage to protect against seller default or transit damage dominate demand in CIF-contract trades. US retailers purchasing from Asian manufacturing hubs drive volume through Los Angeles and Long Beach port gateways.
- Exporters:Sellers protecting against payment default risk and physical loss concentrate among Chinese electronics manufacturers. FOB-contract exporters retain coverage through delivery to carrier.
- Logistics Providers:Third-party operators securing contingent cargo interest coverage protect against contractual liability. The segment concentrates among European contract logistics specialists.
- Freight Forwarders:Intermediaries purchasing errors-and-omissions overlays with cargo coverage address multimodal liability accumulation. The category shows steepest expansion trajectory as NVOCCs deepen insurance integration.
Importers command the largest premium share, with Freight Forwarders gaining share fastest.
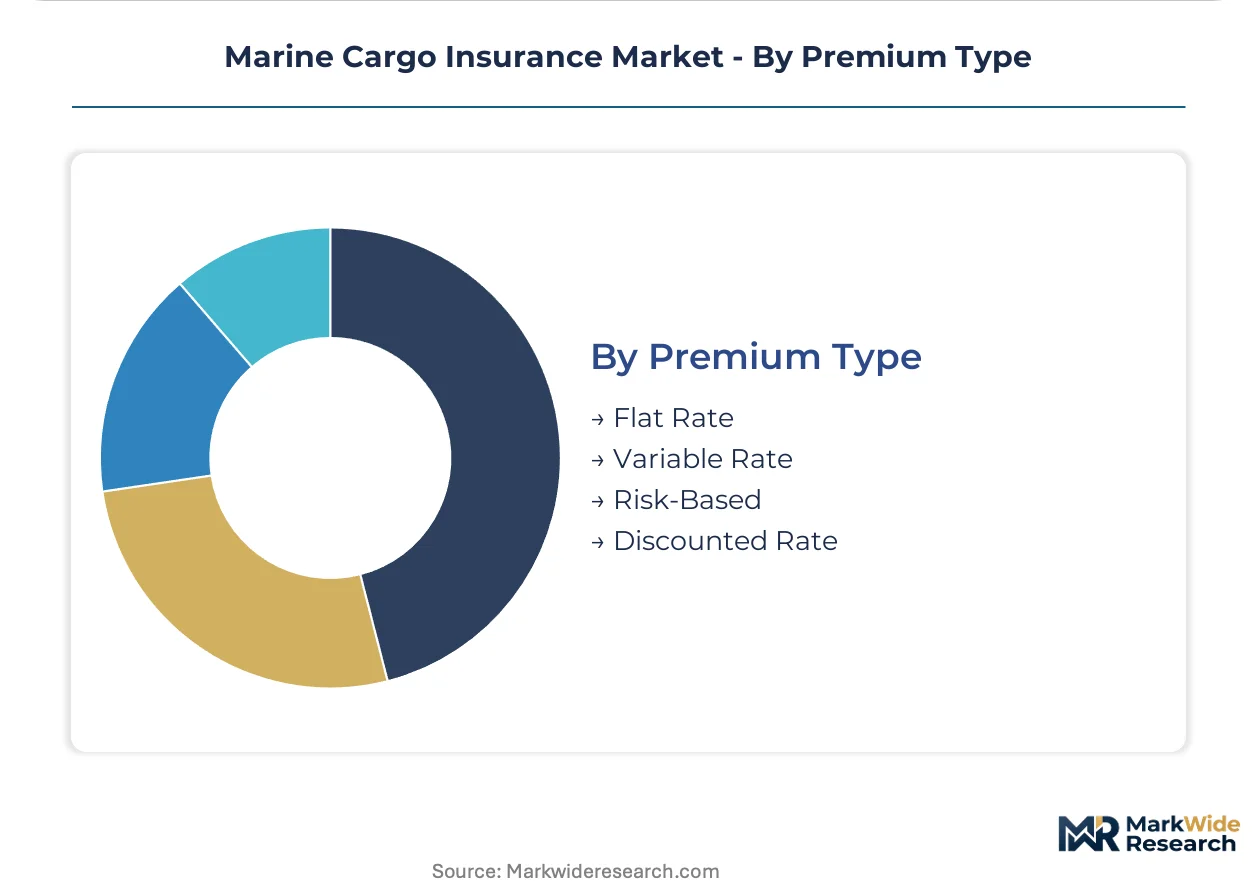
Premium Type:
Margin structure in rating methodology separates commoditized flat-rate offerings from capital-intensive risk-based pricing requiring proprietary data infrastructure.
- Flat Rate:Standardized premium per unit value simplifies placement for low-complexity cargo. Bulk-commodity traders favor this predictability.
- Variable Rate:Adjustments for route, season, and vessel age introduce limited flexibility. The structure serves general cargo with moderate risk differentiation.
- Risk-Based:Individual loss history, security protocols, and supply chain resilience metrics determine pricing. High-value cargo routes through the Indian Ocean and Gulf of Aden require this granularity.
- Discounted Rate:Volume commitments or captive retention structures reduce premium for large industrial shippers. German automotive exporters leverage scale for preferential terms.
Risk-Based rating captures the highest-margin placement volume, with Discounted Rate showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Shanghai port clusters anchor premium concentration as Asian manufacturing hubs generate specialized open-policy demand for high-frequency cross-border shipments.
China
Shenzhen and Shanghai manufacturing clusters drive concentrated risk pools requiring specialized marine cargo policies for electronics exporters. The country's central shipping authority enforces container-weight verification protocols that elevate underwriting documentation standards. Guangdong province shippers purchase comprehensive coverage as carrier liability limits tighten under IMO-mandated safety rules.
United States
Los Angeles and Long Beach port gateways absorb cargo coverage demand from retailers sourcing through Asian manufacturing hubs. The Federal Maritime Commission monitors carrier liability ceilings that constrain attachment-point flexibility for cargo owners. California-based importers bridge coverage gaps with supplemental policies as trade volumes surge through Pacific shipping lanes.
Germany
Rotterdam and Hamburg port clusters concentrate demand for All Risk coverage among industrial importers with project-cargo financing covenants. The EU's Insurance Distribution Directive governs broker placement standards and elevates compliance overhead across European trading corridors. German automotive exporters leverage scale for preferential terms under discounted rate structures.
India
Jawaharlal Nehru Port and Mundra Port clusters are developing specialized marine cargo ecosystems with regulatory support from the country's central shipping authority. Indian electronics and pharmaceutical exporters upgrade coverage tiers as supply chain financing requirements tighten. Maharashtra-based manufacturers generate concentrated demand for open-policy structures serving high-frequency cross-border trade.
United Kingdom
London marine market heritage sustains leadership in complex project-cargo placements through Lloyd's syndicates and established carriers. The EU's Insurance Distribution Directive extends disclosure standards to UK-European trading corridors post-Brexit. British specialty underwriters dominate placement for fine art and temperature-sensitive pharmaceutical risks requiring bespoke wording.
Marine Cargo Insurance Market Vendor Landscape
Capacity expansion dominates the current landscape as underwriters deepen predictive-analytics investment to capture climate-loss volatility. The market structures around three tiers: global multi-line carriers with integrated logistics liability programs, London market specialists leveraging marine heritage for complex placements, and regional underwriters anchoring portfolios in fishing fleets and coastal trades. Two competitive moves define positioning: geographic expansion into Indian port clusters and portfolio diversification through single-shipment digital platforms for SME e-commerce entrants.
Within the London market heritage tier, Allianz Commercial and AXA XL exemplify integrated cargo and logistics liability positioning for multinational manufacturers. Falvey Insurance Group occupies the specialized regional anchor position, competing through underwriting expertise concentrated in North American fishing and towing fleets. These three carriers represent the dominant archetypes: global multi-line integration, complex project-cargo specialization, and regional fleet expertise.
| Leading Market Players |
|---|
| Progressive |
| PURE Insurance |
| Allianz Commercial |
| Falvey Insurance Group |
| Global Marine Insurance Agency |
| AXA XL |
| Nationwide |
| AXIS Specialty |
| Great American Insurance Group |
| Others |
Supply Flow & Price Mechanics
Reinsurance capacity costs cascade through primary underwriter rate cards as climate-loss volatility compresses retrocession availability for Pacific shipping lane exposures. This input-cost pass-through stratifies buyer segments, with bulk-commodity traders absorbing standardized flat-rate premiums while high-value cargo shippers absorb risk-based rate granularity for Indian Ocean routes.
Pricing Analysis
Input-cost pass-through from retrocession panels drives rate divergence between commodity and specialty tiers. Risk-based pricing dominates high-value cargo routes through the Gulf of Aden, where individual loss history and security protocols determine premium granularity. Flat-rate structures serve bulk-commodity traders favoring per-tonne predictability. Price differentiation hinges on coverage breadth and financing covenant requirements. Pricing pressure stems from climate-loss volatility elevating reinsurance attachment costs. Bulk-commodity traders exhibit highest price sensitivity, while pharmaceutical exporters with project-cargo financing mandates accept premium tiers for All Risk protection.
Supply Chain Analysis
Single-source vulnerability sits with Lloyd's syndicate capacity concentration for complex project-cargo placements. Underwriting expertise draws from London market heritage, with secondary capacity anchored in German industrial importer programs and Chinese e-commerce platform integrations. Raw material dependencies include actuarial talent pools, satellite vessel-tracking infrastructure, and Internet-of-Things sensor networks. Supply chain risk centers on marine actuarial talent scarcity concentrating at shrinking specialist pools. Distribution runs through broker platforms for SME single-shipment coverage and direct carrier relationships for multinational open-policy programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive-analytics premium tiers as telematics-enabled cargo monitoring compresses information asymmetry and elevates risk-based rate capture.
For Market Incumbents: Cement London market heritage positioning through deeper Lloyd's syndicate integration for complex project-cargo placements. Invest in API-connected cargo sensor architecture to resolve legacy system friction. Climate-loss volatility threatens unhedged portfolios; reinsurance panel relationships are the critical lever. For New Entrants and Emerging Players: Begin with Indian port cluster expansion at Jawaharlal Nehru and Mundra, where regulatory support from the central shipping authority creates white-space availability. Target SME single-shipment channels through digital broker platforms. Embedded coverage at logistics marketplace checkout offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where marine actuarial talent scarcity concentrates capability at legacy Lloyd's syndicates. Long-term viability favors carriers with predictive-analytics infrastructure and integrated cargo-logistics liability programs. Watch satellite vessel-tracking adoption rates as the inflection signal for real-time premium adjustment model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Investment | Real-time premium adjustment from IoT container sensors captures climate-loss volatility margins. |
| Indian Port Cluster Expansion | Jawaharlal Nehru and Mundra regulatory support builds specialized marine cargo ecosystems. |
| Digital Broker Platform Integration | Single-shipment transactional coverage captures SME e-commerce entrants at logistics checkout. |
| Legacy System API Modernization | Embedded cargo sensor data resolves decades-old policy administration architecture friction. |
| Reinsurance Panel Diversification | Retrocession capacity access hedges Pacific shipping lane climate-loss accumulation exposure. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged marine underwriters at Lloyd's syndicates, cargo risk managers at German industrial importers, platform merchants in Shenzhen and Shanghai manufacturing clusters, and digital broker operators serving SME cross-border e-commerce. Secondary validation drew from International Maritime Organization protocol documentation, EU Insurance Distribution Directive filings, US Federal Maritime Commission carrier liability determinations, and customs trade flow records. Bottom-up shipment volume estimates triangulated against top-down premium pool assessments.
Comparable-period anchoring established baseline reference points across historical and projected intervals. Segmentation modeling incorporated coverage type tiers, policy structure categories, end-user custody control patterns, and premium rating methodologies. CAGRs were derived from trajectory fitting across the projection horizon. Industry-specific forecast inputs included container-weight verification compliance adoption curves and satellite vessel-tracking penetration rates for perishable cargo routes.
Several conditions sit outside the modeled scope, including sovereign trade policy disruptions, pandemic-scale supply chain discontinuities, and catastrophic canal blockage events exceeding historical accumulation thresholds. Forecasts reflect documented assumptions about regulatory implementation timelines and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Drone Insurance Market
Insurance
Takaful Market
Insurance
US Homeowner's Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Horse Insurance Market
Insurance
US Travel Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Crop Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Boiler Insurance Market
Insurance
Takaful Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
India Online Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Asia-Pacific EV Insurance Market