
 Crypto Asset Management Market | 2026-2036
Crypto Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto Asset Management Market Intelligence
The premium-commodity split in crypto asset management is shifting as institutional-grade custody and compliance services separate from retail trading tools. Grayscale Investments leverages its ETF infrastructure to anchor institutional access. Coinbase Global sustains regulatory licensure across multiple jurisdictions. Pantera Capital specializes in early-stage token strategies that differentiate its risk profile from passive index offerings.
Crypto asset management encompasses the professional oversight, custody, and optimization of digital asset portfolios through cryptographic key management, multi-signature security protocols, and blockchain-native settlement rails. The primary purpose centers on delivering risk-adjusted exposure to tokenized assets while satisfying fiduciary obligations around safekeeping and reporting. Custodial Services command premium fee structures due to insurance requirements and cold-storage infrastructure costs. Institutional Investors represent the fastest-growing end-user category as defined-benefit plans seek non-correlated returns. Smart Contracts embedded in portfolio management automate rebalancing and reduce intermediary friction.
The SEC shapes product architecture through enforcement actions on unregistered investment vehicles, while the EU's MiCA framework establishes licensing thresholds for custodial providers operating across member states. The IRS and OECD tax-reporting standards compel service-type expansion into specialized compliance and tax-engineering functions. Stakeholders must monitor how jurisdictional regulatory divergence affects cross-border fund structuring and client onboarding workflows.
Market Dynamics
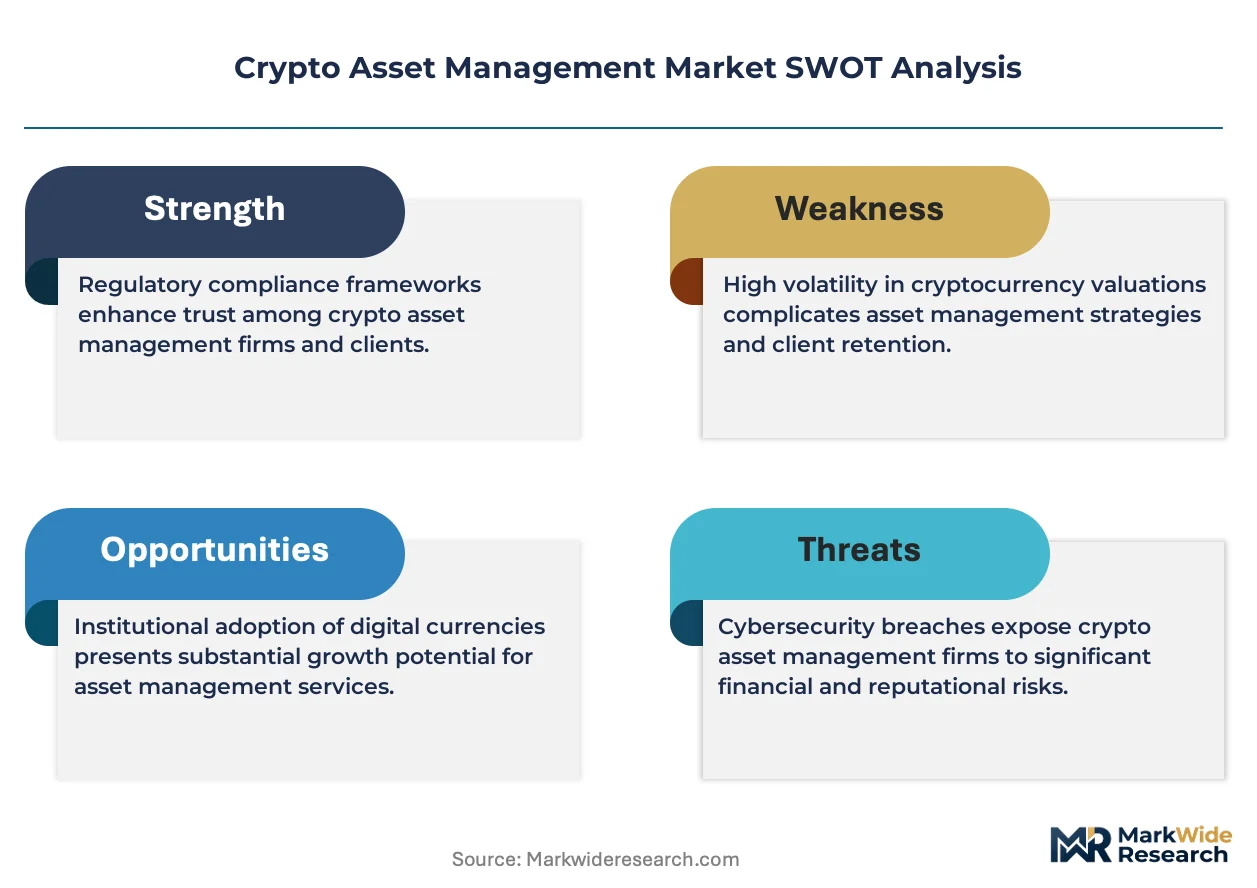
Institutional capital deployment into tokenized portfolios is compressing fee structures while demanding institutional-grade custody infrastructure, forcing asset managers to rebuild operational stacks around cold-storage security and real-time compliance reporting.
Growth Catalysts
- Spot ETF Frameworks:The SEC's evolving approval pathway for exchange-traded products is unlocking pension fund participation. Defined-benefit plans now access crypto exposure through regulated wrappers.
- Multi-Signature Custody Protocols:Hardware security modules and distributed key management are reducing counterparty risk. Family offices mandate these standards for treasury allocation.
- MiCA Licensing Thresholds:The EU's unified regulatory framework is enabling cross-border passporting for custodial services. Asset managers establish Dublin and Luxembourg hubs to serve continental clients.
Market Restraints
- Insurance Cost Volatility:Cold-storage coverage premiums fluctuate with breach frequency. Lloyd's syndicates restrict policy capacity for unproven custodial technologies.
- Jurisdictional Arbitrage Limits:Divergent SEC and FCA stances on staking rewards create product fragmentation. Managers maintain separate fund structures for US and UK LPs.
- Settlement Finality Gaps:Blockchain reorganization risk in proof-of-work networks prevents same-day NAV certainty. Institutional auditors require confirmation delays.
Strategic Opportunities
- Tokenized Real-Asset Strategies:On-chain representation of private credit and real estate expands addressable AUM. Singapore's regulatory sandbox accelerates pilot programs.
- Tax-Engineering Services:IRS and OECD reporting mandates create compliance white space. Specialized advisory units capture high-margin recurring revenue.
- Smart-Contract Automation:Programmable rebalancing and yield harvesting reduce operational headcount. DeFi-native strategies attract quant-focused allocators.
Industry Challenges
- Cryptographic Talent Scarcity:Qualified security engineers command compensation multiples above traditional asset management. Recruitment timelines extend to nine months for senior roles.
- Legacy System Integration:Portfolio accounting software lacks native blockchain data feeds. Middleware development consumes disproportionate IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto Asset Management Market |
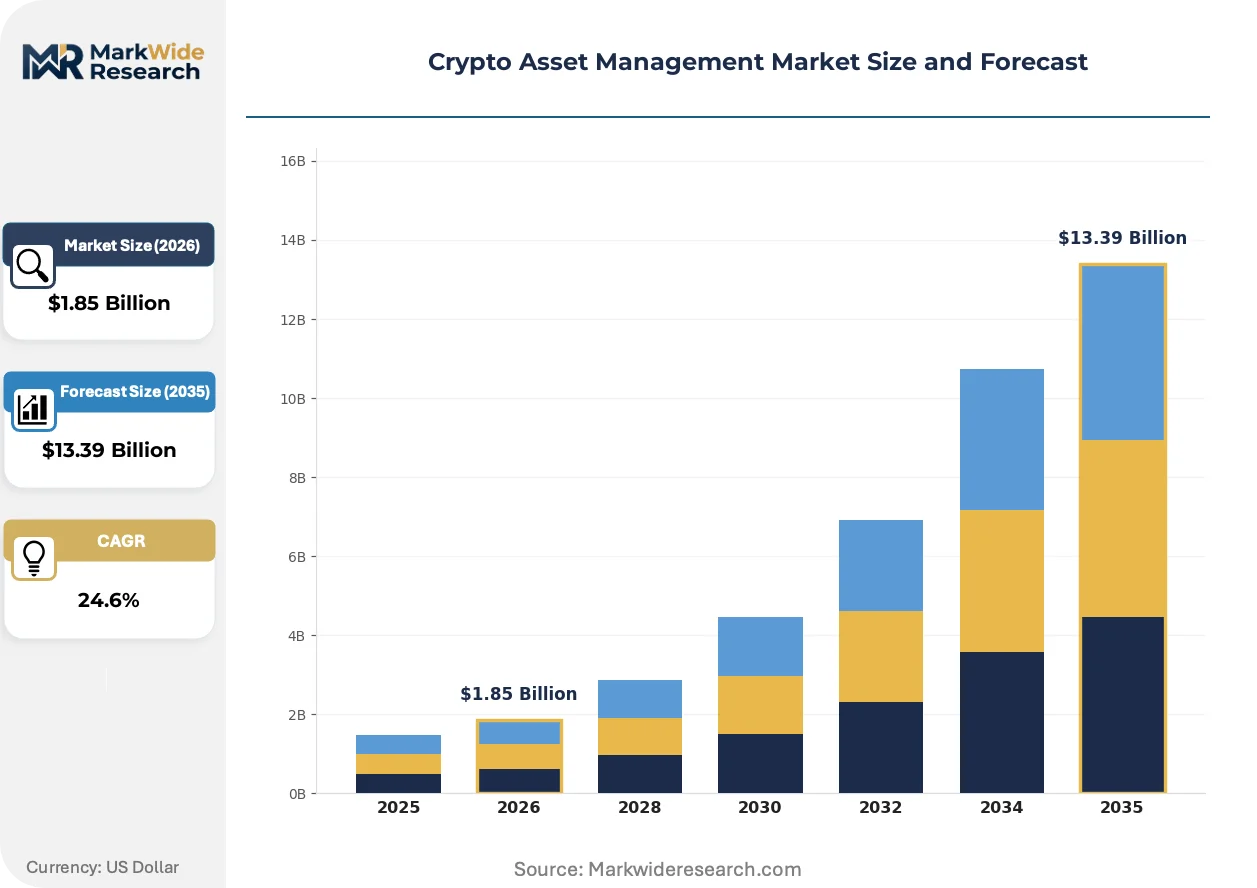
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.39 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wallets, Exchanges, Custodial Services, Trading Platforms End User: Retail Investors, Institutional Investors, Fund Managers, High Net-Worth Individuals Service Type: Advisory Services, Portfolio Management, Compliance Services, Tax Services Technology: Blockchain, Smart Contracts, Artificial Intelligence, Data Analytics |
| Companies Covered | Multicoin Capital, Paradigm, Grayscale Investments, MicroStrategy, Coinbase Global, Galaxy Digital, Polychain Capital, VanEck, Pantera Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto Asset Management Market Strategic Shifts & Innovations
Technology architecture and regulatory taxonomy are diverging sharply between institutional and retail service tiers, with compliance automation becoming the primary competitive battleground rather than raw performance.
Institutional custody infrastructure is modularizing around hardware security modules and policy engines that separate key management from trade execution. Pension consultants now require SOC 2 Type II attestation as a minimum threshold for manager selection. This bifurcation is compressing margins for undifferentiated retail wallet providers while entrenching specialized custodians with insurance-backed cold storage.
The SEC's enforcement posture on unregistered investment vehicles is forcing product redesign around qualified purchaser exemptions. Managers are restructuring feeder funds to limit LP counts while maintaining regulatory compliance. This regulatory pressure is most acute for staking-as-a-service offerings, where the Howey analysis remains unsettled and counsel fees consume basis points.
Family office procurement of crypto exposure is rotating from direct token holding to fund-of-funds structures with embedded custody and reporting. Single-family offices in Wyoming and South Dakota lead this shift, drawn by state-level trust company frameworks. The operational burden of private key management is outsourcing to specialized administrators who bundle tax, custody, and portfolio accounting.
Crypto Asset Management Market Segmentation
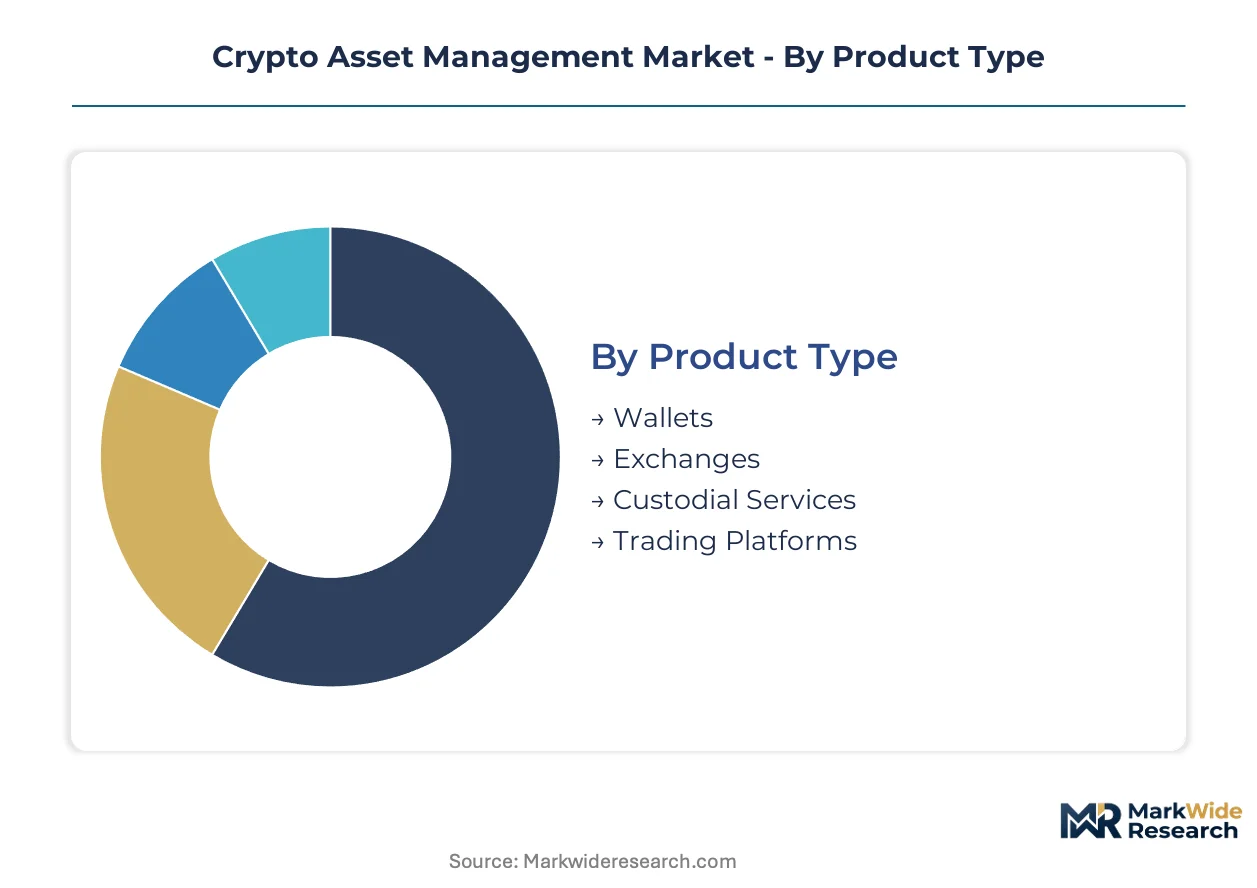
Crypto asset management segmentation reveals how buyer sophistication and regulatory complexity fragment service delivery. Institutional procurement standards now diverge sharply from retail accessibility requirements across custody, trading, and advisory functions.
Product Type:
Institutional procurement teams prioritize insurance-backed infrastructure and audit trails over user interface simplicity.
- Wallets:Software and hardware solutions for private key storage span hot-wallet connectivity and air-gapped cold storage. Retail adoption concentrates in mobile-first jurisdictions with limited banking access, while family offices mandate multi-signature configurations with geographic key distribution.
- Custodial Services:Third-party safekeeping combines cold-storage vaults, insurance coverage, and regulatory licensure. Pension fund due diligence now requires SOC 2 Type II attestation and segregated bankruptcy-remote structures as baseline thresholds.
- Exchanges:Centralized order-matching platforms with fiat on-ramps and spot trading functionality.
- Trading Platforms:Execution venues with algorithmic order types and institutional connectivity protocols.
Volume sits with Exchanges; growth tilts toward Custodial Services.
End User:
Fee compression and service bundling vary dramatically across wealth tiers and fiduciary obligations.
- Institutional Investors:Pension funds, endowments, and sovereign wealth vehicles deploy capital through regulated fund structures. Defined-benefit plans in the United States access exposure via SEC-registered investment vehicles with qualified custodian requirements.
- Fund Managers:Registered investment advisers and hedge funds managing third-party capital require prime brokerage integration and real-time portfolio accounting. Operational workflows demand automated reconciliation against blockchain explorers and sub-custodian feeds.
- Retail Investors:Individual account holders accessing crypto through mobile applications and self-custody solutions.
- High Net-Worth Individuals:Single-family offices and private wealth seeking bespoke allocation strategies.
Revenue concentration favors Institutional Investors; margin expansion tracks Fund Managers.
Service Type:
Regulatory enforcement is forcing unbundled compliance functions to merge into integrated advisory offerings.
- Compliance Services:AML/KYC onboarding, transaction monitoring, and regulatory reporting infrastructure. MiCA licensing in the European Union mandates ongoing surveillance obligations that custodial providers must embed operationally.
- Tax Services:Cost-basis tracking, gain-loss reporting, and jurisdiction-specific filing preparation. IRS guidance on staking income and airdrop taxation creates specialized advisory demand among US-based allocators.
- Advisory Services:Strategic allocation recommendations and risk profiling for crypto exposure.
- Portfolio Management:Active rebalancing, yield harvesting, and risk-adjusted optimization.
Advisory Services capture current spend; Compliance Services are expanding most quickly.
Technology:
Infrastructure investment priorities separate automated execution capabilities from data-intensive risk analytics.
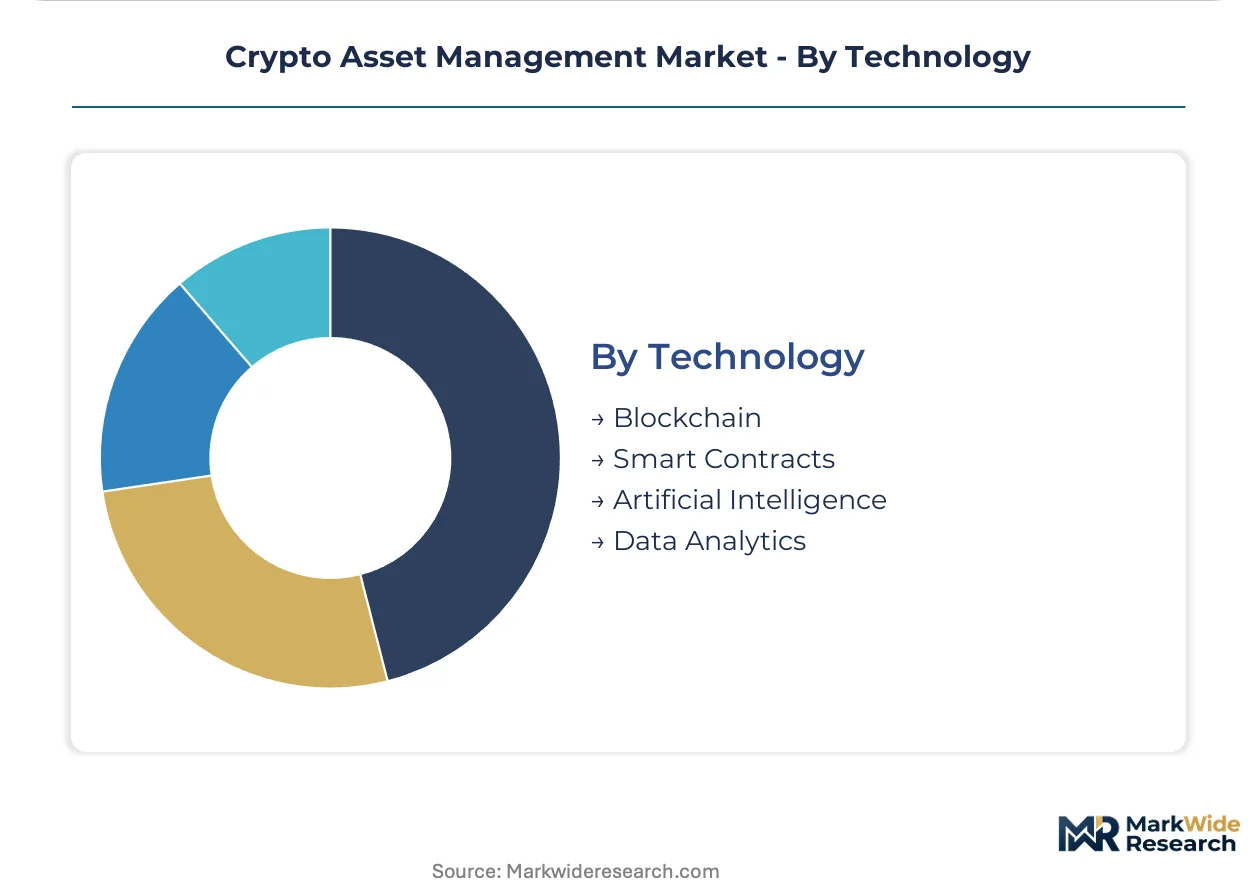
- Smart Contracts:Self-executing protocols automating portfolio rebalancing, yield distribution, and settlement finality. DeFi-native strategies in Singapore's regulatory sandbox leverage programmable logic to reduce operational headcount.
- Artificial Intelligence:Machine learning models for price prediction, anomaly detection, and sentiment analysis. Quantitative allocators demand signal generation across on-chain and off-chain data sources with sub-second latency.
- Blockchain:Distributed ledger infrastructure for settlement, custody, and asset provenance.
- Data Analytics:On-chain metrics, wallet clustering, and network health monitoring tools.
Deployment maturity rests with Blockchain; capability investment flows to Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York anchors institutional crypto asset management activity through concentrated hedge fund and family office operations. The metropolitan corridor houses the largest concentration of SEC-registered investment advisers offering digital asset strategies. Regulatory clarity from Washington shapes cross-border fund structuring decisions.
United States
Pension fund mandates and defined-benefit plan allocations drive institutional demand across the Northeast and West Coast. The SEC's spot ETF approval pathway and qualified custodian requirements determine product architecture. Wyoming and South Dakota trust company frameworks attract single-family offices seeking embedded custody solutions.
Switzerland
Private banking clients and wealth management divisions of universal banks generate advisory service demand in Zurich and Geneva. Swiss FINMA licensing creates regulatory certainty for institutional custodial providers. The Crypto Valley cluster in Zug concentrates blockchain-native fund administration and tokenization infrastructure.
Singapore
Family office migration from Hong Kong and mainland China accelerates capital deployment into tokenized strategies. The Monetary Authority of Singapore's regulatory sandbox permits pilot programs for DeFi-native portfolio management. Marina Bay financial district hosts specialized administrators bundling tax, custody, and reporting functions.
Germany
Institutional investors and corporate treasuries seek compliant exposure through BaFin-licensed special funds. The EU's MiCA framework enables passporting across member states from Frankfurt and Berlin hubs. Bavarian and Baden-Württemberg industrial family offices lead adoption of multi-signature custody protocols.
United Kingdom
Hedge funds and registered investment advisers require prime brokerage integration with real-time blockchain reconciliation. The FCA's evolving stance on staking-as-a-service creates product fragmentation versus US structures. London's fintech corridor concentrates middleware development for legacy portfolio accounting integration.
Crypto Asset Management Market Key Industry Players
Premium-margin players sit above commodity-margin players across custody infrastructure and compliance automation capabilities. The market structure consolidates around specialized custodians with insurance-backed cold storage and undifferentiated retail wallet providers facing compression. Three archetypes dominate: ETF infrastructure specialists, early-stage token strategists, and integrated exchange-custody platforms. Competitive moves center on MiCA licensing expansion and SOC 2 Type II attestation acquisition.
Within the institutional infrastructure tier, Grayscale Investments and Coinbase Global represent established regulatory licensure archetypes. Pantera Capital occupies a position exemplifying early-stage token strategy specialization. Galaxy Digital anchors the integrated financial services model spanning trading, custody, and advisory functions.
| Leading Market Players |
|---|
| Multicoin Capital |
| Paradigm |
| Grayscale Investments |
| MicroStrategy |
| Coinbase Global |
| Galaxy Digital |
| Polychain Capital |
| VanEck |
| Pantera Capital |
| Others |
Cost & Logistics Intelligence
Cold-storage infrastructure costs cascade through custody fee tiers, with hardware security module procurement and Lloyd's syndicate insurance premiums anchoring premium pricing for pension funds while compressing margins for undifferentiated retail wallet providers.
Pricing Analysis
AUM-based fee structures with performance overlays dominate institutional mandates, with custody providers differentiating through SOC 2 Type II attestation grade and bankruptcy-remote structural protections. Price compression runs through the retail tier as exchange-integrated wallets compete on trading fee subsidies. Pension consultants exhibit lowest price sensitivity, prioritizing insurance-backed safekeeping over basis point optimization. Family offices occupy the middle tier, negotiating bundled tax-engineering and custody packages.
Supply Chain Analysis
Hardware security module fabrication rests on semiconductor foundries concentrated in Taiwan, South Korea, and the United States, with specialized secure-element manufacturing tethered to European and Japanese component suppliers. Cryptographic engineering talent scarcity in Zurich, Singapore, and New York drives compensation inflation through the operational stack. Single-source vulnerability concentrates in qualified custodian licensing jurisdictions. Distribution runs through prime brokerage integrations and direct fund administrator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crypto asset management is becoming a vertical-integration race, with custody infrastructure and compliance automation representing the critical upstream and downstream levers players are consolidating to defend margin position.
For Market Incumbents: Cement regulatory licensure moats through MiCA passporting and SOC 2 Type II attestation acquisition before emerging neobank entrants achieve scale. Prioritize prime brokerage integration to lock in hedge fund manager workflows. Counter the threat of DeFi-native yield strategies by embedding smart-contract automation into proprietary rebalancing tools. For New Entrants and Emerging Players: Capture tax-engineering white space created by IRS and OECD reporting mandates, where specialized advisory units command recurring revenue with minimal balance-sheet intensity. Target single-family offices in Wyoming and South Dakota trust jurisdictions with embedded custody-and-reporting bundles. Lead with regulatory sandbox participation to accelerate product-market fit validation. For Investors and Strategic Acquirers: MiCA licensing completion by mid-tier custodial providers is the leading indicator that regulatory clarity is unlocking continental European AUM flows. Frame long-term viability around the 5-10 year transition from speculative token exposure to tokenized real-asset allocation. Prioritize acquisition targets with established Dublin or Luxembourg hubs and existing pension fund consultant relationships.| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Expansion | Enables cross-border passporting from Dublin and Luxembourg hubs into continental pension mandates. |
| SOC 2 Type II Attestation Acquisition | Meets minimum procurement threshold for defined-benefit plan due diligence requirements. |
| Prime Brokerage Integration | Locks in hedge fund and registered investment adviser operational workflows against competitor displacement. |
| Smart-Contract Automation Deployment | Reduces operational headcount for yield harvesting and rebalancing in DeFi-native strategies. |
| Tax-Engineering Service Launch | Captures high-margin recurring revenue from IRS and OECD compliance mandates. |
Research Approach
SEC filings, MiCA regulatory notices, and pension fund consultant databases formed the secondary backbone, supplemented by primary interviews with digital asset custody officers, regulatory affairs leads at custodial providers, pension fund investment committee members, and prime brokerage relationship managers. Bottom-up and top-down triangulation validated segment-level assumptions against blockchain explorer data and fund administrator AUM disclosures.
Bottom-up modeling aggregated individual custody provider capacity and licensed fund structures, while top-down analysis calibrated against macro flows into SEC-registered investment vehicles across the projection horizon. Segmentation dimensions included end-user wealth tier, service-type bundling intensity, technology automation level, and jurisdictional regulatory cluster. CAGRs derived from historical adoption curves in comparable alternative asset classes, adjusted for spot ETF approval pathway progression and institutional onboarding friction.
The model holds under sustained regulatory clarity conditions; deviation in SEC enforcement posture or MiCA implementation timing would shift institutional deployment velocity. Forecasts reflect assumptions around custody insurance capacity expansion and cryptographic engineering labor supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
Global Blockchain in Supply Chain Finance Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market