
 Digital Asset Transaction Market | 2026-2036
Digital Asset Transaction Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Asset Transaction Market Insights
Corporate treasury buyer concentration is expanding as publicly traded firms accumulate digital assets on their balance sheets. Strategy leverages its pioneering treasury reserve strategy to anchor market visibility for institutional entry. Coinbase Global sustains dominant custody and exchange infrastructure for enterprise-grade holdings. MARA Holdings competes through vertical integration into mining operations that generate self-custodied Bitcoin reserves.
Digital asset transactions encompass the cryptographic transfer of value across distributed ledger networks, validated through consensus mechanisms requiring private-key signatures and on-chain settlement finality. These transactions serve commercial purposes ranging from cross-border remittance to programmable financial contracts. The platform type dimension shows centralized exchanges still capturing the deepest liquidity pools for institutional block trades, while non-custodial services attract users prioritizing self-sovereign key management. Within transaction types, smart contract execution represents the fastest-growing category as programmable settlement automates escrow, lending, and derivatives clearing without intermediary counterparty risk.
The SEC, FASB, and OCC collectively shape US market architecture through ETF approval frameworks, fair-value accounting standards, and bank custody guidance respectively. MiCA in Europe imposes reserve-backing and consumer-protection obligations on stablecoin issuers and exchange operators, creating a compliance moat that favors well-capitalized platforms. Stakeholders must monitor how jurisdictional regulatory divergence affects cross-border settlement rails and institutional onboarding friction.
Market Dynamics
Institutional treasury departments are reallocating corporate reserves into programmable settlement rails, compressing settlement latency from T+2 banking cycles to deterministic block finality. This capital rotation from traditional custody to cryptographic self-custody protocols is restructuring liquidity provision across exchange and non-custodial infrastructure.
Growth Catalysts
- FASB Fair-Value Accounting:The US accounting standard now permits mark-to-market treatment of digital assets, eliminating impairment-only recognition that previously discouraged corporate accumulation.
- Smart Contract Programmability:Automated escrow, lending, and derivatives clearing execute without intermediary counterparty risk, compressing operational overhead for institutional treasuries.
- Spot ETF Approval Framework:The SEC's evolving stance on exchange-traded products creates regulated on-ramps for pension and endowment capital previously excluded from direct custody.
Market Restraints
- Energy Input Volatility:Proof-of-work settlement consumes electricity at scales tied to regional grid pricing, exposing transaction cost bases to hydrocarbon and renewable tariff fluctuations.
- Key Custody Concentration:Enterprise-grade hardware security module production clusters in East Asian semiconductor foundries, creating single-source dependency for institutional cold-storage infrastructure.
- Cross-Border Regulatory Friction:Divergent stablecoin reserve-backing requirements between US OCC guidance and EU MiCA obligations fragment liquidity pools and complicate multi-jurisdictional treasury operations.
Strategic Opportunities
- Programmable Central Bank Currency Integration:Wholesale CBDC settlement rails under development at the Federal Reserve and European Central Bank will interface with private distributed ledger networks, creating interoperability infrastructure demand.
- Tokenized Real-Asset Collateral:Commercial real estate and commodity inventory representation on-chain unlocks fractional liquidity for previously illiquid balance-sheet holdings.
- Non-Custodial Wallet Distribution:Mobile-first key management applications bypass traditional exchange onboarding friction, penetrating underbanked demographics in Sub-Saharan African and Southeast Asian corridors.
Industry Challenges
- Cryptographic Talent Scarcity:Zero-knowledge proof engineering and formal verification expertise commands premium compensation, constraining protocol security audit capacity.
- Legacy Core Banking Integration:Mainframe-era treasury management systems require middleware development to recognize on-chain balances, delaying institutional deployment timelines.
- Cross-Chain Settlement Finality:Bridging assets between incompatible consensus mechanisms introduces smart contract exploit vectors that have absorbed significant institutional capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Asset Transaction Market |
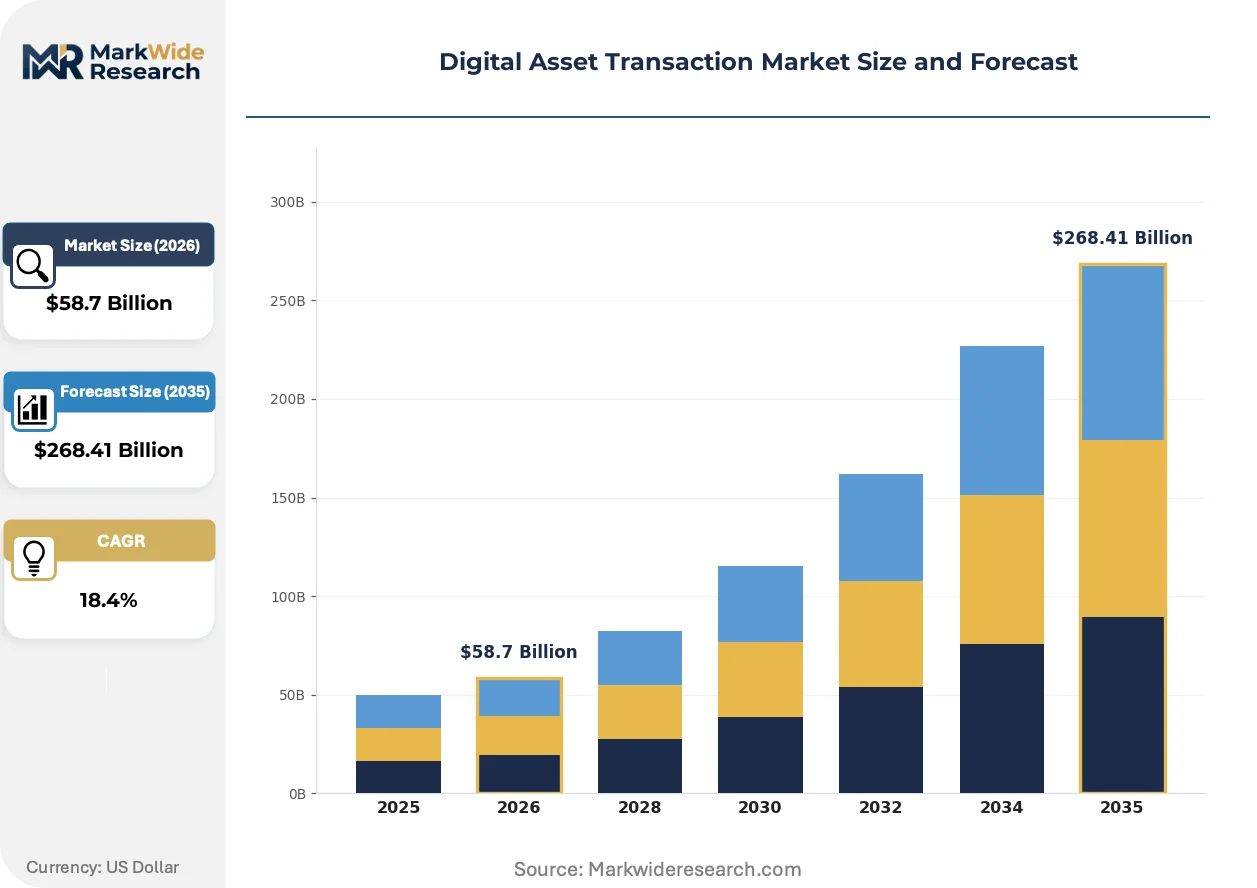
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $268.41 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Cryptocurrency Transfer, Token Exchange, Smart Contract Execution, Digital Wallet Payment, Asset Lending Platform Type: Decentralized Exchange, Centralized Exchange, Peer-to-Peer Network, Custodial Service, Non-Custodial Service End User: Retail Traders, Institutional Investors, Payment Processors, Technology Providers, Asset Managers Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, API Integration, SaaS |
| Companies Covered | Strategy, MARA Holdings, Metaplanet, Riot Platforms, Coinbase Global, CleanSpark, Semler Scientific, Bullish, SharpLink Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Asset Transaction Market Trends and Innovations
Settlement infrastructure is bifurcating between regulated custody layers and permissionless execution environments, with institutional capital demanding compliance wrappers around programmatic financial contracts. This architectural tension is driving innovation in verifiable computation and identity attestation protocols.
Account abstraction standards are absorbing the complexity of private-key management into smart contract wallets that execute multi-signature policies and social recovery mechanisms. Corporate treasury teams at publicly traded firms are adopting these programmable custody structures to replicate board-level authorization workflows on-chain. The technology is absorbing operational security overhead previously borne by dedicated custody departments, compressing headcount requirements for digital asset operations.
MiCA's reserve-backing mandates and consumer-protection obligations impose capital and compliance burdens on stablecoin issuers and exchange operators across European Union member states. The regulation forces operational separation between proprietary trading and custody functions, mirroring traditional securities market structure. EU-domiciled platforms are responding by relocating execution infrastructure to compliant jurisdictions while maintaining liquidity access through bilateral agreements.
Treasury procurement of settlement infrastructure now emphasizes API-first integration over standalone platform adoption, with finance teams demanding direct ERP connectivity. This specification is displacing multi-step reconciliation workflows that previously required manual intervention between blockchain explorers and accounting systems. The shift is most visible in North American corporate adopters, where MicroStrategy-style balance-sheet diversification has created template demand for automated cost-basis tracking and tax-lot optimization.
Digital Asset Transaction Market Segmentation
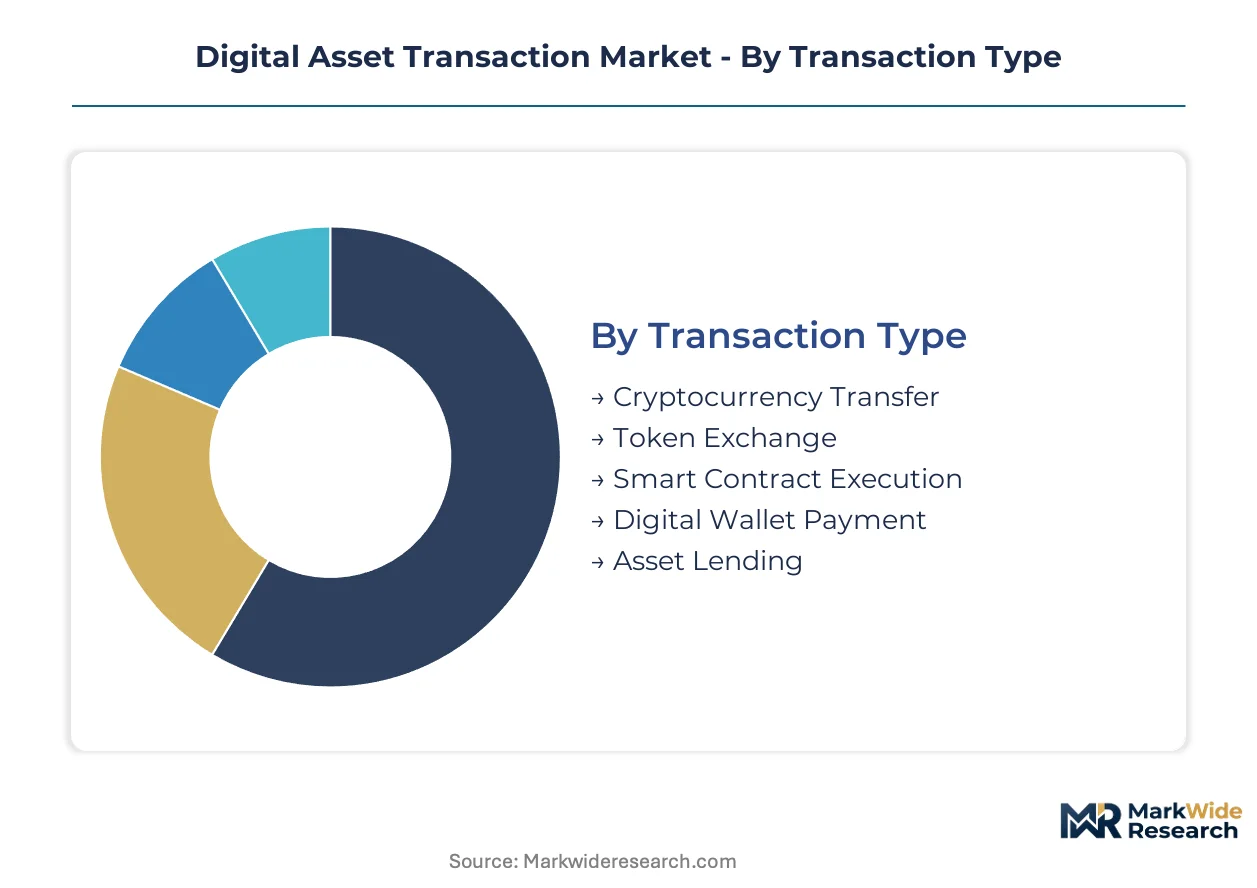
Digital asset transaction markets fragment across multiple operational dimensions, each carrying distinct capital requirements and compliance burdens. Treasury departments at publicly traded firms prioritize platform reliability and audit trails when selecting infrastructure, while retail participants weight accessibility and fee structures.
Transaction Type:
Capital intensity varies sharply across settlement mechanisms, with smart contract infrastructure demanding specialized engineering talent and formal verification auditing.
- Cryptocurrency Transfer:Native layer-one settlement of Bitcoin, Ethereum, and alternative base-layer assets requires node infrastructure and mempool monitoring. Demand concentrates among corporate treasuries in the United States seeking balance-sheet diversification, constrained by FASB fair-value accounting implementation costs.
- Smart Contract Execution:Programmable settlement automates escrow, lending, and derivatives clearing through deterministic code execution. Asset managers in the United States drive adoption for automated treasury operations, though formal verification and audit expenses elevate deployment costs.
- Token Exchange:Cross-asset swaps rely on automated market maker curves and order book matching engines.
- Digital Wallet Payment:Point-of-sale cryptographic settlement enables merchant acceptance without intermediary acquirers.
- Asset Lending:Collateralized borrowing protocols generate yield on dormant treasury holdings.
Cryptocurrency Transfer absorbs the bulk of installed capacity; Smart Contract Execution is expanding most quickly.
Platform Type:
Customer risk tolerance determines platform selection, with institutional capital gravitating toward regulated custody layers and retail users accepting self-custody trade-offs.
- Centralized Exchange:Order-matching engines and custodial wallets operated by licensed entities provide deep liquidity and fiat on-ramps. Institutional Investors in the United States dominate flow, drawn by SEC-registered custody and insurance-backed cold storage.
- Decentralized Exchange:Non-custodial automated market makers execute trades through smart contracts without intermediary control. Retail Traders across Southeast Asian corridors favor permissionless access, though slippage and MEV extraction erode execution quality.
- Peer-to-Peer Network:Bilateral settlement without platform intermediation relies on reputation systems and escrow smart contracts.
- Custodial Service:Third-party key management replicates traditional safekeeping for corporate treasuries.
- Non-Custodial Service:Self-hosted wallet infrastructure preserves user sovereignty over private keys.
Centralized Exchange commands the largest transaction volume; Decentralized Exchange is climbing the fastest.
End User:
Procurement sophistication separates segments, with enterprise buyers demanding API-first integration and individual users prioritizing mobile accessibility.
- Institutional Investors:Pension funds, endowments, and corporate treasuries deploy capital through regulated custody and over-the-counter desks. United States-based entities lead allocation, propelled by spot ETF approval frameworks and FASB accounting clarity.
- Retail Traders:Individual speculators and payment users access markets through consumer-facing applications. Demand clusters in Sub-Saharan African remittance corridors and Southeast Asian underbanked populations, driven by mobile-first onboarding.
- Payment Processors:Merchant acquirers integrate cryptographic settlement into existing checkout flows.
- Technology Providers:Infrastructure builders supply node services, indexing, and developer tooling.
- Asset Managers:Fund operators construct diversified digital asset portfolios for external capital.
Institutional Investors anchor infrastructure investment; Retail Traders are gaining share fastest.
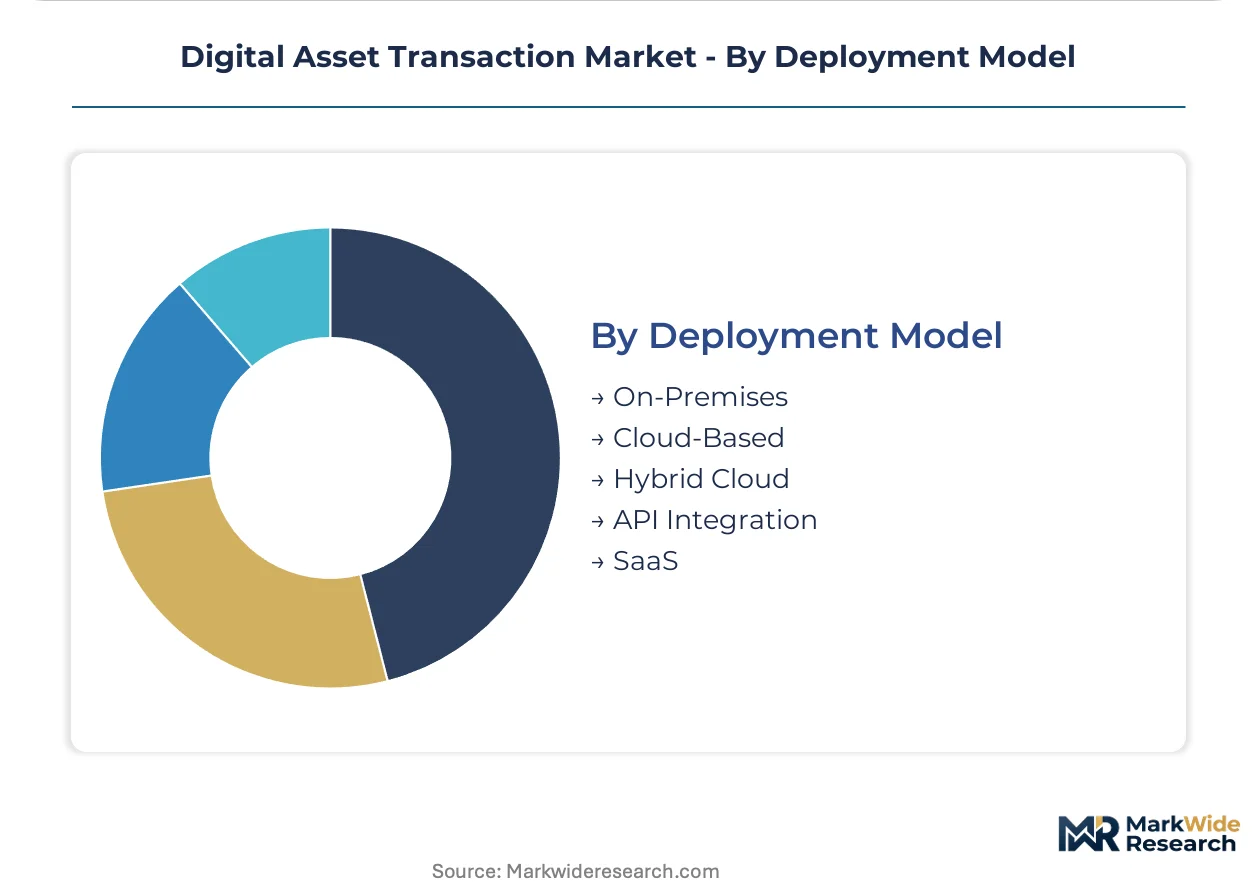
Deployment Model:
Integration complexity drives model selection, with legacy treasury systems requiring hybrid architectures to recognize on-chain balances.
- Cloud-Based:Hosted infrastructure eliminates capital expenditure on hardware and operational security staffing. Payment Processors in the United States favor elastic scaling for transaction volume spikes, though data residency requirements complicate multi-jurisdictional deployment.
- API Integration:Direct connectivity into ERP and treasury management systems automates reconciliation and cost-basis tracking. Technology Providers serving North American corporate adopters emphasize SAP and Oracle connector development.
- On-Premises:Self-managed hardware security modules and node infrastructure for maximum control.
- Hybrid Cloud:Segregated hot-wallet operations in cloud environments with cold-storage air gaps.
- SaaS:Subscription-based access to pre-configured trading and custody workflows.
Cloud-Based deployments hold the majority of new implementations; API Integration is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate treasury departments in the United States drive the dominant share of institutional capital deployment into digital asset infrastructure. Demand concentrates where regulatory clarity intersects with developed custody and exchange ecosystems.
United States
Publicly traded firms accumulate Bitcoin reserves through regulated custody frameworks, with Strategy establishing the template for balance-sheet diversification. The SEC's evolving spot ETF approval process and FASB fair-value accounting standards shape institutional entry. New York and Miami host concentrated exchange and custody operations serving enterprise treasuries.
Germany
Institutional investors access digital assets through BaFin-regulated crypto custody licenses and Spezialfonds structures. MiCA implementation imposes reserve-backing obligations on stablecoin issuers and operational separation between trading and custody functions. Frankfurt anchors compliance-heavy infrastructure serving EU-domiciled pension and insurance capital.
Singapore
Family offices and wealth management platforms leverage the Monetary Authority of Singapore's licensing framework for digital payment token services. The Payment Services Act mandates capital requirements and consumer protection safeguards for exchange operators. The city-state's fintech corridor attracts regional treasury operations seeking regulatory certainty.
United Arab Emirates
Virtual asset service providers cluster under Dubai's VARA licensing regime and Abu Dhabi's FSRA framework for institutional custody. The central bank's guidance on dirham-backed stablecoins creates demand for compliant settlement infrastructure. Dubai International Financial Centre hosts concentrated exchange and custody operations serving Middle Eastern and African capital flows.
Japan
Corporate treasuries and asset managers operate within the Financial Services Agency's registration requirements for crypto asset exchange businesses. The amended Payment Services Act mandates cold storage ratios and segregation of customer assets. Tokyo's financial district maintains concentrated institutional custody infrastructure serving domestic insurance and trust bank capital.
Digital Asset Transaction Market Competitive Landscape
United States-based operators anchor the institutional custody and exchange tier; Asia-Pacific mining and holding specialists occupy a parallel capital-deployment vector. The competitive structure bifurcates between regulated financial infrastructure providers and vertically integrated treasury reserve accumulators. Two dominant archetypes emerge: exchange-custody platforms serving third-party institutional flows, and corporate treasury vehicles deploying proprietary balance-sheet capital into self-custodied reserves. Competitive moves concentrate on API-first ERP integration and geographic licensing expansion into MiCA-compliant jurisdictions.
Within the corporate treasury reserve archetype, Strategy and MARA Holdings exemplify divergent approaches to balance-sheet digital asset accumulation. Strategy occupies a position as the pioneering template for publicly traded corporate Bitcoin treasury strategy. MARA Holdings sits within the vertically integrated mining-to-holding model, generating self-custodied reserves through proprietary hash rate rather than market acquisition. Coinbase Global anchors the regulated exchange-custody tier, serving institutional capital that requires SEC-registered infrastructure and insurance-backed cold storage.
| Leading Market Players |
|---|
| Strategy |
| MARA Holdings |
| Metaplanet |
| Riot Platforms |
| Coinbase Global |
| CleanSpark |
| Semler Scientific |
| Bullish |
| SharpLink Gaming |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up custody infrastructure specialists concentrate ownership of enterprise-grade hardware security module production, compressing procurement leverage for exchange operators while enforcing disciplined SaaS pricing tiers across institutional client segments.
Pricing Analysis
High-volume retail transaction processing compresses per-unit margins to commodity levels, while institutional custody and API integration services sustain premium pricing through regulatory certification and insurance-backed cold storage. Three-tier pricing structure across premium, standard, and economy levels segments by compliance depth, with SOC-2 and ISO-27001 certification tiers commanding substantial uplifts. Pricing pressure stems from cloud-native entrants undercutting on infrastructure overhead. Retail traders exhibit highest price sensitivity, while corporate treasuries prioritize audit trails over fee minimization.
Supply Chain Analysis
Regional distribution centers for hardware security modules cluster in Taiwan, South Korea, and Japan, creating hub-and-spoke fulfillment patterns for institutional cold-storage deployments. Semiconductor fabrication for secure enclave chips draws from TSMC and Samsung foundry capacity, with specialized packaging resting on ASE and Amkor facilities. Single-source vulnerability concentrates in East Asian HSM component supply. Distribution runs through authorized reseller networks and direct OEM relationships for enterprise treasuries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmable settlement infrastructure is displacing legacy correspondent banking rails, with smart contract automation replacing T+2 reconciliation workflows for institutional treasury operations.
For Market Incumbents: Acquire formal verification engineering talent pools to defend against smart contract exploit vectors that have absorbed institutional capital. Prioritize MiCA-compliant licensing expansion into Frankfurt and Dublin to preempt regulatory arbitrage by emerging exchange operators. Vertical integration into self-custody hardware manufacturing reduces dependency on East Asian semiconductor foundries. For New Entrants and Emerging Players: The premium-to-economy pricing gap in institutional custody services creates entry space for API-first infrastructure providers targeting mid-market corporate treasuries. Underpenetrated Sub-Saharan African remittance corridors offer mobile-first wallet distribution opportunities with minimal incumbent saturation. Go-to-market through embedded finance partnerships with neobanks bypasses direct exchange licensing burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mining-to-holding operators in North American jurisdictions with stranded energy access and favorable grid interconnection policies. Long-term viability hinges on regulatory clarity persistence and institutional treasury allocation normalization. Monitor spot ETF flow velocity as inflection indicator for pension and endowment capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-First ERP Integration | SAP and Oracle connector development eliminates manual reconciliation for MicroStrategy-style corporate adopters. |
| MiCA Compliance Licensing | BaFin and ECB regulatory alignment secures access to EU-domiciled pension and insurance capital pools. |
| Formal Verification Investment | Zero-knowledge proof engineering capacity constrains protocol security audit supply for institutional deployment. |
| Hardware Security Module Manufacturing | Captive production of cold-storage infrastructure reduces single-source dependency on East Asian foundries. |
| Wholesale CBDC Interoperability | Federal Reserve and European Central Bank settlement rail integration positions for programmable currency infrastructure demand. |
Research Methodology
SEC filings, FASB accounting standards documentation, and MiCA regulatory texts formed the secondary backbone, supplemented by customs records of mining equipment imports and hyperscaler capex disclosures. Primary interviews with corporate treasury officers, crypto custody infrastructure engineers, and regulatory compliance leads at exchange operators combined with this documentary base. Bottom-up transaction volume modeling and top-down institutional allocation surveys were triangulated for convergence validation.
Historical trendline analysis of corporate balance-sheet accumulation patterns and exchange trading volumes established baseline growth trajectories across the projection horizon. Segmentation dimensions encompassed transaction type, platform architecture, end-user sophistication, and deployment model complexity. CAGRs were derived from regression analysis against institutional adoption curves and regulatory clarity indices, with inputs from mining difficulty adjustments and network hash rate expansion feeding supply-side constraints.
Inputs from exchange volume APIs and custody provider disclosures were available through the study window; gaps in proprietary treasury allocation data introduce uncertainty bands around institutional penetration forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market