
 Investor ESG Software Market | 2026-2036
Investor ESG Software Market Size, Share, and Industry Trends Forecast 2026-2036
Investor ESG Software Market Outlook
Buyer concentration among institutional asset owners is realigning competitive priorities across the vendor landscape. Sweep leverages carbon accounting automation to differentiate its platform for private equity workflows. Persefoni anchors its position through deep integration with ERP systems and emissions calculation engines. Watershed competes by extending its climate data infrastructure into supplier engagement tools for portfolio companies.
Investor ESG software encompasses platforms that aggregate environmental, social, and governance data to support portfolio construction, risk quantification, and regulatory disclosure for investment professionals. These systems ingest structured and unstructured data streams, apply standardized frameworks such as SASB and GRI, and generate auditable outputs for stakeholder reporting. Cloud-based deployment leads the solution architecture as fund administrators prioritize scalability and multi-tenant security models. Portfolio analytics within the solution category captures the fastest expansion as allocators integrate climate scenario stress-testing into due diligence workflows. Wealth management firms among end users represent a maturing segment with established procurement patterns, while hedge funds present emerging demand for real-time ESG signal integration.
The SEC climate disclosure framework and the EU's CSRD are reshaping product requirements by mandating granular emissions attribution and third-party assurance capabilities. The UK's FCA sustainable disclosure regime adds a third compliance layer for cross-border fund distribution. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether platform standardization or regional customization delivers superior competitive returns.
Market Dynamics
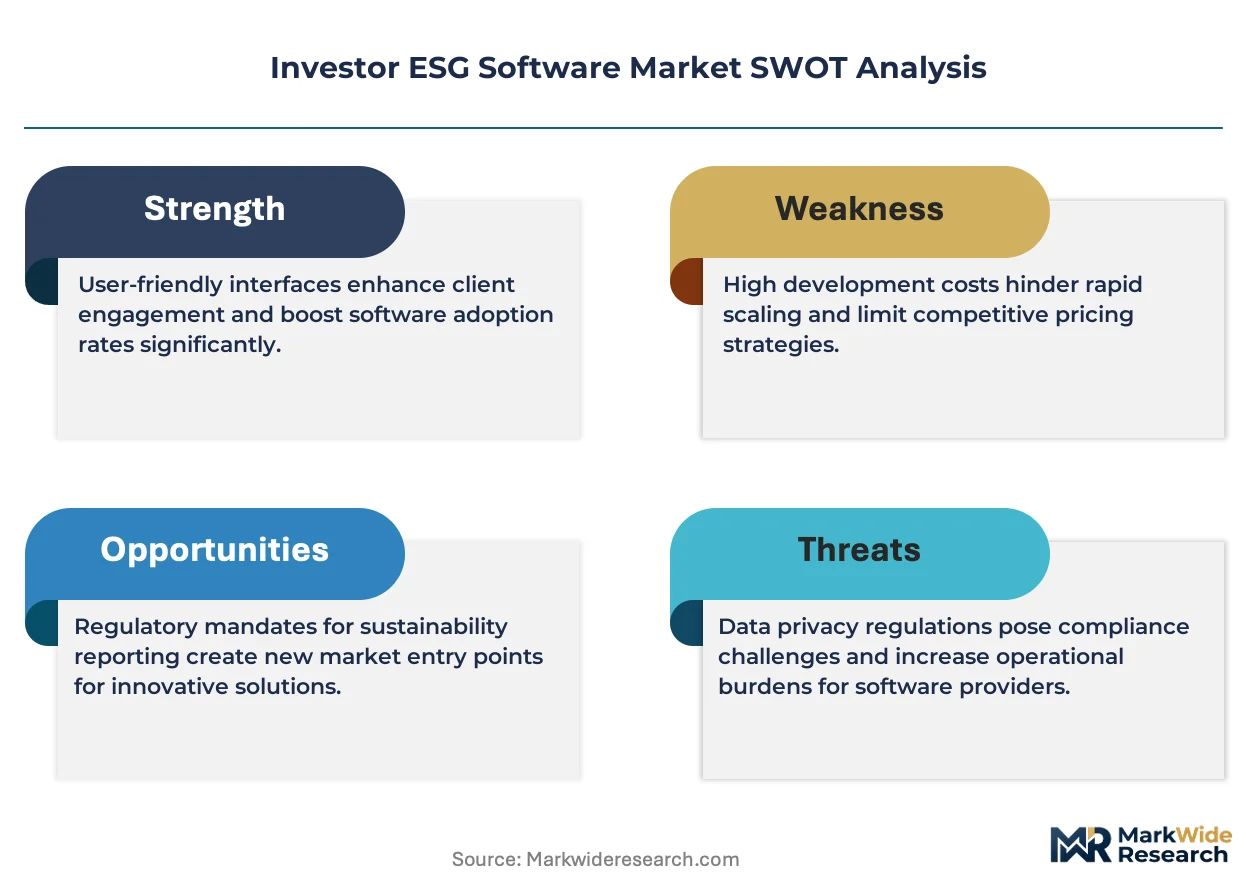
Regulatory disclosure mandates from the SEC, EU CSRD, and UK FCA are compressing procurement timelines as asset managers race to deploy auditable ESG infrastructure before enforcement deadlines.
Growth Catalysts
- CSRD Mandate Expansion:The EU's Corporate Sustainability Reporting Directive requires granular emissions attribution across portfolio holdings, forcing asset owners to upgrade from spreadsheet-based tracking to integrated platforms.
- Pension Fund Fiduciary Pressure:US state pension systems in California and New York are embedding climate risk metrics into investment policy statements, creating procurement urgency among their external managers.
- Cloud-Native Architecture:Multi-tenant SaaS deployment models reduce implementation friction for mid-sized allocators previously priced out of enterprise ESG systems.
Market Restraints
- Data Fragmentation Costs:Portfolio companies lack standardized emissions disclosure formats, forcing software vendors to absorb expensive data cleaning and gap-filling labor.
- Assurance Provider Concentration:The big four accounting firms control third-party verification capacity, creating bottlenecks for funds seeking CSRD-compliant attestation.
- Framework Proliferation:Competing standards from SASB, GRI, TCFD, and ISSB force vendors to maintain parallel calculation engines, inflating R&D overhead.
Strategic Opportunities
- Private Equity Workflow Automation:GP-led secondaries and continuation vehicles in North America need ESG due diligence tools purpose-built for hold-period monitoring and exit preparation.
- Scope 3 Supplier Engagement:Platforms that extend carbon accounting downstream to private company supply chains unlock recurring revenue from portfolio operations teams.
- UK FCA Sustainable Disclosure Regime:Cross-border fund distributors face labeling requirements that create demand for automated product classification and consumer-facing disclosure generation.
Industry Challenges
- Climate Scenario Modeling Talent Scarcity:Vendors struggle to hire quants capable of translating NGFS transition pathways into portfolio-level stress tests.
- Legacy System Integration Complexity:Asset servicers running decades-old portfolio accounting software require expensive API middleware to ingest ESG data streams.
- Assurance Timeline Compression:CSRD's phased implementation demands that platforms deliver audit-ready outputs before accounting firms have finalized their verification methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Investor ESG Software Market |
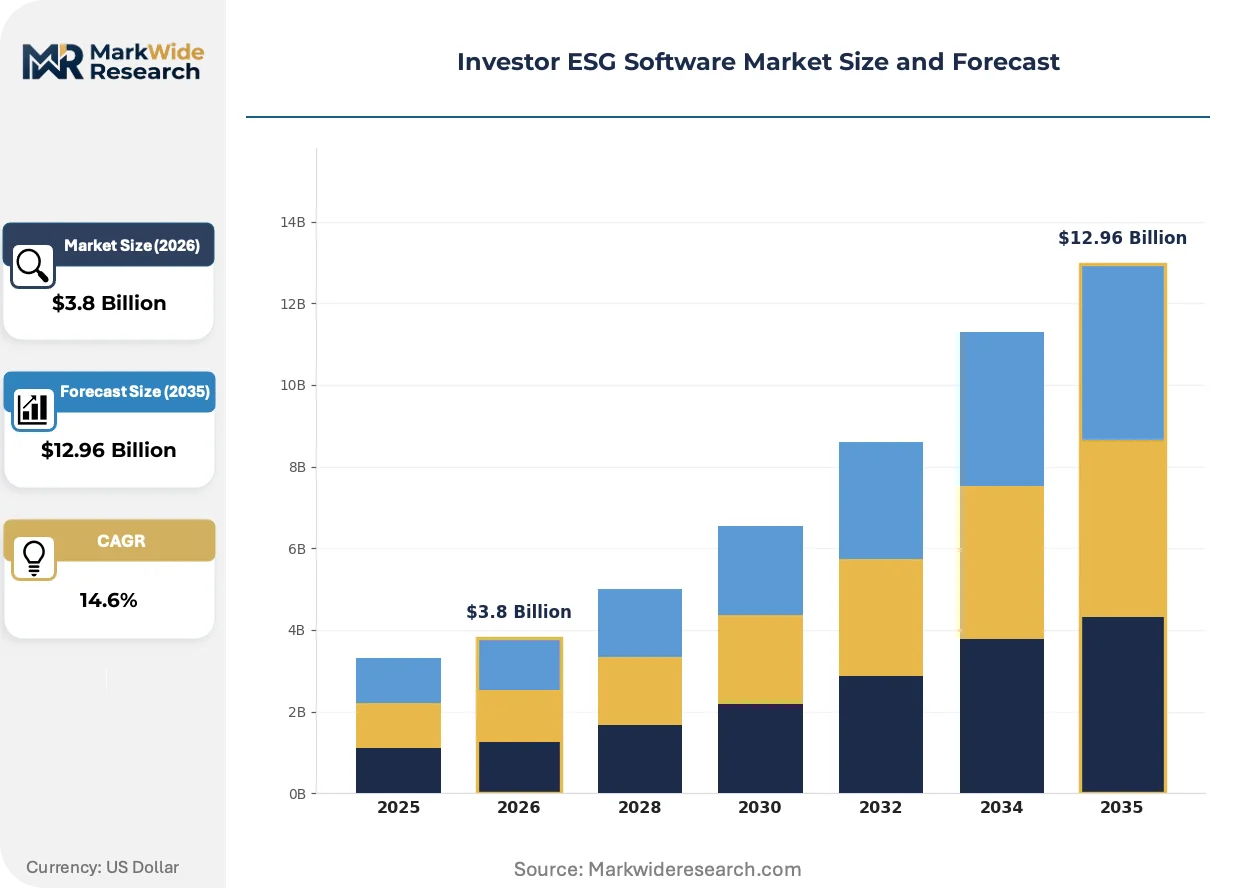
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, SaaS Customer Type: Institutional Investors, Retail Investors, Fund Managers, Asset Allocators Solution: Portfolio Management, Reporting Tools, Analytics, Risk Assessment End User: Financial Advisors, Wealth Management Firms, Hedge Funds, Private Equity |
| Companies Covered | Workiva, Greenly, Sweep, IBM Environmental Intelligence Suite, Microsoft Sustainability Cloud, Persefoni, Novata, Navex One, Watershed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Investor ESG Software Market Strategic Shifts
Artificial intelligence is reshaping how ESG platforms process unstructured disclosures, while regulatory divergence between jurisdictions forces modular product architectures.
Natural language processing is expanding into automated extraction of ESG risk signals from earnings calls, regulatory filings, and news archives. Sovereign wealth funds in Singapore and Norway are deploying these tools for real-time monitoring of geopolitical exposures in emerging market debt portfolios. The technology is expanding into private credit workflows where traditional data coverage remains sparse.
The EU CSRD's double materiality requirement is mandating that platforms calculate both financial impact on the enterprise and enterprise impact on sustainability outcomes. This is forcing vendors to rebuild their data models around stakeholder-specific disclosure boundaries rather than single-issuer profiles. Asset managers with EU-domiciled funds are prioritizing platforms with built-in materiality assessment workflows.
Buy-side procurement teams are consolidating vendor relationships by demanding that ESG platforms integrate directly with existing portfolio management systems rather than operating as standalone overlays. This is displacing point solutions that require manual data exports and reconciliation. The shift is most visible among US mutual fund complexes seeking to reduce operational risk and vendor management overhead.
Investor ESG Software Market Segmentation
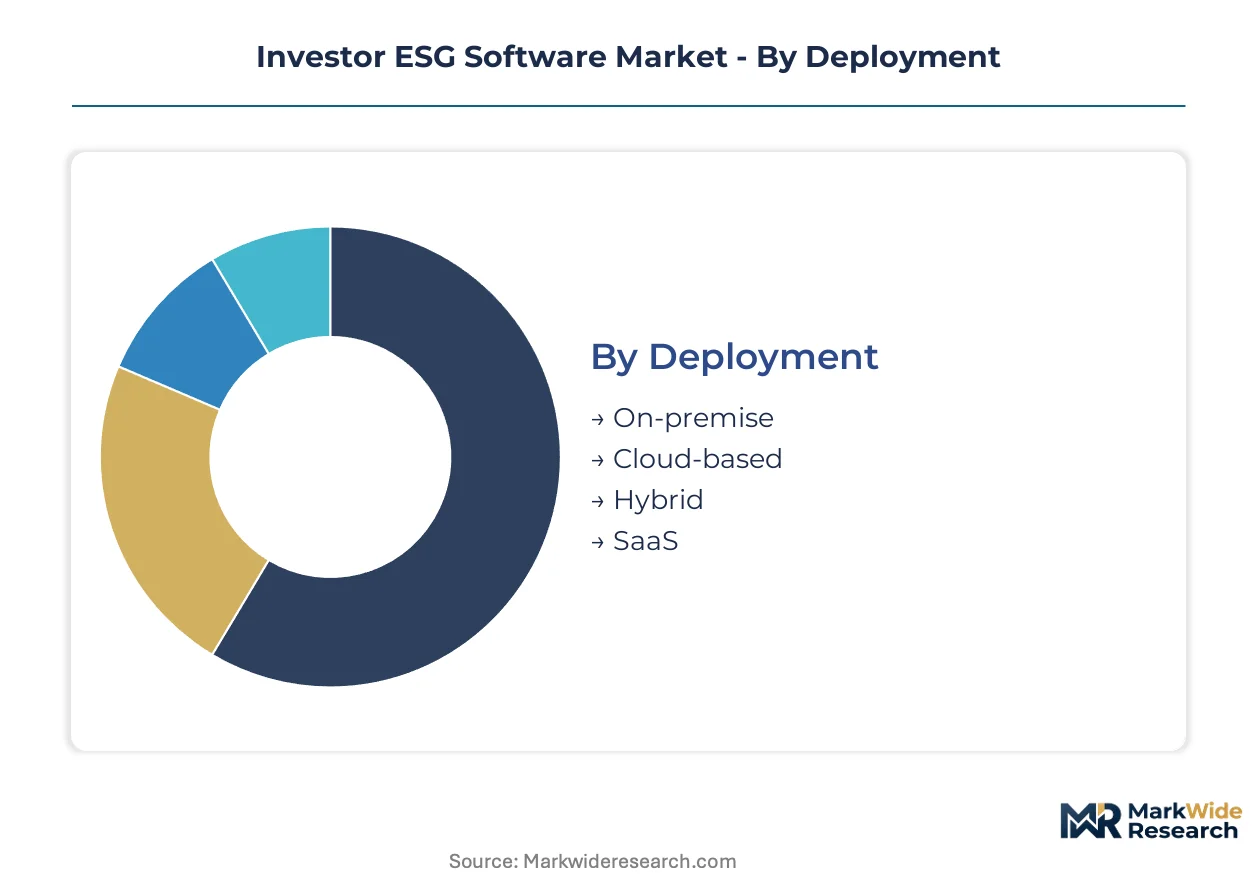
Deployment architecture determines upfront infrastructure spend and ongoing operational overhead for ESG data platforms. Customer sophistication shapes feature requirements across institutional and retail channels. Solution depth and end-user workflow integration complete the segmentation map for vendor positioning.
Deployment:
Capital intensity varies sharply across deployment modes, with on-premise installations demanding the heaviest upfront server and security infrastructure investment.
- Cloud-based:Multi-tenant SaaS architectures eliminate capital expenditure for hardware provisioning while enabling elastic scaling during quarterly reporting peaks. Asset managers in the United States and Germany are consolidating procurement around these models to compress implementation timelines ahead of SEC and CSRD enforcement deadlines.
- SaaS:Subscription pricing aligns vendor revenue with client reporting cycles, reducing procurement friction for mid-sized allocators previously priced out of enterprise systems. The delivery model concentrates demand among fund administrators seeking rapid deployment without dedicated IT staffing.
- On-premise:Self-hosted installations persist among sovereign wealth funds with data sovereignty mandates.
- Hybrid:Split architectures accommodate sensitive portfolio data on local servers while leveraging cloud analytics for non-proprietary benchmarks.
Cloud-based deployments absorb the bulk of installed capacity; SaaS is expanding most quickly as procurement teams prioritize operational flexibility over capital control.
Customer Type:
Institutional scale drives per-seat pricing power and customization depth across the customer base.
- Institutional Investors:Pension systems and insurance conglomerates mandate granular emissions attribution across thousands of portfolio holdings, forcing platforms to integrate with legacy portfolio accounting systems. California and New York state pension funds are embedding climate risk metrics directly into investment policy statements.
- Fund Managers:Mutual fund complexes require automated regulatory filing generation to satisfy EU SFDR and UK FCA sustainable disclosure regimes simultaneously.
- Asset Allocators:Endowments and family offices prioritize scenario stress-testing tools for transition risk quantification.
- Retail Investors:Direct-to-consumer platforms emphasize simplified ESG scoring and impact visualization dashboards.
Institutional Investors command the largest aggregate contract values; Fund Managers are climbing the fastest as regulatory filing automation becomes non-negotiable.
Solution:
Functional depth separates workflow-integrated platforms from standalone reporting utilities.
- Analytics:Climate scenario modeling engines translate NGFS transition pathways into portfolio-level risk metrics, requiring specialized quant talent scarce across vendor engineering teams. Demand concentrates among private equity GPs preparing ESG due diligence for GP-led secondaries.
- Reporting Tools:Automated disclosure generation maps raw emissions data to SASB, GRI, and CSRD formats with third-party assurance readiness.
- Portfolio Management:ESG-integrated construction tools embed carbon intensity constraints directly into optimization workflows.
- Risk Assessment:Real-time monitoring systems flag controversy exposure and regulatory enforcement actions affecting issuer credit quality.
Analytics captures the steepest expansion trajectory as allocators integrate forward-looking climate stress tests; Reporting Tools retain the largest installed base from early compliance-focused procurement waves.
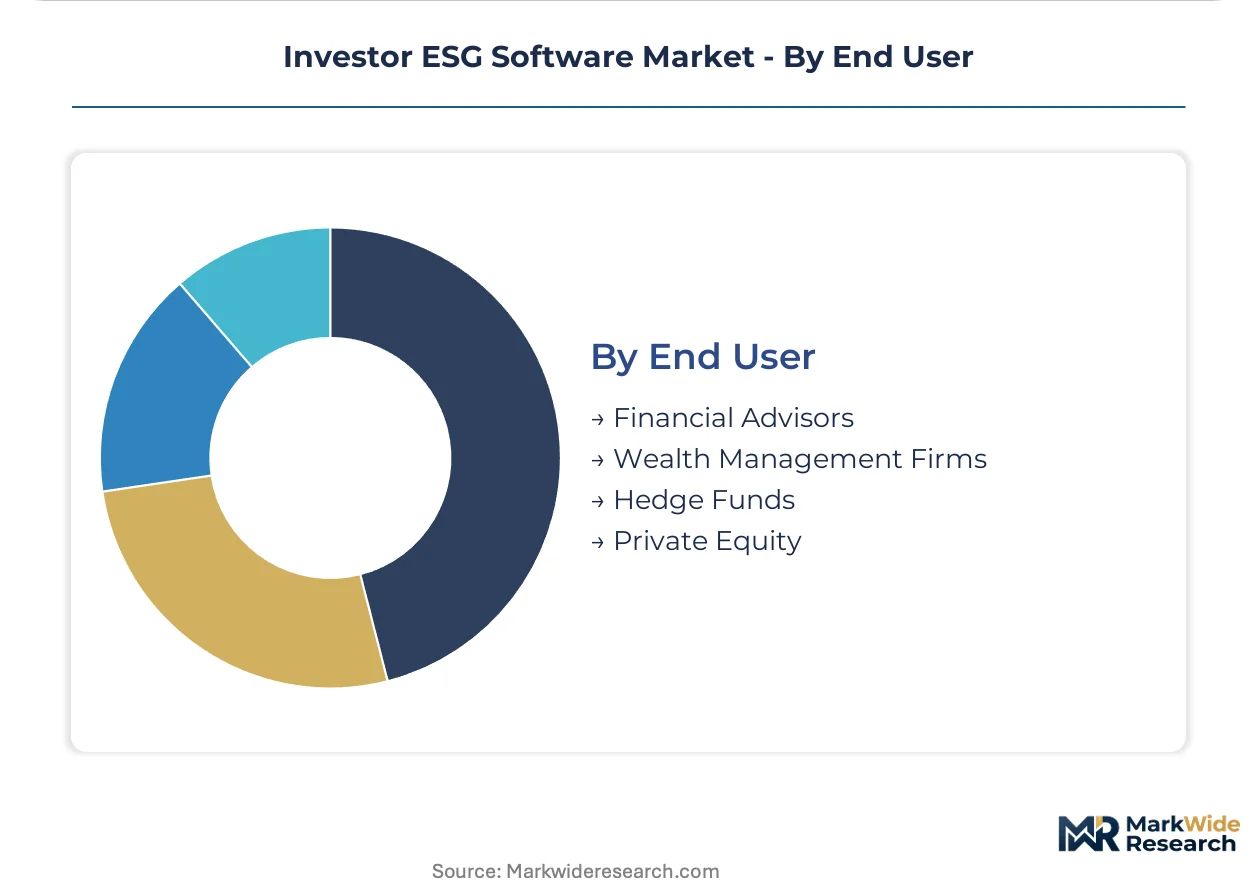
End User:
Workflow specificity determines whether platforms serve advisory relationships or direct investment execution.
- Private Equity:Hold-period monitoring and exit preparation tools require bespoke data collection from portfolio company management teams without standardized disclosure formats. North American buyout funds are deploying these capabilities for continuation vehicles and secondaries.
- Hedge Funds:Real-time ESG signal integration into systematic strategies demands low-latency data feeds and alternative data fusion.
- Wealth Management Firms:Established procurement patterns favor platforms with CRM integration and client-facing impact reporting.
- Financial Advisors:Simplified product classification tools automate UK FCA and EU SFDR label assignment for fund distribution.
Private Equity is gaining share fastest as GP-led transaction volume expands; Wealth Management Firms anchor the largest segment of mature, renewing contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial data infrastructure clusters in jurisdictions with the most stringent disclosure mandates. Regulatory enforcement timelines in the United States, Germany, and the United Kingdom are compressing procurement cycles for ESG analytics platforms.
United States
Asset managers in New York and Boston are racing to deploy auditable emissions tracking ahead of SEC climate disclosure enforcement. California's state pension systems have embedded climate risk metrics into investment policy statements, forcing external managers to upgrade ESG infrastructure. The San Francisco Bay Area hosts a concentration of SaaS vendors developing carbon accounting automation for private equity workflows.
Germany
Frankfurt-based fund administrators are consolidating procurement around cloud-native platforms to meet CSRD's granular emissions attribution requirements. The Bundesbank has signaled climate stress-testing expectations for domestic insurers, accelerating demand for scenario modeling tools. Munich's insurance conglomerates are mandating Scope 3 supplier engagement capabilities across their asset management subsidiaries.
United Kingdom
London asset servicers face overlapping compliance obligations from the FCA sustainable disclosure regime and EU SFDR for cross-border fund distribution. The City's wealth management firms are prioritizing platforms with automated product classification for consumer-facing labels. Edinburgh's pension funds are integrating ESG analytics directly into legacy portfolio accounting systems.
France
Parisian asset managers are rebuilding data models around CSRD's double materiality requirement, calculating both financial impact and sustainability outcomes. The Autorité des Marchés Financiers has tightened expectations for third-party assurance readiness. La Défense hosts a cluster of vendors developing materiality assessment workflows for EU-domiciled funds.
Singapore
Sovereign wealth funds in Singapore are deploying natural language processing tools for real-time geopolitical risk monitoring in emerging market debt. The Monetary Authority of Singapore has issued sustainable finance disclosure guidelines that align with ISSB standards. Local fintech clusters are developing alternative data fusion capabilities for private credit workflows where traditional ESG coverage remains sparse.
Investor ESG Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue carbon accounting automation and supplier engagement extensions. The vendor landscape stratifies between enterprise incumbents with ERP integration depth and specialized challengers with workflow-specific tooling. Three archetypes dominate: legacy software platforms with sustainability modules, pure-play carbon accounting specialists, and climate data infrastructure providers extending into portfolio analytics. Competitive moves center on API middleware development for legacy system integration and strategic partnerships with assurance providers to compress attestation timelines.
Among pure-play specialists, Sweep, Persefoni, and Watershed occupy positions exemplifying divergent strategic vectors. Sweep represents the carbon accounting automation archetype purpose-built for private equity hold-period monitoring. Persefoni anchors the ERP-integrated tier through emissions calculation engines designed for enterprise resource planning connectivity. Watershed sits within the climate data infrastructure category, extending downstream into supplier engagement tools for portfolio company operations teams. These three exemplify how vendors are carving defensible positions through workflow specificity rather than horizontal platform breadth.
| Leading Market Players |
|---|
| Workiva |
| Greenly |
| Sweep |
| IBM Environmental Intelligence Suite |
| Microsoft Sustainability Cloud |
| Persefoni |
| Novata |
| Navex One |
| Watershed |
| Others |
Value Chain & Pricing Dynamics
Cloud compute pricing indices from AWS, Azure, and Google Cloud Platform cascade through ESG software vendor cost structures, compressing margins for mid-tier SaaS providers while enabling premium pricing for platforms with proprietary emissions calculation engines. The divergence between hyperscaler infrastructure costs and specialized carbon accounting IP creates three distinct pricing tiers across the vendor landscape.
Pricing Analysis
Third-party assurance bundling separates premium tiers from standard offerings, with CSRD-compliant attestation packages commanding substantial uplifts over base subscription rates. Pricing stratifies across premium, standard, and economy tiers based on integration depth with ERP systems and granularity of Scope 3 supplier engagement tools. Cost compression in the mid-market tier is intensifying as fund administrators consolidate vendor relationships and demand consolidated platform pricing. Family offices and smaller allocators exhibit the highest price sensitivity, while sovereign wealth funds and large pension systems prioritize functionality over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with the big four accounting firms' control over third-party verification capacity, creating bottlenecks for funds seeking CSRD-compliant attestation. Engineering talent concentrates in the United States, Germany, and the United Kingdom, where climate scenario modeling expertise commands premium compensation. Raw material dependencies include hyperscaler cloud infrastructure, alternative data feeds from satellite and IoT providers, and NLP training datasets from financial disclosure archives. Tariff exposure runs through cross-border data transfer regulations affecting EU-US data flows. Distribution runs through direct enterprise sales teams for institutional contracts and channel partnerships with fund administrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Investor ESG software market has become a vertical-integration race, with vendors pursuing backward integration into alternative data collection and upstream control over assurance provider relationships to defend margin position.
For Market Incumbents: Hedge against pure-play carbon accounting specialists by acquiring API middleware capabilities for legacy portfolio accounting system integration. Prioritize certification investment in ISSB-aligned disclosure frameworks before the SEC finalizes climate rule enforcement. Channel control through exclusive partnerships with the big four accounting firms creates defensive moats around attestation-ready output generation. For New Entrants and Emerging Players: Mid-sized private equity firms with GP-led secondaries exposure represent the most penetrable buyer archetype, as these allocators lack dedicated ESG infrastructure but face imminent CSRD compliance deadlines. Target North American buyout funds deploying continuation vehicles with purpose-built hold-period monitoring tools. A direct sales motion emphasizing rapid implementation timelines without dedicated IT staffing unlocks procurement decisions. For Investors and Strategic Acquirers: Distressed-cycle entries favor climate data infrastructure providers with existing supplier engagement tool deployments in the United States and Germany, where regulatory enforcement timelines are compressing procurement cycles. Long-term viability hinges on platform consolidation around workflow-integrated architectures rather than standalone reporting utilities. Monitor CSRD assurance methodology finalization from the big four as the critical inflection signal for vendor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Assurance Provider Partnership | Exclusive attestation relationships with Deloitte or PwC compress CSRD compliance timelines for asset managers. |
| ERP Integration Depth | Native SAP and Oracle connectivity displaces point solutions requiring manual data reconciliation workflows. |
| Alternative Data Acquisition | Satellite emissions monitoring and IoT sensor networks differentiate carbon accounting accuracy for private equity. |
| Geographic Expansion | Singapore and Tokyo offices capture sovereign wealth fund demand for geopolitical risk monitoring in emerging markets. |
| Workflow Automation | GP-led secondaries tooling automates ESG due diligence for continuation vehicles and exit preparation processes. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with ESG platform product managers, institutional asset owner procurement leads, carbon accounting engineers, and assurance provider sustainability partners. SEC climate disclosure drafts, EU CSRD implementation guidance, UK FCA sustainable disclosure rules, and fund administrator RFP databases provided regulatory and demand-side validation. Bottom-up vendor revenue estimates triangulated against top-down addressable market calculations derived from pension fund AUM and ESG integration penetration rates.
Granularity-level modeling deployed deployment architecture, customer type, solution depth, and end-user workflow as primary segmentation dimensions across the analysis window. CAGRs were derived from regression analysis against regulatory enforcement timelines and institutional procurement cycle data. Forecast inputs included CSRD phased implementation schedules, SEC climate rule litigation outcomes, and pension fund investment policy statement amendment velocity.
Revisions become necessary when regulatory divergence between jurisdictions accelerates, assurance provider capacity constraints intensify, or alternative data cost curves shift materially. Forecasts reflect documented assumptions regarding CSRD adoption rates and institutional allocator technology refresh cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market