
 Cold Brew Coffee Pots Market | 2026-2036
Cold Brew Coffee Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Brew Coffee Pots Market Insights
Specialty beverage retail is pivoting toward dedicated cold brew equipment as cafés replace improvised methods with purpose-built systems. OXO leverages its kitchen-tool heritage to compete in premium manual segments. Takeya anchors the North American market through mass retail channel control. Hario specializes in precision glass construction that appeals to craft coffee operators.
Cold brew coffee pots are vessels designed for extended steeping of coarse-ground coffee in cold or room-temperature water, typically over 12 to 24 hours, producing a concentrate with reduced acidity and distinct flavor profiles. Manual variants dominate household penetration due to lower price points and minimal maintenance requirements, while electric systems command margin pools in commercial settings where throughput and consistency carry operational weight. Stainless steel construction leads the material mix for durability and thermal properties, though glass retains share among consumers prioritizing visual brewing monitoring.
The US Food and Drug Administration oversees food-contact material safety for plastic components, while the EU REACH framework restricts hazardous substances in imported kitchenware, shaping material selection across supply chains. California Proposition 65 disclosure requirements add compliance layers for brands distributing in that state. Stakeholders must monitor evolving chemical safety thresholds and energy efficiency standards as regulatory divergence between jurisdictions intensifies product development complexity.
Market Dynamics
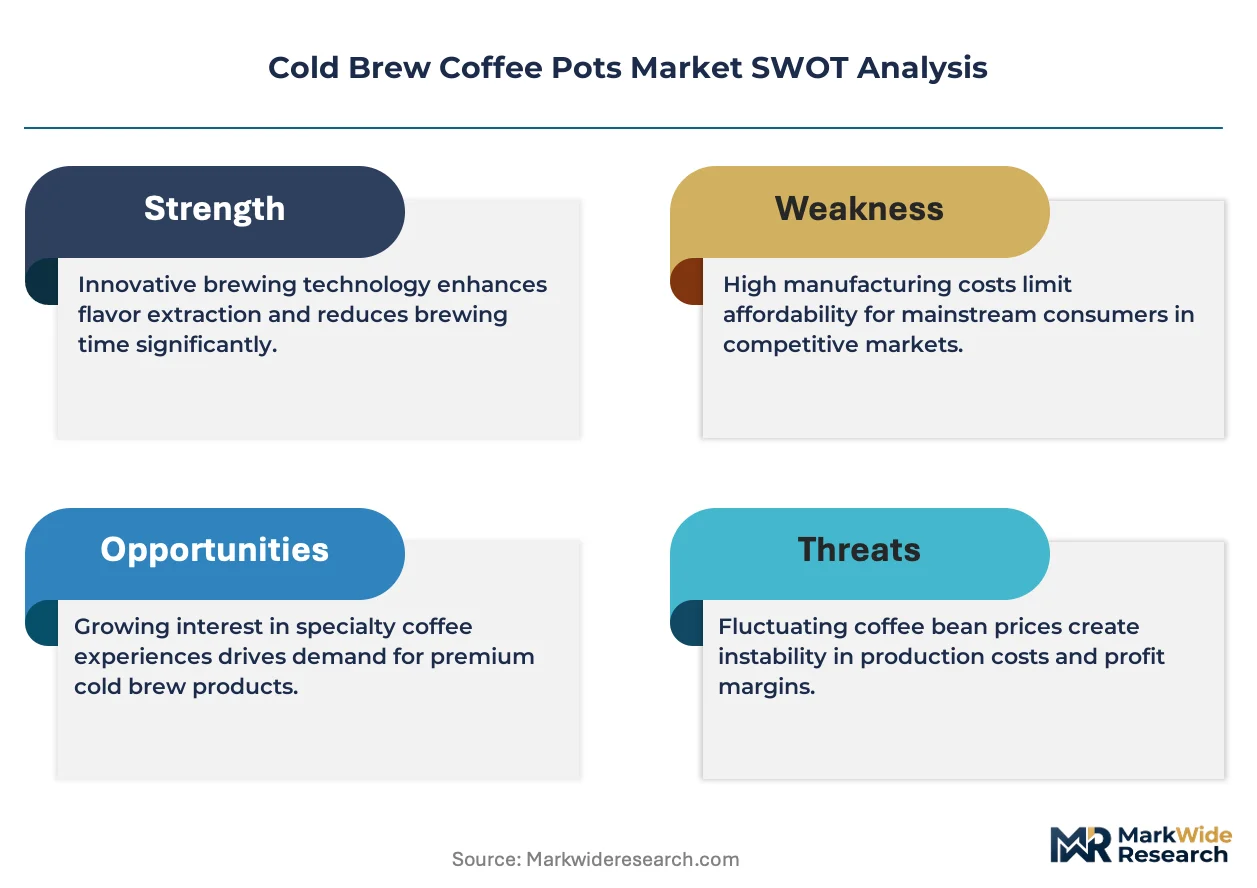
Specialty cafés are replacing improvised cold brew methods with purpose-built equipment, compressing equipment replacement cycles from five years to eighteen months as operators chase consistency and throughput advantages.
Growth Catalysts
- REACH chemical restrictions:The EU REACH framework restricts hazardous substances in imported kitchenware, pushing manufacturers toward glass and stainless steel construction that commands premium positioning.
- Third-wave coffee shop expansion:Specialty cafés across the United States are dedicating menu space to lower-acidity cold brew offerings, driving equipment procurement from manual vessels to automated systems.
- BPA-free mandates:Regulators in California and multiple jurisdictions enforce Proposition 65 disclosure requirements, accelerating material transitions away from polycarbonate components.
Market Restraints
- Stainless steel price volatility:Raw material input costs for 304-grade stainless fluctuate with nickel and chromium spot markets, compressing margin pools for mid-tier manufacturers.
- Supply concentration in Guangdong:Glass component sourcing clusters in southern Chinese manufacturing zones, exposing brands to logistics disruption and tariff exposure.
- Technical limitation in thermal extraction:Electric cold brew systems cannot achieve the flavor complexity of extended steeping, limiting penetration among craft coffee purists.
Strategic Opportunities
- Underpenetrated German households:Dedicated cold brew equipment penetration lags the United States by approximately sixty percentage points, creating whitespace for premium manual vessel launches.
- Regulatory tailwind from EU Green Deal:Circular economy packaging requirements favor durable glass and steel construction over disposable alternatives, aligning with cold brew pot material trends.
- Convergence of IoT sensors and brewing:Temperature and timing automation through connected devices enables subscription-based consumable bundling for electric system manufacturers.
Industry Challenges
- Food-contact certification timelines:FDA material safety approvals for new polymer alternatives extend eighteen to twenty-four months, delaying product launches.
- Skill gaps in cold extraction:Commercial operators lack trained staff for grind calibration and steep-time optimization, increasing support costs for equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Brew Coffee Pots Market |
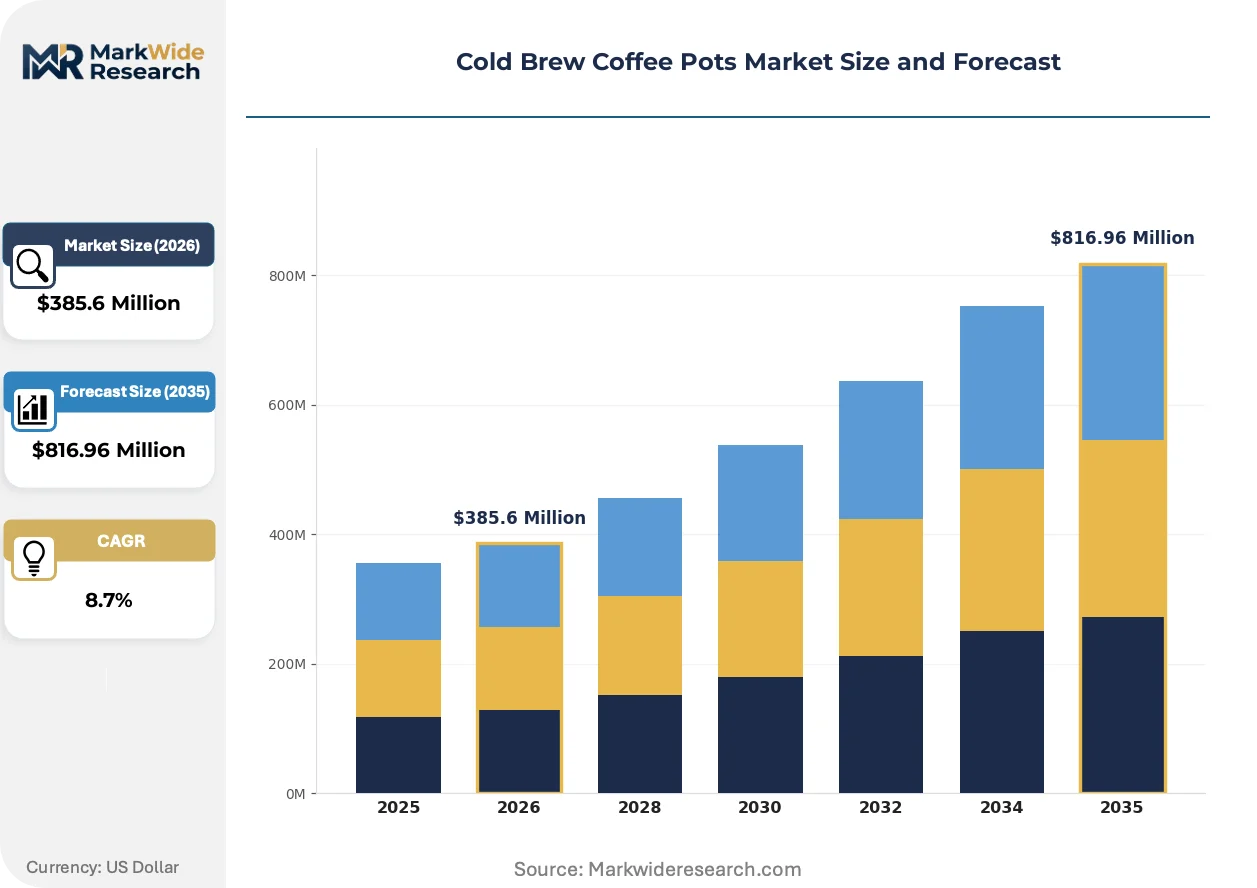
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Portable, Bulk Material: Glass, Stainless Steel, Plastic, Ceramic Capacity: 1L, 2L, 4L, 6L End User: Household, Cafés, Restaurants, Offices |
| Companies Covered | KitchenAid, OXO, Primula, Hario, Takeya, Coffee Gator, SharkNinja, Toddy, Cuisinart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Brew Coffee Pots Market Trends and Innovations
Equipment manufacturers are embedding precision controls into previously manual vessels, blurring the line between craft authenticity and operational consistency that cafés now demand.
Integrated heating elements within cold brew vessels are electrifying the extraction process, enabling temperature-accelerated brewing that compresses steep times from twenty-four hours to four hours. High-volume coffee chains in the United States are piloting these systems for overnight batch production. The technology is electrifying competitive positioning by allowing operators to maintain cold brew availability without dedicating refrigerator footprint to extended steeping vessels.
The EU F-Gas Regulation restricts fluorinated greenhouse gases in refrigeration equipment, indirectly pressuring cold brew system designers to improve thermal efficiency in concentrate storage units. Manufacturers serving European markets now prioritize vacuum-insulated stainless reservoirs over traditional glass carafes with separate cooling. Commercial operators in Germany and France face compliance deadlines that accelerate equipment refresh cycles.
Direct-to-consumer subscription models are displacing traditional retail channel dependence for premium cold brew pot brands. Specialty coffee enthusiasts in Australia and Canada now expect bundled offerings combining vessels with curated bean selections and brewing guides. This channel shift concentrates customer acquisition spending on digital platforms rather than mass retail slotting fees, favoring niche brands with authentic craft positioning over kitchenware conglomerates.
Cold Brew Coffee Pots Market Segmentation
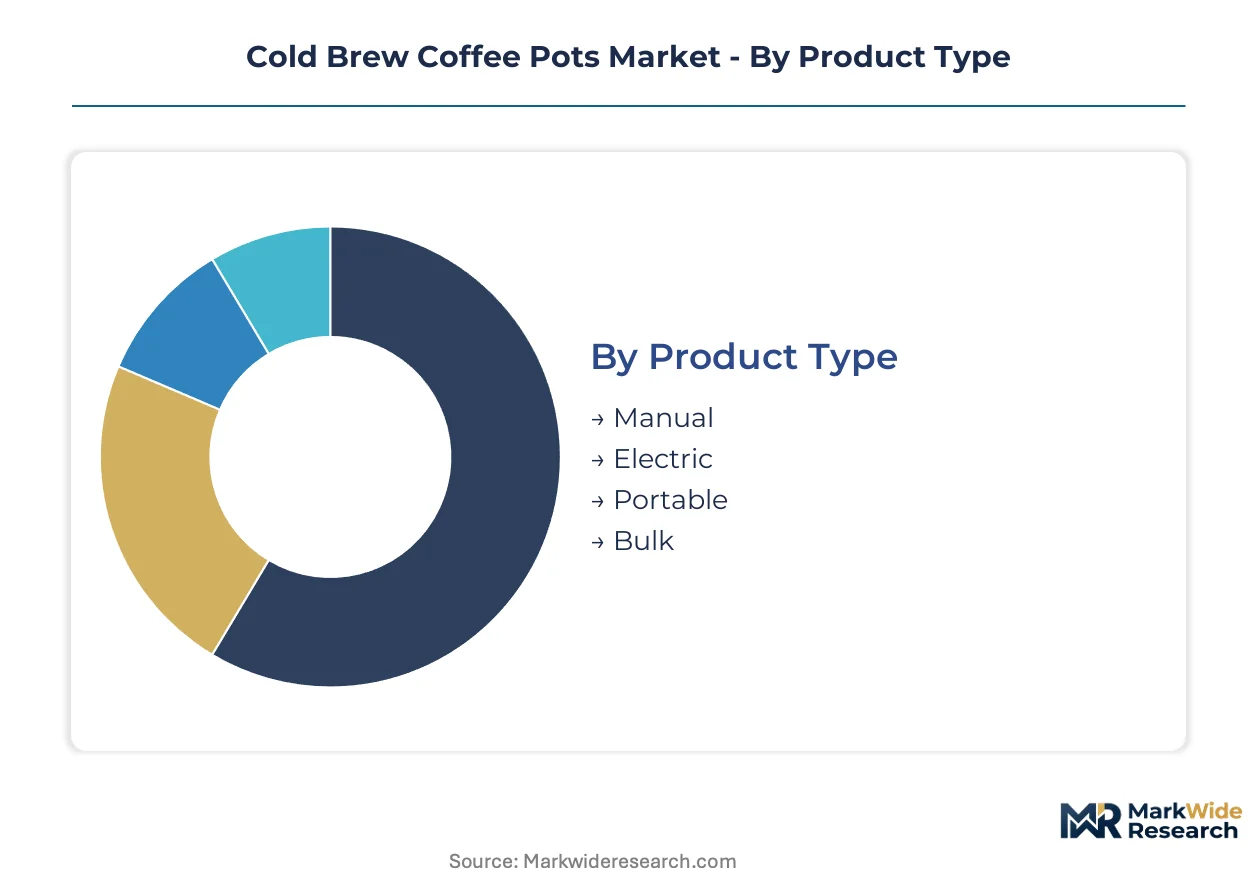
Cold brew coffee pots fragment across four distinct axes that reshape procurement priorities. Product type and material selection drive the largest purchase price spreads, while capacity and end-user targeting determine channel strategy and margin structure.
Product Type:
Customization intensity varies sharply across this category, from fully programmable electric systems to zero-electronics manual vessels that prioritize user control.
- Manual:These vessels rely on gravity filtration and user-managed steep timing without electrical components. Household penetration in the United States concentrates here due to sub-forty-dollar entry pricing and dishwasher-safe construction that minimizes maintenance.
- Electric:Integrated pumps and temperature controls accelerate extraction cycles and enable programmable batch scheduling. Commercial cafés in Germany and France are adopting these systems to compress overnight production windows and reduce refrigerator footprint demands.
- Portable:Compact vessels with sealed lids target commuter and travel use cases, typically under one-liter capacity with shatter-resistant materials.
- Bulk:High-volume systems exceeding six-liter output serve restaurant back-of-house and office pantry installations where concentrate throughput outweighs countertop constraints.
Most installed capacity flows through Manual. Expansion is steepest in Electric.
Material:
Cost tier stratification aligns tightly with regulatory compliance burden, as BPA-free mandates and REACH chemical restrictions eliminate the lowest-cost options from premium positioning.
- Glass:Borosilicate construction enables visual brewing monitoring and eliminates chemical leaching concerns. Craft coffee operators in Melbourne and Portland favor glass for its neutrality and aesthetic presentation, though fragility limits commercial kitchen adoption.
- Stainless Steel:304-grade and 316-grade alloys dominate commercial procurement for thermal retention and impact resistance. Nickel price volatility compresses margin pools for mid-tier manufacturers sourcing from Guangdong fabricators.
- Plastic:Tritan copolyester and polypropylene variants serve entry-level household segments where sub-twenty-dollar price points outweigh longevity concerns.
- Ceramic:Glazed stoneware appeals to design-conscious consumers seeking countertop aesthetics, though weight and thermal shock sensitivity constrain volume.
Glass captures the premium household segment. Stainless Steel is climbing the fastest in commercial channels.
Capacity:
Volume tier selection correlates directly with end-user scale, from single-serve preparation to multi-gallon concentrate production for foodservice.
- 1L:Individual and small-household formats dominate direct-to-consumer subscription bundles where vessel-plus-coffee pairings target trial users.
- 2L:The standard household reference size balances refrigerator storage efficiency with three-to-four-day concentrate supply for two-person consumption.
- 4L:Small café and office breakroom installations favor this tier for daily batch production without dedicated equipment footprint.
- 6L:Restaurant and high-volume specialty coffee chains deploy these systems for concentrate centralization, often paired with nitrogen dispensing infrastructure.
2L vessels anchor current installed base. 4L systems are expanding most quickly as hybrid work patterns reshape office beverage service.
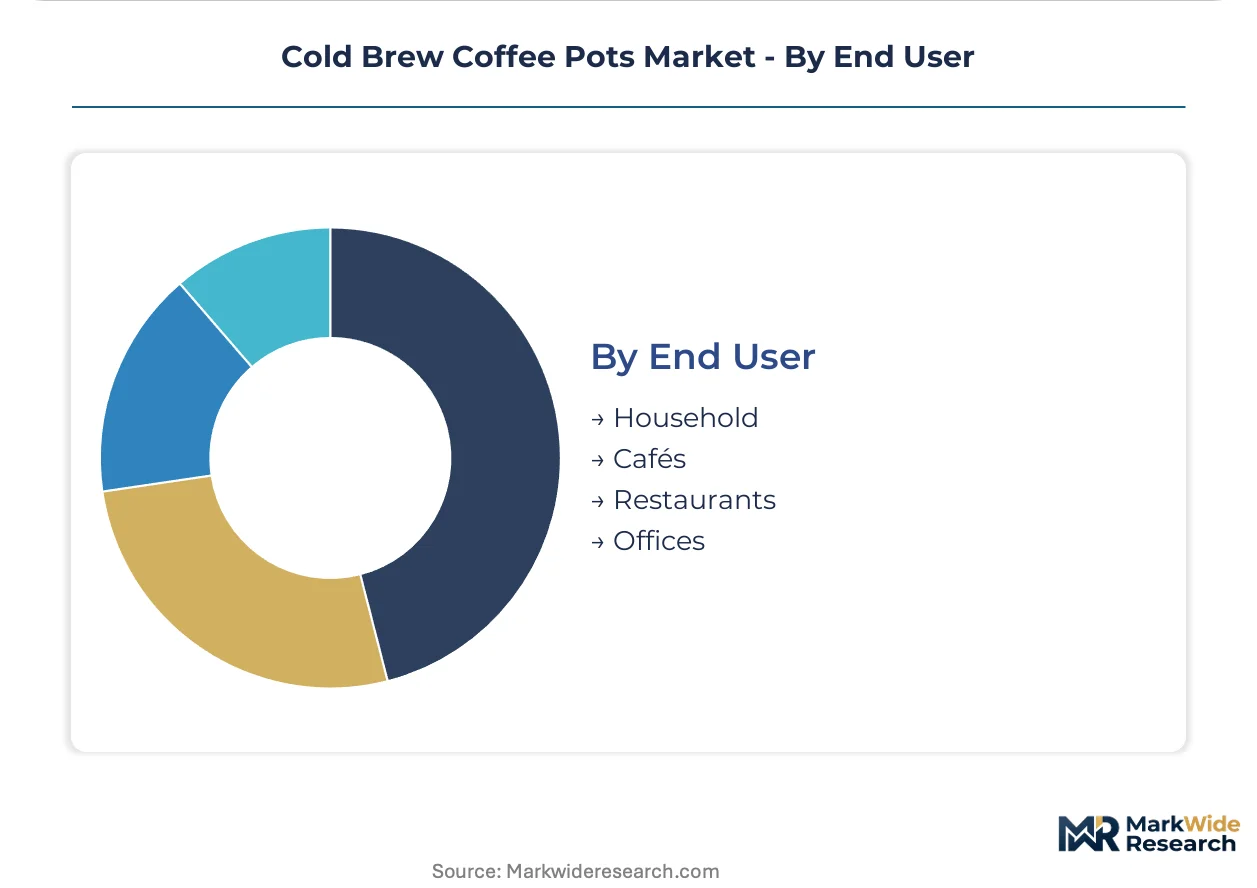
End User:
Customer type segmentation reveals diverging performance priorities, from price sensitivity and design aesthetics in households to throughput reliability and NSF certification in foodservice.
- Household:Consumers prioritize compact storage, dishwasher compatibility, and sub-fifty-dollar price ceilings. Manual glass and plastic variants dominate this channel.
- Cafés:Third-wave coffee shops demand consistency and speed, driving electric system adoption with programmable steep profiles and batch logging capabilities.
- Restaurants:Back-of-house operators require NSF-certified construction and six-liter-plus capacity for menu integration, favoring stainless steel for durability.
- Offices:Corporate pantry procurement balances employee satisfaction metrics against facilities management constraints, creating demand for 4L electric systems with self-cleaning cycles.
Household accounts for the largest unit volume. Cafés are gaining share fastest as cold brew menu penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors cold brew coffee pot manufacturing through glass component fabrication clusters serving export markets. Specialty café expansion in Melbourne, Portland, and Berlin drives equipment procurement from manual vessels to automated systems. Regulatory divergence between the FDA, ECHA, and national food safety agencies reshapes material selection and compliance timelines.
United States
Third-wave coffee shops in Seattle, Portland, and Brooklyn are replacing improvised cold brew methods with purpose-built equipment, compressing replacement cycles to eighteen months. The FDA oversees food-contact material safety for plastic components while California Proposition 65 mandates BPA-free disclosure. Austin and Nashville specialty roasters are piloting temperature-accelerated electric systems for overnight batch production.
Germany
Dedicated cold brew equipment penetration lags US household adoption by approximately sixty percentage points, creating whitespace for premium manual vessel launches. The EU F-Gas Regulation restricts fluorinated greenhouse gases in refrigeration equipment, pressuring thermal efficiency improvements in concentrate storage. Berlin and Hamburg craft coffee operators are adopting vacuum-insulated stainless reservoirs to meet compliance deadlines.
China
Guangdong manufacturing zones concentrate glass component sourcing for global brands, exposing supply chains to logistics disruption and tariff exposure. The country's national food safety regulator enforces GB standards for food-contact materials in kitchenware exports. Shenzhen and Dongguan fabricators are shifting toward 304-grade stainless steel construction to circumvent REACH chemical restrictions in European markets.
Australia
Melbourne's specialty coffee culture drives direct-to-consumer subscription models combining vessels with curated bean selections and brewing guides. The country's national consumer protection regulator monitors product safety claims for imported kitchenware. Sydney and Brisbane roasters are expanding cold brew menu penetration, accelerating café equipment procurement from manual to electric systems.
Japan
Precision glass construction from Hario and domestic competitors appeals to craft coffee operators prioritizing visual brewing monitoring and aesthetic presentation. METI oversees industrial standards for food-contact materials while JIS certification shapes commercial procurement requirements. Tokyo and Osaka third-wave cafés are integrating IoT-enabled temperature controls into previously manual vessels.
Cold Brew Coffee Pots Market Competitive Landscape
Strategic partnerships dominate the current landscape as kitchenware conglomerates and specialty coffee equipment specialists align for distribution reach. The vendor base organizes into three distinct tiers: mass-market conglomerates with retail channel control, craft-focused specialists commanding premium positioning, and contract manufacturers serving private-label programs. Two strategic archetypes predominate: heritage kitchen-tool brands leveraging design credibility and precision-focused Japanese manufacturers emphasizing material neutrality. Competitive intensity centers on M&A activity targeting subscription-capable direct-to-consumer platforms and capacity expansion in Vietnamese and Indonesian fabrication facilities.
Within the heritage kitchen-tool tier, KitchenAid and Cuisinart occupy positions anchored by mass retail distribution networks and cross-category brand recognition. Among precision-focused specialists, Hario exemplifies the Japanese glass construction archetype that appeals to craft coffee purists in Melbourne, Portland, and Berlin. OXO sits within the premium manual segment, leveraging its kitchen-tool heritage to compete against electric system manufacturers. These three companies represent divergent strategic paths: conglomerate scale, specialist craft authenticity, and design-forward premium positioning.
| Leading Market Players |
|---|
| KitchenAid |
| OXO |
| Primula |
| Hario |
| Takeya |
| Coffee Gator |
| SharkNinja |
| Toddy |
| Cuisinart |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Japanese glassware and German stainless steel fabrication anchor premium-tier pricing discipline through captive artisan networks that resist commoditization. Their ownership structures prioritize margin protection over volume capture, compressing price competition in craft-positioned segments while mass-market tiers face cost-down pressure from private-label contract manufacturers.
Pricing Analysis
Distributor margin layering shapes final price points most acutely in North American mass retail, where keystone markups separate entry-level plastic vessels from premium glass and steel alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects material grade differentiation, with borosilicate glass and 316-grade stainless commanding certification-linked premiums. Cost compression in mid-tier electric systems is intensifying because nickel price volatility feeds directly into 304-grade stainless input costs. Household consumers exhibit highest price sensitivity, while third-wave cafés prioritize throughput reliability over unit economics.
Supply Chain Analysis
Workforce availability constraints in Guangdong glass-blowing clusters and Dongguan metal-fabrication zones are tightening supplier selection criteria for export-facing brands. Manufacturing concentrates in China, Vietnam, and Indonesia, with Vietnamese facilities gaining share as tariff exposure reshapes sourcing calculus. Raw material flows draw from Australian nickel ore, German borosilicate glass feedstock, and domestic Chinese stainless billet. Single-source vulnerability in Guangdong glass component clusters exposes brands to logistics disruption. Distribution runs through mass retail chains, direct-to-consumer subscription platforms, and foodservice equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through material-grade upselling and regulatory-compliant premium positioning as BPA-free mandates eliminate lowest-cost competitors.
For Market Incumbents: Anticipate consolidation pressure from kitchenware conglomerates acquiring subscription-capable direct-to-consumer platforms. Defend craft authenticity positioning through JIS certification investment and in-house production of precision glass components. Counter electric system encroachment by embedding IoT-enabled timing controls into manual vessel architectures. For New Entrants and Emerging Players: Enter via underpenetrated German household segments where dedicated cold brew equipment adoption trails US benchmarks by substantial margins. Target premium manual vessel launches through Melbourne and Berlin specialty coffee channels. Leverage direct-to-consumer subscription bundling with curated bean selections to bypass mass retail slotting fee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with private-label capabilities and Vietnamese fabrication footprints. Long-term viability hinges on regulatory compliance infrastructure and circular economy packaging alignment. Acquisition candidates with EU F-Gas Regulation-ready thermal storage systems and established food-contact certification timelines present defensive positioning. Watch for inflection in nickel price stabilization as signal for margin recovery in stainless-dependent tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Concentrates customer acquisition spend on digital platforms rather than retail slotting fees. |
| Material Transition to BPA-Free Construction | Aligns with California Proposition 65 and EU REACH chemical restriction compliance deadlines. |
| IoT-Enabled Temperature Control Integration | Blurs craft authenticity with operational consistency demanded by third-wave cafés. |
| Vietnamese Manufacturing Footprint Expansion | Reduces tariff exposure from Guangdong supply concentration and logistics chokepoints. |
| Premium Manual Vessel Certification Investment | JIS and NSF credentials unlock commercial café procurement and restaurant back-of-house integration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with specialty coffee roasters, kitchenware procurement directors, foodservice equipment distributors, and regulatory compliance officers with secondary validation. Secondary sources included FDA food-contact material filings, EU ECHA REACH restriction updates, customs trade data for glass and stainless steel kitchenware imports, and SEC 10-K disclosures from listed kitchenware conglomerates. Bottom-up vessel shipment tracking and top-down category spend estimates were triangulated for convergence.
Historical reference periods anchored the projection horizon through comparable-period growth rate analysis and segment-level elasticity modeling. Segmentation dimensions included product type, material grade, capacity tier, and end-user archetype across household, café, restaurant, and office channels. CAGRs were derived through trend extrapolation adjusted for regulatory inflection points and material cost cycle positioning. Forecast inputs incorporated nickel price volatility indices, specialty café expansion rates, and BPA-free mandate implementation timelines.
Inputs from regulatory filing databases and trade association shipment reports were available through the study window; gaps in private-label contract manufacturer production data introduce uncertainty bands in mass-market tier estimates. Forecasts reflect documented assumptions regarding specialty coffee shop expansion persistence and REACH restriction enforcement intensity. Material deviation in nickel price trajectories, tariff implementation schedules, or FDA polymer approval timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
GCC Instant Coffee Market
Coffee
Oceania Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
India Coffee Roaster Market
Coffee
Encapsulated Caffeine Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Australia Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Bags Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
Global Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Green Coffee Bean Extract Market
Coffee
Drip Coffee Machine Market