
 Asia-Pacific Espresso Coffee Market | 2026-2036
Asia-Pacific Espresso Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Espresso Coffee Market Outlook
The gap between single-origin arabica offerings and mass-market robusta blends is repositioning how roasters allocate sourcing budgets and equipment investments. Luigi Lavazza anchors its presence through direct trade relationships with Vietnamese and Indonesian growers. Nestle competes via automated capsule systems designed for smaller urban kitchens. Blue Tokai Coffee Roasters differentiates through micro-lot roasting facilities in Bangalore and Mumbai.
Asia-Pacific espresso coffee comprises concentrated brews extracted under high pressure, typically using nine bars to yield 25-30 milliliters from seven to nine grams of finely ground, dark-roasted beans with particle sizes between 250 and 500 microns. Coffee pods lead volume growth through convenience-driven household penetration, while specialty coffee shops command the highest margin pools through experiential service models. Whole beans retain strength among enthusiasts who prioritize grind freshness and origin traceability.
India's FSSAI mandates strict labeling for caffeine content and additive disclosures on packaged espresso products. China's SAMR enforces GB standards for food contact materials in brewing equipment, affecting import compliance costs. Japan's METI promotes sustainable sourcing certifications that influence procurement decisions by major roasters. Stakeholders must monitor how evolving digital commerce regulations reshape direct-to-consumer channel economics.
Market Dynamics
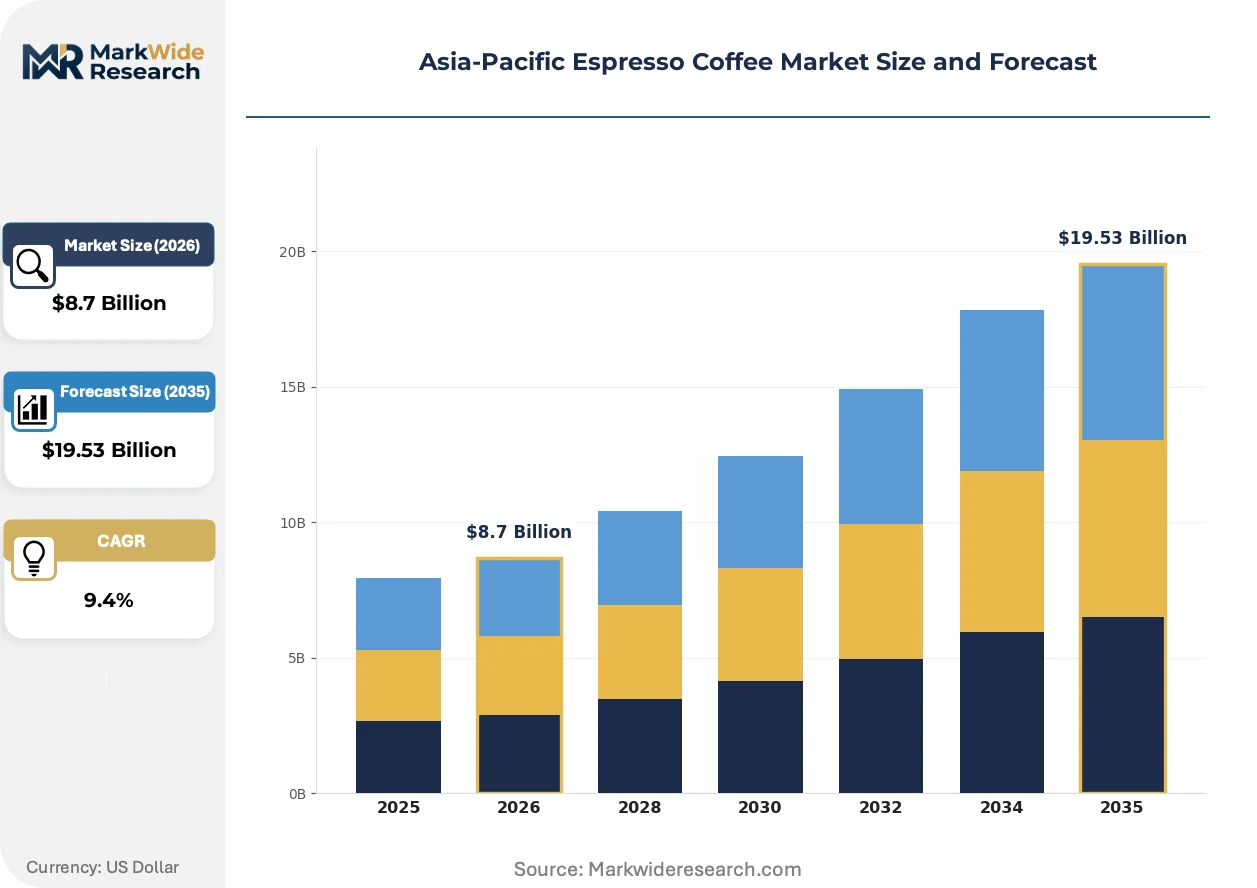
The Asia-Pacific espresso coffee market is experiencing a fundamental restructuring as digital commerce frameworks from TRAI and equivalent bodies across the region rewire distribution economics, compressing traditional wholesale margins while enabling direct-to-consumer channels to capture value previously held by intermediaries.
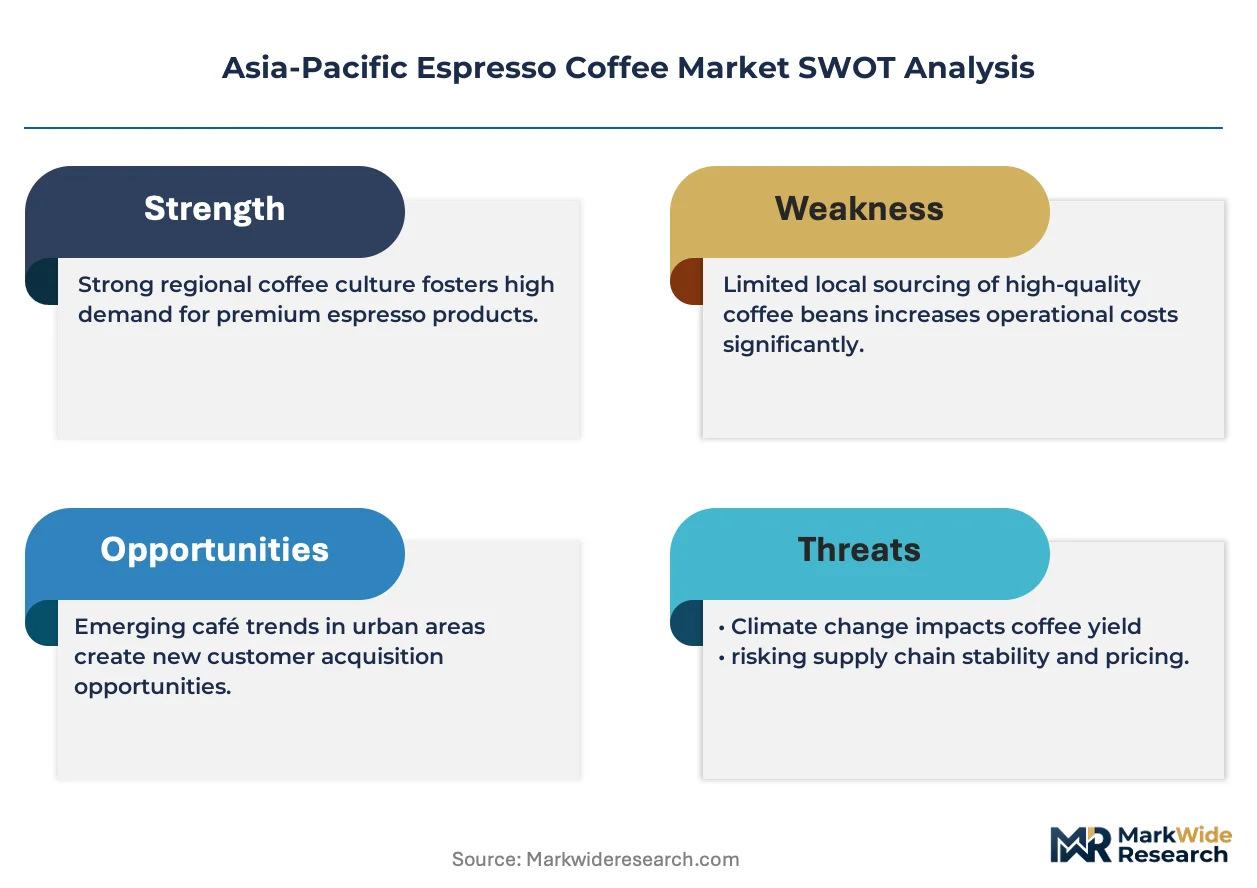
Growth Catalysts
- TRAI's digital commerce frameworks:India's telecommunications regulator has streamlined e-commerce infrastructure requirements, reducing barrier-to-entry costs for specialty roasters seeking direct consumer relationships.
- Specialty coffee shop density:South Korea and Japan's premium cafe networks are cultivating consumer willingness to pay origin premiums, pulling demand upward across the entire pricing spectrum.
- Capsule system penetration:Automated brewing technologies designed for compact urban kitchens are converting tea-drinking households into daily espresso consumers.
Market Restraints
- Arabica price volatility:Climate-induced harvest fluctuations in Vietnamese and Indonesian growing regions create input cost instability for roasters maintaining single-origin product lines.
- GB standards compliance:China's SAMR enforcement of food contact material regulations imposes testing and certification burdens on imported brewing equipment, elevating landed costs.
- Robusta substitution ceiling:Mass-market blenders face technical limitations in replacing arabica beyond 40-60% ratios without sacrificing extraction quality and crema stability.
Strategic Opportunities
- Tier-two Chinese cities:Cafe culture diffusion beyond Shanghai, Beijing, and Shenzhen presents whitespace for mid-market positioning before premium saturation sets in.
- Micro-lot roasting facilities:Distributed production nodes in Bangalore, Mumbai, and comparable hubs enable freshness differentiation and reduced logistics costs for regional brands.
- METI sustainable sourcing certifications:Japan's Ministry of Economy, Trade and Industry incentive structures reward roasters who meet traceability standards, creating procurement preference advantages.
Industry Challenges
- Q-grader talent scarcity:Certified coffee quality assessor availability lags behind roasting capacity expansion, creating bottlenecks in green coffee selection and blend development.
- FSSAI additive disclosure timelines:India's food safety regulator mandates detailed caffeine content labeling that extends product development cycles and reformulation costs.
- Legacy equipment integration:Traditional espresso machine fleets in established cafe chains resist connectivity upgrades for IoT-enabled maintenance and consumption tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Espresso Coffee Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Ground Coffee, Coffee Pods, Instant Coffee Distribution Channel: Supermarkets, Specialty Coffee Shops, Online Retail, Convenience Stores End User: Households, Office Settings, Cafes, Restaurants Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Bristot (Procaffé), Nestle, Luigi Lavazza, Blue Tokai Coffee Roasters, De'Longhi, Tchibo, Illy, Coffeeza, Segafredo Zanetti (Massimo Zanetti Beverage Group), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Espresso Coffee Market Strategic Shifts
Automation and sustainability mandates are converging to reshape how espresso reaches consumers across the Asia-Pacific region, with equipment intelligence and regulatory compliance emerging as twin vectors of competitive differentiation.
Smart brewing systems with integrated grind-by-weight sensors and pressure profiling algorithms are consolidating control over extraction variables previously managed through barista skill. High-volume cafe chains in Tokyo and Seoul are deploying these units to standardize output across locations while reducing training overhead. The technology is compressing the performance gap between flagship and satellite locations.
Japan's METI has expanded sustainable sourcing certification requirements to cover scope-three emissions in coffee supply chains, compelling roasters to document farm-level agricultural practices. Major processors must now verify deforestation-free status for Indonesian and Vietnamese suppliers. Compliance investments are favoring larger roasters with dedicated sustainability teams over smaller competitors.
Cafe patrons across China's tier-one cities are exhibiting preference rotation toward origin-transparency, with menu cards detailing farm names, processing methods, and harvest dates displacing generic regional labels. Specialty operators in Shanghai and Beijing are responding by shortening supply chains through direct trade relationships. This behavioral shift is most visible among consumers aged 25-35 in white-collar employment clusters.
Asia-Pacific Espresso Coffee Market Segmentation
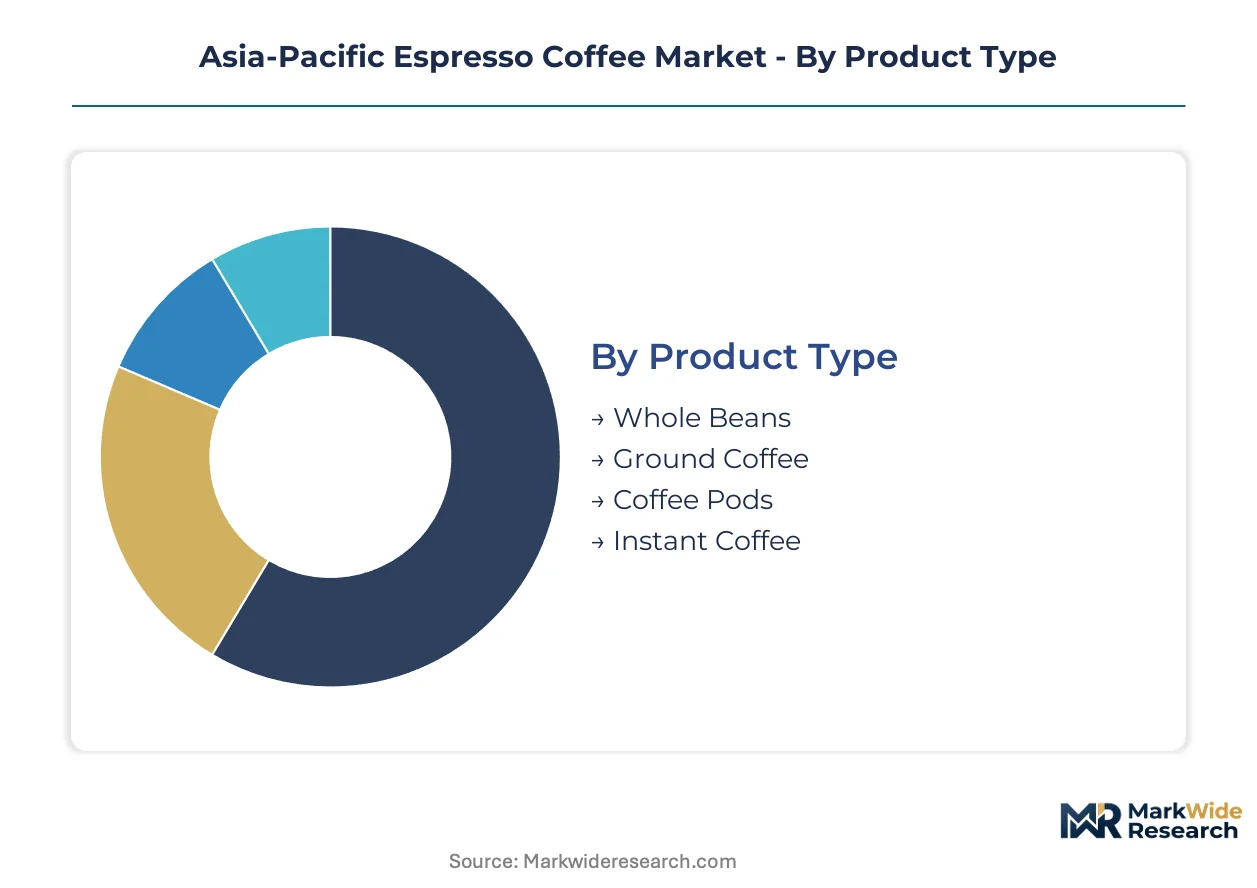
Segmentation in the Asia-Pacific espresso coffee market reveals how brewing format preferences and channel economics split consumer wallets across convenience-driven pods, freshness-prioritizing whole beans, and experience-centered cafe consumption. Each product and channel configuration carries distinct margin profiles and regulatory exposure that shape competitive strategy.
Product Type:
Standalone brewing formats dominate household penetration while embedded systems serve commercial installations requiring volume consistency.
- Coffee Pods:Single-serve aluminum or compostable capsules engineered for nine-bar extraction in automated machines. Demand concentrates in Japanese and South Korean urban apartments where counter space constraints favor compact brewing systems; convenience-driven daily consumption patterns sustain repeat purchase velocity despite higher per-cup costs.
- Whole Beans:Unroasted or freshly roasted seeds requiring consumer-operated grinding before extraction. Enthusiasts in Shanghai and Bangalore prioritize grind freshness and origin traceability; direct trade relationships with Vietnamese and Indonesian growers enable roasters to command origin premiums through harvest date transparency.
- Ground Coffee:Pre-milled particles packaged in nitrogen-flushed bags to slow oxidation. Supermarket shelves in tier-one Chinese cities stock medium-roast blends calibrated for automatic drip machines rather than true espresso extraction.
- Instant Coffee:Spray-dried or freeze-dried soluble granules reconstituted with hot water. Budget-conscious households across India and Southeast Asia maintain this format for price accessibility despite sensory trade-offs.
Coffee pods lead volumes today; whole beans are gaining share fastest.
Distribution Channel:
Channel selection determines margin capture and consumer education depth, with experiential formats pulling demand upward across price tiers.
- Specialty Coffee Shops:Third-wave cafes with on-site roasting and trained baristas executing manual extraction. Seoul's Gangnam district and Tokyo's Shibuya cluster host dense networks where origin storytelling justifies premium pricing; experiential service models command the highest margin pools in the regional market.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts enabled by TRAI's streamlined e-commerce infrastructure. Specialty roasters in Bangalore and Mumbai bypass traditional wholesale intermediaries; subscription models lock in recurring revenue with freshness guarantees.
- Supermarkets:Mass-market retail with private-label and branded shelf-stable offerings. GB standards compliance for food contact materials elevates landed costs for imported brewing equipment sold alongside packaged coffee.
- Convenience Stores:Grab-and-go formats serving immediate consumption needs. Japan's Lawson and 7-Eleven chains stock canned espresso beverages for commuter traffic.
Specialty coffee shops anchor premium positioning; online retail is expanding most quickly.
End User:
Usage context dictates equipment investment levels and quality tolerance, separating ritual-driven home preparation from throughput-optimized commercial operations.
- Households:Residential kitchens where brewing frequency and equipment sophistication vary by income tier. Capsule systems convert tea-drinking families in Chinese tier-one cities into daily espresso consumers; compact urban footprints favor space-efficient automated solutions.
- Cafes:Commercial establishments with trained baristas and high-volume extraction equipment. METI sustainable sourcing certifications influence procurement decisions for Tokyo-based chains documenting farm-level practices.
- Office Settings:Workplace pantries and hospitality suites requiring low-maintenance solutions. Bean-to-cup machines with automated cleaning cycles reduce facility management overhead.
- Restaurants:Foodservice operations where espresso complements meal service rather than driving traffic. Menu integration emphasizes speed and consistency over origin narrative.
Households generate the largest volume base; cafes capture the steepest margin expansion.
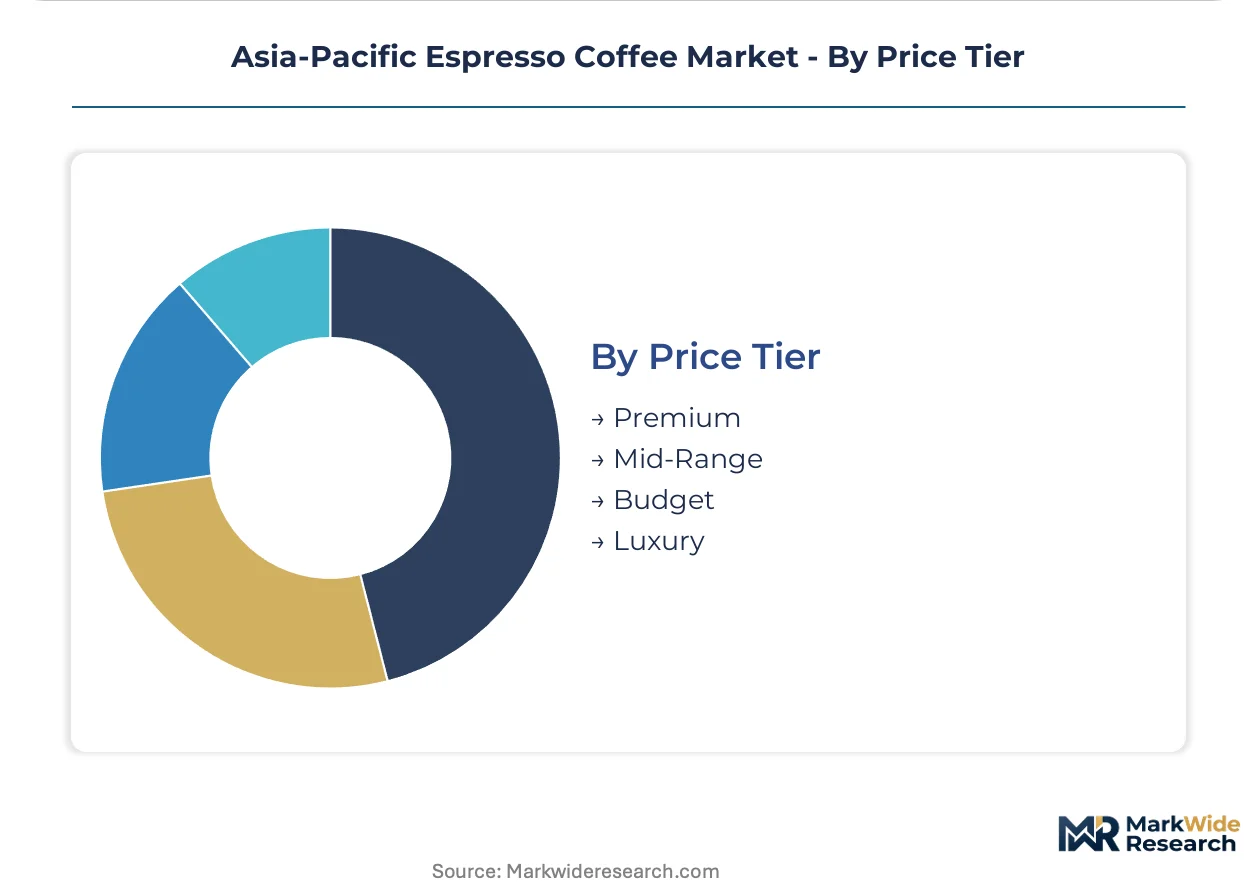
Price Tier:
Price stratification aligns with certification depth, processing method transparency, and packaging format costs rather than origin alone.
- Premium:Single-origin arabica with documented harvest dates and processing method disclosure. Direct trade relationships and micro-lot roasting facilities in Mumbai enable freshness differentiation; FSSAI caffeine content labeling mandates extend development cycles for packaged offerings.
- Luxury:Limited-release lots with auction-provenance and exclusive distribution. Collector-oriented releases target gifting occasions in Seoul and Tokyo.
- Mid-Range:Blended arabica-robusta formulations balancing crema stability with cost control. Regional roasters in Jakarta and Ho Chi Minh City optimize for local palate preferences.
- Budget:High-robusta blends with commodity-grade sourcing and minimal processing transparency. Price-sensitive penetration across Indian and Southeast Asian mass markets.
Premium tier anchors revenue per kilogram; mid-range is climbing the fastest as cafe culture diffuses beyond tier-one cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty coffee shop density and certified Q-grader concentrations anchor the Asia-Pacific espresso coffee geography, with talent clustering in Seoul, Tokyo, and Shanghai driving premium extraction standards across the region.
China
Cafe culture maturation in Shanghai and Beijing pulls arabica demand upward, with SAMR's GB standards for food contact materials elevating compliance costs for imported brewing equipment. Tier-two cities including Hangzhou and Chengdu present whitespace for mid-market positioning before premium saturation sets in.
Japan
Third-wave coffee density in Tokyo's Shibuya and Harajuku districts cultivates consumer willingness to pay origin premiums, while METI's expanded sustainable sourcing certifications compel roasters to document scope-three emissions and deforestation-free status for Indonesian suppliers.
South Korea
Gangnam district's specialty cafe networks standardize high-pressure extraction protocols that diffuse across Seoul's metropolitan area, with the country's MFDS-equivalent food safety frameworks mandating additive disclosures that extend product development cycles for packaged espresso offerings.
India
Micro-lot roasting facilities in Bangalore and Mumbai enable freshness differentiation for domestic brands, as TRAI's streamlined e-commerce infrastructure reduces barrier-to-entry costs for specialty roasters building direct-to-consumer channels bypassing traditional wholesale intermediaries.
Vietnam
Robusta production clusters in the Central Highlands supply mass-market blenders facing technical limitations beyond 40-60% arabica substitution ratios, with climate-induced harvest fluctuations creating input cost instability for roasters maintaining single-origin product lines.
Asia-Pacific Espresso Coffee Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific espresso coffee market, where integrated roasters with captive green coffee sourcing face asset-light specialty brands outsourcing production to contract facilities. The structure splits between consolidated multinational beverage groups, regional roasting specialists with direct trade relationships, and equipment manufacturers bundling hardware with consumable ecosystems. Strategic moves concentrate on micro-lot roasting facility expansion and automated capsule system penetration for compact urban kitchens.
Within the multinational beverage tier, Nestle and Luigi Lavazza occupy positions that exemplify divergent approaches to household penetration. Among regional roasting specialists, Blue Tokai Coffee Roasters anchors the Indian market's premium segment through distributed production nodes.
| Leading Market Players |
|---|
| Bristot (Procaffé) |
| Nestle |
| Luigi Lavazza |
| Blue Tokai Coffee Roasters |
| De'Longhi |
| Tchibo |
| Illy |
| Coffeeza |
| Segafredo Zanetti (Massimo Zanetti Beverage Group) |
| Others |
Value Chain & Pricing Dynamics
METI's expanded scope-three emissions documentation gates both qualified green coffee supply and premium-tier pricing access for Japanese roasters seeking origin-transparency positioning, compressing margins for processors lacking dedicated sustainability teams while rewarding integrated players with verified deforestation-free Indonesian and Vietnamese supplier networks.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment-inclusive capsule ecosystems from unbundled whole-bean transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and harvest date transparency. Cost compression in mid-range blends is intensifying because regional roasters in Jakarta and Ho Chi Minh City optimize for local palate preferences. Budget-tier buyers in Indian mass markets exhibit highest price sensitivity; luxury auction-provenance collectors in Seoul and Tokyo show least.
Supply Chain Analysis
Dual-sourcing requirements from major Tokyo-based chains mandate multi-supplier qualification for Indonesian and Vietnamese arabica growers. Geographic supply concentrates in Vietnam's Central Highlands, Indonesia's Sumatra, and India's Karnataka highlands. Raw material dependencies span green coffee beans, aluminum capsule materials, and nitrogen-flush packaging films. Single-source vulnerability runs through climate-exposed Vietnamese harvests. Distribution runs through direct-to-consumer platforms enabled by TRAI's streamlined e-commerce infrastructure alongside traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: TRAI's reduced e-commerce barrier-to-entry costs in India contrast with SAMR's GB standards compliance burdens elevating landed equipment costs in China, creating divergent channel economics for identical product tiers.
For Market Incumbents: To counter capsule system commoditization by Nestle's automated platforms, anchor positioning through micro-lot roasting facility expansion in Bangalore and Mumbai, and deepen backward integration into direct trade relationships with Vietnamese growers to secure origin-premium pricing power. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer lowest customer acquisition costs in tier-two Chinese cities including Hangzhou and Chengdu, where cafe culture diffusion presents whitespace before premium saturation; target mid-market arabica-robusta blends with freshness-guaranteed logistics. For Investors and Strategic Acquirers: Roll-up economics work for regional roasting specialists with captive Q-grader talent because certified assessor scarcity creates acquisition currency for quality-validated brands; watch METI certification compliance rates as inflection indicator for procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Lot Roasting Facility Expansion | Distributed production nodes in Mumbai and Bangalore reduce logistics costs for freshness differentiation. |
| Direct-to-Consumer Channel Launch | TRAI's streamlined e-commerce infrastructure enables bypass of traditional wholesale intermediaries. |
| Sustainable Sourcing Certification Investment | METI's scope-three emissions requirements reward roasters with documented farm-level practices. |
| Capsule System Technology Partnership | Automated brewing platforms convert tea-drinking households in compact urban kitchens. |
| Tier-Two City Distribution Expansion | Hangzhou and Chengdu present whitespace before Shanghai-Beijing premium saturation sets in. |
Study Parameters
Multiple input streams — primary interviews with roasting operations heads, green coffee procurement managers, and cafe chain sustainability directors; secondary validation through customs trade records, FSSAI additive disclosure filings, and METI certification registries — were reconciled using bottom-up volume triangulation against top-down category spend estimates.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, end-use context, and price tier. CAGRs were derived from trend extrapolation of channel shift velocities and equipment penetration curves. Forecast inputs incorporated Q-grader talent availability constraints and climate-induced harvest fluctuation patterns.
The model assumes a particular technology adoption path; alternative pathways for IoT-enabled smart brewing systems would alter the outlook if legacy equipment integration resistance persists in established Tokyo and Seoul cafe chains. Deviation in METI certification enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Drip Coffee Machine Market
Coffee
Coffee Syrup Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
Latin America Coffee Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Instant Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Nitrogenated Coffee Market
Coffee
Green Coffee Market
Coffee
Germany Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Middle East Coffee Market
Coffee
Butter Coffee Market
Coffee
Australia Coffee Market