
 Workflow Content Automation (WCA) Market | 2026-2036
Workflow Content Automation (WCA) Market Size, Share, and Industry Trends Forecast 2026-2036
Workflow Content Automation (WCA) Market Analytics
ISO/IEC 27001 certification is redrawing competitive boundaries in workflow content automation. UiPath leverages its RPA heritage to anchor enterprise-grade security positioning. Zapier competes through breadth of third-party connectors rather than deep compliance stacks. Workato differentiates via native integration with Salesforce Flow ecosystems.
Workflow Content Automation orchestrates the creation, routing, approval, and distribution of digital content through rule-based engines and AI-driven decision layers, typically operating across REST APIs and event-driven architectures with sub-second trigger latency. Its primary purpose eliminates manual handoffs in high-volume content pipelines. Cloud-based deployment leads absolute revenue contribution as enterprises abandon capital-intensive infrastructure, while AI-Powered technology segments expand fastest as large language models embed directly into approval workflows. Text Automation solutions currently occupy the deepest margin pools due to regulatory documentation demands in financial services and healthcare.
FDA 21 CFR Part 11 shapes product validation requirements for pharmaceutical content workflows, while GDPR and the EU AI Act impose algorithmic transparency obligations on automated decision systems processing personal data. The SEC's marketing compliance scrutiny extends these standards to investor-facing content automation in capital markets. Stakeholders must weigh certification investment against vertical specialization to determine sustainable positioning as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Generative AI integration into approval workflows is compressing cycle times and forcing platform vendors to rearchitect around large language model orchestration rather than traditional rule-based engines.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision systems processing personal data in European enterprises must embed algorithmic transparency, creating procurement urgency for auditable workflow platforms.
- Pharmaceutical documentation pipelines:FDA 21 CFR Part 11 validation requirements for electronic records are expanding WCA adoption in drug development and clinical trial content management.
- Capital markets marketing scrutiny:SEC enforcement actions against misleading investor communications are driving automated compliance checks into content production workflows.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency in North American deployments creates single-point-of-failure exposure for mission-critical content routing.
- On-premises migration costs:European publishers face stranded asset risk from EUDPR-mandated data localization requirements conflicting with prior cloud investments.
- API rate limiting:Third-party connector throttling from SaaS vendors constrains real-time workflow orchestration at enterprise scale.
Strategic Opportunities
- India's PLI scheme for IT hardware:Domestic manufacturing incentives are reducing data center equipment costs for on-premises WCA deployments in regulated sectors.
- Healthcare prior authorization automation:HIPAA-compliant content routing between payers and providers represents underpenetrated workflow volume.
- Convergence of RPA and LLM layers:Hybrid architectures combining deterministic bots with generative content creation are opening new platform design space.
Industry Challenges
- ISO/IEC 27001 certification timelines:12-18 month audit cycles delay enterprise sales cycles and strain vendor cash conversion.
- Legacy ERP integration complexity:SAP and Oracle system heterogeneity forces costly custom connector development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workflow Content Automation (WCA) Market |
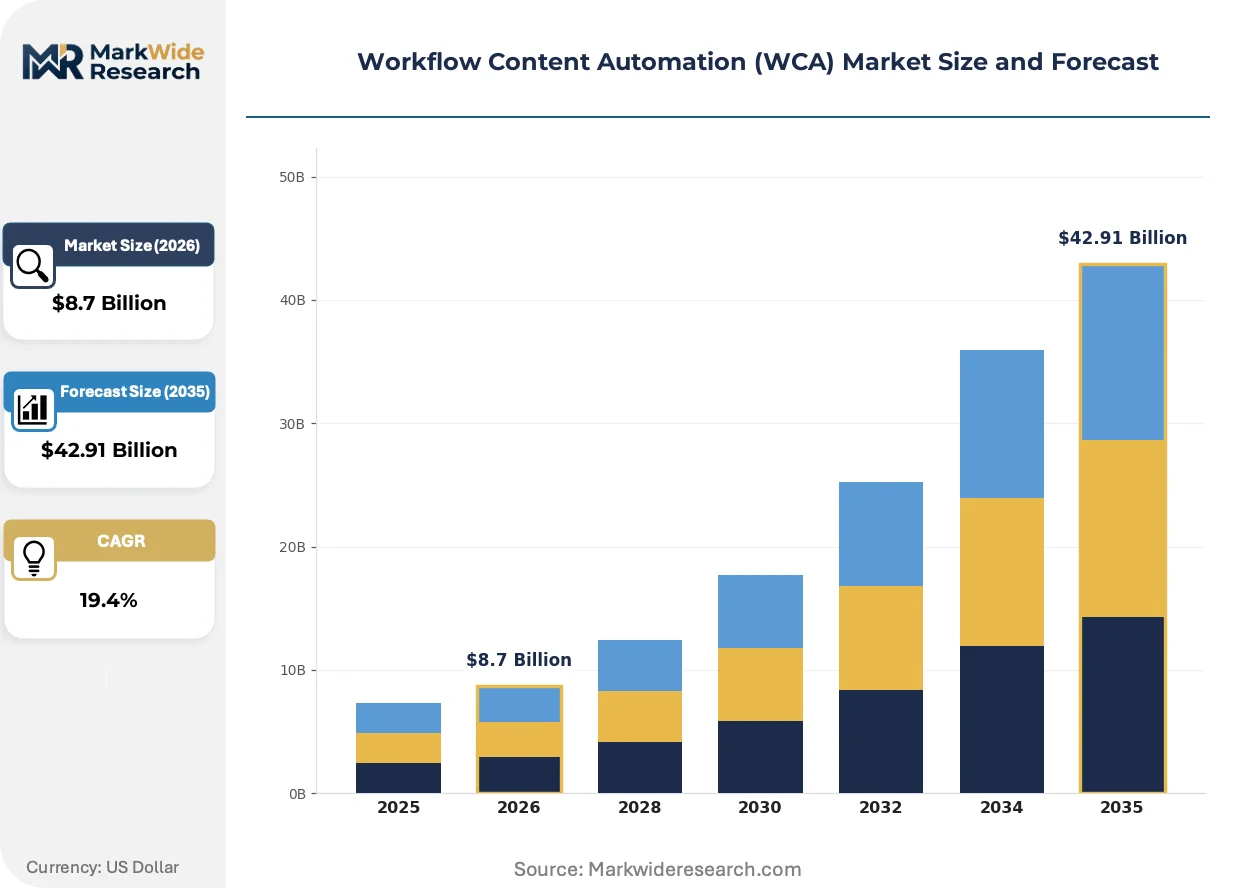
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Publishing, Media, Education, Enterprises Solution: Text Automation, Visual Workflow, Data Management, Content Collaboration Technology: AI-Powered, Machine Learning, RPA, Natural Language Processing |
| Companies Covered | Microsoft Power Automate, Tray.io, Zapier, UiPath, Getint, Make, n8n, Salesforce Flow, Workato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workflow Content Automation (WCA) Market Evolving Landscape
Agentic AI architectures are redefining workflow automation from deterministic routing to autonomous decision-making, compressing the boundary between content generation and governance.
Large language model inference APIs are supplanting static business rules in approval workflows. Financial services compliance teams are adopting these capabilities fastest, with pilot deployments scaling to production within six-month cycles. The shift is compressing vendor differentiation around prompt engineering and retrieval-augmented generation rather than traditional workflow design tools.
GDPR Article 22 enforcement on automated profiling is forcing algorithmic explainability into WCA product roadmaps. European data protection authorities are rejecting black-box routing decisions in hiring and credit content. Platform vendors are responding with counterfactual explanation modules and human-in-the-loop override mandates.
Enterprise legal departments are consolidating procurement authority over IT-led automation purchases. Centralized buying committees are replacing distributed SaaS adoption, with security certification and liability indemnification now gatekeeping vendor selection. This concentration is most visible in German and French multinational headquarters, where GDPR fines have elevated risk officer influence over technology decisions.
Workflow Content Automation (WCA) Market Segmentation
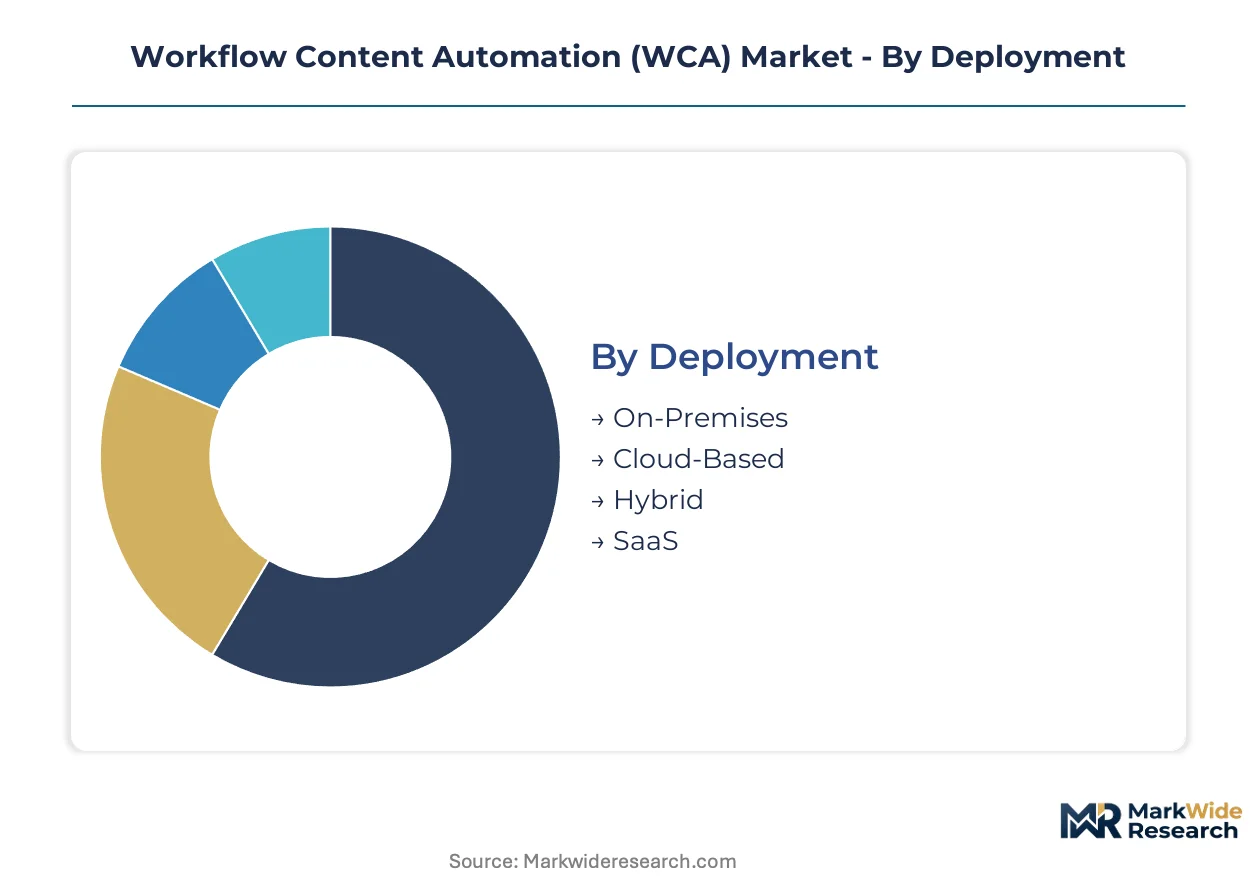
Workflow Content Automation segmentation reveals distinct procurement patterns across deployment modes and technology stacks. Channel strategy varies sharply between compliance-heavy verticals and speed-oriented media operations.
Deployment:
Cloud-based models flow through direct vendor sales and hyperscaler marketplaces, while on-premises deployments route through systems integrators and value-added resellers with security certification.
- On-Premises:Hardware-resident installations with full data sovereignty control. German automotive suppliers and French pharmaceutical manufacturers under CNIL and EMA jurisdiction drive procurement here, prioritizing air-gapped environments over operational velocity.
- Cloud-Based:Multi-tenant SaaS architectures with API-first integration. US financial services firms and UK fintechs dominate consumption, attracted to sub-second scaling and consumption pricing models.
- Hybrid:Split architectures keeping sensitive workflows local while routing collaborative stages to cloud. Japanese manufacturers with METI data governance guidelines favor this pattern for supply chain documentation.
- SaaS:Fully managed software subscriptions with embedded maintenance. Indian IT services firms leverage PLI scheme infrastructure incentives to deploy these for export-oriented clients.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest as sovereignty requirements harden.
End User:
Customer type determines implementation complexity and sales cycle length, with regulated enterprises demanding 18-month validation against media buyers seeking 30-day deployment.
- Publishing:Editorial workflow orchestration across print and digital channels. European publishers under EUDPR constraints are migrating from cloud to on-premises, creating stranded asset negotiations with prior vendors.
- Media:Real-time content distribution with brand safety filtering. US streaming platforms and social networks drive throughput requirements, processing millions of assets daily with FDA and FTC marketing compliance overlays.
- Education:Curriculum development and accreditation documentation. Indian universities and Australian vocational institutes represent emerging procurement clusters with TGA-aligned research data management needs.
- Enterprises:Cross-functional content governance spanning legal, HR, and investor relations. German and French multinationals with consolidated legal procurement authority are standardizing on ISO/IEC 27001-certified platforms.
Enterprises generate the deepest revenue per account. Media delivers the shortest sales cycles.
Solution:
Margin concentration follows regulatory documentation intensity, with text-heavy compliance applications commanding premium pricing over visual production tools.
- Text Automation:Structured document generation with version control and audit trails. FDA 21 CFR Part 11 validation requirements in US pharmaceutical pipelines and EMA clinical trial submissions create the steepest expansion trajectory here.
- Visual Workflow:Image and video routing with rights management. US advertising agencies and Brazilian broadcasters under ANVISA health product advertising rules deploy these for campaign compliance.
- Data Management:Metadata governance and lineage tracking. HIPAA-covered entities in US healthcare prior authorization processes use these to route patient data between payers and providers.
- Content Collaboration:Concurrent editing with permission hierarchies. UAE and Saudi enterprises with MOHAP and SFDA localization mandates favor these for multilingual regulatory submissions.
Text Automation holds the widest margin pools. Content Collaboration is gaining share fastest in emerging markets.
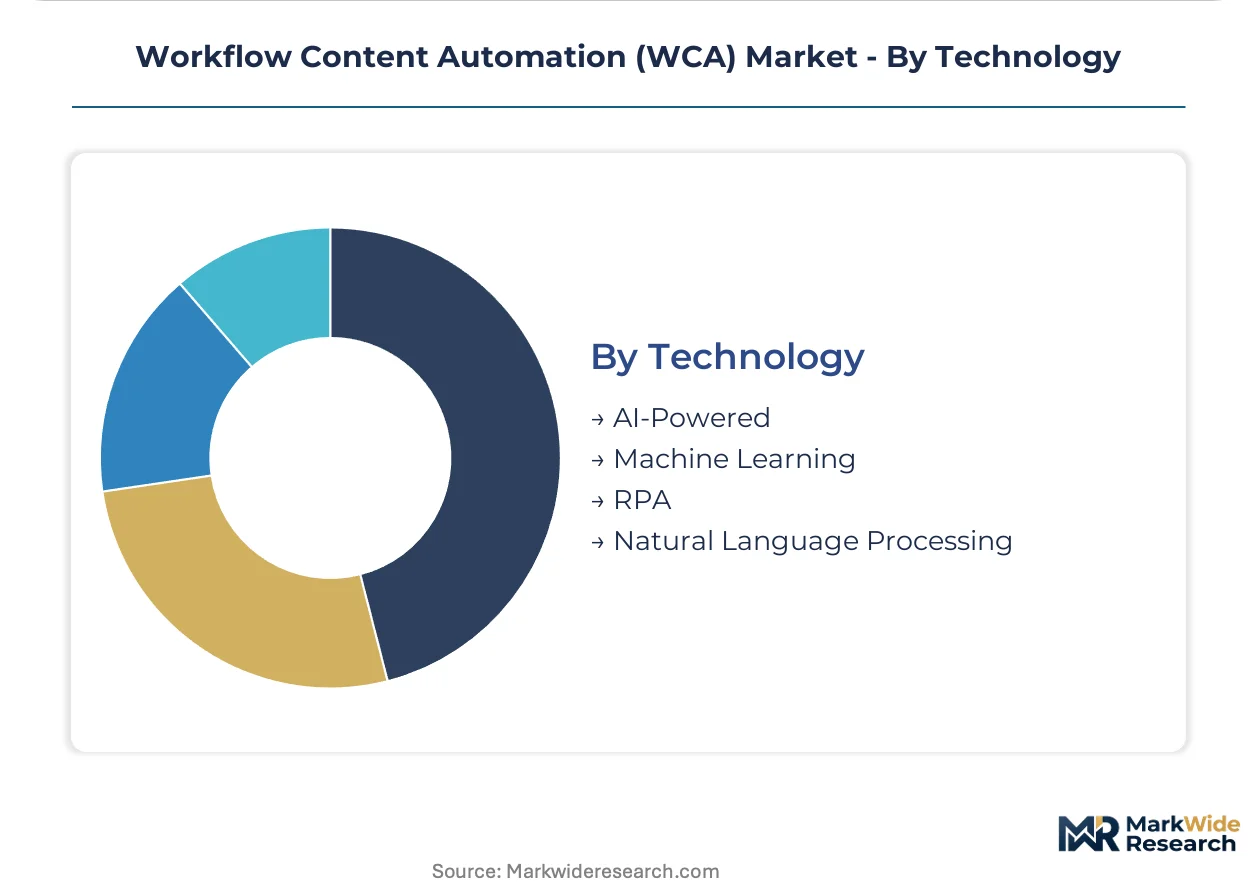
Technology:
Architecture choices determine competitive moat depth, with LLM-native platforms displacing rule-based incumbents in approval-intensive workflows.
- AI-Powered:Large language model inference embedded directly in decision layers. EU AI Act algorithmic transparency mandates are accelerating procurement among French and German enterprises requiring auditable routing logic.
- Machine Learning:Pattern recognition for anomaly detection and routing optimization. US capital markets compliance teams deploy these for SEC marketing scrutiny, with six-month pilot-to-production cycles.
- RPA:Deterministic bot execution for repetitive handoff elimination. UiPath heritage platforms anchor enterprise security positioning here through ISO/IEC 27001 certification.
- Natural Language Processing:Semantic parsing for content classification and sentiment filtering. Japanese financial institutions under JIS standards and South Korean insurers with MFDS requirements drive adoption for contract analysis.
RPA retains the largest installed base. AI-Powered solutions are expanding most quickly as LLM inference costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ashburn-Loudoun data center corridor underwrites United States dominance in cloud-based WCA deployment, processing sub-second workflow triggers for financial services and media enterprises. Transatlantic fiber capacity through MAREA and Dunant cables positions Northern Virginia as the latency-critical node for cross-border content routing.
United States
SEC marketing compliance enforcement drives automated content validation in New York and Chicago capital markets clusters. HIPAA-covered entities in Boston and Minneapolis deploy prior authorization automation between payers and providers. FDA 21 CFR Part 11 requirements shape pharmaceutical documentation pipelines across New Jersey and North Carolina research triangles.
Germany
CNIL-aligned data protection authorities in Berlin and Munich mandate algorithmic transparency for automated hiring and credit content workflows. ISO/IEC 27001 certification gates enterprise procurement from consolidated legal departments at DAX headquarters. Baden-Württemberg automotive suppliers maintain air-gapped environments for supply chain documentation under METI-influenced governance standards.
India
PLI scheme incentives for IT hardware manufacturing reduce data center equipment costs for on-premises deployments in Bengaluru and Hyderabad export zones. RBI-regulated fintechs in Mumbai adopt hybrid architectures for cross-border payment documentation. CDSCO-aligned clinical trial sponsors in Delhi-NCR deploy validated workflow platforms for regulatory submissions.
Japan
METI data governance guidelines steer Japanese manufacturers toward hybrid deployments keeping sensitive supply chain workflows local. JIS standards compliance anchors financial institution procurement in Tokyo and Osaka for contract analysis automation. PMDA validation requirements extend WCA adoption into pharmaceutical quality management systems across Kansai medical device clusters.
United Kingdom
FCA consumer duty rules pressure London asset managers into auditable content approval chains for investor communications. UK fintechs in Manchester and Edinburgh leverage consumption pricing models for rapid workflow scaling. Post-Brexit data adequacy negotiations create procurement hesitation, slowing cloud migration relative to continental European peers.
Workflow Content Automation (WCA) Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and connector breadth. The vendor base stratifies into three tiers: hyperscaler-anchored suites, independent automation platforms, and open-source workflow engines. Strategic differentiation clusters around ISO/IEC 27001 security positioning, Salesforce-native integration, and RPA heritage. Competitive moves concentrate on M&A for vertical compliance modules and strategic partnerships with large language model providers.
Within the RPA-heritage tier, UiPath anchors enterprise-grade security positioning through certification-heavy sales cycles. Zapier exemplifies the connector-breadth archetype, competing through third-party integration volume rather than deep compliance stacks. Workato occupies the CRM-native position, differentiating via Salesforce Flow ecosystem embedding. These three patterns represent the dominant strategic vectors as procurement authority consolidates within enterprise legal departments.
| Leading Market Players |
|---|
| Microsoft Power Automate |
| Tray.io |
| Zapier |
| UiPath |
| Getint |
| Make |
| n8n |
| Salesforce Flow |
| Workato |
| Others |
Value Network & Pricing Analysis
ISO/IEC 27001 certification gates both vendor qualification and price differentiation in enterprise WCA procurement, with audit timelines stretching 12-18 months and certification tiers separating premium positioning from commodity SaaS tiers. Legal departments now wield this standard as a procurement filter, compressing margins for uncertified players while accredited vendors capture pricing power in regulated verticals.
Pricing Analysis
Volume-discount tiering structures dominate WCA procurement, with three-tier pricing separating ISO-certified enterprise platforms from mid-market standard offerings and economy SaaS tiers lacking compliance depth. Price differentiation hinges on certification grade and vertical specialization, with FDA-validated pharmaceutical modules commanding substantial premiums over generic workflow tools. Cost compression in the economy tier is intensifying because hyperscaler marketplace listings are democratizing basic connector functionality. Small and mid-market buyers exhibit the sharpest price sensitivity, while DAX and CAC 40 legal departments prioritize liability indemnification over unit economics.
Supply Chain Analysis
Inbound logistics costs through the Ashburn-Loudoun corridor and transatlantic fiber routes through MAREA and Dunant cables anchor cloud infrastructure delivery timelines for North American WCA deployments. Supply concentration centers on the United States, Ireland, and Singapore for hyperscaler data center capacity, while Taiwan and South Korea feed semiconductor dependencies for on-premises server hardware. Single-source vulnerability runs through AWS, Azure, and GCP control planes, constraining enterprise negotiation leverage. Distribution runs through direct vendor sales for enterprise accounts and hyperscaler marketplaces for mid-market self-service adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WCA vendors are pivoting toward service-attach revenue models, with compliance monitoring and audit support subscriptions expanding faster than core platform licensing as regulatory complexity deepens customer dependency.
For Market Incumbents: Shield installed base relationships by embedding LLM orchestration layers ahead of pure-play AI entrants, and accelerate ISO/IEC 27001 certification coverage across product lines before European procurement committees consolidate vendor lists. Vertical integration into specialized compliance modules for FDA and EMA validation requirements will defend margin position against connector-breadth competitors. For New Entrants and Emerging Players: Lead with healthcare prior authorization automation as the most penetrable white-space segment, targeting HIPAA-covered entities in Minneapolis and Boston clusters with API-first architectures that bypass legacy ERP integration complexity. A channel partnership strategy with systems integrators holding security certification accelerates enterprise access without 18-month direct sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed RPA specialists seeking AI-native transformation, particularly those with ISO/IEC 27001 foundations but lacking LLM inference capabilities. Long-term viability hinges on algorithmic explainability modules meeting EU AI Act enforcement trajectories. The signal to watch is GDPR Article 22 precedent rulings on automated profiling in hiring and credit workflows, which will accelerate replacement demand for black-box routing systems.| Strategic Initiative | Industry Significance |
|---|---|
| LLM-Native Platform Architecture | Embedding large language model inference directly into approval workflows displaces rule-based incumbents in financial services compliance. |
| ISO/IEC 27001 Certification Expansion | Extended security audit coverage gates enterprise procurement from consolidated legal departments at German and French multinationals. |
| Healthcare Prior Authorization Automation | HIPAA-compliant content routing between payers and providers captures underpenetrated workflow volume in Minneapolis and Boston clusters. |
| Vertical Compliance Module Acquisition | Specialized FDA 21 CFR Part 11 and EMA validation tools deepen margin pools in pharmaceutical documentation pipelines. |
| Hyperscaler Marketplace Distribution | AWS and Azure marketplace listings compress customer acquisition costs for mid-market SaaS tiers lacking direct sales infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with enterprise legal department heads, CTOs at financial services firms, pharmaceutical regulatory affairs leads, healthcare payer IT directors, and channel partners at systems integrators. Secondary validation drew from SEC enforcement action databases, FDA 21 CFR Part 11 guidance documents, EMA clinical trial submission records, and hyperscaler capex disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing from certification body audit statistics.
Across the analysis window, the forecasting framework modeled deployment mode segmentation alongside organization size tiers, vertical regulatory intensity, integration complexity levels, and regional adoption patterns. CAGRs were derived from penetration rate trajectories in compliance-heavy verticals weighted against cloud migration velocity in less regulated segments. Inputs included LLM inference cost decline curves, EU AI Act implementation timelines, and pharmaceutical pipeline documentation volume projections.
Underlying assumptions cover sustained regulatory fragmentation across GDPR, EU AI Act, and SEC marketing compliance enforcement, with deviation risk concentrated in hyperscaler concentration policy shifts or accelerated on-premises migration mandates from EUDPR-like data localization regimes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Data Extraction Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Global DDI Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Global Delivery Management Software Market