
 Data Acquisition Market | 2026-2036
Data Acquisition Market Size, Share, and Industry Trends Forecast 2026-2036
Data Acquisition Market Analysis
The capability gap between vertically integrated platform vendors and modular component suppliers is collapsing as Ethernet-based architectures commoditize hardware layers. Schneider Electric SE leverages its EcoStruxure platform to anchor industrial edge deployments across energy-intensive sectors. Yokogawa Electric Corporation competes through specialized high-speed measurement systems for test and validation environments. National Instruments sustains R&D intensity in software-defined instrumentation that bridges laboratory and production floor workflows.
Data acquisition encompasses the systematic sampling of physical signals via analog-to-digital converters, typically operating at resolutions between 12 and 24 bits and sampling rates from kilohertz to megahertz ranges, to translate temperature, pressure, vibration, and electrical phenomena into digital records for analysis, control, and compliance documentation. Ethernet technology leads in bandwidth-intensive process control installations while Bluetooth expands in portable environmental monitoring configurations where cabling constraints dominate deployment costs. Modular form factors capture margin pools in aerospace and automotive test cells where channel count flexibility determines equipment lifecycle economics.
FDA 21 CFR Part 11 requirements shape validation protocols for healthcare data logging systems, while EU AI Act risk classifications impose documentation burdens on autonomous monitoring applications. The EPA mandates emissions data integrity standards that drive environmental monitoring hardware specifications. Stakeholders must weigh software subscription models against perpetual licensing as vendor ecosystems consolidate around cloud-native architectures.
Market Dynamics
Ethernet-based architectures are collapsing the traditional hardware layer differentiation between integrated platform vendors and modular component suppliers, compressing margins and forcing vendors to compete through software ecosystems and vertical application expertise.
Growth Catalysts
- Automotive sensor network expansion:Manufacturers are deploying dense arrays of temperature, pressure, and vibration sensors for real-time vehicle diagnostics and predictive maintenance, driving channel count requirements in test and validation environments.
- EU AI Act compliance mandates:Risk classification documentation requirements for autonomous monitoring systems are compelling industrial operators to upgrade data logging infrastructure with enhanced traceability and audit trail capabilities.
- Germany's industrial automation corridor:Concentrated demand around Munich and Stuttgart from precision manufacturing and automotive OEMs is anchoring high-resolution measurement system deployments.
Market Restraints
- ADC and signal conditioning component concentration:Specialized analog-to-digital converter supply chains concentrate among a limited set of semiconductor foundries, creating vulnerability to capacity constraints.
- FDA 21 CFR Part 11 validation costs:Healthcare and pharmaceutical data logging systems require extensive protocol documentation, extending sales cycles and inflating total cost of ownership.
- Wireless substitution in portable applications:Bluetooth-enabled environmental monitors are capturing share in field-deployed configurations where cabling infrastructure proves prohibitively expensive.
Strategic Opportunities
- Cloud-native architecture migration:Vendors consolidating ecosystems around subscription-based software platforms can capture recurring revenue streams from industrial edge deployments.
- EPA emissions data integrity mandates:Environmental monitoring hardware specifications are tightening, creating specification upgrade cycles for compliance-grade logging systems.
- India's industrial digitization push:PLI scheme incentives for manufacturing automation are stimulating first-time DAQ adoption among domestic automotive and electronics producers.
Industry Challenges
- Embedded firmware security certification:Connected DAQ nodes require IEC 62443 compliance documentation, stretching engineering resources and delaying product releases.
- Multi-protocol integration complexity:Industrial customers demand seamless interoperability between legacy fieldbus installations and modern Ethernet-based measurement networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Acquisition Market |
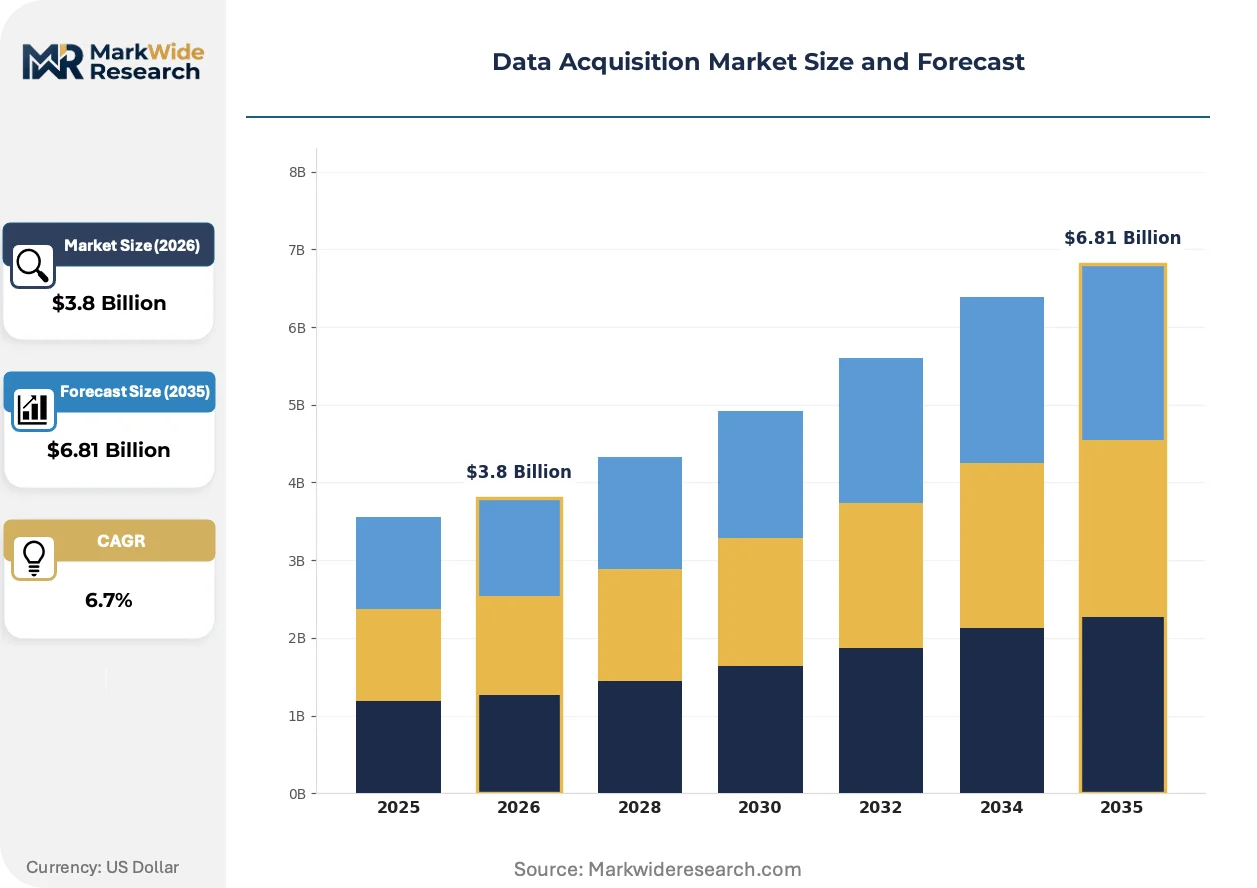
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: USB, RS-232, Ethernet, Bluetooth End User: Manufacturing, Healthcare, Automotive, Telecommunications Application: Remote Monitoring, Process Control, Data Logging, Environmental Monitoring Form Factor: Portable, Stationary, Integrated, Modular |
| Companies Covered | Schneider Electric SE, Yokogawa Electric Corporation, National Instruments, Dewesoft d.o.o, Advantech Co. Ltd., Keysight Technologies, Honeywell International Inc., Teledyne Technologies Incorporated, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Acquisition Market Emerging Trajectories
Software-defined instrumentation is dissolving the boundary between laboratory precision and production floor ruggedness, while regulatory pressure on data integrity is reshaping validation protocols across connected industrial systems.
Time-sensitive networking extensions to standard Ethernet are displacing proprietary industrial fieldbus protocols in bandwidth-intensive process control installations. Automotive test cell operators are adopting TSN-enabled DAQ backbones to synchronize distributed measurement nodes with sub-microsecond precision. This convergence is compressing the traditional separation between R&D instrumentation and manufacturing execution systems.
The EU AI Act's risk-based classification framework is mandating algorithmic transparency documentation for autonomous monitoring applications deployed in healthcare and critical infrastructure. Medical device manufacturers must now maintain detailed records of training data provenance and model validation procedures. High-risk system categories face the most stringent documentation burdens, driving specification upgrades in clinical-grade logging hardware.
Subscription-based software licensing is replacing perpetual ownership models as vendors consolidate ecosystems around cloud-native architectures. Industrial buyers are accepting recurring fees for firmware updates, remote diagnostics, and predictive analytics capabilities. This shift is most pronounced in Germany's automotive and energy-intensive sectors, where total cost of ownership calculations now favor operational expenditure structures.
Data Acquisition Market Segmentation
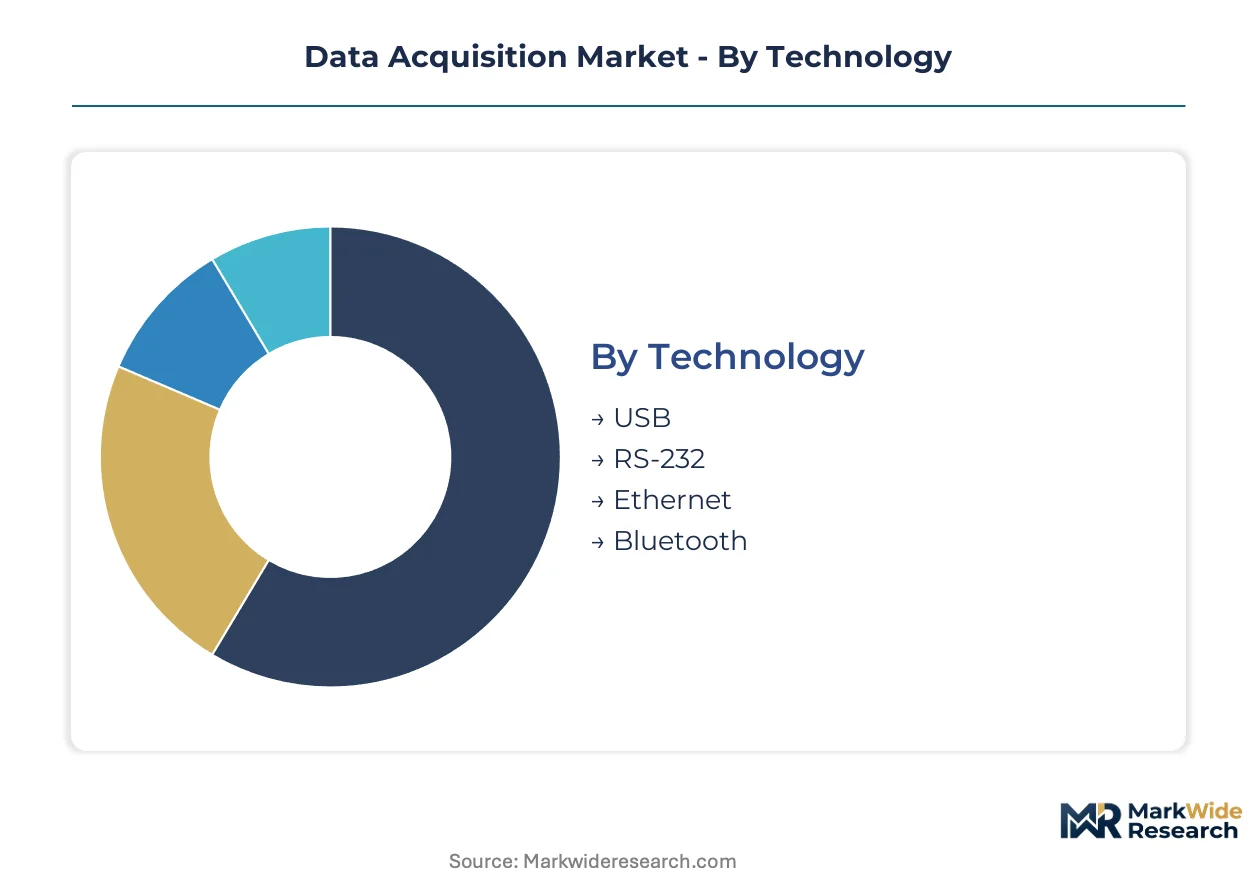
Technology choices determine channel density limits and synchronization precision, while form factor decisions lock in lifecycle economics for aerospace test cells and field environmental deployments. End-user concentration in Germany's automotive corridor and FDA-regulated healthcare systems creates divergent specification requirements across segments.
Technology:
Ethernet commands premium pricing in bandwidth-intensive process installations where sub-microsecond synchronization justifies infrastructure investment.
- Ethernet:Time-sensitive networking extensions enable sub-microsecond synchronization across distributed nodes. Automotive test cells around Stuttgart deploy TSN-enabled backbones for powertrain validation workflows where timing precision determines measurement validity.
- Bluetooth:Low-energy protocols eliminate cabling costs in portable environmental monitoring configurations. Field-deployed air quality sensors across industrial zones favor wireless architectures where trenching and conduit installation would exceed hardware expenditure.
- USB:Plug-and-play connectivity dominates laboratory benchtop instrumentation with moderate channel counts.
- RS-232:Legacy serial interfaces persist in retrofit installations requiring compatibility with existing SCADA infrastructure.
Ethernet holds installed capacity. Bluetooth is rotating up the share rankings.
End User:
Automotive and healthcare sectors generate the steepest specification escalation as EU AI Act and FDA 21 CFR Part 11 compliance harden validation requirements.
- Automotive:Dense sensor arrays for real-time diagnostics demand high-channel-count systems with automotive-grade temperature specifications. Munich-based OEMs specify measurement hardware capable of simultaneous vibration, pressure, and thermal logging across powertrain test beds.
- Healthcare:Clinical-grade data logging requires audit trail documentation and algorithmic transparency for autonomous monitoring. FDA digital health guidance mandates training data provenance records that drive specification upgrades in connected patient monitoring systems.
- Manufacturing:Precision automation corridors concentrate demand for ruggedized edge devices with predictive maintenance analytics.
- Telecommunications:5G infrastructure testing drives high-speed RF measurement requirements in base station validation environments.
Automotive anchors current procurement volume. Healthcare is climbing the fastest as regulatory documentation burdens intensify.
Application:
Remote monitoring applications capture recurring software revenue through cloud-native architectures, while process control demands deterministic real-time performance.
- Process Control:Deterministic loop closure requires guaranteed latency bounds in chemical and energy processing installations. Refinery operators specify SIL-rated measurement chains where signal integrity directly impacts safety system response.
- Remote Monitoring:Subscription-based telemetry platforms enable predictive analytics revenue streams from distributed asset fleets. Wind farm operators across Denmark and Spain deploy cellular-connected vibration sensors with cloud-hosted diagnostic algorithms.
- Data Logging:Compliance-grade archival systems serve EPA emissions monitoring and pharmaceutical batch records.
- Environmental Monitoring:Portable air and water quality instruments face Bluetooth substitution pressure where cabling constraints dominate deployment economics.
Process control maintains the deepest installed base. Remote monitoring is gaining share fastest through recurring revenue models.
Form Factor:
Modular architectures command margin premiums in aerospace validation programs where channel count scalability determines equipment reuse across test campaigns.
- Modular:Hot-swappable chassis accommodate evolving channel requirements without full system replacement. Airbus and Boeing suppliers specify PXI-based architectures for avionics test cells where program phases demand rapid reconfiguration.
- Portable:Battery-powered enclosures with IP ratings serve environmental field crews in emissions auditing and water quality surveillance. EPA inspection protocols favor handheld instruments with GPS tagging and immediate cloud upload.
- Stationary:Rack-mounted systems anchor permanent process control installations with dedicated power and cooling infrastructure.
- Integrated:Purpose-built embedded modules serve OEM equipment where space constraints preclude standard enclosures.
Modular retains the largest deployed base. Portable is ascending the share ladder as wireless substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys Ethernet-based architectures for precision manufacturing validation, while India favors modular USB configurations for cost-sensitive first-time adoption. The United States concentrates healthcare-grade systems under FDA oversight. China scales environmental monitoring networks under dual carbon mandates.
Germany
Automotive powertrain validation and industrial automation anchor demand for time-sensitive networking backbones. The EU AI Act imposes documentation burdens on autonomous monitoring systems deployed in critical infrastructure. Munich and Stuttgart host dense clusters of OEM test cells specifying high-channel-count measurement hardware.
United States
Healthcare data logging and aerospace validation drive specification escalation toward 21 CFR Part 11 compliance. FDA digital health guidance mandates training data provenance records for connected patient monitoring systems. Greater Boston and Southern California concentrate medical device manufacturers upgrading clinical-grade instrumentation.
China
Environmental monitoring networks and semiconductor test facilities absorb high-volume DAQ deployments. MEE emissions data integrity standards tighten hardware specifications for compliance-grade logging systems. The Yangtze River Delta anchors manufacturing automation corridors where edge device adoption accelerates under dual carbon goals.
India
Automotive electronics testing and pharmaceutical batch documentation stimulate first-time modular system procurement. PLI scheme incentives for manufacturing automation reduce capital barriers for domestic producers. Maharashtra and Gujarat host expanding electronics manufacturing clusters specifying entry-level Ethernet configurations.
Japan
Precision instrumentation for robotics validation and automotive quality control sustains demand for high-speed measurement systems. METI industrial digitization guidelines encourage predictive maintenance analytics integration. The Nagoya industrial corridor concentrates Toyota supplier networks deploying synchronized sensor arrays.
Data Acquisition Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes through vertical application expertise and software ecosystem differentiation. The hardware layer has commoditized around Ethernet architectures, compressing margins and forcing competitive separation through firmware capabilities and compliance documentation services. Two strategic archetypes dominate: platform vendors bundling cloud-native subscription models, and measurement specialists anchoring high-speed validation environments. Consolidation pressure manifests through strategic partnerships bridging legacy fieldbus installations with modern Ethernet backbones, and portfolio diversification into predictive analytics software layers.
Among diversified industrial technology groups, Schneider Electric SE and Siemens AG exemplify platform-centric positioning through ecosystem consolidation around edge computing architectures. Yokogawa Electric Corporation occupies a specialist position exemplifying high-speed measurement system expertise for test and validation environments. National Instruments represents the software-defined instrumentation archetype bridging laboratory precision with production floor deployment workflows. These three companies illustrate the competitive tension between integrated platform breadth and focused measurement specialization.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| National Instruments |
| Dewesoft d.o.o |
| Advantech Co. Ltd. |
| Keysight Technologies |
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for 24-bit analog-to-digital converters concentrate pricing power among Taiwanese and German foundry suppliers, while automotive OEMs in Stuttgart and Munich negotiate multi-year offtake agreements to lock in channel density for powertrain validation programs.
Pricing Analysis
Long-term offtake contracts dominate procurement for high-channel-count Ethernet systems in automotive test cells, while spot purchasing prevails for portable Bluetooth modules in environmental field deployments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare systems from industrial-grade configurations and entry-level USB benchtop instruments. Cost compression in the standard tier is intensifying because Ethernet hardware commoditization erodes differentiation. Healthcare buyers demonstrate the lowest price sensitivity due to 21 CFR Part 11 compliance requirements, whereas Indian electronics manufacturers exhibit acute sensitivity to upfront capital expenditure.
Supply Chain Analysis
Strategic stockpiling of specialized ADCs and signal conditioning components characterizes procurement behavior among aerospace validation contractors, contrasting with just-in-time inventory practices for standard Ethernet interface modules. Manufacturing concentrates in Taiwan, Germany, and the United States for precision converter silicon, while final system assembly distributes across China, Mexico, and Hungary. Raw material dependencies include rare-earth elements for magnetic sensors, high-purity copper for signal integrity, and epoxy substrates for ruggedized enclosures. Single-source vulnerability in 24-bit delta-sigma ADC fabrication creates exposure to foundry capacity constraints. Distribution runs through authorized industrial automation distributors and direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing as Ethernet architectures commoditize, yet firmware subscription and predictive analytics services expand at multiples of base equipment growth, creating a service-attach opportunity that restructures vendor economics toward recurring revenue.
For Market Incumbents: Compound ecosystem lock-in through cloud-native platform consolidation and embedded firmware security certification investments that stretch engineering resources at smaller competitors. Threat from modular component suppliers collapsing the traditional hardware differentiation layer demands defensive vertical integration into specialized measurement silicon. Priority lever rests on predictive analytics software layers that capture margin pools beyond commoditized sensor interfaces. For New Entrants and Emerging Players: Firmware update latency in legacy installations presents a service-layer gap where incumbents under-serve industrial operators with aging fieldbus infrastructure. White-space targets include India's PLI-stimulated first-time adoption corridors and Bluetooth-enabled environmental monitoring configurations where cabling constraints dominate deployment economics. Most penetrable segment is cost-sensitive modular USB systems for domestic automotive electronics testing in Maharashtra and Gujarat. Go-to-market angle emphasizes subscription-based telemetry platforms with cellular connectivity for distributed asset fleets. For Investors and Strategic Acquirers: Long-term, this sits as a software-transition play because recurring revenue from firmware subscriptions and predictive analytics will dominate value creation as hardware margins compress toward commodity levels. Acquisition target archetype includes measurement specialists with validated healthcare compliance documentation and established automotive OEM relationships. Signal to watch is TSN-enabled backbone deployment velocity in European automotive test cells as indicator of infrastructure upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Captures recurring revenue from Stuttgart automotive OEMs adopting subscription telemetry models. |
| TSN-Enabled Backbone Deployment | Enables sub-microsecond synchronization for Munich powertrain validation workflows. |
| FDA 21 CFR Part 11 Certification Investment | Extends sales cycles but locks in healthcare procurement committees with audit trail requirements. |
| Backward Integration into ADC Silicon | Reduces exposure to Taiwanese foundry capacity constraints for 24-bit precision converters. |
| Predictive Analytics Software Development | Targets wind farm operators in Denmark and Spain with cloud-hosted diagnostic algorithms. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with test cell engineers, biomedical equipment procurement managers, industrial automation system integrators, and firmware development leads; and secondary validation against SEC 10-K filings, EU AI Act regulatory documentation, FDA 510(k) submission databases, and automotive OEM supplier qualification records. Bottom-up channel count estimates from aerospace and automotive validation programs triangulated against top-down vendor revenue segmentation.
Across the analysis window, the forecasting framework modeled technology adoption by interface protocol, form factor scalability, end-user vertical, and regional regulatory cluster. CAGRs derived from weighted average of historical deployment trajectories and projected compliance-driven upgrade cycles. Industry-specific inputs included EU AI Act risk classification implementation timelines and EPA emissions data integrity mandate enforcement intensity.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11 enforcement and EU AI Act documentation requirements; material policy shifts would require re-modeling compliance cost burdens and sales cycle durations. Revision becomes warranted when TSN standard adoption in automotive test cells crosses critical mass thresholds or when ADC foundry capacity utilization signals sustained constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Temperature Loggers Market