
 Mobile Satellite Services (MSS) Market | 2026-2036
Mobile Satellite Services (MSS) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Satellite Services (MSS) Market Analysis
Direct-to-device distribution channels is narrowing as constellation operators bypass legacy ground station networks. Iridium Communications leverages its cross-linked L-band architecture to sustain pole-to-pole coverage for government and maritime clients. Viasat competes through high-throughput Ka-band satellites that anchor broadband services for remote energy installations. Globalstar differentiates with specialized IoT messaging products that occupy niche asset-tracking segments.
Mobile Satellite Services deliver wireless connectivity via orbiting transponders operating across L-band, Ku-band, C-band, and Ka-band frequency allocations, enabling voice, data, and video transmission beyond terrestrial infrastructure reach. Broadband services command the largest revenue pool among service types due to enterprise and government hunger for high-speed remote access, while IoT applications represent the fastest-expanding application category as sensor networks proliferate across maritime and energy assets. L-band technology leads in reliability for mission-critical defense and aerospace end users, whereas Ka-band systems capture margin-rich commercial broadband contracts.
The FCC governs spectrum allocation and orbital slot coordination for U.S.-based operators, while the ITU coordinates international frequency assignments and interference mitigation protocols. The EU's Radio Spectrum Policy Programme and national regulators such as Ofcom in the United Kingdom shape market access conditions for European service providers. Stakeholders must monitor evolving spectrum sharing mandates and low-Earth orbit debris mitigation standards that will determine constellation scalability and capital deployment timelines.
Market Dynamics
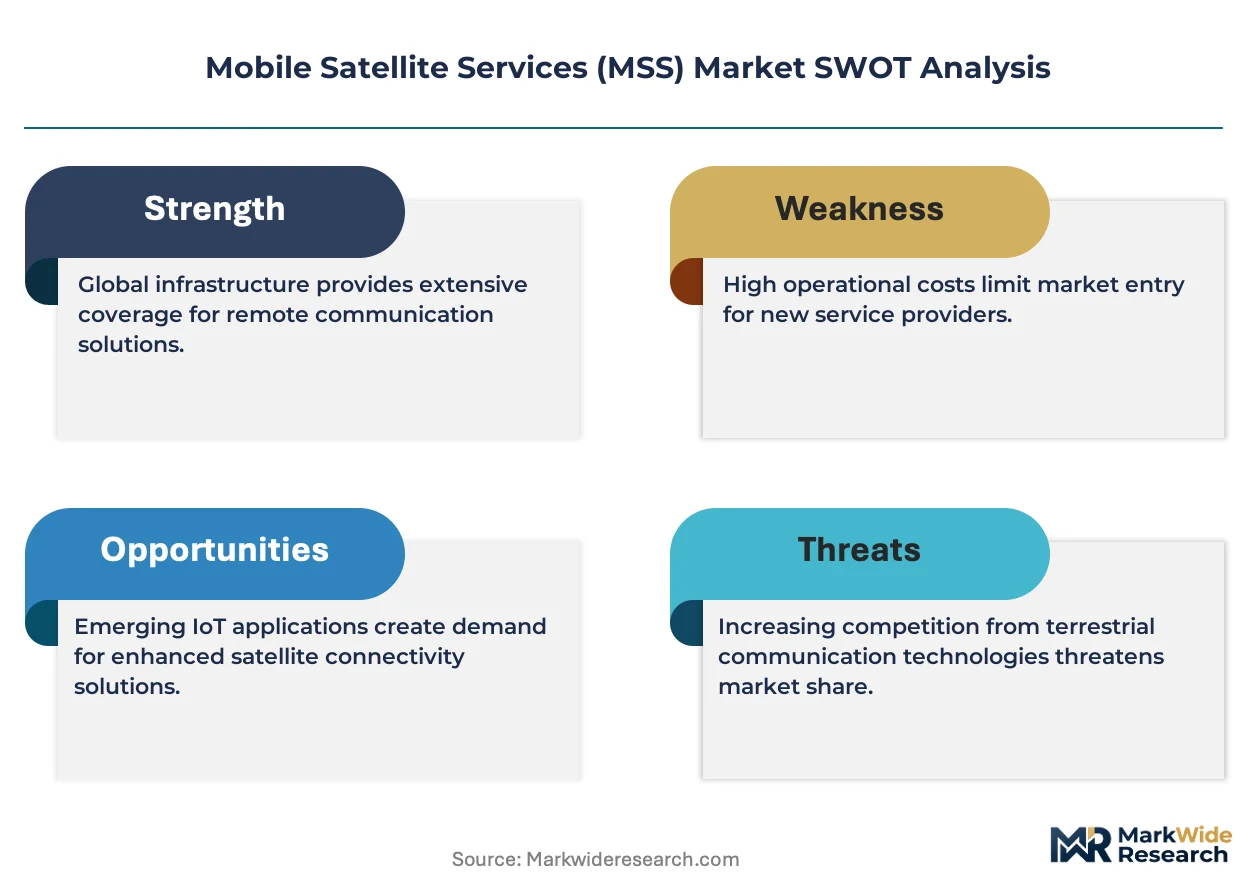
The FCC's streamlined licensing framework for non-geostationary orbit systems is compressing competitive entry timelines and forcing legacy operators to accelerate constellation refresh cycles or risk displacement by capital-rich newcomers.
Growth Catalysts
- Rural broadband mandates:United States federal connectivity programs are channeling procurement dollars toward MSS providers capable of serving unserved territories beyond fiber economics.
- Defense secure communications procurement:NATO member states are expanding classified satellite bandwidth contracts for pole-to-pole coverage requirements.
- L-band reliability premium:Mission-critical aerospace and maritime operators prioritize proven L-band architectures for safety-of-life applications over unproven alternatives.
Market Restraints
- Spectrum coordination complexity:ITU interference mitigation protocols create multi-year delays for new constellation entrants seeking international frequency assignments.
- Launch capacity bottlenecks:Concentrated heavy-lift provider geography limits deployment velocity for capital-ready operators.
- Terrestrial 5G substitution:Expanding cellular coverage in coastal zones and aviation corridors erodes addressable market for legacy MSS voice services.
Strategic Opportunities
- Direct-to-device convergence:Smartphone-native satellite messaging partnerships between constellation operators and handset manufacturers are opening consumer segments previously unreachable through dedicated terminal sales.
- IoT sensor network proliferation:Energy and maritime asset operators are deploying machine-to-machine terminals for remote monitoring where cellular backhaul remains uneconomical.
- EU spectrum harmonization:The Radio Spectrum Policy Programme is creating unified licensing conditions for cross-border MSS service delivery.
Industry Challenges
- Orbital debris compliance:Emerging low-Earth orbit mitigation standards are forcing constellation designers to incorporate propulsion and de-orbit capabilities that inflate unit spacecraft costs.
- Legacy system integration:Government clients require backward compatibility with existing secure terminals, constraining architecture flexibility for next-generation networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Satellite Services (MSS) Market |
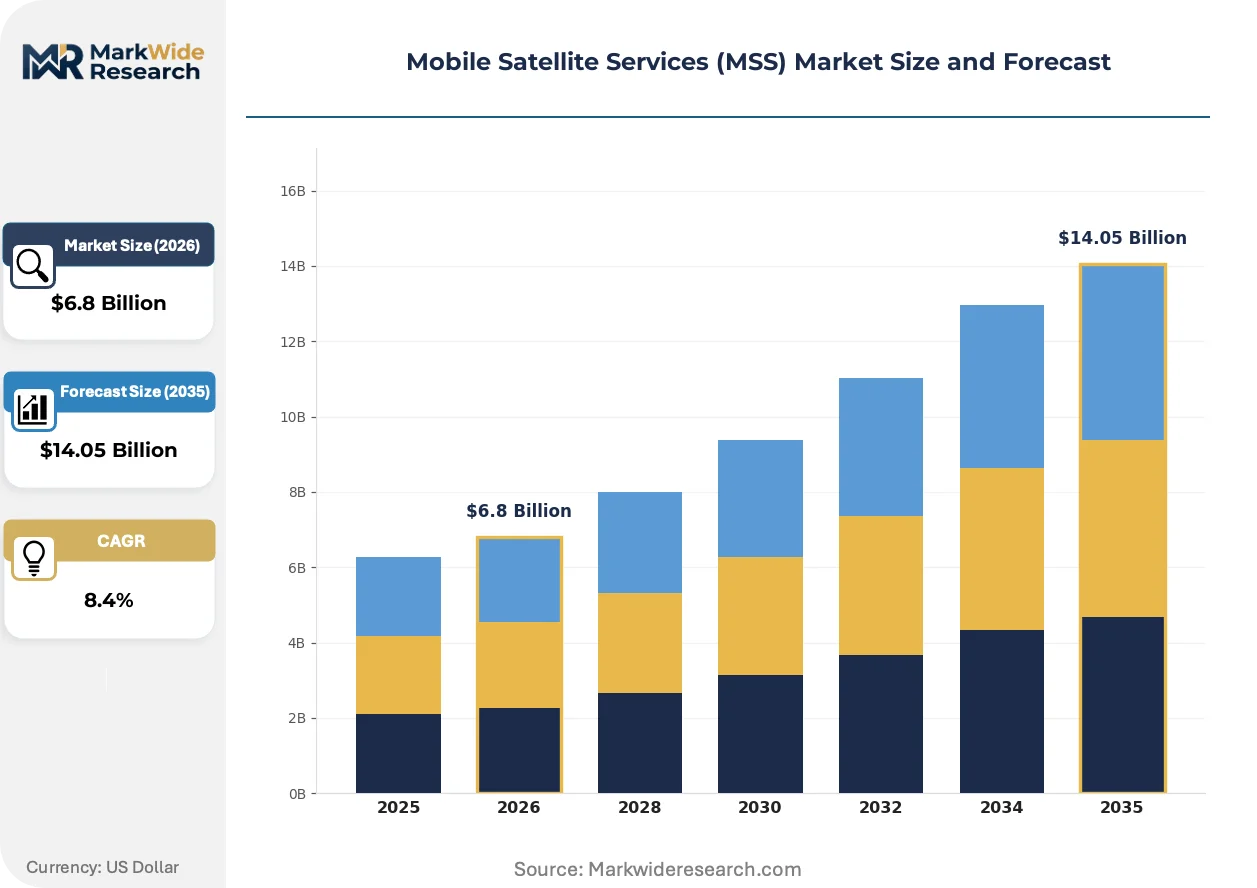
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Voice, Data, Video End User: Aerospace, Maritime, Defense, Energy Technology: Ku-Band, C-Band, Ka-Band, L-Band Application: Telecommunications, Remote Sensing, Broadcasting, IoT |
| Companies Covered | Inmarsat, Iridium Communications, Globalstar, Viasat, SES, Intelsat, Thuraya Telecommunications Company, Telesat, EchoStar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Satellite Services (MSS) Market Emerging Trajectories
Constellation operators are abandoning traditional ground station hierarchies in favor of direct-to-device architectures that compress service delivery paths and reshape competitive economics across consumer and enterprise segments.
Software-defined radio payloads are digitizing frequency agility and beam-forming capabilities aboard individual spacecraft. Maritime and aviation fleet operators are retrofitting terminals to exploit these dynamic capacity allocations. This compression of hardware specificity into reprogrammable firmware is digitizing how MSS providers manage spectrum scarcity across contested orbital slots.
The FCC's streamlined small satellite licensing rules are compressing authorization timelines for non-geostationary orbit deployments. This regulatory acceleration is enabling new entrants to achieve operational constellations faster than legacy licensing frameworks permitted. Ka-band broadband providers targeting remote energy installations are responding by front-loading capital deployment to secure first-mover orbital positions.
Enterprise buyers are unbundling long-term service contracts from dedicated terminal procurement. Energy majors and shipping lines now source connectivity on usage-adjusted terms while retaining equipment flexibility. This shift from bundled to unbundled procurement is most pronounced in United States government contracting, where agencies now mandate separate satellite bandwidth and ground infrastructure awards.
Mobile Satellite Services (MSS) Market Segmentation
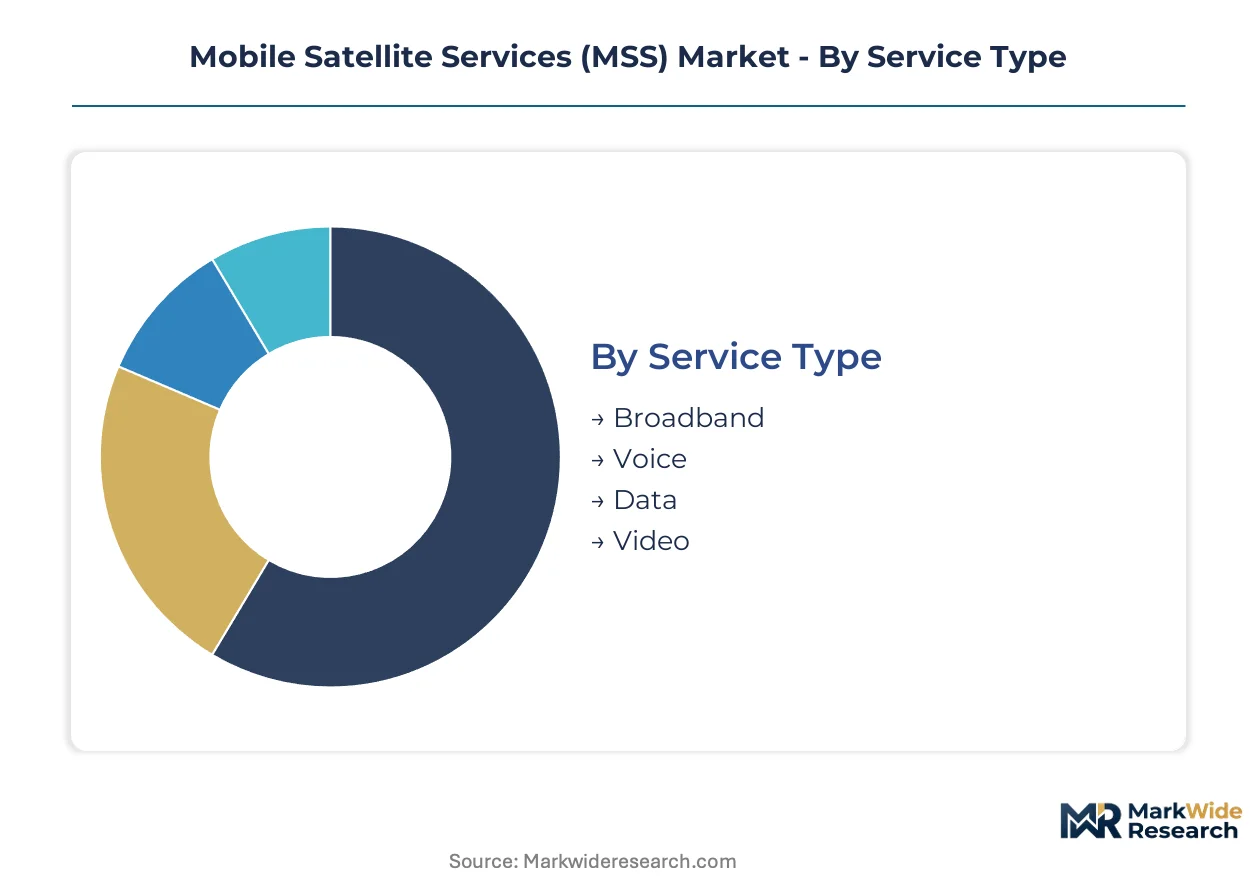
MSS providers configure service portfolios around frequency economics, terminal mobility requirements, and mission-critical reliability thresholds. Segmentation discipline separates commodity bandwidth from premium safety-of-life contracts and identifies where constellation capital earns the highest returns.
Service Type:
Cost tier separates commodity connectivity from premium mission-critical services, with pricing power concentrating in guaranteed availability segments.
- Broadband:High-throughput data pipes deliver internet access to remote enterprise sites and government installations beyond fiber reach. Energy majors in the United States and maritime fleet operators absorb the majority of contracted capacity, driven by operational technology bandwidth requirements for remote monitoring and crew welfare.
- Voice:Circuit-switched and VoIP satellite telephony serves aviation crews, maritime personnel, and expeditionary military units where cellular roaming fails. Demand concentrates in polar routes and open-ocean corridors where L-band reliability justifies per-minute premiums over terrestrial alternatives.
- Data:Store-and-forward messaging and low-bandwidth telemetry support machine-to-machine applications across distributed infrastructure networks.
- Video:Occasional-use and dedicated satellite newsgathering circuits serve broadcasters covering remote events and disaster zones.
Broadband commands the established base. The steepest expansion runs through Data.
End User:
Application context determines terminal specifications, with aerospace and maritime operators imposing the most stringent certification requirements.
- Defense:Classified communications networks require anti-jam waveforms, cross-linked constellation resilience, and sovereign ground segment control. NATO procurement offices in the United States, United Kingdom, and Germany are expanding multi-year bandwidth contracts for pole-to-pole coverage of expeditionary forces.
- Energy:Offshore platforms, pipelines, and remote drilling camps demand redundant connectivity for SCADA systems and emergency response. North Sea operators and Permian Basin producers are standardizing MSS backup for terrestrial fiber failures.
- Aerospace:Commercial aviation and business jet fleets require seamless cabin connectivity across oceanic and polar routes.
- Maritime:Merchant shipping, fishing fleets, and yacht operators combine regulatory safety systems with crew broadband consumption.
Defense commands the established base. Energy shows the steepest expansion trajectory.
Technology:
Frequency allocation dictates propagation characteristics, terminal size, and interference resilience across contested spectrum environments.
- L-Band:Lower frequencies penetrate weather, foliage, and building materials with minimal signal attenuation. Iridium and Inmarsat networks serve aviation safety services and maritime distress systems where link reliability overrides bandwidth constraints.
- Ka-Band:High-frequency spot beams concentrate power for broadband throughput to small aperture terminals. Viasat and emerging constellations target remote energy installations and government field offices with fiber-competitive speeds.
- Ku-Band:Traditional FSS frequencies support broadcast distribution and enterprise VPNs with established ground infrastructure.
- C-Band:Resilient rain-fade performance sustains tropical region connectivity and interference-resistant government networks.
L-Band commands the established base. Ka-Band climbs the fastest.
Application:
Customer type separates infrastructure operators from sensor network deployers, with procurement patterns diverging between long-term contracts and usage-based consumption.
- IoT:Low-power wide-area terminals transmit asset location, environmental conditions, and equipment status from unmanned remote sites. Globalstar's specialized messaging products and emerging direct-to-device services are capturing maritime container tracking and energy pipeline monitoring contracts.
- Telecommunications:Backhaul extension and network redundancy services support mobile operators and ISPs serving rural populations.
- Remote Sensing:Earth observation downlink and command uplink services complement dedicated remote sensing constellations.
- Broadcasting:Content distribution and contribution circuits sustain television and radio transmission beyond terrestrial infrastructure.
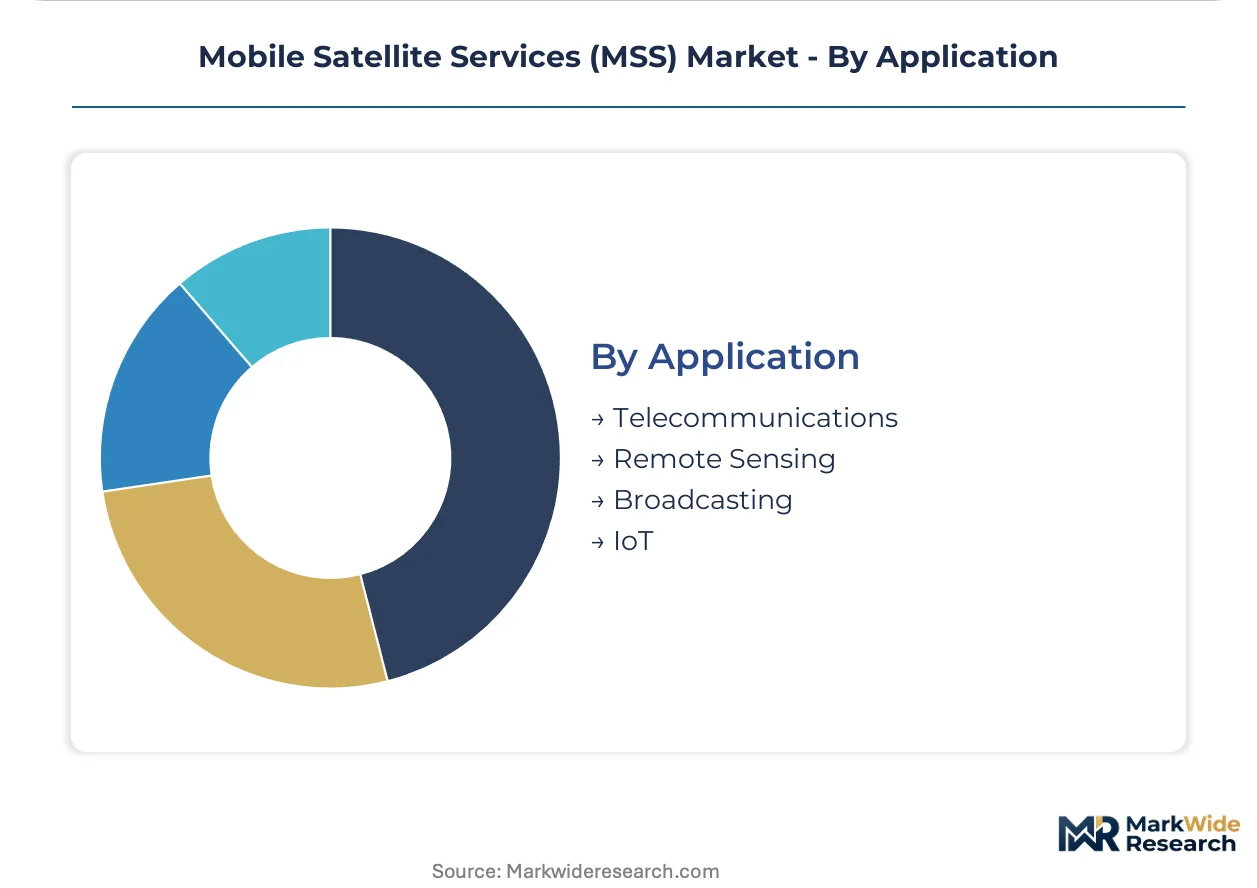
Telecommunications commands the established base. IoT gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Pacific Coast submarine cable landing stations and Gulf Coast energy export terminals create dual anchor points for MSS demand. Government bandwidth procurement flows through defense installations in Colorado and maritime gateways in Louisiana. Commercial adoption clusters around aerospace corridors linking Seattle to Los Angeles.
United States
Federal rural broadband programs and classified defense contracts drive procurement volume. The FCC streamlined small satellite licensing rules compress authorization timelines for non-geostationary orbit deployments. Colorado Springs hosts concentrated defense communications infrastructure serving NORAD and Space Command requirements.
United Kingdom
North Sea offshore energy platforms and transatlantic aviation corridors generate sustained connectivity demand. Ofcom coordinates spectrum allocation under EU Radio Spectrum Policy Programme harmonization mandates. London's financial district anchors maritime insurance and shipping headquarters that specify MSS backup for fleet operations.
Germany
Automotive manufacturer telematics requirements and defense export contracts shape service specifications. The national regulator implements EU spectrum frameworks for cross-border MSS coordination. Bavaria's aerospace cluster around Munich integrates satellite terminals into military vehicle and commercial aircraft production lines.
Japan
Coastal fishing fleet modernization and disaster resilience protocols drive terminal deployment. METI coordinates industrial policy supporting domestic satellite operator participation in regional consortia. Tokyo Bay maritime traffic control systems integrate L-band safety services for dense commercial shipping lanes.
Australia
Mining operations in the Pilbara and remote pastoral stations require beyond-cellular telemetry infrastructure. The national spectrum regulator aligns with ITU protocols for southern hemisphere interference coordination. Perth serves as the operational hub for Indian Ocean maritime connectivity serving offshore energy and container shipping routes.
Mobile Satellite Services (MSS) Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying antenna modules and radio frequency subsystems. The vendor base concentrates around constellation operators with orbital slot holdings and ground segment providers with terrestrial gateway networks. Two strategic archetypes dominate: established L-band incumbents with cross-linked architectures and Ka-band challengers deploying high-throughput spot beams. Competitive moves center on spectrum acquisition through regulatory proceedings and direct-to-device partnerships bypassing legacy terminal distribution.
Within the established operator tier, Iridium Communications and Globalstar represent divergent frequency strategies, while Viasat anchors the high-throughput broadband segment. Iridium's cross-linked L-band architecture exemplifies pole-to-pole coverage capabilities for government and maritime safety applications. Globalstar occupies a position in specialized IoT messaging and asset-tracking niches where low-power terminals predominate. Viasat sits within the Ka-band expansion vector targeting energy installations and remote enterprise sites with fiber-competitive throughput. These three operators illustrate how spectrum allocation choices and constellation architecture decisions segment competitive positioning across defense, maritime, and energy verticals.
| Leading Market Players |
|---|
| Inmarsat |
| Iridium Communications |
| Globalstar |
| Viasat |
| SES |
| Intelsat |
| Thuraya Telecommunications Company |
| Telesat |
| EchoStar Corporation |
| Others |
Supply Flow & Price Mechanics
Launch capacity undercapacity across heavy-lift provider geography constrains constellation deployment velocity, compressing supplier bargaining power while inflating procurement premiums for bandwidth-hungry energy and defense clients.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates mission-critical L-band safety services from commodity broadband and low-power IoT messaging tiers. Price differentiation rests on certification grade for aviation distress systems and volume scale for maritime fleet contracts. Cost compression in standard broadband tiers is intensifying because Ka-band spot-beam providers front-load capacity to secure orbital positions. Government defense agencies show lowest price sensitivity, while regional maritime operators absorb highest relative cost pressure.
Supply Chain Analysis
Contract manufacturing concentration for satellite payloads sits with North American and European space-qualified component foundries, with final assembly gravitating toward facilities in the United States, France, and Germany. Raw material dependencies center on gallium arsenide substrates, radiation-hardened semiconductors, and specialized propulsion systems. Single-source vulnerability runs through concentrated launch provider geography for heavy-lift capacity. Distribution runs through direct-to-device partnerships with handset manufacturers alongside legacy ground station network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital slot scarcity and spectrum coordination expertise constitute the binding constraint on scalable MSS deployment, rewarding operators with regulatory navigation capabilities and established ITU filing precedence.
For Market Incumbents: Pre-empt displacement by capital-rich newcomers through accelerated constellation refresh cycles and exclusive direct-to-device partnerships with smartphone manufacturers. Prioritize backward integration into radiation-hardened component supply to reduce launch delay exposure. Secure additional L-band spectrum filings before FCC streamlined licensing enables rival entrants. For New Entrants and Emerging Players: Pursue white-space opportunities in maritime container tracking and energy pipeline monitoring where low-power IoT terminals face limited incumbent saturation. Target Australian mining operations and Japanese fishing fleet modernization as most penetrable geographies. Deploy usage-adjusted procurement models to unbundle service contracts from dedicated terminal sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among constellation operators with cross-linked L-band architectures serving multi-year government bandwidth contracts. Long-term viability favors platforms with de-orbit compliance capabilities and sovereign ground segment control. Acquisition target archetype: specialized IoT messaging providers with established sensor network deployments. Monitor ITU interference mitigation protocol delays as inflection indicator for competitive entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Device Partnership | Smartphone-native satellite messaging compresses distribution paths and unlocks consumer segments beyond dedicated terminal markets. |
| Constellation Refresh Acceleration | Software-defined radio payload upgrades digitize frequency agility and extend spacecraft operational lifespans against rival entrants. |
| Spectrum Acquisition Filing | Pre-emptive ITU coordination secures international frequency assignments before streamlined FCC licensing enables competitor orbital slots. |
| IoT Sensor Network Expansion | Low-power wide-area terminal deployment captures maritime container tracking and energy pipeline monitoring contracts with minimal terrestrial backhaul. |
| Backward Integration into Components | In-house production of radiation-hardened semiconductors reduces launch delay exposure and insulates against single-source supplier concentration. |
Methodological Framework
The analysis maps L-band, Ka-band, Ku-band, and C-band service tiers, each validated through constellation operators, defense procurement officers, maritime fleet managers, and energy sector connectivity directors. Primary interviews with satellite terminal manufacturers and ground segment providers combined with secondary validation from FCC licensing databases, ITU frequency coordination filings, and EU Radio Spectrum Policy Programme documentation. Bottom-up capacity deployment models and top-down bandwidth demand projections triangulate market sizing.
Assumptions held fixed include existing spectrum allocation frameworks and debris mitigation standards, while launch cost trajectories and direct-to-device partnership penetration were varied across scenarios. Segmentation dimensions modeled encompass frequency band, service type, end-user vertical, and application category throughout the forecast period. CAGRs derive from contracted capacity absorption rates and terminal shipment trajectories, with defense procurement cycles and rural broadband program disbursement schedules as industry-specific inputs.
Sensitivities concentrate around ITU interference mitigation delays, launch provider capacity constraints, and terrestrial 5G coastal coverage expansion. Forecasts reflect documented assumptions regarding constellation deployment timelines and spectrum coordination outcomes. Quarterly review of FCC licensing velocity, NATO bandwidth contract awards, and direct-to-device partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Global GPON Technology Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Brazil Telecom Market
Telecommunications
Cambodia ICT Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Nigeria Telecom Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Iran Telecom Market
Telecommunications
Optical Fronthaul Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Fixed Voice Market
Telecommunications
MVNO Market