
 Spain Digital Twin Market | 2026-2036
Spain Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Digital Twin Market Insights
High-fidelity physics-based simulation is unwinding legacy monitoring approaches across Spanish industrial assets. Telefónica Tech leverages its nationwide 5G infrastructure to deliver edge-connected twin deployments for utility clients. Indra sustains defense-aerospace dominance through classified digital thread programs. R2M Solution Spain S.L. anchors Barcelona's smart-city ecosystem with building information modeling integrations.
A digital twin constitutes a dynamic virtual representation of a physical asset, system, or process, maintained through real-time sensor telemetry and physics-based modeling engines that synchronize state variables across operational lifecycles. The construct enables predictive intervention, scenario testing, and lifecycle optimization without physical disruption. Software and platform segments command margin concentration due to recurring license architectures and integration complexity. Manufacturing end users exhibit the steepest adoption slope as Spanish automotive and food-processing plants retrofit legacy lines. IoT and cloud computing technologies underpin scalable architectures, though machine learning layers differentiate premium offerings through autonomous anomaly detection.
Spain's national AI strategy imposes algorithmic transparency mandates on autonomous decision systems, while BIS-aligned cybersecurity standards govern critical infrastructure digitalization. The EU AI Act classifies predictive maintenance in energy and transport as high-risk, requiring conformity assessments before operational deployment. Stakeholders must monitor evolving EN ISO 23247 interoperability standards and assess whether their data architectures satisfy upcoming cross-border digital product passport requirements.
Market Dynamics
Physics-based simulation fidelity is displacing rule-based monitoring across Spanish industrial assets, while the EU AI Act's high-risk classification mandates reshape deployment timelines for autonomous maintenance systems.
Growth Catalysts
- EU AI Act Conformity Pathways:High-risk system classification for predictive maintenance in energy infrastructure creates certified vendor preference, accelerating procurement standardization among Spanish utilities.
- 5G Edge Architecture:Telefónica Tech's nationwide infrastructure enables millisecond-latency twin synchronization for distributed manufacturing assets, collapsing deployment friction previously associated with cloud-only models.
- Aerospace Cluster Concentration:Madrid's defense-aerospace corridor sustains classified digital thread programs, generating spillover demand for dual-use simulation platforms across adjacent automotive suppliers.
Market Restraints
- Interoperability Fragmentation:EN ISO 23247 standardization gaps force costly custom integration layers between legacy SCADA systems and modern twin platforms, compressing project margins.
- Specialized Talent Scarcity:Spain produces insufficient mechatronics engineers with combined physics modeling and machine learning competencies, inflating implementation timelines.
- Cybersecurity Certification Burden:BIS-aligned critical infrastructure standards impose multi-month assessment windows before operational deployment, delaying revenue recognition.
Strategic Opportunities
- Andalusian Renewable Integration:Concentrated solar power and offshore wind construction creates greenfield demand for asset lifecycle twins without legacy system drag.
- Digital Product Passport Mandates:Upcoming EU cross-border traceability requirements position Spanish food-processing exporters for compliance-driven twin adoption.
- Building Information Modeling Convergence:Fusion of BIM with operational twins opens municipal infrastructure retrofit markets anchored by Barcelona's smart-city procurement frameworks.
Industry Challenges
- Multiphysics Model Calibration:Spanish automotive suppliers struggle to align finite element models with actual thermal and vibration signatures from heterogeneous legacy equipment.
- Data Sovereignty Architecture:National AI strategy transparency mandates conflict with proprietary algorithm protection, forcing architectural compromises that degrade inference performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Digital Twin Market |
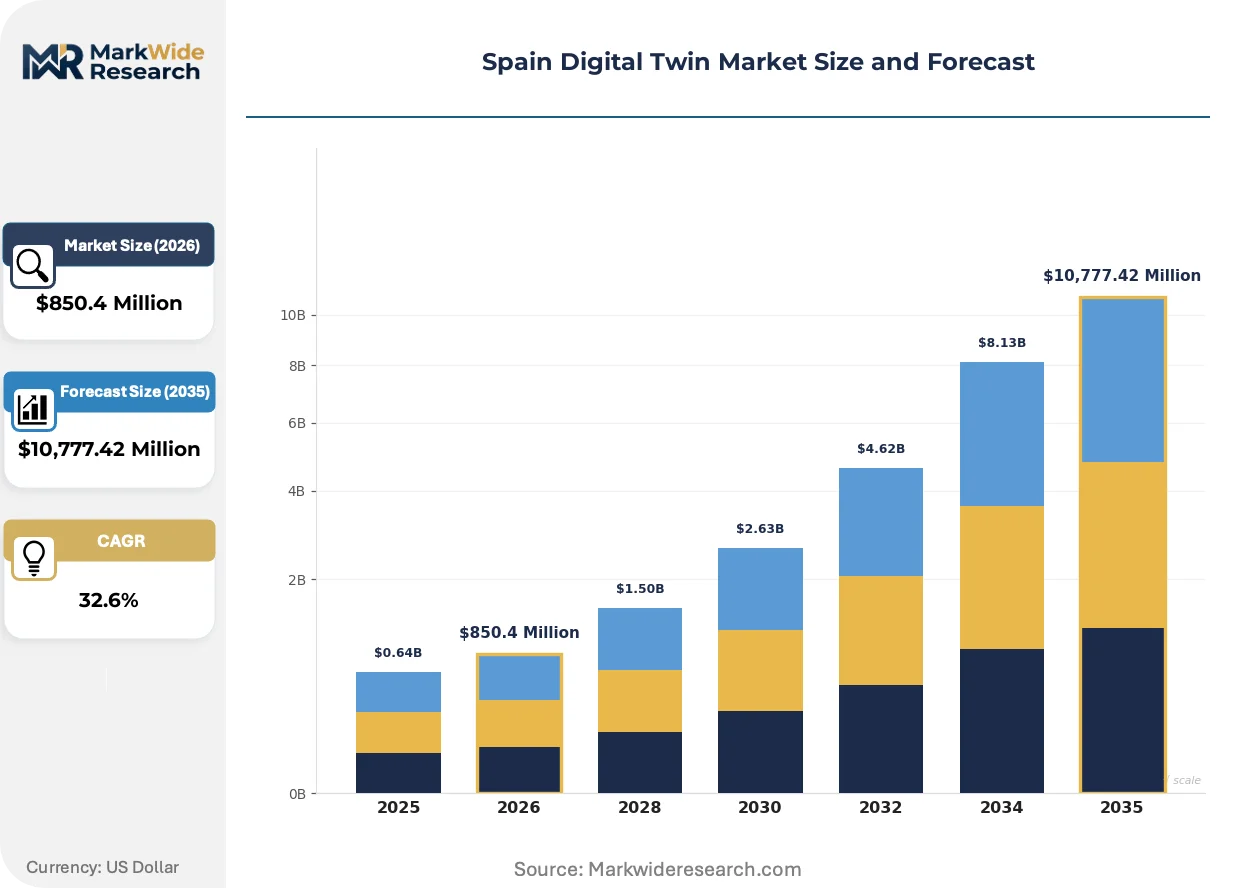
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $10,777.42 Million |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Platform End User: Aerospace, Manufacturing, Healthcare, Construction Technology: Machine Learning, IoT, Cloud Computing, Simulation Application: Facility Management, Asset Monitoring, Product Development, Performance Optimization |
| Companies Covered | R2M Solution Spain S.L., piensas.xyz, STOWAI, Telefónica Tech, Indra, URBIM, Agrointel, Iberdrola, Zenit Solar Tech SL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Digital Twin Market Trends and Innovations
Real-time sensor fusion architectures are compressing the latency gap between physical state changes and virtual model updates, enabling closed-loop intervention cycles previously confined to simulation environments.
Generative physics engines are displacing pre-calculated lookup tables in Spanish automotive paint-shop simulations. Tier-1 suppliers adopt neural surrogate models that learn thermodynamic behaviors from sparse sensor grids, collapsing computational requirements for real-time coating thickness optimization. This displacement enables edge deployment without dedicated HPC infrastructure, democratizing access among mid-cap component manufacturers.
Spain's National Artificial Intelligence Strategy imposes algorithmic explainability mandates on autonomous decision systems deployed in critical infrastructure. Industrial operators must document model decision pathways for regulatory inspection, forcing architectural investments in interpretable surrogate layers. Energy and transport verticals face the steepest compliance burden, with conformity assessment timelines now embedded in procurement specifications.
Spanish food-processing multinationals are unbundling after-sales service from equipment procurement, demanding performance-guaranteed twin subscriptions from OEMs. Machinery suppliers pivot from capital sales to availability-based contracts, absorbing operational risk in exchange for recurring telemetry access. This shift concentrates most visibly in Catalonia's dairy and meat-processing corridors, where margin pressure accelerates vendor consolidation.
Spain Digital Twin Market Segmentation
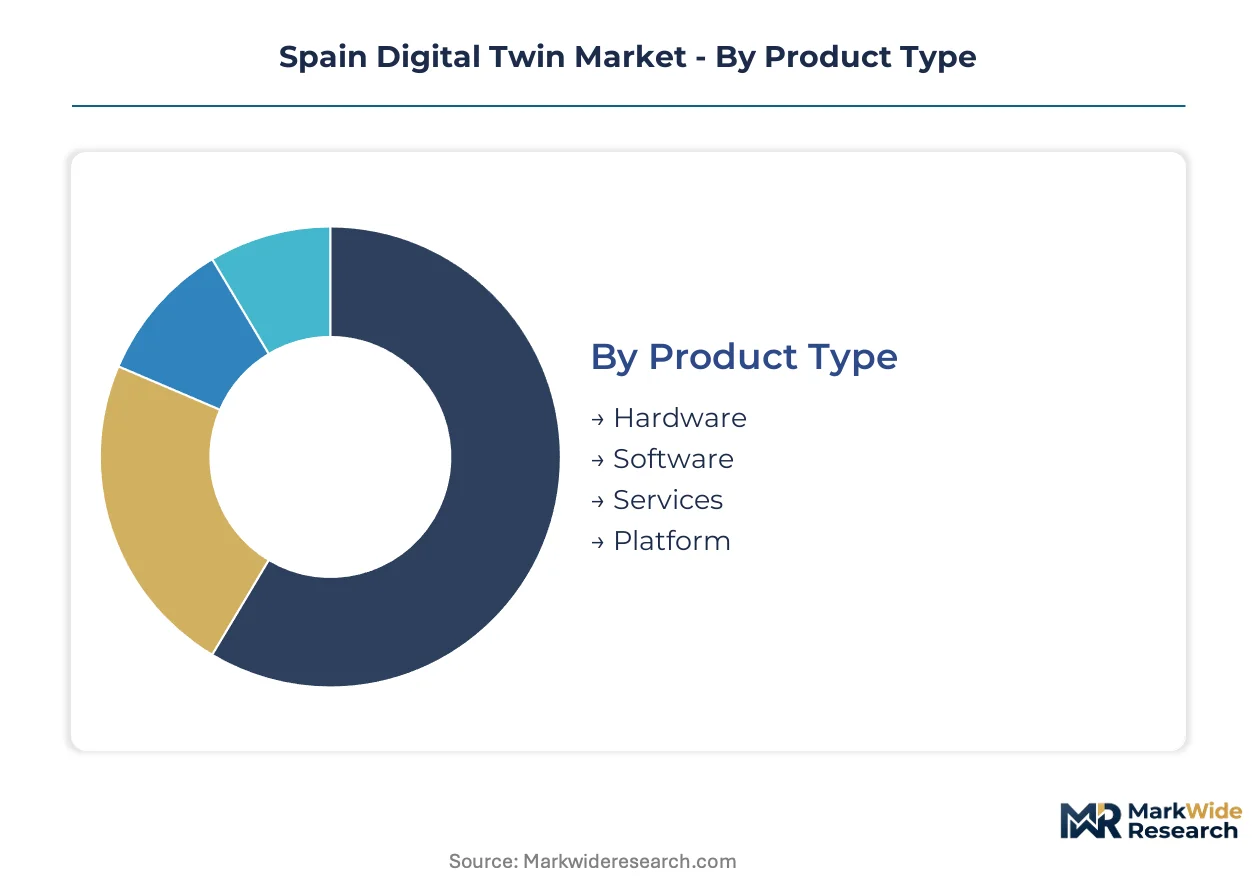
Digital twin architectures fragment across four distinct dimensions in Spain, each revealing divergent margin structures and deployment timelines. Product type determines recurring revenue potential, while end-user verticals expose varying regulatory exposure under the EU AI Act.
Product Type:
Software and platform deployments concentrate in Madrid's aerospace corridor and Barcelona's smart manufacturing belt, while hardware integration remains tethered to domestic system integrators.
- Software:Recurring license architectures dominate revenue models, with physics-based modeling engines requiring continuous calibration against live sensor feeds. Madrid's defense-aerospace cluster generates premium demand for classified digital thread programs, though BIS-aligned cybersecurity certifications extend sales cycles.
- Platform:Integration complexity sustains margin concentration, as vendors must orchestrate multivendor sensor networks and legacy SCADA bridges. Barcelona's smart-city procurement frameworks anchor municipal adoption, with building information modeling convergence accelerating retrofit demand.
- Hardware:Edge computing nodes and industrial gateways from domestic electronics suppliers.
- Services:Implementation and calibration contracts tied to EN ISO 23247 interoperability mandates.
Software holds the largest share; momentum sits with Platform.
End User:
Manufacturing exhibits the steepest adoption slope, yet aerospace commands the highest contract values per deployment.
- Manufacturing:Spanish automotive and food-processing plants retrofit legacy lines with predictive maintenance twins, absorbing operational risk through availability-based contracts. Catalonia's dairy and meat-processing corridors drive vendor consolidation as multinationals unbundle after-sales service from equipment procurement.
- Aerospace:Classified digital thread programs in Madrid's defense corridor generate spillover demand for dual-use simulation platforms. Indra sustains dominance through sovereign capability requirements, though export controls limit technology transfer.
- Healthcare:Hospital asset tracking and medical device lifecycle management under Spain's national AI strategy transparency mandates.
- Construction:Building information modeling integrations for municipal infrastructure retrofits.
Manufacturing dominates volume; aerospace claims the highest value per deployment.
Technology:
Cloud computing underpins scalable architectures, though machine learning layers differentiate premium offerings through autonomous anomaly detection.
- IoT:Real-time sensor telemetry forms the data foundation, with Telefónica Tech's nationwide 5G infrastructure enabling millisecond-latency edge synchronization. Utility clients deploy distributed sensing grids without dedicated fiber backhaul.
- Machine Learning:Neural surrogate models learn thermodynamic behaviors from sparse sensor grids, collapsing computational requirements for automotive paint-shop optimization. Algorithmic explainability mandates under Spain's National Artificial Intelligence Strategy force architectural investments in interpretable surrogate layers.
- Cloud Computing:Scalable compute pools for batch simulation workloads.
- Simulation:Physics-based engines for multiphysics model calibration.
IoT anchors deployment scale; machine learning captures the steepest expansion trajectory.
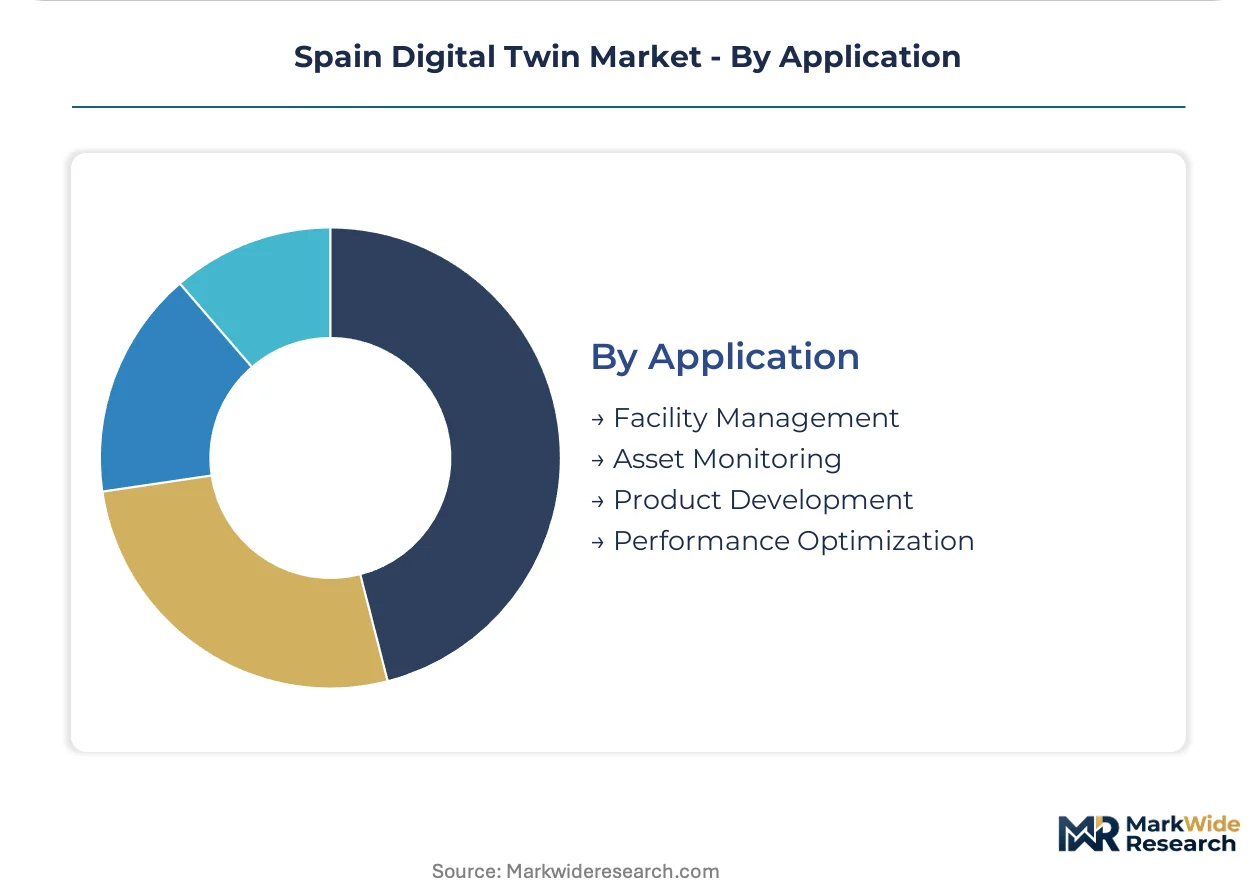
Application:
Asset monitoring concentrates in energy infrastructure, while facility management spreads across municipal portfolios.
- Asset Monitoring:Predictive maintenance in energy and transport faces EU AI Act high-risk classification, requiring conformity assessments before operational deployment. Spanish utilities accelerate procurement standardization around certified vendors.
- Performance Optimization:Real-time coating thickness control in automotive paint shops leverages generative physics engines displacing pre-calculated lookup tables. Tier-1 suppliers achieve edge deployment without dedicated HPC infrastructure.
- Facility Management:Integrated building operations across Barcelona's smart-city ecosystem.
- Product Development:Virtual prototyping for reduced physical testing cycles.
Asset monitoring holds the largest share; performance optimization gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish digital twin deployment concentrates in autonomous communities with dense industrial bases and EU funding access. Madrid and Catalonia anchor software and platform development, while peripheral regions capture greenfield infrastructure applications.
Madrid
Aerospace and defense clusters drive high-value digital thread programs. Spain's National Artificial Intelligence Strategy imposes algorithmic transparency mandates on autonomous systems deployed in critical infrastructure. The capital's utilities sector accelerates procurement standardization around EU AI Act-certified predictive maintenance vendors.
Catalonia
Smart manufacturing corridors in Barcelona generate demand for building information modeling integrations. The region's food-processing multinationals unbundle after-sales service from equipment procurement, demanding performance-guaranteed twin subscriptions. Municipal procurement frameworks anchor BIM-operational twin convergence for infrastructure retrofits.
Basque Country
Advanced manufacturing heritage supports machine tool digitalization. Spain's BIS-aligned cybersecurity standards govern critical infrastructure digitalization timelines. Bilbao's port and energy logistics cluster deploys asset lifecycle twins for heterogeneous equipment fleets.
Andalusia
Concentrated solar power and offshore wind construction creates greenfield demand without legacy system drag. EU Green Deal funding streams accelerate renewable asset digitalization. Seville and Málaga anchor utility-scale simulation deployments for grid integration management.
Valencia
Automotive component suppliers retrofit legacy lines with predictive maintenance architectures. EN ISO 23247 interoperability gaps force costly custom integration layers between SCADA systems and modern platforms. The region's ceramics and tile manufacturing base experiments with generative physics engines for kiln optimization.
Spain Digital Twin Market Competitive Landscape
Concentration sits with telecommunications-anchored platform providers and defense-aerospace specialists. The vendor base spans three tiers: infrastructure-backed integrators, vertical specialists, and emerging SaaS entrants. Strategic moves center on 5G edge deployment partnerships and algorithmic explainability investments for EU AI Act compliance.
Among telecommunications-anchored integrators, Telefónica Tech occupies a position exemplifying nationwide infrastructure leverage for millisecond-latency deployments. Defense-aerospace specialists include Indra, which sits within the sovereign capability tier serving classified digital thread programs. Barcelona-based R2M Solution Spain S.L. represents the smart-city vertical specialist archetype, anchoring municipal BIM integration demand.
| Leading Market Players |
|---|
| R2M Solution Spain S.L. |
| piensas.xyz |
| STOWAI |
| Telefónica Tech |
| Indra |
| URBIM |
| Agrointel |
| Iberdrola |
| Zenit Solar Tech SL |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation timelines for EU AI Act conformity assessments compress vendor selection windows and concentrate procurement authority among certified systems integrators. This lead-time compression rewards incumbents with pre-certified architectures while forcing price concessions from challengers still navigating BIS-aligned cybersecurity approvals.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across Spanish digital twin deployments, separating high-risk certified predictive maintenance suites from standard monitoring tools. Three-tier pricing structure across premium, standard, and economy levels reflects algorithmic explainability depth and EN ISO 23247 interoperability maturity. Cost compression in the economy tier intensifies because domestic electronics suppliers compete on edge hardware margins. Municipal procurement officers in Barcelona's smart-city frameworks exhibit the sharpest price sensitivity, while Madrid's defense-aerospace buyers absorb premiums for classified digital thread capabilities.
Supply Chain Analysis
Germany and France anchor physics-based simulation engine production for Spanish industrial clients, with domestic system integrators handling edge node assembly and SCADA bridge deployment. Software stacks draw from proprietary modeling kernels developed in Northern European R&D centers, while sensor hardware feeds from East Asian electronics manufacturers. Single-source vulnerability concentrates in 5G edge infrastructure where Telefónica Tech maintains nationwide exclusivity. Distribution runs through certified systems integrators who bundle implementation, calibration, and ongoing telemetry services under multi-year availability contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
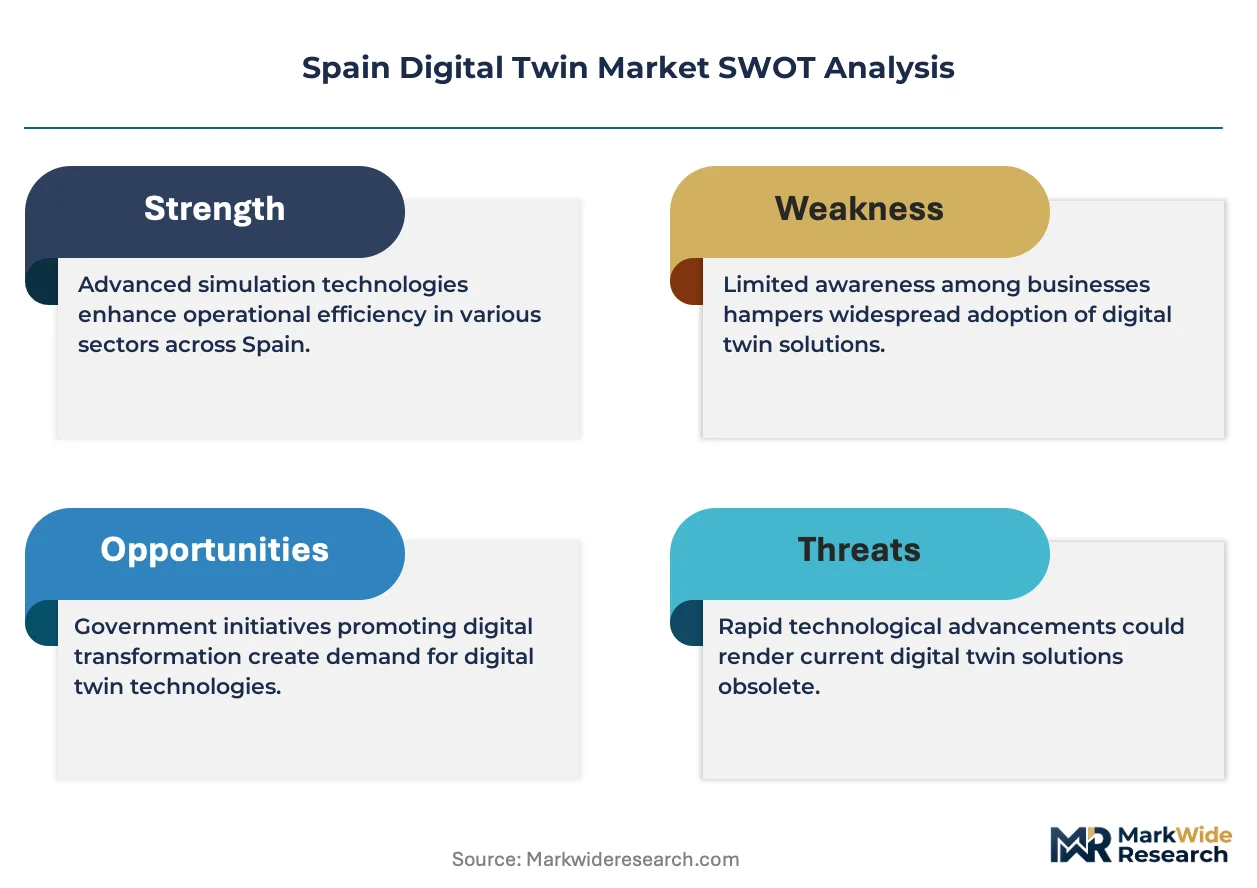
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU AI Act certification timelines and BIS-aligned cybersecurity standards create sticky vendor relationships that resist displacement once operational.
For Market Incumbents: Consolidate around EN ISO 23247 interoperability investments to deepen switching costs in manufacturing verticals. Acquire specialized mechatronics engineering boutiques to address talent scarcity inflating implementation timelines. Lock in long-term telemetry access through availability-based contracts before food-processing multinationals complete vendor consolidation.
For New Entrants and Emerging Players: Mid-market automotive component suppliers underserved by Tier-1 platform vendors represent the most penetrable entry point. Target Valencia's ceramics and tile manufacturing base with generative physics engines for kiln optimization, bypassing Madrid and Barcelona's contested procurement corridors. Lead with edge-deployable neural surrogate models that collapse computational requirements without dedicated HPC infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because telemetry-based availability contracts transform capital equipment sales into sticky subscription relationships. Target acquisition archetypes include vertical specialists with pre-certified EU AI Act compliance in energy or transport verticals. Monitor Andalusian renewable construction velocity as the inflection signal—greenfield solar and offshore wind deployments bypass legacy system drag and accelerate pure-play digital twin adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Accelerates procurement preference among Spanish utilities facing high-risk system mandates. |
| 5G Edge Infrastructure Partnership | Telefónica Tech's nationwide deployment collapses latency barriers for distributed manufacturing assets. |
| Mechatronics Engineering Acquisition | Addresses specialized talent scarcity compressing implementation timelines across Barcelona's smart manufacturing corridor. |
| Availability-Based Contract Expansion | Transforms capital sales into recurring telemetry access in Catalonia's dairy and meat-processing sectors. |
| Andalusian Renewable Vertical Entry | Captures greenfield solar and offshore wind demand without legacy SCADA integration drag. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and municipal smart-city officers anchored the qualitative base. These primary engagements combined with secondary validation against EU AI Act implementation guidance, EN ISO 23247 draft specifications, BIS cybersecurity standards documentation, and Spanish National Artificial Intelligence Strategy policy releases. Bottom-up deployment sizing across Madrid's aerospace cluster, Barcelona's manufacturing belt, and Andalusian renewable sites triangulated against top-down market aggregation.
Sensitivity analysis tested forecast outputs against varying EU AI Act enforcement timelines and 5G edge infrastructure rollout assumptions across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, underlying technology stack, and application use case, with regional adoption patterns capturing autonomous community-level variation. CAGRs derived from weighted average growth contributions across software platform expansion, hardware edge node deployment, and services implementation cycles, with machine learning layer penetration treated as a separate acceleration variable.
Forecasts assume regulatory continuity in EU AI Act classification regimes and Spain's BIS-aligned critical infrastructure standards; material policy shifts would require re-modeling deployment timelines and procurement authorization pathways. Specific risks include EN ISO 23247 standardization delays, mechatronics talent pipeline constraints, and cybersecurity certification backlog expansion. Recalibration cycles align with material shifts in EU AI Act enforcement guidance and renewable construction award velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Location As a Service Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Master Data Management Market
Digital Solutions
Weather Information Technologies Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Global E-Filing Platforms Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
System Integrator Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Smart Set-Top Box and Dongle Market