
 Session Replay Software Market | 2026-2036
Session Replay Software Market Size, Share, and Industry Trends Forecast 2026-2036
Session Replay Software Market Analytics
Retail and e-commerce is expanding as the dominant end-use vertical for session replay platforms, displacing earlier reliance on generic web analytics in media and publishing. FullStory leverages deep API integration capabilities to anchor enterprise deployments across Fortune 500 retailers. Hotjar competes aggressively in the mid-market with freemium-to-paid conversion mechanics that sustain high user acquisition velocity.
Session replay software captures, reconstructs, and visualizes user interactions on web and mobile interfaces through DOM mutation logging and event stream processing, enabling product teams to diagnose friction points without relying solely on aggregate metrics. Cloud-based deployment leads the architecture mix due to elastic storage requirements for high-fidelity recording, while on-premises solutions retain share in finance and healthcare where data residency mandates constrain SaaS adoption. Feature-level segmentation shows user experience analytics commanding the widest margin pool as vendors bundle heatmaps, funnel analysis, and replay into unified suites rather than standalone tools.
The Federal Trade Commission and HIPAA in the United States, alongside GDPR and the EU AI Act in Europe, shape vendor roadmaps by mandating explicit consent mechanisms, data minimization, and algorithmic transparency for automated insights derived from behavioral data. ISO 27001 and SOC 2 Type II certifications have become baseline procurement filters rather than differentiators. Stakeholders must monitor regulatory divergence between jurisdictions as cross-border data transfer restrictions threaten the economics of centralized cloud replay infrastructure.
Market Dynamics
GDPR and the EU AI Act are forcing session replay vendors to rebuild data architectures around explicit consent logging and automated decision transparency, compressing margins while creating compliance-driven product differentiation.
Growth Catalysts
- Behavioral analytics convergence:Product teams now demand unified suites combining heatmaps, funnel analysis, and replay rather than standalone tools. E-commerce platforms represent the fastest-growing buyer segment as merchants seek granular friction-point diagnostics.
- FTC enforcement trajectory:The United States Federal Trade Commission is intensifying scrutiny of dark patterns and deceptive design, compelling enterprises to invest in session replay for proactive UX audit trails and litigation defense.
- Cloud elasticity:Elastic storage architectures enable high-fidelity DOM mutation logging at scale without prohibitive infrastructure capex, removing a historical barrier to enterprise deployment.
Market Restraints
- Cross-border data friction:GDPR's data transfer restrictions and Schrems II rulings threaten the economics of centralized cloud replay infrastructure, forcing redundant regional deployments.
- Storage cost volatility:High-fidelity session capture generates petabyte-scale data volumes, making cloud storage pricing fluctuations a direct margin pressure on SaaS vendors.
- On-premises substitution:Finance and healthcare buyers constrained by HIPAA data residency mandates retain on-premises solutions, fragmenting vendor R&D and diluting cloud-native network effects.
Strategic Opportunities
- Mobile app expansion:Native iOS and Android replay remains technically underdeveloped relative to web, creating white space for vendors who solve OS-level privacy sandbox constraints.
- AI Act compliance services:The EU AI Act's algorithmic transparency requirements for automated behavioral insights create a services and tooling revenue layer atop raw replay capture.
- Real-time intervention:Convergence of session replay with live chat and personalization engines enables mid-session friction resolution, shifting value from retrospective analysis to immediate conversion recovery.
Industry Challenges
- Data engineering scarcity:Vendors struggle to hire engineers proficient in both high-throughput event stream processing and privacy-preserving architecture design.
- Legacy analytics displacement:Enterprises running decade-old web analytics stacks face integration complexity and organizational resistance when migrating to replay-centric workflows.
- SOC 2 Type II timeline:Enterprise procurement now mandates this certification as a baseline filter, extending sales cycles by 6-12 months for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Session Replay Software Market |
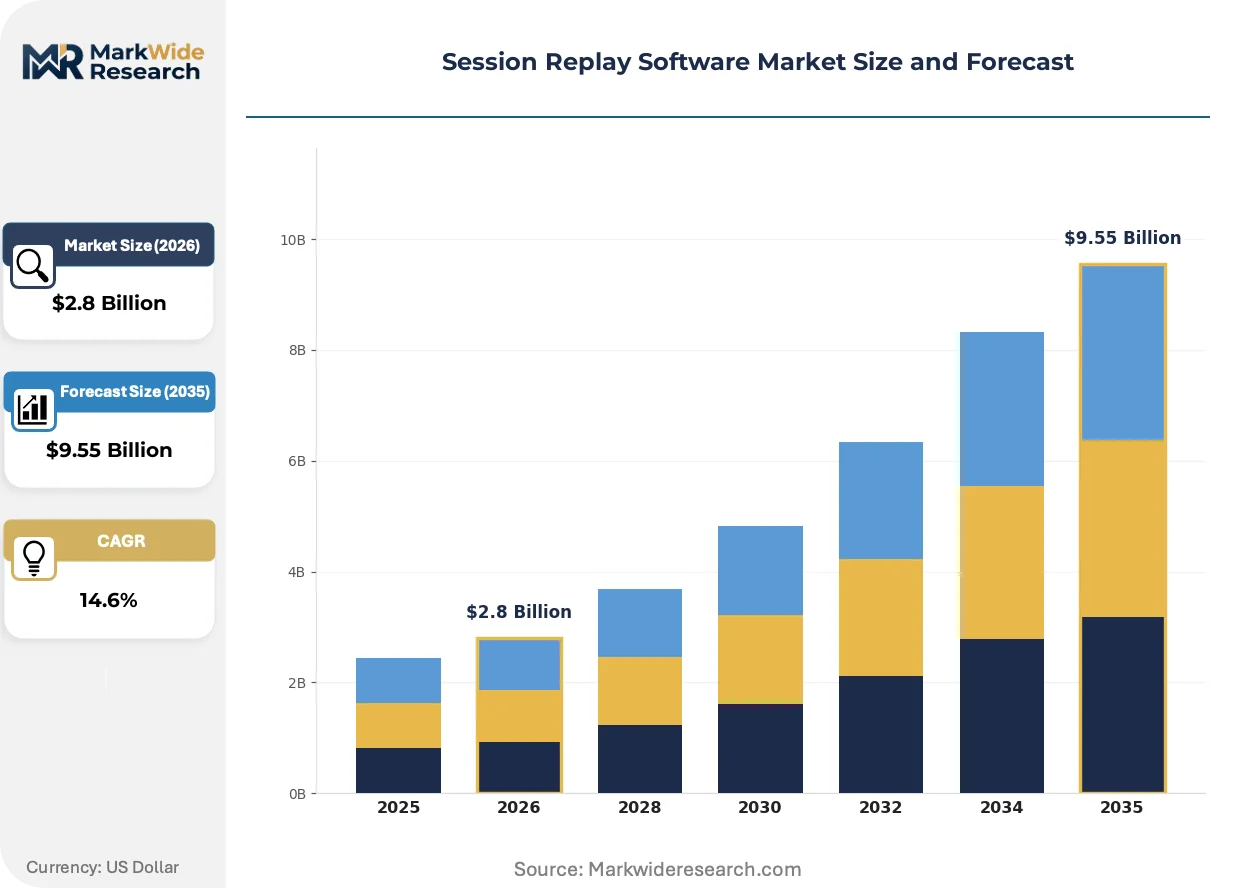
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, eCommerce, Finance, Healthcare Feature: User Experience Analytics, Heatmaps, Session Recording, Replays Integration Level: API Integration, CRM Integration, Analytics Platform, Others |
| Companies Covered | Smartlook, Crazy Egg, FullStory, Pendo, Contentsquare, Hotjar, Mouseflow, Quantum Metric, LogRocket, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Session Replay Software Market Evolving Landscape
Privacy-preserving capture methods are electrifying competitive positioning as differential privacy and client-side masking techniques mature. Vendors must now deliver analytical fidelity without exposing raw user data.
DOM mutation logging paired with edge-compute preprocessing is electrifying the technical architecture of session replay platforms. Retailers with high-traffic seasonal spikes are adopting this stack fastest, compressing the window between user action and analyst visibility from minutes to seconds. The structural consequence is electrifying vendor differentiation around latency rather than storage cost alone.
The EU AI Act's Article 52 mandates on automated decision transparency are reshaping product roadmaps for behavioral analytics vendors selling into Europe. Session replay tools must now expose the logic behind AI-generated friction scores and recommendations, adding engineering overhead but creating switching costs for compliant installations. Financial services buyers in Germany and France are driving the earliest compliance-driven procurement cycles.
Enterprise buying committees are consolidating vendor relationships, displacing point-solution session replay contracts in favor of bundled customer experience platforms. Mid-market SaaS companies previously buying Hotjar or FullStory standalone now demand these capabilities within broader analytics suites. This concentration is most visible in the United States, where digital transformation budgets remain the largest worldwide and procurement teams prioritize vendor reduction over best-of-breed specialization.
Session Replay Software Market Segmentation
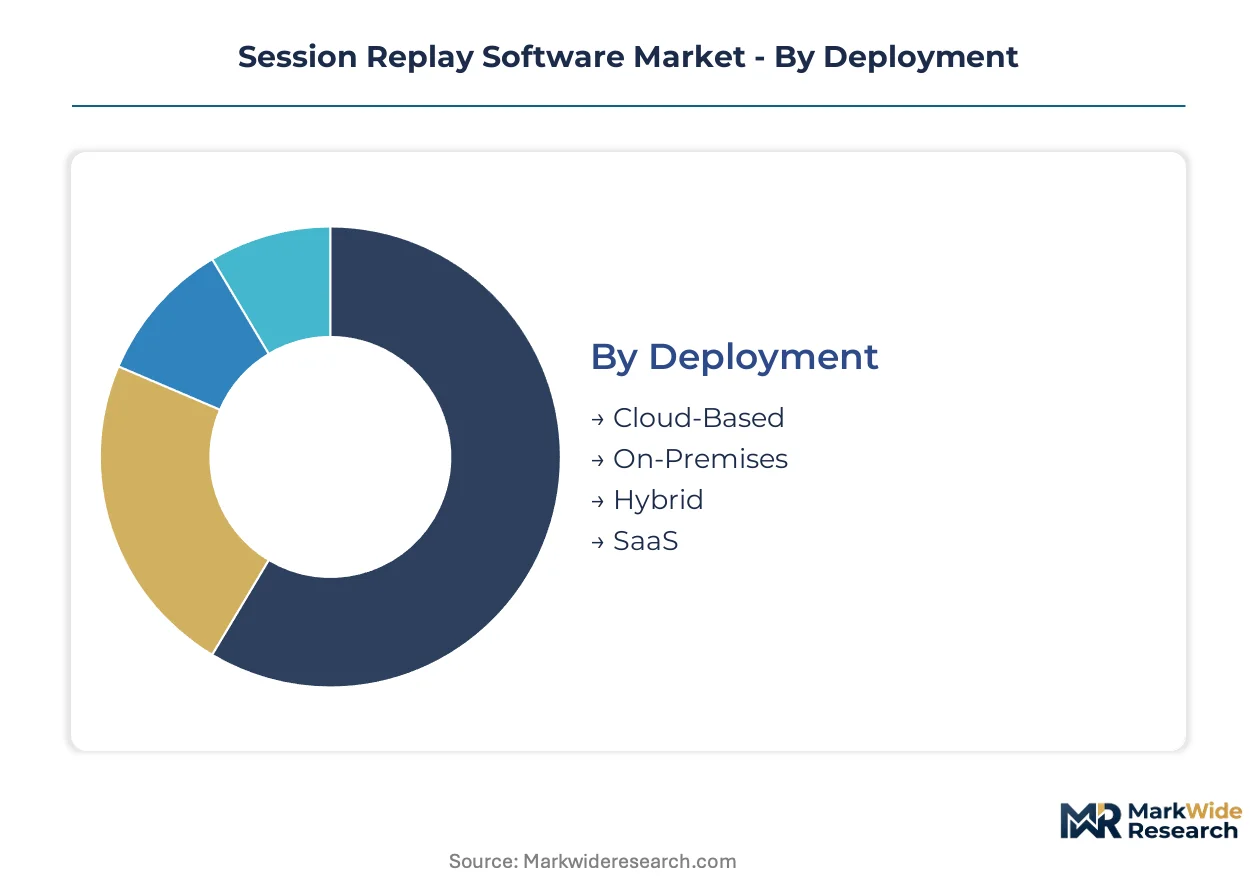
Segmentation in session replay software reveals how architectural choices, integration depth, and feature bundling determine vendor profitability and buyer procurement patterns. Understanding these divisions exposes where compliance burdens concentrate and where elastic scaling creates competitive advantage.
Deployment:
Cloud-native architectures dominate standalone deployments, while hybrid and on-premises configurations anchor embedded enterprise systems with stringent data residency requirements.
- Cloud-Based:Elastic storage architectures enable petabyte-scale DOM mutation logging without capital infrastructure. E-commerce platforms in the United States deploy this most aggressively, driven by seasonal traffic spikes that demand automatic scaling.
- On-Premises:Finance and healthcare buyers constrained by HIPAA data residency mandates retain these solutions, fragmenting vendor R&D and diluting cloud-native network effects. German financial services firms drive procurement here due to Bundesbank guidance on cross-border data controls.
- Hybrid:Split architectures process sensitive PII on-premises while pushing anonymized analytics to cloud dashboards.
- SaaS:Multi-tenant platforms with standardized feature sets serve mid-market buyers seeking rapid deployment without engineering overhead.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid as compliance complexity rises.
End User:
Cost tier stratification separates enterprise buyers with dedicated compliance budgets from mid-market adopters prioritizing speed-to-insight over governance depth.
- Retail:High-traffic seasonal operations demand real-time friction diagnostics to recover abandoned carts. United States merchants allocate the largest digital transformation budgets to these tools, particularly during Q4 volume spikes.
- eCommerce:Pure-play online merchants seek granular behavioral diagnostics without legacy system integration burdens. This segment climbs the fastest as direct-to-consumer brands displace traditional retail analytics stacks.
- Finance:Banks and insurers require audit trails for FTC dark pattern scrutiny and algorithmic transparency under the EU AI Act.
- Healthcare:HIPAA-mandated consent logging and data minimization constrain architecture choices, preserving on-premises share.
Revenue concentration sits with Retail; steepest expansion trajectory belongs to eCommerce as merchant platform adoption accelerates.
Feature:
Application maturity varies sharply, with bundled suites displacing standalone tools as procurement committees consolidate vendor relationships.
- User Experience Analytics:Unified dashboards combining multiple diagnostic modalities command the widest margin pool. Enterprise buyers in France and Germany now mandate these suites for EU AI Act compliance documentation.
- Heatmaps:Aggregate visualizations of click density and scroll depth serve as entry-level diagnostics for mid-market product teams. Adoption concentrates in United States SaaS companies with lean analytics functions.
- Session Recording:High-fidelity capture of individual user journeys generates the largest storage volumes and privacy exposure.
- Replays:Reconstructed browsing sessions enable qualitative friction-point diagnosis without statistical aggregation.
Margin capture concentrates in User Experience Analytics; the segment gaining share fastest is Replays as real-time intervention capabilities mature.
Integration Level:
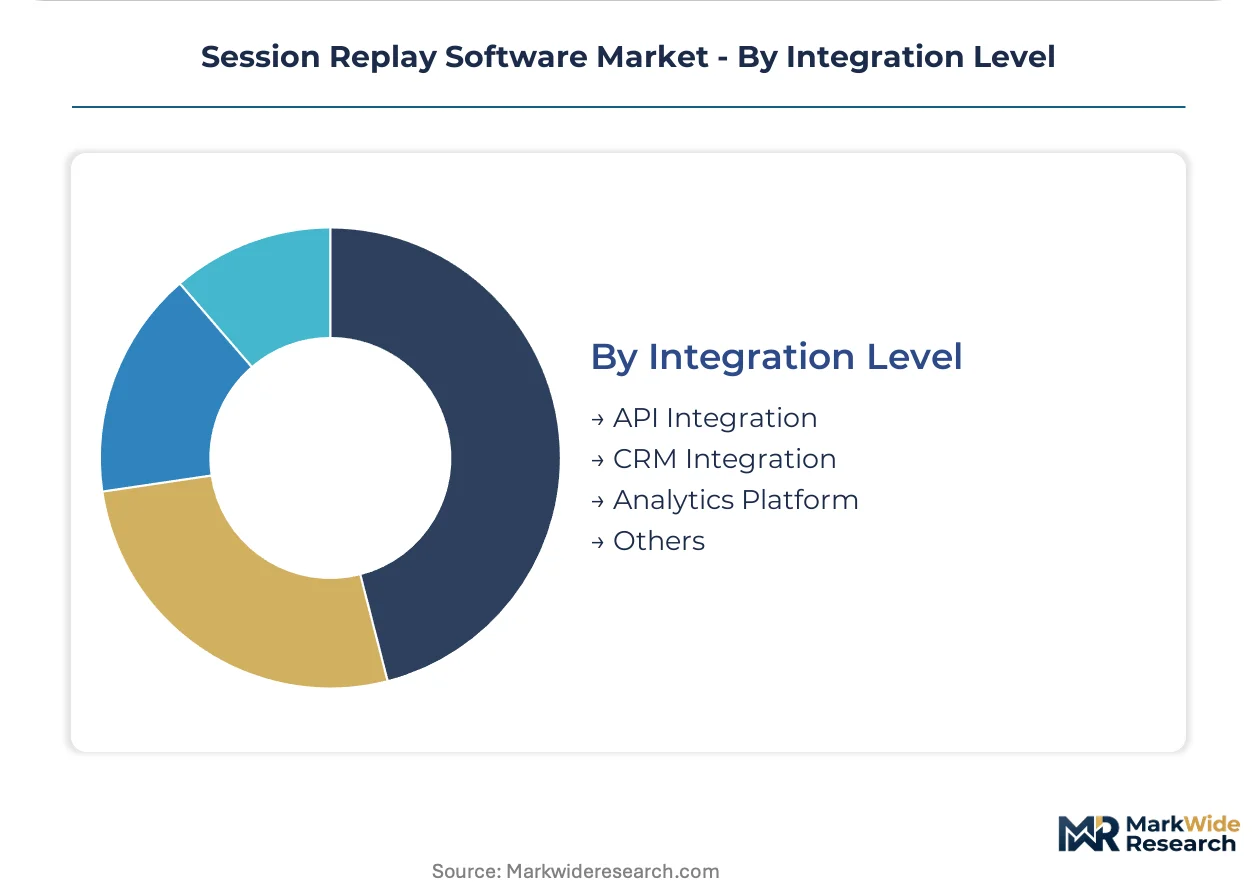
Supply concentration in API-first architectures reflects how deeply session replay has penetrated core enterprise workflows versus peripheral analytics stacks.
- API Integration:Deep system connectivity enables bi-directional data flow between replay platforms and operational tools. United States Fortune 500 retailers anchor demand here, requiring real-time funnel data to feed personalization engines.
- CRM Integration:Synchronization with customer record systems supports account-level behavioral history for sales and support teams. Healthcare providers in the United States deploy this for patient journey mapping under HIPAA consent frameworks.
- Analytics Platform:Pre-built connectors to legacy web analytics reduce migration friction for enterprises replacing decade-old stacks.
- Others:Custom integration workarounds for niche operational systems or proprietary data warehouses.
Deployment scale concentrates in API Integration; the fastest-climbing category is CRM Integration as revenue operations teams demand unified customer visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and United Kingdom, while consumption spreads across retail and finance clusters in Germany, France, and Japan. This production-consumption divide shapes vendor go-to-market strategies and compliance investments.
United States
Fortune 500 retailers in New York and California drive enterprise demand for real-time friction diagnostics. FTC enforcement on dark patterns compels UX audit trail investments. The San Francisco Bay Area anchors vendor headquarters density, with product teams prioritizing API-first architectures for personalization engine integration.
Germany
Bundesbank guidance on cross-border data controls preserves on-premises deployment share among Frankfurt financial services firms. The EU AI Act mandates algorithmic transparency for automated behavioral insights. Munich-based insurers are procuring compliance-documentation suites that bundle replay with audit-ready UX analytics.
United Kingdom
London fintech clusters demand session replay for conversion optimization across mobile banking interfaces. GDPR consent logging requirements shape vendor selection criteria. The Manchester-Leeds corridor sees mid-market SaaS adoption accelerating as direct-to-consumer brands displace legacy retail analytics.
France
Paris luxury e-commerce houses deploy replay tools for high-consideration purchase journey analysis. CNIL enforcement on tracking consent elevates privacy-preserving capture methods in procurement scorecards. Lyon-based B2B software vendors represent emerging demand for product-led growth diagnostics.
Japan
Tokyo retail conglomerates invest in mobile app replay as iOS privacy sandboxes complicate behavioral data collection. METI guidelines on consumer protection influence UX audit standards. Osaka manufacturing exporters adopt session replay for B2B portal optimization, linking behavioral data to CRM systems for account-level visibility.
Session Replay Software Market Competitive Landscape
Top-tier vendors anchor enterprise deployments with deep API integration, while mid-market specialists compete on freemium conversion velocity and rapid deployment. The vendor base stratifies across three tiers: unified customer experience platforms, standalone replay specialists, and open-source tooling providers. Strategic moves concentrate on M&A for feature bundling and regional data residency compliance investments.
Within the unified platform tier, FullStory and Contentsquare exemplify enterprise-grade positioning through deep system connectivity. Hotjar occupies the mid-market vector with freemium-to-paid mechanics that sustain high user acquisition velocity. These three anchors illustrate how vendor archetypes map to buyer procurement patterns across compliance-heavy and speed-to-insight segments.
| Leading Market Players |
|---|
| Smartlook |
| Crazy Egg |
| FullStory |
| Pendo |
| Contentsquare |
| Hotjar |
| Mouseflow |
| Quantum Metric |
| LogRocket |
| Others |
Value Network & Pricing Analysis
Cloud storage bandwidth costs cascade through SaaS pricing tiers as session replay vendors negotiate hyperscaler contracts in the United States, with petabyte-scale DOM mutation logging forcing mid-market buyers toward standard-tier subscriptions while enterprise deployments absorb premium elasticity charges.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects hyperscaler storage renegotiation cycles and freemium conversion mechanics that compress annual contract values. Three-tier pricing structure across premium, standard, and economy levels segments by data retention depth, API call volume, and SOC 2 Type II certification bundling. Pricing pressure stems from cloud storage pricing volatility transmitted directly to SaaS margins. eCommerce pure-plays exhibit highest price sensitivity; Fortune 500 retailers with dedicated compliance budgets show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand while self-serve onboarding funnels capture mid-market velocity. Engineering talent concentrates in the United States, United Kingdom, and Germany; cloud infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Singapore. Raw material dependencies span event-stream processing frameworks, differential privacy libraries, and edge-compute hardware. Single-source vulnerability in specialized data engineering talent threatens delivery timelines. Distribution runs through API-first integration partnerships and direct sales motions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into consent-logging infrastructure and real-time intervention engines is accelerating as vendors seek margin defense against compliance-driven engineering overhead.
For Market Incumbents: Cement API ecosystem dominance by acquiring mobile replay specialists before OS-level privacy sandboxes mature. Expand SOC 2 Type II certification velocity to compress 6-12 month procurement cycles threatening mid-market expansion. Vertical integration into edge-compute preprocessing preserves latency advantages as cloud storage costs escalate. For New Entrants and Emerging Players: Capture native iOS and Android replay white space before incumbent technical debt accumulates around web-centric architectures. Target German and French financial services buyers facing EU AI Act algorithmic transparency mandates with compliance-documentation tooling. Lead with AI Act audit-trail capabilities as the primary go-to-market wedge. For Investors and Strategic Acquirers: EU AI Act enforcement waves in Germany and France are the leading indicator that compliance-driven procurement cycles will consolidate vendor relationships toward bundled suites. Position for 5-10 year horizon around customer experience platform convergence rather than standalone replay tools. Acquire differential privacy engineering teams as the critical capability signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified suites displace standalone replay contracts as enterprise procurement committees consolidate vendor relationships. |
| Geographic Expansion | Regional data residency deployments in Frankfurt and Singapore address GDPR and Bundesbank cross-border control mandates. |
| Acquisition of Specialist Firm | Mobile replay engineering teams command premium valuations as iOS privacy sandboxes complicate behavioral capture. |
| Product Launch | Real-time intervention capabilities shift value from retrospective analysis to immediate conversion recovery. |
| Strategic Partnership | Hyperscaler co-selling agreements reduce cloud storage margin exposure through committed-use discounts. |
Research Methodology
Multi-period observation of vendor pricing disclosures, hyperscaler contract structures, and procurement cycle durations anchored the trend analysis, supplemented by interviews with CTOs at Fortune 500 retailers, IT procurement officers at German financial services firms, platform engineers at mid-market SaaS companies, and integration specialists at customer experience consultancies. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, App Annie mobile analytics data, and EU regulatory guidance documents. Bottom-up deployment estimates and top-down market sizing triangulated volume and value outputs.
Input-output matrices mapped deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern against elasticity-adjusted storage costs and compliance-driven feature bundling. CAGRs derived from segment-level growth rate distributions weighted by procurement cycle acceleration and regulatory enforcement trajectories. Forecast inputs included seasonal eCommerce traffic spike patterns and EU AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Schrems II ruling expansions, hyperscaler storage pricing volatility, and mobile OS privacy sandbox evolution. Forecasts reflect assumptions around regulatory stability and cloud infrastructure availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Work From Home Setup Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Dating Services Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Global Data Quality Tool Market