
 US Digital Market | 2026-2036
US Digital Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Market Insights
Healthcare provider adoption of digital infrastructure is recalibrating the US Digital Market's end-use composition. Amazon leverages its cloud computing backbone to dominate enterprise data migration contracts. Alphabet competes aggressively in artificial intelligence-enabled search and advertising optimization tools. Microsoft anchors public-sector digital transformation through its Azure Government cloud offerings.
The US Digital Market encompasses electronically delivered services, software platforms, and data-driven tools that process, store, and transmit information across internet protocol networks with latency thresholds below 100 milliseconds for real-time applications. These systems enable commercial transactions, content distribution, enterprise workflow automation, and consumer engagement at scale. Cloud Computing and Artificial Intelligence segments command the largest margin pools as enterprises shift capital expenditure to operational expenditure models. Small Businesses represent the fastest-growing end-user category as no-code platforms lower technical barriers. Digital Advertising applications within the Application segment sustain mature growth rates while Customer Relationship Management tools capture expanding enterprise budgets.
The FCC governs broadband access and net neutrality frameworks that directly determine platform service tiers and pricing structures available to consumers. State attorneys general in California and New York enforce privacy regulations that compel data handling transparency across Social Media and E-commerce service types. The SEC's disclosure requirements for publicly traded technology firms shape how Cloud Computing and Cybersecurity providers report material risks to investors. Stakeholders must monitor emerging state patchworks of artificial intelligence governance that threaten to fragment compliance architectures.
Market Dynamics
The migration of enterprise workloads from on-premises infrastructure to distributed cloud architectures is compressing traditional hardware procurement cycles and forcing legacy vendors to recalibrate their service delivery models around subscription-based consumption.
Growth Catalysts
- Healthcare Provider Digitalization:Hospital systems and outpatient networks are deploying integrated electronic health record platforms that require HIPAA-compliant cloud storage and real-time data analytics capabilities.
- FCC Broadband Infrastructure Investment:Federal funding programs for rural broadband expansion are extending high-speed connectivity to previously underserved markets, unlocking new subscriber bases for streaming and cloud services.
- No-Code Development Platforms:Small businesses across Texas and California are adopting visual programming tools that eliminate traditional software engineering bottlenecks.
Market Restraints
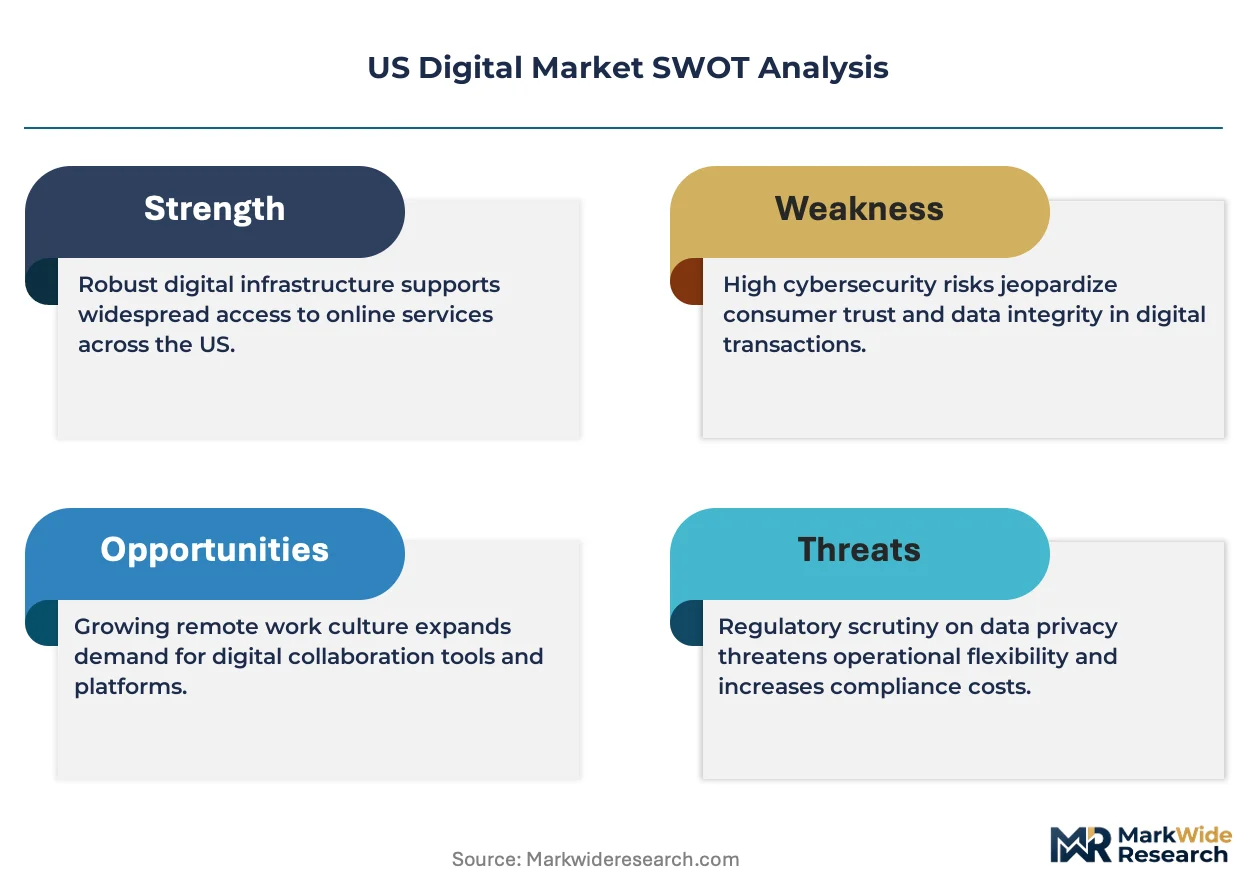
- State Privacy Law Fragmentation:California's CCPA and emerging statutes in Virginia and Colorado impose conflicting data handling requirements that inflate compliance costs for multi-state operators.
- Semiconductor Supply Concentration:Advanced chip fabrication for AI accelerators remains concentrated in East Asian foundries, creating geopolitical exposure for US-based cloud providers.
- Legacy System Technical Debt:Federal agencies and regulated industries maintain decades-old mainframe architectures that resist API-based integration with modern microservices.
Strategic Opportunities
- Underpenetrated Midwest Markets:Secondary metropolitan areas in Ohio and Michigan show lagging cloud adoption rates relative to coastal corridors, presenting first-mover expansion potential.
- AI Governance Services:The absence of unified federal artificial intelligence regulation is creating demand for compliance consulting and audit platforms from specialized vendors.
- Edge Computing Convergence:Integration of 5G network slicing with containerized workloads enables sub-10-millisecond latency for autonomous vehicle and industrial robotics applications.
Industry Challenges
- Cybersecurity Talent Scarcity:Zero-trust architecture implementation requires certified security engineers that remain in critically short supply across the domestic labor market.
- Multi-Cloud Integration Complexity:Enterprises operating hybrid environments spanning AWS, Azure, and Google Cloud face escalating orchestration costs and interoperability failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Market |
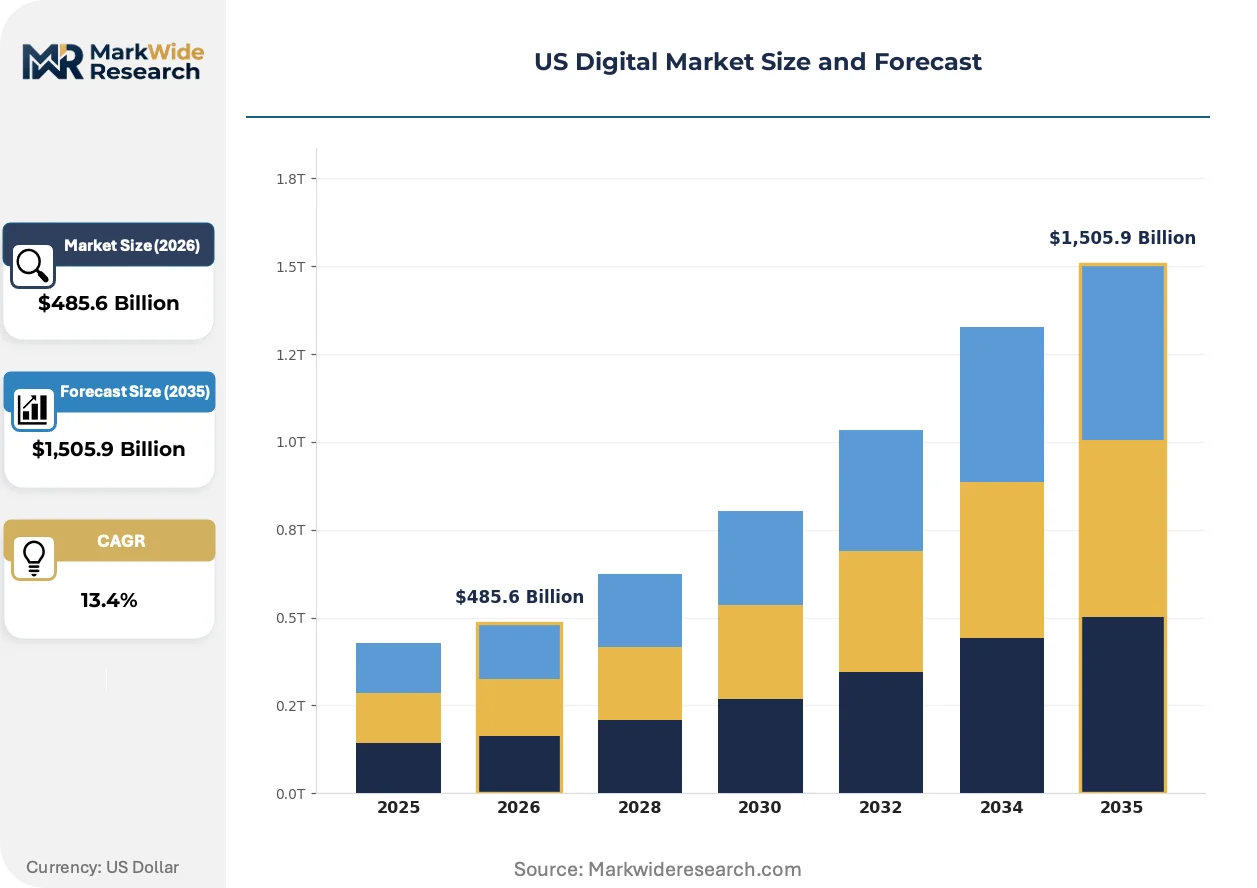
| Market Size in 2026 | $485.6 Billion |
| Market Size in 2035 | $1,505.9 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Social Media, E-commerce, Search Engine Marketing, Email Marketing End User: Small Businesses, Enterprises, Nonprofits, Government Agencies Technology: Cloud Computing, Artificial Intelligence, Analytics, Cybersecurity Application: Content Management, Customer Relationship Management, Digital Advertising, Web Development |
| Companies Covered | Amazon, Alphabet, Apple, Microsoft, Adobe, Salesforce, Oracle, HubSpot, IBM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Market Trends and Innovations
Generative artificial intelligence capabilities are embedding into core enterprise software stacks, transforming how organizations automate content creation, code generation, and customer interaction workflows.
Large language model fine-tuning is consolidating the competitive landscape around vertically specialized AI applications. Healthcare systems in Massachusetts and Pennsylvania are deploying domain-trained models for clinical documentation at scale. This capability compression is eliminating standalone natural language processing vendors and absorbing their functionality into platform suites.
The SEC's cybersecurity disclosure rules for public companies are mandating board-level accountability for data breach reporting timelines. Technology firms must now document material incident response protocols in quarterly filings. Cloud service providers serving publicly traded clients are restructuring service level agreements to accommodate accelerated forensic investigation requirements.
Enterprise software purchasing is gravitating toward usage-based metering rather than perpetual licensing arrangements. Chief financial officers in manufacturing and logistics sectors are rejecting upfront capital commitments in favor of consumption-correlated operational expenditures. This behavioral shift is most pronounced among mid-market firms in the Pacific Northwest that experienced cash flow constraints during recent interest rate cycles.
US Digital Market Segmentation
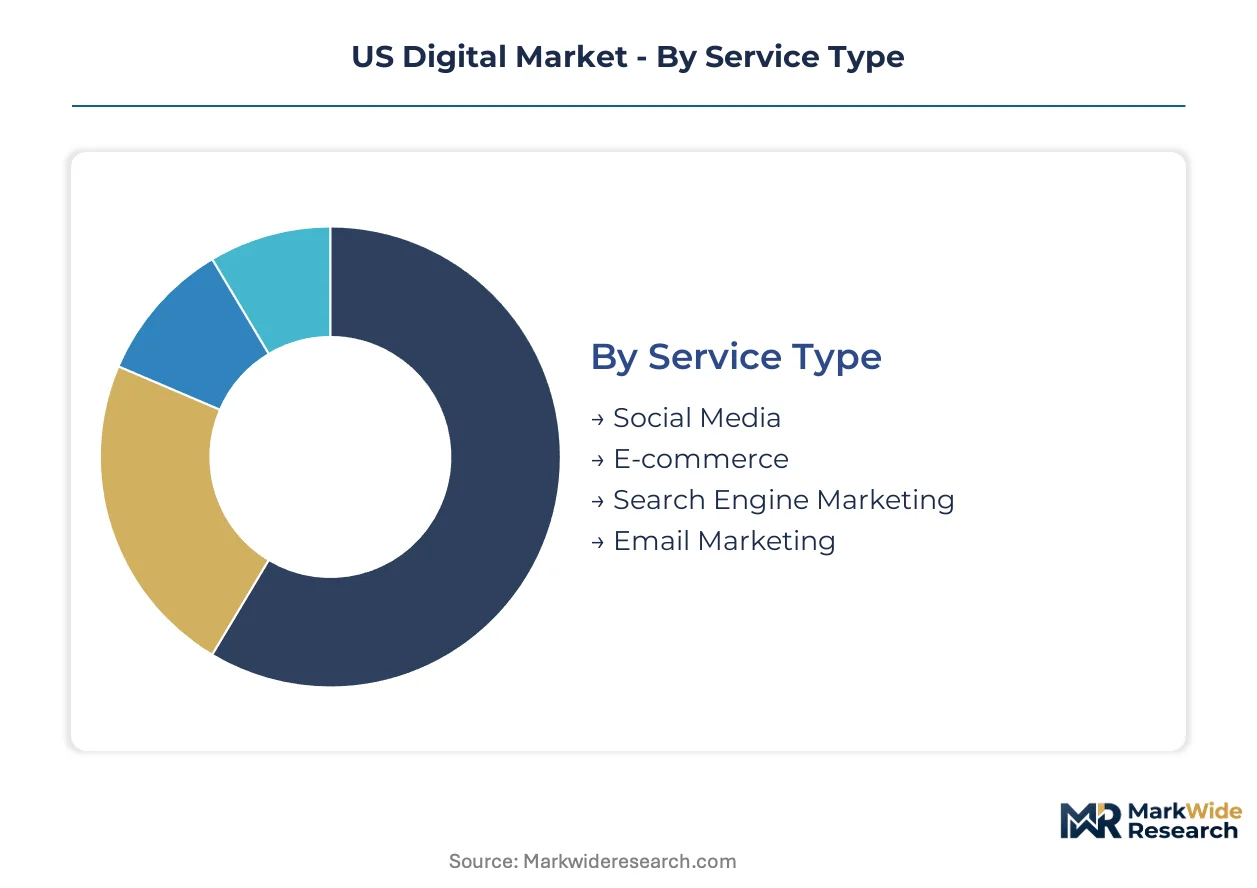
Service delivery models across the US Digital Market fragment along technical architecture, customer scale, and functional application. These divisions determine procurement patterns, margin structures, and compliance obligations for platform providers operating across state jurisdictions.
Service Type:
Platform infrastructure investments concentrate heavily in advertising-supported and transaction-enabled service categories.
- Social Media:Content distribution platforms monetize through behavioral targeting algorithms that process user engagement signals in real time. California and New York regulators enforce transparency mandates that reshape ad auction mechanics and data retention policies.
- E-commerce:Transaction processing systems integrate payment gateways, inventory management, and fulfillment orchestration into unified merchant dashboards. Texas-based retailers and California direct-to-consumer brands drive merchant adoption through demand for omnichannel sales integration.
- Search Engine Marketing:Keyword auction platforms connect advertiser bids with query intent matching.
- Email Marketing:Campaign automation tools segment subscriber lists for personalized outreach.
Social Media absorbs the bulk of installed capacity; E-commerce is expanding most quickly.
End User:
Customer scale tiers dictate pricing architecture and service level agreement structures across vendor portfolios.
- Small Businesses:No-code platforms eliminate engineering dependencies for proprietors in Ohio and Michigan secondary metros. These operators prioritize consumption-based pricing over capital-intensive infrastructure commitments.
- Enterprises:Multi-divisional organizations require API ecosystems, single sign-on federation, and custom SLA guarantees. Healthcare systems and financial institutions in Massachusetts and Pennsylvania anchor demand for HIPAA-compliant and SOX-audited deployments.
- Nonprofits:Mission-driven organizations access discounted licensing tiers for donor management and volunteer coordination.
- Government Agencies:Federal and state entities procure through FedRAMP-authorized cloud environments with domestic data residency requirements.
Enterprises command the largest contract values; Small Businesses are gaining share fastest.
Technology:
Underlying infrastructure capabilities determine competitive differentiation and margin capture for platform vendors.
- Cloud Computing:Distributed server virtualization enables elastic resource provisioning with geographic redundancy. Virginia data center clusters and Oregon hyperscale campuses anchor domestic capacity expansion.
- Artificial Intelligence:Machine learning inference engines automate pattern recognition across unstructured datasets. Healthcare providers deploy clinical documentation models trained on Pennsylvania and Massachusetts hospital records.
- Analytics:Business intelligence dashboards aggregate operational metrics for executive decision support.
- Cybersecurity:Zero-trust access controls and encryption key management protect distributed workforces.
Cloud Computing dominates current infrastructure spend; Artificial Intelligence shows the steepest expansion trajectory.
Application:
Functional use cases align software procurement with specific operational workflows and departmental budgets.
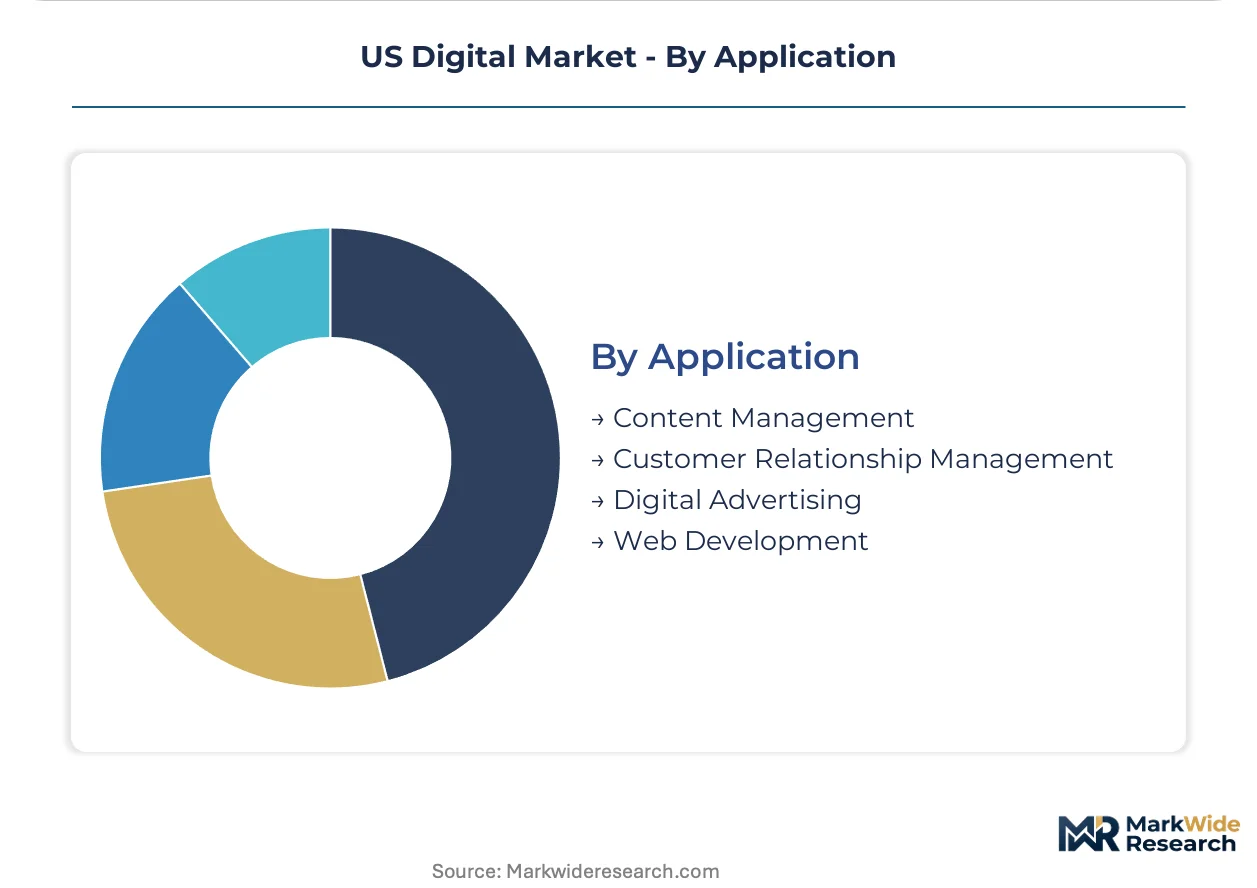
- Content Management:Web publishing systems organize digital assets for multi-channel distribution. Media organizations and marketing agencies in California's Silicon Valley corridor drive demand for headless CMS architectures.
- Customer Relationship Management:Sales pipeline and support ticket platforms centralize customer interaction histories. Midwest manufacturing firms in Michigan and Ohio adopt these tools to replace legacy contact databases.
- Digital Advertising:Programmatic buying platforms automate media placement across publisher networks.
- Web Development:Integrated development environments and deployment pipelines accelerate software release cycles.
Customer Relationship Management captures the largest enterprise software budgets; Content Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US digital infrastructure production concentrates in Virginia hyperscale campuses and Oregon data centers, while consumption spreads across coastal tech corridors and emerging Midwest metros. This geographic mismatch shapes latency engineering priorities and edge computing investments.
California
Enterprise cloud adoption and healthcare provider digitalization dominate demand in the Golden State. The California Consumer Privacy Act imposes data handling transparency mandates that reshape platform compliance architectures. Silicon Valley anchors AI research commercialization, with San Francisco Bay Area clusters driving generative model deployment across enterprise software stacks.
Texas
Austin-Dallas tech belt expansion and energy sector digitalization propel infrastructure investment. State-level data center tax incentives accelerate campus development in Dallas-Fort Worth and Austin metro corridors. Houston's healthcare systems deploy HIPAA-compliant cloud storage alongside real-time analytics platforms for clinical operations.
Virginia
Federal cloud procurement and defense contractor demand sustain Northern Virginia's data center dominance. FedRAMP authorization requirements filter vendor eligibility for government agency contracts. Loudoun County maintains the highest concentration of hyperscale facilities globally, with Ashburn-Eastern corridor expansion continuing unabated.
New York
Financial services digital transformation and media conglomerate cloud migration anchor demand in the Northeast. New York State's SHIELD Act supplements federal cybersecurity frameworks with breach notification mandates. Manhattan's fintech clusters and Brooklyn's creative agency ecosystems drive hybrid cloud adoption across regulated and unregulated sectors.
Illinois
Manufacturing digitization and logistics platform modernization lag coastal adoption curves, presenting expansion opportunities. Chicago's commodity trading floors and pharmaceutical distribution networks require low-latency connectivity for algorithmic operations. Downstate secondary metros show accelerating small business cloud adoption as no-code platforms reduce technical barriers.
US Digital Market Competitive Landscape
Top-tier vendors anchor hyperscale cloud and AI platform tiers, while mid-market specialists occupy vertical application niches. The vendor base stratifies across infrastructure-as-a-service providers, enterprise software suites, and point-solution developers. Three archetypes dominate: cloud-native platform builders, legacy software modernizers, and vertical AI specialists. Competitive dynamics center on M&A-driven capability expansion and strategic partnerships for multi-cloud orchestration.
Within the hyperscale infrastructure tier, Amazon and Microsoft exemplify platform consolidation through cloud computing dominance and government-facing service delivery. Alphabet occupies a position bridging consumer search monetization with enterprise AI tooling. Adobe and Salesforce represent the vertical application archetype, anchoring creative workflow and customer relationship management segments respectively. These named entities illustrate how competitive positioning fragments across infrastructure, platform, and application layers rather than consolidating under single-vendor control.
| Leading Market Players |
|---|
| Amazon |
| Alphabet |
| Apple |
| Microsoft |
| Adobe |
| Salesforce |
| Oracle |
| HubSpot |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Captive hyperscale infrastructure ownership by Amazon, Microsoft, and Google anchors both supply security and pricing power across cloud service tiers. This vertical integration into data center campuses in Virginia and Oregon insulates tier-one providers from colocation cost volatility while enabling aggressive consumption-based pricing for enterprise workloads.
Pricing Analysis
Short lead-time provisioning commands premium rates in the US Digital Market, while reserved capacity and spot instances trade at steep discounts. Three-tier pricing structure across premium, standard, and economy levels segments enterprise buyers by workload criticality and latency requirements. Price differentiation hinges on geographic redundancy guarantees and FedRAMP authorization status. Pricing pressure stems from multi-cloud arbitrage as enterprises benchmark AWS, Azure, and Google Cloud against one another. Small businesses in Ohio and Michigan secondary metros exhibit highest price sensitivity, while federal agencies prioritize compliance over cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and the United States directly constrain advanced chip fabrication for AI accelerators. Supply draws from East Asian foundries for 3nm and 5nm process nodes, Oregon-based facilities for mature node production, and Virginia assembly campuses for final integration. Single-source vulnerability concentrates in TSMC's Taiwan operations for leading-edge GPU and TPU silicon. Distribution runs through direct hyperscaler procurement channels and authorized reseller networks serving mid-market enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Digital Market functions as a vertical-integration race where cloud providers deepen control over silicon design, data center construction, and fiber backbone ownership to compress marginal costs and defend pricing power.
For Market Incumbents: Hedge against multi-cloud orchestration complexity by investing in unified control plane software that abstracts AWS, Azure, and Google Cloud APIs into single management interfaces. Acquire specialized AI governance consultancies in Washington DC and Boston to capture compliance spending from healthcare and financial services clients navigating fragmented state privacy statutes.
For New Entrants and Emerging Players: Regional systems integrators in Columbus, Cleveland, and Detroit represent underexploited channel partners for no-code platform distribution. White-space concentration in Midwest manufacturing digitization and HIPAA-compliant clinical documentation tools for independent physician practices offers penetrable entry points. Pursue co-selling arrangements with Microsoft Azure Government resellers to bypass direct hyperscaler competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking vertical AI capabilities or compliance automation tooling. Long-term viability favors vendors with durable data moats in healthcare, defense, or financial services where regulatory barriers protect incumbent positions. Watch for state AI governance legislation in California and New York as inflection indicators that will trigger compliance-spending acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies AWS, Azure, and Google Cloud APIs into single orchestration layers for enterprise clients. |
| Acquisition of Specialist Firm | Absorbs vertical AI vendors in clinical documentation and regulatory compliance automation. |
| Geographic Expansion | Establishes edge computing presence in Columbus and Detroit to capture Midwest manufacturing demand. |
| Strategic Partnership | Aligns with FedRAMP-authorized resellers to access federal agency procurement channels. |
| Product Launch | Introduces HIPAA-compliant real-time analytics platforms for Texas and Massachusetts hospital systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cloud platform engineers, healthcare CIOs, federal procurement officers, and channel sales executives validated demand assumptions. SEC 10-K disclosures, FCC broadband deployment reports, and state attorney general privacy enforcement records supplemented quantitative sizing. Bottom-up deployment estimates across Virginia, Oregon, and Texas data center clusters were reconciled with top-down enterprise IT spending surveys.
Data-stream reconciliation across vendor revenue disclosures, hyperscaler capex announcements, and end-user procurement databases shaped the analytical framework. Segmentation dimensions modeled include service type, end-user scale tier, underlying technology stack, and regional adoption pattern. CAGRs were derived from elasticity-adjusted demand curves and infrastructure capacity expansion timelines. AI inference workload growth rates and FCC rural broadband subsidy disbursement trajectories informed cloud computing segment projections.
Caveats apply where semiconductor export restrictions, state privacy law fragmentation, or federal AI governance legislation could materially shift the outlook. Forecasts reflect assumptions about enterprise cloud migration velocity and healthcare provider digitalization timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Search Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Consent Management Market
Digital Solutions
Bahrain ICT Market
Digital Solutions
Online Dating Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Australia System Integration Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Returnless Refund Fraud Detection Market