
 Asia-Pacific Smart Government Market | 2026-2036
Asia-Pacific Smart Government Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Government Market Insights
Public safety modernization is decoupling from legacy municipal IT refresh cycles across the Asia-Pacific region. Huawei Technologies Co., Ltd. leverages its integrated 5G and IoT stack to anchor large-scale safe-city deployments in multiple Southeast Asian countries. IBM competes through sovereign cloud and AI governance consulting for agencies navigating data-localization mandates. Cisco Systems, Inc. specializes in resilient network backbones for emergency-response coordination across archipelagic nations.
Smart government denotes the digitization of public administration through interconnected infrastructure, real-time data exchange, and automated service delivery, typically built on API-first architectures with sub-100-millisecond latency requirements for critical applications. The primary purpose is to reduce administrative friction while improving transparency and resource allocation across public agencies. E-Government Services currently dominates procurement budgets as agencies consolidate fragmented portals into unified citizen interfaces. Artificial Intelligence within the Technology dimension is expanding fastest as ministries deploy predictive analytics for traffic flow optimization and fraud detection in social welfare distribution.
India's BIS cloud standards, Australia's Digital Transformation Agency guidelines, and Singapore's IMDA data governance frameworks collectively shape vendor qualification requirements and interoperability protocols across the region. Compliance with these overlapping regimes adds implementation complexity but also creates competitive moats for providers with proven multi-jurisdiction deployments. Stakeholders must track which governments are mandating domestic data residency versus permitting regional cloud zones, as this distinction will determine infrastructure investment patterns and partnership structures.
Market Dynamics
Municipal IT procurement across Southeast Asia is fragmenting as national data-localization mandates force vendors to rebuild cloud architectures country-by-country, multiplying compliance costs and reshaping partnership structures.
Growth Catalysts
- India's Digital India initiative:The program mandates universal digital service access, driving integrated platform procurement across state and central agencies with standardized API frameworks.
- Smart city missions:Urban infrastructure digitization in Indonesia, Vietnam, and the Philippines is concentrating demand for IoT-enabled traffic management and automated utility billing systems.
- 5G network densification:Telecom infrastructure rollouts in Singapore and South Korea enable sub-50-millisecond latency for real-time emergency response coordination and predictive public safety analytics.
Market Restraints
- Domestic data residency requirements:India's BIS cloud standards and Vietnam's cybersecurity law mandate in-country server deployment, fragmenting vendor economics and preventing regional scale efficiencies.
- Legacy system integration debt:Decades-old municipal ERP installations in Thailand and Malaysia require expensive middleware layers that consume 40-60% of project budgets before new capabilities deploy.
- Skilled solution architect scarcity:Shortages of professionals certified in both sovereign cloud platforms and local regulatory compliance extend implementation timelines by 8-14 months.
Strategic Opportunities
- Philippines archipelagic connectivity:Satellite-5G hybrid networks for island municipalities remain undersupplied, creating first-mover advantages for resilient backbone providers.
- Australia's whole-of-government cloud-first policy:The Digital Transformation Agency mandate accelerates multi-tenant platform consolidation, rewarding vendors with federal security accreditation.
- AI governance consulting services:Singapore's IMDA data governance frameworks and emerging algorithmic accountability rules create premium advisory revenue streams around explainable AI deployment.
Industry Challenges
- Interoperability certification delays:India's BIS standards, Australia's DTA guidelines, and Singapore's IMDA frameworks lack mutual recognition, forcing redundant testing cycles for multi-country vendors.
- Cybersecurity talent gaps:Government security operations centers across Indonesia and Vietnam operate at 30-40% staffing levels, constraining threat monitoring for critical infrastructure.
- Procurement cycle misalignment:Annual budget appropriations in most Asia-Pacific jurisdictions prevent multi-year SaaS contracts, complicating vendor cash flow planning and platform investment recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Government Market |
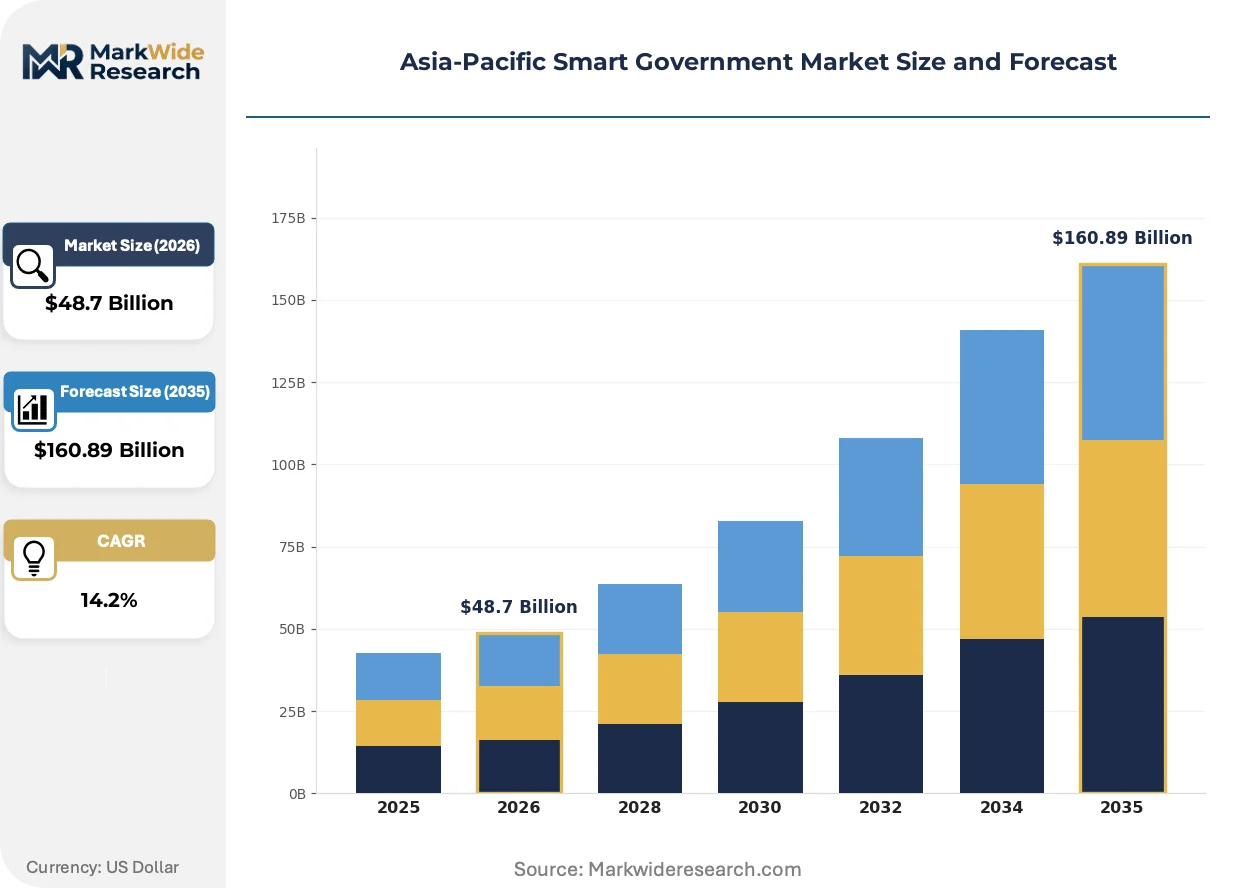
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: E-Government Services, Smart City Solutions, Digital Identity, Citizen Engagement Platforms Technology: IoT Solutions, Cloud Computing, Big Data Analytics, Artificial Intelligence End User: Municipalities, Government Agencies, Public Safety Organizations, Educational Institutions Application: Traffic Management, Waste Management, Public Safety, Emergency Response |
| Companies Covered | Huawei Technologies Co., Ltd., Siemens AG, IBM, Accenture, SAP SE, Microsoft Corporation, Cisco Systems, Inc., Hitachi, Ltd., Oracle Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Government Market Trends and Innovations
Edge computing architectures are redistributing data processing away from centralized hyperscale facilities toward municipal network nodes, enabling real-time service delivery while complicating security perimeter design.
Blockchain-based identity verification is decentralizing citizen credential management across Australian state governments and Singapore's digital services layer. Queensland and New South Wales pilot self-sovereign identity wallets for license and benefit access. The shift reduces single-point-of-failure risks but requires new key-recovery protocols and cross-border recognition frameworks.
Singapore's IMDA data governance frameworks and Australia's Digital Transformation Agency guidelines are converging on API-first interoperability standards for government service platforms. The alignment reduces vendor re-certification burdens across both markets. Procurement templates in both jurisdictions now mandate open data formats and modular architecture, pressuring legacy system integrators to restructure offerings.
Citizen service expectations are compressing response-time benchmarks for public agencies. Municipal chatbots and automated case routing in India's smart city deployments now target sub-30-second initial engagement. The behavioral shift forces backend system modernization before front-end interfaces can deliver promised performance, creating implementation sequencing risks for undercapitalized vendors.
Asia-Pacific Smart Government Market Segmentation
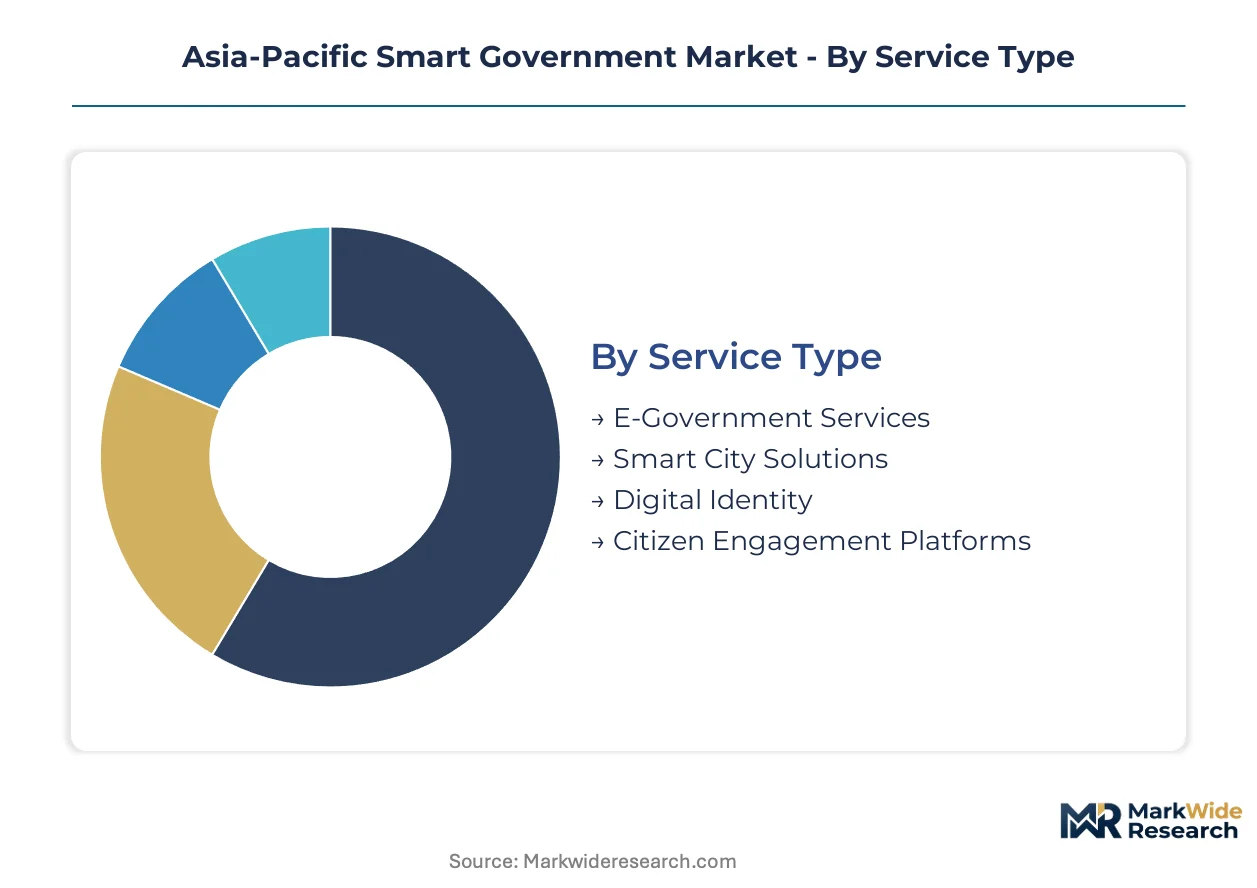
Smart government procurement across Asia-Pacific follows distinct technology refresh cycles that vary by administrative tier and legacy system burden. Understanding these upgrade patterns reveals where vendor resources generate highest returns and where integration complexity erodes margins.
Service Type:
Replacement timelines for core administrative systems diverge sharply between national platforms and municipal deployments across India, Singapore, and Australia.
- E-Government Services:Unified portal architectures consolidating fragmented agency interfaces dominate central government procurement in India and Australia. Standardized API frameworks mandated by India's Digital India initiative accelerate procurement velocity for vendors with pre-certified integration layers.
- Smart City Solutions:Urban infrastructure digitization concentrates in Indonesia's new capital development and Vietnam's secondary city expansions. IoT-enabled utility networks and integrated command centers absorb the largest share of municipal capital budgets in these jurisdictions.
- Digital Identity:Biometric authentication systems and sovereign identity wallets gain traction in Singapore and Australian state governments. Queensland and New South Wales pilot self-sovereign credential frameworks for license and benefit access.
- Citizen Engagement Platforms:Mobile-first service interfaces with sub-30-second response benchmarks spread across India's smart city missions. Automated case routing and municipal chatbots reshape service delivery expectations.
Volume placements concentrate in E-Government Services; the faster expansion belongs to Smart City Solutions.
Technology:
Cost tiering separates hyperscale cloud deployments from edge-computing architectures requiring specialized hardware integration.
- IoT Solutions:Sensor networks for traffic flow optimization and utility monitoring anchor Southeast Asian municipal procurement. 5G network densification in Singapore and South Korea enables sub-50-millisecond latency for real-time emergency coordination.
- Cloud Computing:Sovereign cloud mandates from India's BIS standards and Vietnam's cybersecurity law fragment vendor economics. Domestic data residency requirements force country-by-country infrastructure rebuilds that prevent regional scale efficiencies.
- Big Data Analytics:Predictive models for fraud detection in social welfare distribution expand fastest in India's central agencies. Data localization constraints limit cross-border analytics deployment despite technical feasibility.
- Artificial Intelligence:Explainable AI governance consulting generates premium revenue around Singapore's IMDA algorithmic accountability frameworks. Traffic optimization and public safety analytics drive ministry-level procurement across the region.
Deployment scale favors Cloud Computing; steepest expansion trajectory belongs to Artificial Intelligence.
End User:
Customer type determines procurement cycle length and contract structure flexibility across Asia-Pacific jurisdictions.
- Municipalities:Annual budget appropriations in most jurisdictions prevent multi-year SaaS contracts. Fragmented procurement across Indonesia's archipelagic geography and India's 100+ smart cities complicates vendor cash flow planning.
- Government Agencies:Whole-of-government cloud-first policies in Australia accelerate multi-tenant platform consolidation. Federal security accreditation requirements create competitive moats for established providers.
- Public Safety Organizations:Safe-city deployments in multiple Southeast Asian countries leverage integrated 5G and IoT stacks. Real-time emergency response coordination demands resilient network backbones across archipelagic terrain.
- Educational Institutions:Digital credential verification and campus management systems lag central government modernization timelines. Procurement depends on state-level education department budget cycles with irregular funding continuity.
Contract volume concentrates in Municipalities; the fastest-climbing segment is Public Safety Organizations.
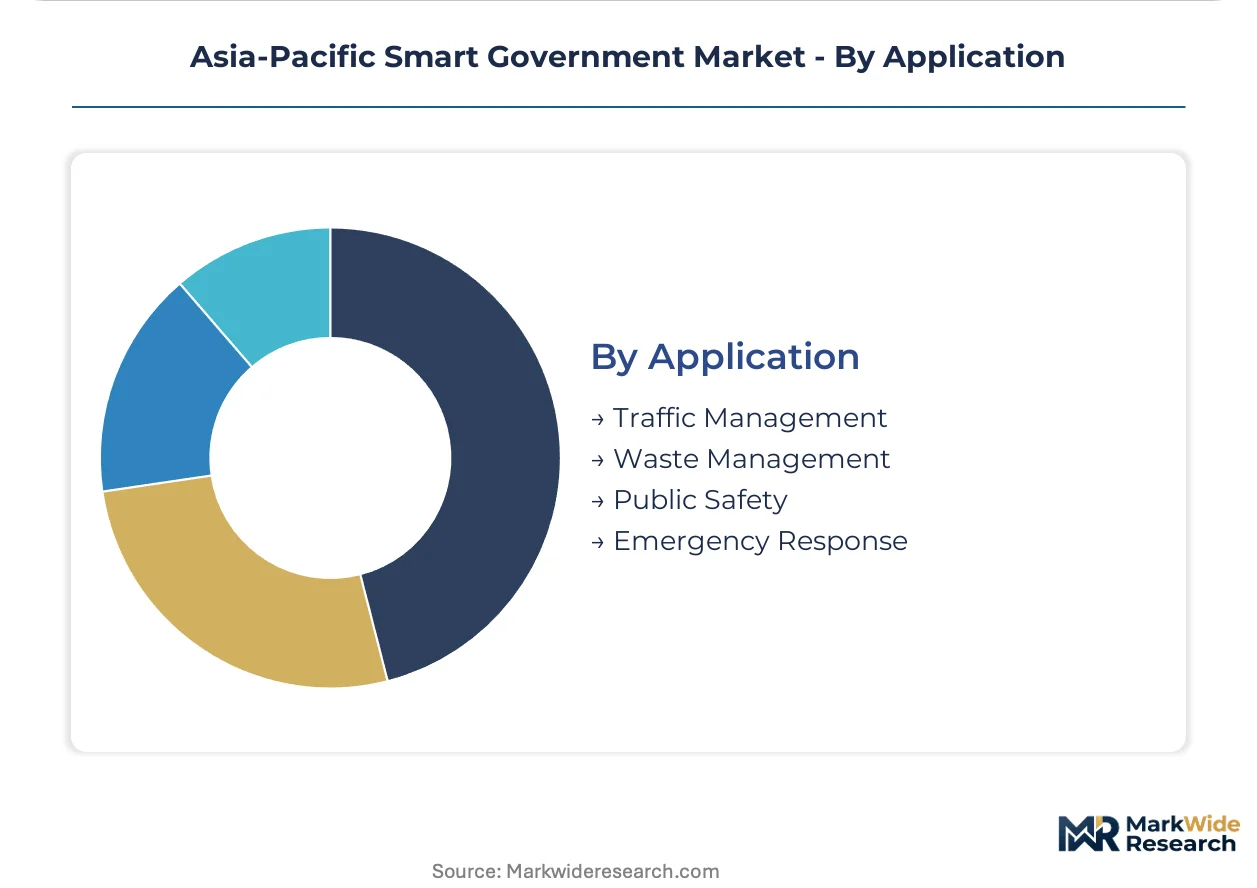
Application:
Maturity gradients separate established traffic and waste systems from emerging emergency response platforms requiring cross-agency coordination.
- Traffic Management:Congestion prediction and adaptive signal control anchor smart city deployments in Indonesia, Vietnam, and the Philippines. Legacy intersection hardware in Thailand and Malaysia requires expensive middleware layers consuming 40-60% of project budgets.
- Waste Management:Sensor-equipped collection routing and automated billing systems spread across secondary cities in India and Southeast Asia. Revenue recovery timelines challenge undercapitalized municipal vendors.
- Public Safety:Predictive analytics and automated threat detection expand with 5G infrastructure rollout in Singapore and South Korea. Cybersecurity talent gaps in Indonesian and Vietnamese government security centers constrain monitoring effectiveness.
- Emergency Response:Satellite-5G hybrid networks for island municipalities remain undersupplied in the Philippines. First-mover advantages accrue to resilient backbone providers addressing archipelagic connectivity gaps.
Installed base concentrates in Traffic Management; gaining share fastest is Emergency Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart government solution consumption concentrates in India, Singapore, and Australia, while production capacity clusters in China, Japan, and South Korea. This divergence shapes procurement patterns and vendor partnership structures across the region.
India
Digital India initiative mandates universal digital service access, driving integrated platform procurement across state and central agencies. BIS cloud standards enforce domestic data residency requirements, fragmenting vendor economics for multi-country providers. Smart city missions in Mumbai, Delhi-NCR, and Bangalore concentrate demand for IoT-enabled traffic management and automated utility billing systems.
Singapore
IMDA data governance frameworks establish algorithmic accountability rules for AI deployment in public services. Government digital services layer mandates API-first interoperability standards, reducing vendor re-certification burdens. The city-state's whole-of-government cloud architecture serves as a regional template for neighboring ASEAN members.
Australia
Digital Transformation Agency guidelines accelerate multi-tenant platform consolidation under whole-of-government cloud-first policies. Federal security accreditation requirements create competitive moats for established providers. Queensland and New South Wales pilot self-sovereign identity wallets for license and benefit access.
South Korea
5G network densification enables sub-50-millisecond latency for real-time emergency response coordination. METI-aligned standards for smart city infrastructure shape vendor qualification protocols. Seoul Capital Area deployments anchor predictive public safety analytics procurement.
Indonesia
New capital development in Nusantara drives integrated command center and IoT utility network procurement. National data-localization mandates force country-by-country cloud architecture rebuilds. Secondary city expansions in Java and Sumatra concentrate municipal capital budgets for urban infrastructure digitization.
Asia-Pacific Smart Government Market Competitive Landscape
Top-tier vendors anchor federal and central government contracts, while mid-tier specialists compete for municipal deployments across fragmented procurement frameworks. The vendor base stratifies across three archetypes: integrated infrastructure providers, sovereign cloud specialists, and AI governance consultants. Consolidation pressure intensifies as data-localization mandates multiply compliance costs and favor providers with proven multi-jurisdiction deployments. Strategic moves concentrate on federal security accreditation acquisition and partnership restructuring for country-specific cloud architectures.
Within the integrated infrastructure tier, Huawei Technologies Co., Ltd. and Cisco Systems, Inc. occupy positions exemplifying divergent approaches to safe-city and emergency-response backbone deployment. IBM represents the sovereign cloud and AI governance consulting archetype, anchoring agency advisory relationships around data-localization compliance. These three entities illustrate how vendor positioning splits across hardware-integrated stacks versus advisory-led service models in a market shaped by overlapping regulatory regimes.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Siemens AG |
| IBM |
| Accenture |
| SAP SE |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Hitachi, Ltd. |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Singapore's IMDA data governance frameworks and Australia's Digital Transformation Agency guidelines gate qualified supply for premium-tier smart government deployments, restricting vendor participation to providers with proven multi-jurisdiction compliance records while amplifying pricing power for accredited integrators.
Pricing Analysis
Margin tightening in municipal deployments reflects fragmented procurement across Indonesia's archipelagic geography and India's 100+ smart cities. Three-tier pricing structure across federal-accredited, state-certified, and municipal-basic levels separates vendors by security clearance depth. Cost compression accelerates in standard-tier cloud services as domestic data residency mandates force country-by-country infrastructure rebuilds. Municipal IT departments exhibit highest price sensitivity due to annual budget appropriations preventing multi-year SaaS contracts.
Supply Chain Analysis
Freight costs for edge-computing hardware to island municipalities in the Philippines and eastern Indonesia strain project economics for archipelagic deployments. Supply concentrates in China for IoT sensors, South Korea for 5G infrastructure components, and Japan for industrial-grade edge servers. Raw material dependencies span rare earth elements for sensor manufacturing, advanced semiconductors for AI accelerators, and specialized fiber-optic cable for resilient backbones. Single-source vulnerability in sovereign cloud certification creates bottlenecks for vendors seeking multi-country accreditation. Distribution runs through systems integrators with established federal security relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart government procurement is becoming a vertical-integration race as vendors pursue backward integration into sovereign cloud infrastructure to capture margin otherwise lost to compliance-driven architecture fragmentation.
For Market Incumbents: Deepen federal security accreditation portfolios across India's BIS standards, Australia's DTA guidelines, and Singapore's IMDA frameworks to erect competitive moats against emerging cloud-native challengers. Acquire specialized AI governance consulting capabilities to anchor agency advisory relationships around algorithmic accountability compliance. Expand in-country server deployment capacity to satisfy Vietnam's cybersecurity law and India's data localization mandates without margin-eroding subcontractor dependence. For New Entrants and Emerging Players: Capture undersupplied satellite-5G hybrid connectivity segments in the Philippines archipelago where resilient backbone infrastructure remains scarce. Target municipal emergency response platforms in Indonesia's Nusantara new capital development before incumbent network providers consolidate command-center contracts. Enter through API-first interoperability specializations that reduce re-certification burdens across Singapore-Australia procurement alignment. For Investors and Strategic Acquirers: Australia's whole-of-government cloud-first policy acceleration is the leading indicator that federal security accreditation scarcity will concentrate vendor economics among pre-qualified providers. Position acquisition screening around mid-tier systems integrators holding multi-jurisdiction compliance certifications but lacking capital for sovereign cloud infrastructure buildout. Monitor India's smart city mission procurement velocity as the signal for regional platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Buildout | Domestic data residency mandates in India and Vietnam force country-specific server deployment that prevents regional scale efficiencies. |
| AI Governance Consulting Acquisition | Singapore's IMDA algorithmic accountability rules create premium advisory revenue streams around explainable AI deployment. |
| Federal Security Accreditation Investment | Australia's Digital Transformation Agency requirements reward vendors with whole-of-government certification. |
| API-First Platform Integration | Converging interoperability standards between Singapore and Australia reduce vendor re-certification burdens. |
| Archipelagic Connectivity Partnership | Philippines island municipalities remain undersupplied for satellite-5G hybrid emergency response networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with smart city program directors, government CIOs, sovereign cloud architects, and municipal procurement officers. BIS cloud standard documentation, Digital Transformation Agency guidelines, and IMDA framework disclosures provided compliance requirement baselines. Bottom-up project pipeline tracking across India's 100 smart cities combined with top-down government IT budget appropriation analysis to triangulate market sizing.
Granularity-level modeling deployed service-type, technology tier, end-user administrative level, and application maturity gradients across the projection horizon. CAGRs derived from segment-specific procurement velocity indices weighted by legacy system integration debt factors. Forecast inputs incorporated 5G network densification timelines, data-localization mandate implementation schedules, and skilled solution architect supply constraints.
The model holds under stable regulatory enforcement trajectories; deviation in data-residency rule expansion or cybersecurity law tightening would shift vendor economics and partnership structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Platform Architecture Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Digital Notepad Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Stylus Pen for Education Market