
 Fault Tolerant Servers Market | 2026-2036
Fault Tolerant Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Fault Tolerant Servers Market Intelligence
Mainframe engineering talent scarcity is unwinding supply elasticity across the fault tolerant server value chain. NEC Corporation leverages deep proprietary expertise in continuous availability architectures to anchor its position in telecommunications infrastructure. Stratus Technologies sustains competitive differentiation through specialized ftServer platforms designed for edge and industrial environments. Hewlett Packard Enterprise dominates enterprise-class nonStop systems for financial clearing and settlement applications.
Fault tolerant servers are computing systems engineered with redundant hardware components, lockstep processing, and automatic failover mechanisms to deliver continuous operation with zero unplanned downtime, typically achieving availability metrics of 99.999% or higher for mission-critical workloads. These systems employ duplicate memory modules, mirrored processors executing identical instruction streams in synchronization, and hot-swappable power supplies to eliminate single points of failure across the compute, storage, and networking subsystems. Rack servers occupy the largest installed base among product type categories, reflecting enterprise data center standardization and density requirements, while blade server configurations are gaining traction in cloud service provider environments where space and thermal efficiency carry premium value. Edge computing deployments represent the fastest-expanding segment, driven by latency-sensitive manufacturing automation and autonomous vehicle infrastructure requiring localized resilience without cloud dependency.
FDA 21 CFR Part 11 requirements for electronic records in pharmaceutical manufacturing and clinical trials mandate validated system uptime, directly sustaining demand for fault tolerant platforms in regulated healthcare environments. The EU NIS2 Directive imposes stricter operational resilience obligations on critical infrastructure operators, compelling upgrades across energy, transport, and digital infrastructure sectors. Stakeholders must weigh the total cost of ownership for proprietary fault tolerant architectures against software-defined resilience alternatives as workload portability and hybrid cloud orchestration mature.
Market Dynamics
Lockstep processing architectures face mounting pressure from software-defined availability alternatives as enterprises reassess proprietary hardware commitments against cloud-native resilience patterns.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators across energy and transport sectors must upgrade operational resilience, compelling fault tolerant server deployments to meet mandatory uptime obligations.
- Edge computing infrastructure:Autonomous vehicle testing facilities and smart manufacturing plants in Germany require localized zero-downtime computing without cloud dependency.
- Electronic records validation:FDA 21 CFR Part 11 mandates for pharmaceutical manufacturing sustain demand for continuously available systems in regulated healthcare environments.
Market Restraints
- Proprietary component sourcing:Lockstep memory modules and specialized processors concentrate supply among limited semiconductor fabricators, exposing buyers to allocation risk.
- Software-defined substitutes:Distributed consensus algorithms and container orchestration platforms erode the economic case for dedicated fault tolerant hardware in non-regulated workloads.
- Specialized engineering scarcity:Mainframe-class continuous availability expertise concentrates among aging practitioner pools, constraining deployment velocity and support scalability.
Strategic Opportunities
- Industrial edge expansion:Automotive automation clusters in Stuttgart and Wolfsburg present concentrated demand for ruggedized fault tolerant platforms in quality-critical inspection systems.
- Telecommunications infrastructure:5G core network functions and Open RAN deployments require carrier-grade availability at distributed cell sites previously served by centralized data centers.
- EU AI Act compliance:High-risk AI system providers must demonstrate operational resilience, creating regulated demand for hardware-level fault tolerance in inference infrastructure.
Industry Challenges
- Legacy integration complexity:Financial clearing applications running on decades-old transaction processing architectures resist migration to modern fault tolerant platforms without extensive revalidation.
- Certification timeline compression:IEC 61508 functional safety assessments for industrial automation deployments extend sales cycles and strain pre-sales engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fault Tolerant Servers Market |
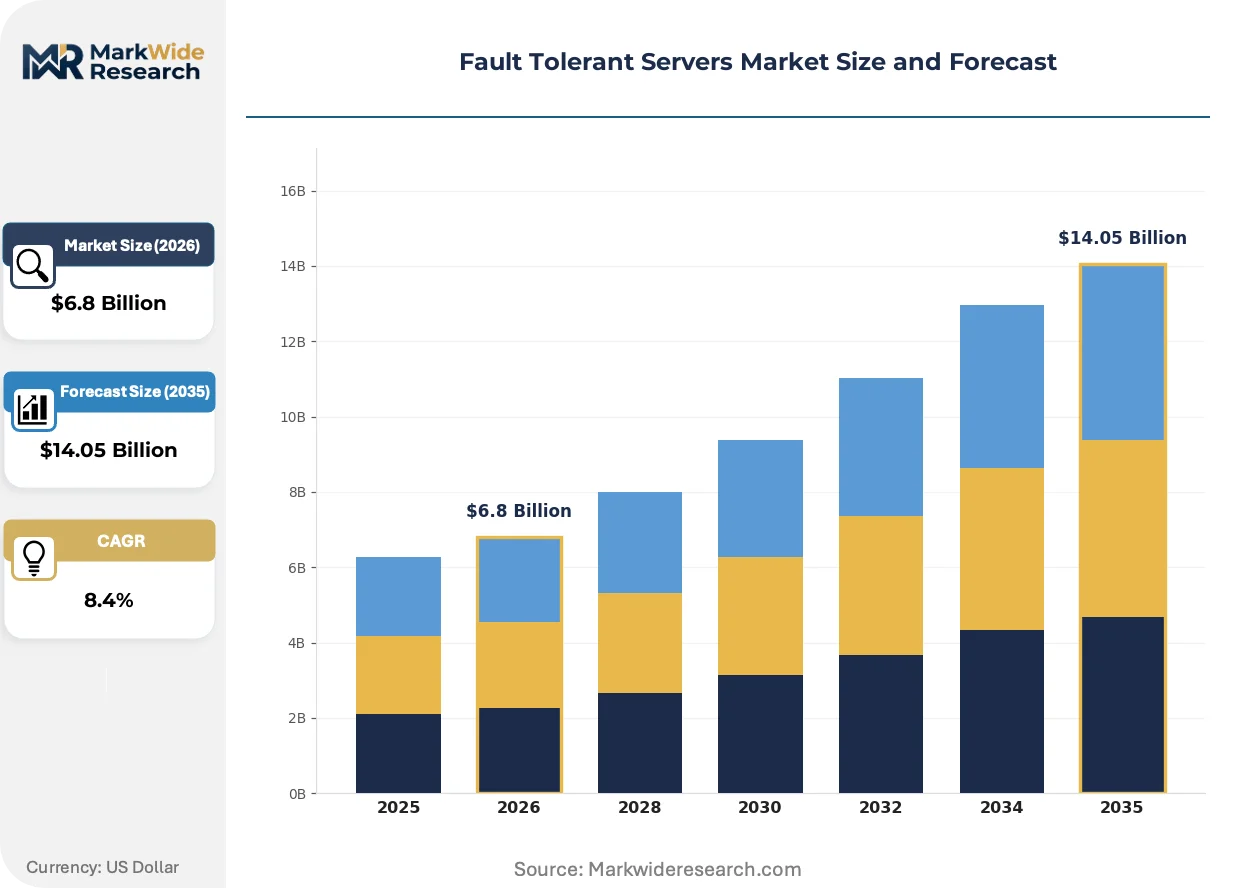
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Mainframe Servers Technology: Redundant Array of Independent Disks, Load Balancing, Clustering, Failover Systems End User: Telecommunications, Aerospace, Financial Services, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Stratus Technologies, NEC Corporation, Dell Technologies, Lenovo, Oracle Corporation, Hewlett Packard Enterprise, Unisys Corporation, Cisco Systems, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fault Tolerant Servers Market Strategic Shifts & Innovations
Hardware redundancy patterns are fragmenting as software-defined resilience matures, forcing traditional fault tolerant vendors to defend proprietary architectures against cloud-native alternatives.
Lockstep processor pairs executing mirrored instruction streams is miniaturizing into system-on-chip configurations for edge deployment. Automotive tier-one suppliers in Germany now integrate these compact modules directly into production line controllers. This compression is miniaturizing the physical footprint of fault tolerant computing from rack-scale appliances to DIN-rail mountable units.
EU AI Act risk classification rules now mandate operational resilience documentation for high-risk AI systems deployed in critical infrastructure. Energy utilities and healthcare providers face expanded audit obligations under NIS2 transposition deadlines. German digital infrastructure operators report the steepest compliance investment curves as federal regulators enforce cross-sector harmonization.
Capital equipment purchasing committees now unbundle hardware acquisition from long-term service contracts previously sold as integrated packages. Industrial buyers in automotive and pharmaceutical verticals negotiate maintenance and support separately, compressing vendor margin structures. This pattern concentrates in German manufacturing clusters where procurement centralization has matured across multi-site enterprises.
Fault Tolerant Servers Market Segmentation
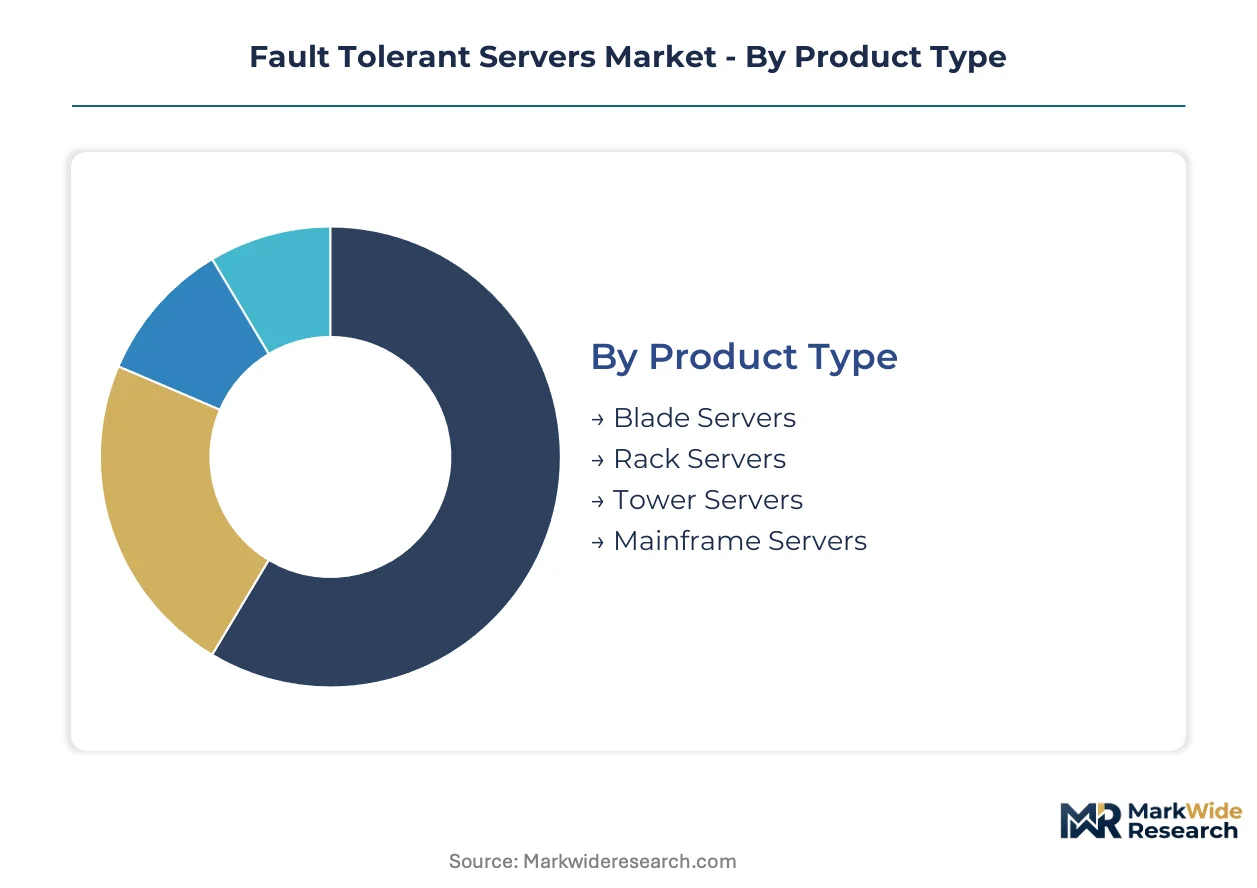
Fault tolerant server architectures fragment across hardware form factors, resilience mechanisms, and deployment topologies. Procurement committees evaluate these dimensions against workload criticality, regulatory exposure, and total cost of ownership constraints.
Product Type:
Rack servers dominate domestic enterprise data center procurement, while blade configurations concentrate in export-led hyperscale deployments.
- Rack Servers:Standardized 19-inch form factors accommodate redundant power supplies and lockstep processor pairs in enterprise facilities. Financial clearing houses in Frankfurt and Singapore specify these units for core transaction processing infrastructure. Density requirements and thermal management drive consolidation toward this category.
- Blade Servers:Modular chassis architectures share cooling and power infrastructure across multiple compute nodes. Cloud service providers in Ireland and the Netherlands deploy these for multi-tenant resilience at reduced floor space. Shared backplane designs complicate fault isolation compared to discrete rack units.
- Tower Servers:Standalone vertical enclosures serve branch office and small data center deployments with limited rack infrastructure.
- Mainframe Servers:Proprietary continuous availability architectures sustain legacy transaction processing workloads in regulated banking environments.
Rack servers hold the largest share; momentum sits with blade servers in cloud provider procurement.
Technology:
Cost tier separation distinguishes hardware-level redundancy from software-orchestrated resilience patterns.
- Failover Systems:Automated switchover mechanisms redirect workloads to standby components upon primary system detection of fault conditions. Healthcare providers in the United States deploy these for FDA 21 CFR Part 11 compliant electronic records infrastructure. Detection latency and state synchronization complexity constrain recovery time objectives.
- Clustering:Distributed node architectures coordinate workload distribution across geographically separated compute resources. Telecommunications operators in Germany utilize these for 5G core network function distribution under EU NIS2 resilience mandates. Network partition tolerance introduces consistency trade-offs versus single-system alternatives.
- Redundant Array of Independent Disks:Mirrored storage subsystems eliminate data loss from individual drive failures through parity and replication schemes.
- Load Balancing:Traffic distribution algorithms optimize resource utilization across available compute capacity without inherent fault tolerance guarantees.
Failover systems command premium pricing tiers; clustering gains share fastest in distributed infrastructure deployments.
End User:
Application criticality determines tolerance for recovery time, with financial and healthcare segments demanding near-zero interruption.
- Financial Services:Real-time payment clearing and securities settlement systems require lockstep processor synchronization to prevent transaction loss. Trading venues in London and Chicago specify 99.999% availability metrics in procurement contracts. Regulatory capital requirements for operational risk amplify the cost of downtime.
- Healthcare:Electronic health record systems and clinical trial data management platforms face FDA validation requirements for system continuity. Hospital networks in the United States and university medical centers in Germany sustain demand for hardware-certified uptime guarantees. Patient safety considerations override cost optimization in purchasing decisions.
- Telecommunications:Carrier-grade infrastructure for voice and data services mandates resilience across distributed network elements.
- Aerospace:Flight control systems and air traffic management platforms require deterministic failure recovery within milliseconds.
Financial services generates the largest revenue concentration; healthcare exhibits the steepest compliance-driven expansion trajectory.
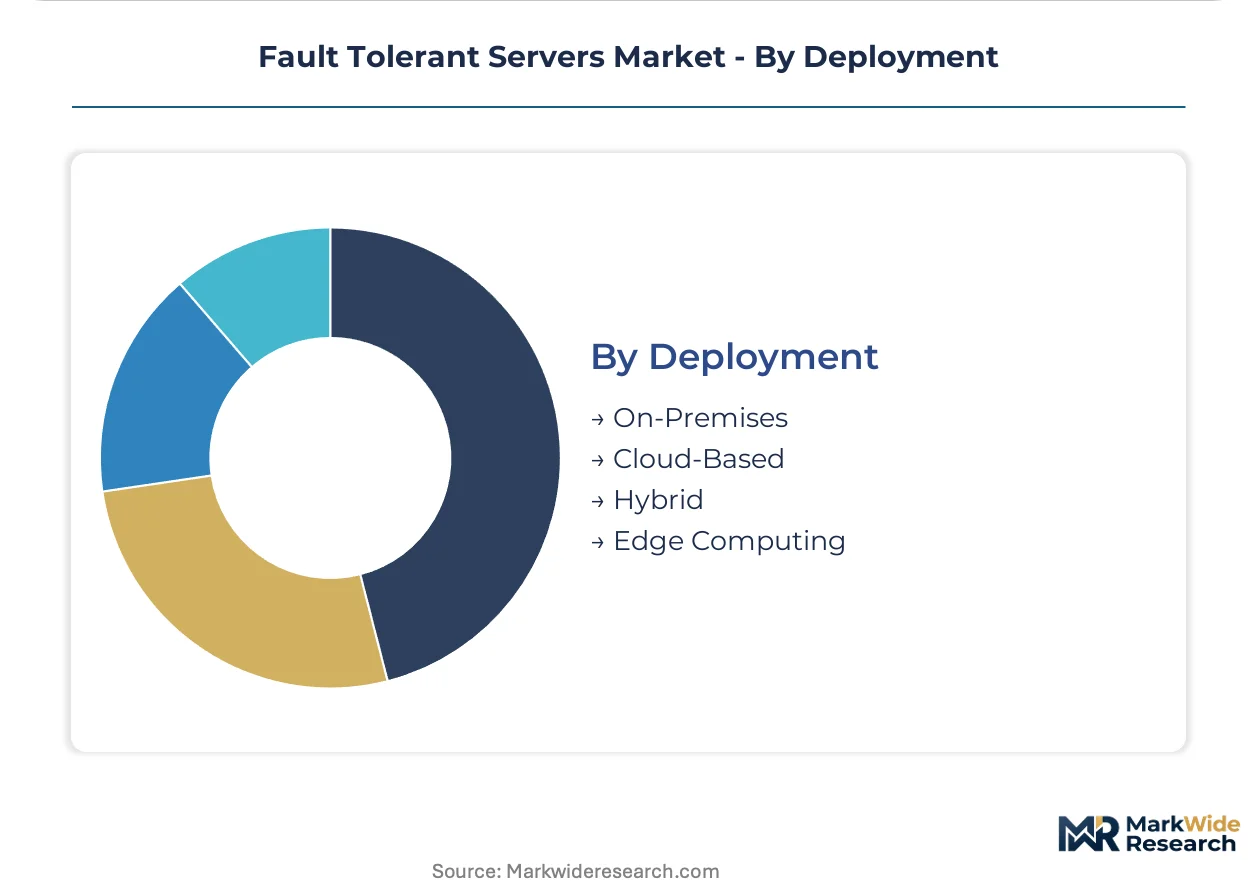
Deployment:
Maturity gradients separate established on-premises installations from emerging edge computing architectures.
- Edge Computing:Localized resilience without cloud dependency serves autonomous vehicle testing facilities and smart manufacturing plants. Automotive clusters in Stuttgart and Wolfsburg deploy ruggedized platforms for quality-critical inspection systems. Latency constraints and connectivity intermittency preclude centralized alternatives.
- Hybrid:Orchestrated workload portability across on-premises and cloud infrastructure balances control with elasticity. Pharmaceutical manufacturers in Switzerland and the United States adopt these configurations for validated environments with burst capacity needs. Data sovereignty requirements complicate cloud-native migration.
- On-Premises:Dedicated facility deployments retain full operational control over physical security and change management.
- Cloud-Based:Managed service offerings abstract hardware resilience through software-defined availability patterns.
On-premises retains dominant installed base; edge computing climbs the fastest among deployment modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fault tolerant servers for automotive automation clusters, while the United States concentrates demand in financial clearing infrastructure. China deploys these systems for telecommunications resilience. Japan maintains specialized expertise in continuous availability architectures.
Germany
Automotive tier-one suppliers and industrial automation clusters drive procurement in Stuttgart and Wolfsburg. The EU NIS2 Directive compels energy utilities and transport operators to upgrade operational resilience. Manufacturing facilities in Baden-Württemberg deploy ruggedized platforms for quality-critical inspection systems.
United States
Financial services institutions in New York and Chicago specify 99.999% availability for real-time payment clearing systems. FDA 21 CFR Part 11 mandates sustain demand for validated uptime in pharmaceutical manufacturing. Hospital networks across the Midwest and Southeast sustain hardware-certified continuity investments.
China
Telecommunications infrastructure expansion for 5G core networks requires carrier-grade resilience at distributed cell sites. The national cybersecurity regulator imposes operational continuity obligations on critical digital service providers. Manufacturing automation in the Yangtze River Delta generates localized zero-downtime computing requirements.
Japan
Telecommunications infrastructure and legacy continuous availability expertise concentrate procurement among specialized system integrators. METI industrial policy supports domestic resilience technology development. Tokyo-based engineering pools maintain deep proprietary knowledge in lockstep processing architectures.
United Kingdom
Financial clearing venues in London specify stringent availability metrics for securities settlement systems. The national cyber security center mandates resilience standards for critical infrastructure operators. Edinburgh and Manchester host expanding data center clusters serving European financial services demand.
Fault Tolerant Servers Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in fault tolerant server supply. NEC Corporation and Hewlett Packard Enterprise anchor the upper tier with proprietary continuous availability architectures. Stratus Technologies occupies the specialized industrial edge segment. Competitive moves concentrate on portfolio diversification into software-defined resilience alternatives and strategic partnerships for hybrid cloud orchestration capabilities.
Among integrated technology conglomerates, NEC Corporation and Hewlett Packard Enterprise exemplify the proprietary architecture archetype through deep investments in lockstep processing expertise. Stratus Technologies represents the specialized tier focused on edge and industrial environments. Dell Technologies and Lenovo occupy positions within the broader enterprise server supply base, serving workloads where hardware-level fault tolerance competes with software-defined substitutes. These groupings illustrate how vendor positioning fragments across workload criticality tiers and regulatory exposure levels.
| Leading Market Players |
|---|
| Stratus Technologies |
| NEC Corporation |
| Dell Technologies |
| Lenovo |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Unisys Corporation |
| Cisco Systems |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Capacity utilization at specialized semiconductor foundries in Taiwan and Japan anchors cost structures across the fault tolerant server value chain, concentrating supply-side leverage among a handful of fabricators while compressing margin flexibility for downstream system integrators. Lockstep processor pairs and redundant memory modules command premium wafer allocations, translating fabrication tightness directly into hardware price floors for enterprise buyers.
Pricing Analysis
Long-term service contracts dominate procurement patterns in financial services and healthcare verticals, with three-tier pricing structure across premium, standard, and economy levels separating hardware-certified uptime guarantees from software-resilience alternatives. Price differentiation hinges on IEC 61508 functional safety certification tier and bundled field engineering support density. Cost compression in mid-range failover configurations is intensifying because container orchestration platforms erode the economic case for proprietary hardware in non-regulated workloads. Cloud service providers exhibit highest price sensitivity; regulated pharmaceutical manufacturers show least elasticity due to FDA validation requirements.
Supply Chain Analysis
Extended lead times for lockstep-capable processors and specialized redundant power supplies stretch procurement cycles to 26-32 weeks, constraining deployment velocity for industrial automation projects. Manufacturing concentration rests on Taiwan, Japan, and the United States for mission-grade semiconductors, with Germany and China contributing precision mechanical assemblies and thermal management subsystems. Single-source vulnerability concentrates in EUV lithography-dependent fabrication nodes for high-reliability processors. Distribution runs through authorized system integrators and direct OEM relationships, bypassing commodity IT channel partners due to pre-sales engineering requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization across multi-site automotive and pharmaceutical enterprises has shifted negotiating leverage toward buyer consortiums, fragmenting vendor pricing power and unbundling hardware from service contracts.
For Market Incumbents: Compound proprietary lockstep expertise through captive silicon design partnerships that secure wafer allocation priority at TSMC and GlobalFoundries. Deepen field engineering certification programs to counter software-defined availability substitutes encroaching from cloud-native infrastructure providers. Vertical integration into edge computing form factors preserves margin in Stuttgart and Wolfsburg automation clusters where ruggedized DIN-rail units command premium positioning. For New Entrants and Emerging Players: Differentiate on hybrid cloud orchestration capabilities that bridge on-premises fault tolerant hardware with burst elasticity, targeting pharmaceutical manufacturers in Switzerland and the United States with validated environment portability. The most penetrable white space sits in telecommunications edge deployments for Open RAN distributed units, where carrier-grade availability requirements meet limited incumbent presence. A channel-centric go-to-market through German system integrators accelerates referenceability in EU NIS2 compliance-driven upgrades. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized industrial edge vendors with software-defined resilience roadmaps over pure hardware plays facing cloud substitution. Long-term viability hinges on workload portability architecture investments that preserve relevance as hybrid orchestration matures. Acquisition targets should demonstrate IEC 61508 certification pipelines and established relationships with automotive tier-one suppliers. The signal to watch is container orchestration penetration rates in financial services clearing applications, where sustained hardware preference validates proprietary architecture durability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Lockstep hardware interoperability with Kubernetes orchestration layers preserves relevance in hybrid cloud migrations. |
| Geographic Expansion | Localized assembly in Baden-Württemberg reduces delivery friction for Stuttgart automotive automation clusters. |
| Strategic Partnership | Silicon co-development agreements with TSMC secure wafer allocation for mission-grade processor pairs. |
| Product Launch | System-on-chip lockstep modules for DIN-rail deployment capture edge computing growth in quality-critical inspection systems. |
| Acquisition of Specialist Firm | Industrial edge software stacks complement hardware portfolios against cloud-native resilience substitutes. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center infrastructure directors, industrial automation engineers, telecommunications network architects, and financial services technology officers. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, IEC standards documentation, and EU regulatory transposition notices. Bottom-up triangulation across procurement volume estimates and top-down reconciliation against installed base depreciation curves anchored market sizing.
Across the analysis window, projections modeled hardware form factor segmentation alongside resilience mechanism tiers, deployment topology patterns, and vertical regulatory exposure levels. CAGRs were derived from elasticity-adjusted replacement cycles and compliance-driven upgrade timelines. Forecast inputs incorporated EU NIS2 transposition velocity, FDA 21 CFR Part 11 enforcement patterns, and automotive automation cluster expansion trajectories in Germany.
Forecasts assume regulatory continuity in EU NIS2 implementation and FDA validation frameworks; material policy shifts or accelerated software-defined availability adoption would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Market