
 KVM Market | 2026-2036
KVM Market Size, Share, and Industry Trends Forecast 2026-2036
KVM Market Outlook
Taiwanese electronics manufacturing capacity is hardening around high-density KVM hardware production. ATEN INTERNATIONAL Co., Ltd. leverages its Kaohsiung manufacturing base to dominate enterprise-grade switch distribution across East Asia. Dell Inc. sustains channel control through embedded KVM modules inside PowerEdge server lines. GIGA-BYTE Technology Co., Ltd. anchors motherboard-integrated KVM silicon for hyperscale data center builds.
A keyboard, video, and mouse (KVM) switch is a hardware or software subsystem that enables centralized control of multiple computers through a single console interface, typically supporting video resolutions up to 4K at 60Hz and USB-HID signal aggregation across 16 to 64 ports. Its primary commercial purpose is eliminating redundant peripherals in server farms, broadcast control rooms, and industrial SCADA environments to reduce cabling complexity and operator station footprint. Hardware KVM units still occupy the largest revenue pool in data center buildouts, though KVM over IP is recording the fastest expansion as remote IT management becomes standard. Digital signal processing dominates technology adoption, while analog legacy lines persist mainly in cost-sensitive industrial automation retrofits.
FCC emissions compliance shapes US market access for KVM over IP devices, while EU REACH substance restrictions and CE marking obligations govern cable and chassis material selection for European shipments. India's BIS mandatory registration scheme blocks uncertified imports, pushing Vertiv Group Corp. and Raritan Americas, Inc. to localize testing partnerships. Procurement teams must weigh IP-based remote management capabilities against air-gapped security requirements when refreshing console infrastructure.
Market Dynamics
Remote IT management mandates are compressing hardware refresh cycles while IP-based console infrastructure displaces legacy analog deployments in data center buildouts. This structural pull is forcing procurement teams to reconcile air-gapped security requirements with centralized management capabilities across hybrid server environments.
Growth Catalysts
- EU Green Deal energy efficiency mandates:German data center operators are expanding KVM deployments to manage hybrid infrastructure under binding carbon reduction targets, driving hardware replacement in Frankfurt and Munich server clusters.
- India's PLI scheme incentives:Domestic procurement of IP-based KVM systems is accelerating as BIS certification requirements and production-linked incentives reshape enterprise IT modernization budgets.
- 4K video resolution standards:Broadcast control rooms and media production facilities are upgrading console infrastructure to support uncompressed 4K at 60Hz signal aggregation across multi-source workflows.
Market Restraints
- Copper and rare earth input volatility:Chassis manufacturing and high-density cable assemblies face margin pressure from fluctuating commodity costs in Taiwanese and Chinese component supply bases.
- FCC emissions compliance friction:KVM over IP device certification creates timeline risk for US market entry, with testing protocols adding four to six months to product launch schedules.
- Software-based remote desktop substitution:Microsoft Remote Desktop and Chrome Remote Desktop are capturing low-complexity use cases in small-office environments, compressing addressable volume for entry-level hardware switches.
Strategic Opportunities
- Industrial automation retrofits in Eastern Europe:Analog-to-digital KVM migration in Polish and Romanian manufacturing facilities presents white-space demand as EU cohesion funds modernize legacy SCADA environments.
- Edge computing micro data centers:5G rollout and IoT aggregation points are creating new console management requirements in distributed telecom infrastructure and smart city deployments.
- India's BIS localization partnerships:Testing and certification alliances with domestic labs are unlocking public-sector procurement channels previously blocked to uncertified import streams.
Industry Challenges
- Cybersecurity certification timelines:Common Criteria and FIPS 140-2 validation for government and defense deployments extends product development cycles by twelve to eighteen months.
- Legacy BIOS integration complexity:Out-of-band management compatibility with aging server fleets requires firmware customization that strains engineering resources and delays hyperscale contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | KVM Market |
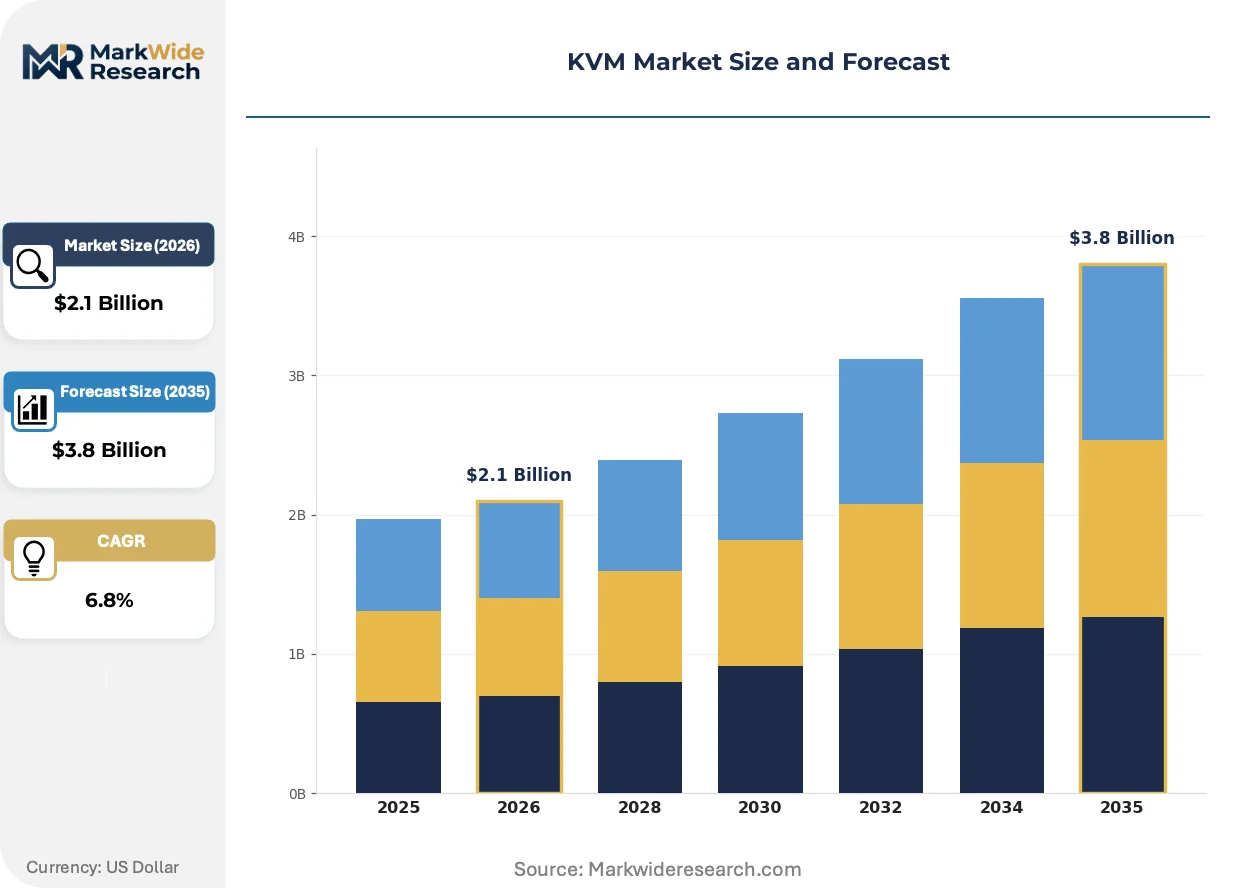
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware KVM, Virtual KVM, Integrated KVM, KVM over IP Technology: Analog, Digital, USB, HDMI Application: Data Centers, Broadcast, IT Management, Industrial Automation End User: Enterprises, SMEs, Government, Educational Institutions |
| Companies Covered | Vertiv Group Corp., ATEN INTERNATIONAL Co., Ltd., IEC., PROSUM, Rextron International Inc., Dell Inc., GIGA-BYTE Technology Co., Ltd., Shenzhen CKL Technology Co., Ltd., Raritan Americas, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
KVM Market Strategic Shifts
KVM over IP is overtaking analog matrix switching as the dominant console architecture, with signal compression and encryption advances enabling secure remote access previously restricted to physical presence. This technology rotation is compressing the hardware-software boundary and reshaping vendor competitive sets.
Digital KVM switches with embedded FPGA signal processors are overtaking ASIC-based legacy designs in enterprise data center procurement. Hyperscale operators in Ashburn and Singapore are specifying these units for sub-millisecond latency in high-frequency trading and real-time analytics environments. The shift is overtaking traditional hardware vendors who lack in-house semiconductor design capabilities.
EU REACH substance restrictions on halogenated flame retardants are forcing chassis and cable material reformulation for European shipments. German and Dutch distributors are now requiring full material disclosure documentation before contract execution. Server OEMs with integrated KVM modules are absorbing compliance costs into PowerEdge and ProLiant line pricing to maintain channel position.
Subscription-based firmware and management software licensing is displacing perpetual purchase models in enterprise procurement. Channel partners in North America are bundling three-year support contracts with hardware sales to capture recurring revenue streams. This behavioral shift is most visible in healthcare and financial services verticals where cybersecurity update mandates compress refresh decision cycles.
KVM Market Segmentation
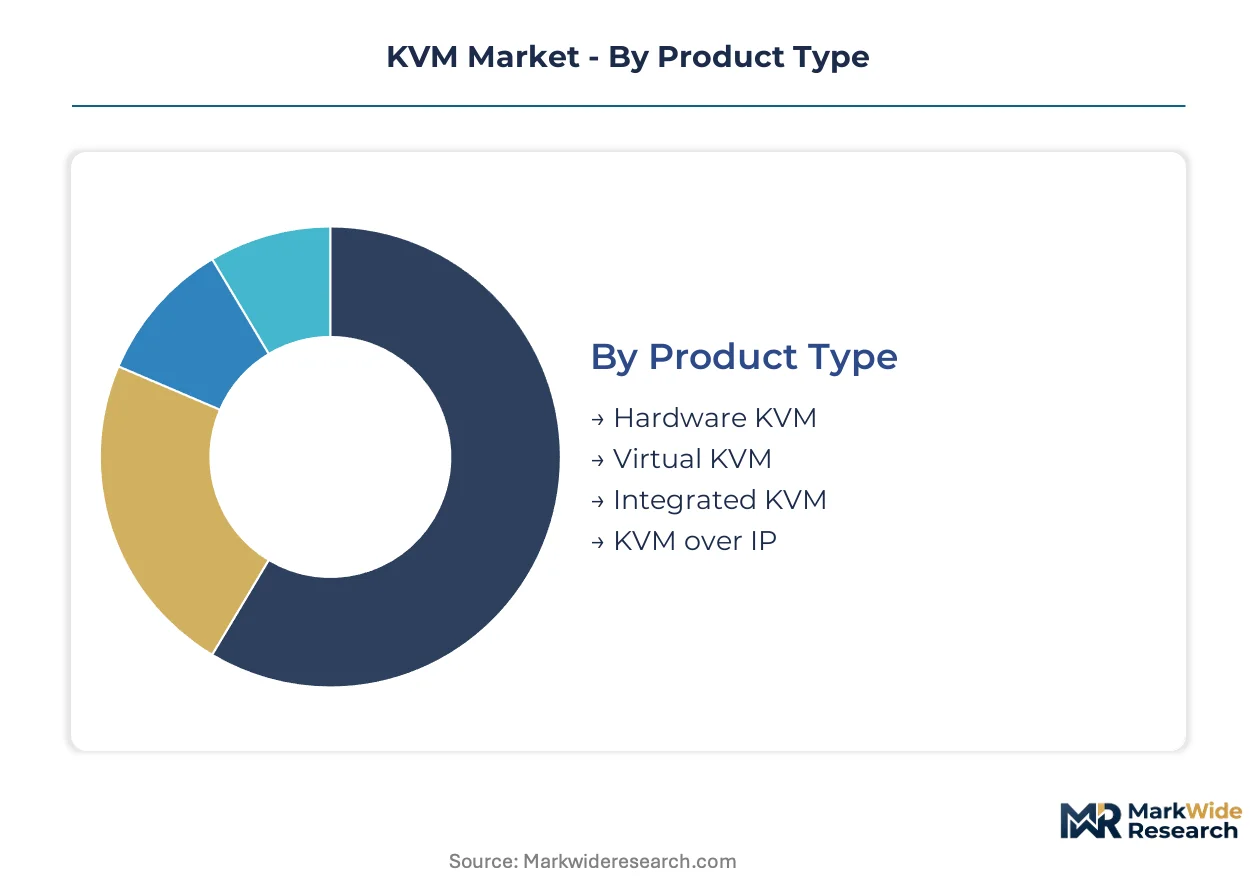
KVM procurement decisions hinge on balancing legacy infrastructure compatibility against remote management requirements. The four segmentation dimensions reveal how upgrade cycles, technology transitions, and end-user scale reshape vendor positioning across console infrastructure markets.
Product Type:
Hardware refresh cycles diverge sharply between embedded modules and standalone appliances, with procurement teams weighing rack density against software-defined flexibility.
- Hardware KVM:Dedicated rack-mounted appliances with dedicated switching matrices and physical port aggregation dominate Frankfurt and Munich data center buildouts under EU Green Deal efficiency mandates. German operators favor these units for deterministic latency in hybrid infrastructure management.
- KVM over IP:Network-encoded console access with AES-256 encryption and browser-based session management is displacing analog deployments in India's enterprise modernization push. BIS certification requirements and PLI scheme incentives accelerate domestic procurement of these systems for remote IT management.
- Virtual KVM:Software-layer console virtualization running on hypervisor hosts eliminates dedicated appliance footprint in edge computing micro data centers.
- Integrated KVM:Motherboard-embedded baseboard management controllers with KVM-over-LAN capability ship standard in hyperscale server builds.
Volume placements concentrate in Hardware KVM; the faster expansion belongs to KVM over IP.
Technology:
Signal processing architecture determines upgrade timing, with digital designs commanding premium positioning while analog persists in cost-sensitive industrial retrofits.
- Digital:FPGA-based signal processors with sub-millisecond latency and 4K 60Hz uncompressed video paths dominate high-frequency trading and real-time analytics environments in Singapore and Ashburn. Hyperscale operators specify these units for deterministic performance.
- Analog:Direct electrical switching of VGA and PS/2 signals persists in Polish and Romanian manufacturing facilities modernizing legacy SCADA environments with EU cohesion funds. These deployments prioritize capital efficiency over remote access capability.
- USB:Human interface device aggregation with USB 3.0 high-speed data tunneling supports modern peripherals in broadcast control rooms.
- HDMI:Consumer-electronics video interface adoption in media production facilities enables uncompressed 4K signal distribution.
Procurement volume clusters in Digital technology; Analog maintains residual demand in Eastern European industrial automation.
Application:
Console infrastructure requirements scale with operational criticality, from always-on data center operations to intermittent industrial maintenance access.
- Data Centers:Multi-thousand-port console aggregation with centralized authentication and session logging supports hybrid cloud management in German Frankfurt and Munich clusters. EU Green Deal carbon reduction targets drive hardware replacement in these facilities.
- Broadcast:Uncompressed 4K 60Hz multi-source workflows with genlock synchronization and frame-accurate switching serve media production facilities upgrading console infrastructure.
- IT Management:Distributed enterprise server rooms with mixed-vendor equipment require flexible console access across heterogeneous infrastructure.
- Industrial Automation:Harsh-environment chassis with extended temperature ranges and vibration tolerance protect console access in manufacturing floor deployments.
Revenue concentration sits with Data Centers; Broadcast applications show steepest expansion trajectory as 4K production standards proliferate.
End User:
Scale and compliance requirements segment procurement behavior, from centralized government certification mandates to decentralized SME purchasing.
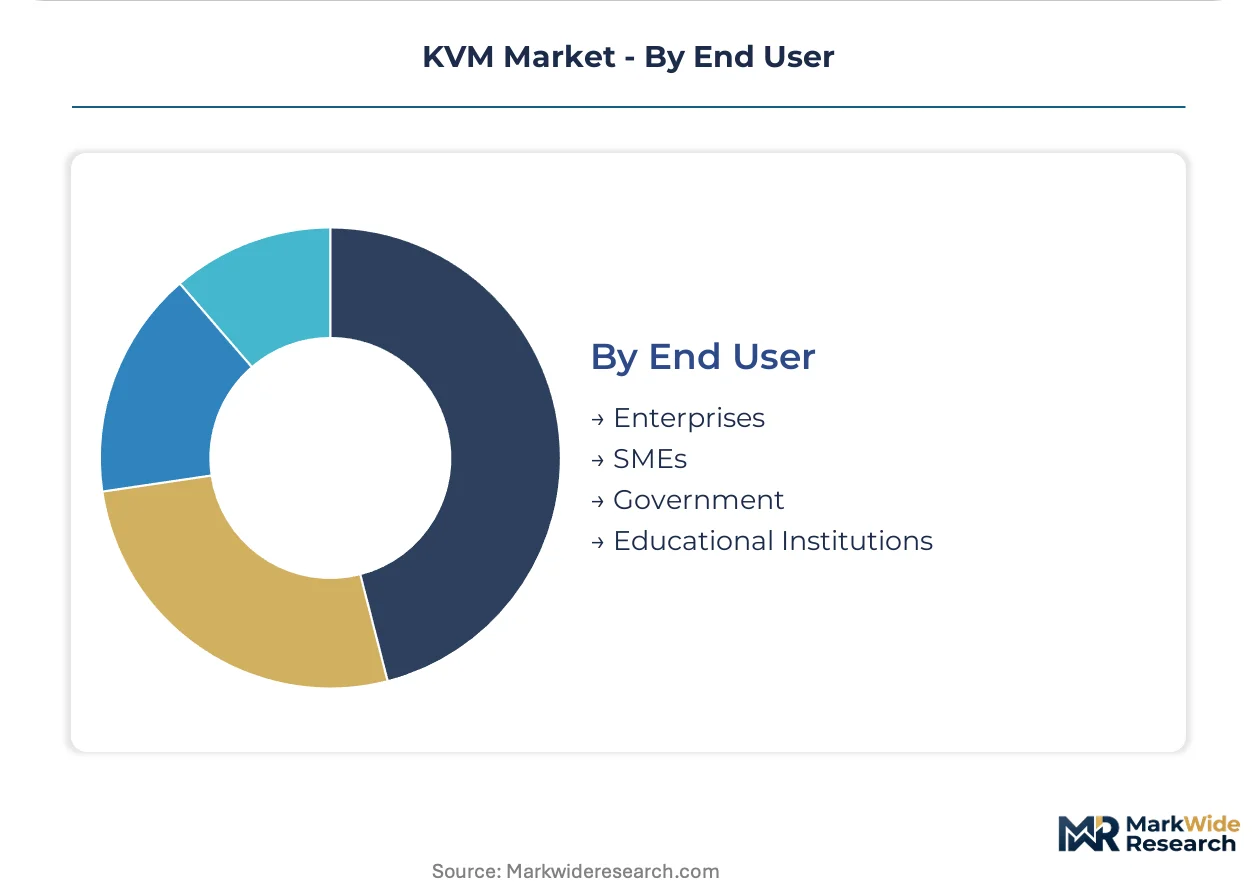
- Enterprises:Multi-site console standardization with centralized procurement and three-year support contracts dominates healthcare and financial services verticals. Cybersecurity update mandates compress refresh decision cycles in these organizations.
- Government:Common Criteria and FIPS 140-2 validation requirements extend product development cycles by twelve to eighteen months for defense and classified deployments.
- SMEs:Price-sensitive purchasing of entry-level hardware switches faces substitution pressure from Microsoft Remote Desktop and Chrome Remote Desktop in small-office environments.
- Educational Institutions:Budget-constrained procurement favors virtual KVM and software-based solutions for computer lab management.
Enterprise accounts drive absolute volume; Government procurement carries longest sales cycles but highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese copper and rare earth processing capacity anchors console hardware manufacturing across East Asian supply chains. German industrial demand shapes European procurement standards through binding efficiency regulations.
United States
FCC emissions compliance timelines and hyperscale data center buildouts drive procurement of IP-based console systems. The IRA energy efficiency provisions accelerate hardware replacement in Virginia and Texas server clusters. Ashburn operators specify FPGA-based units for sub-millisecond latency in financial trading environments.
Germany
EU Green Deal carbon reduction mandates compel Frankfurt and Munich operators to refresh hybrid infrastructure management systems. REACH substance restrictions govern halogenated flame retardant reformulation in chassis manufacturing. Bavarian distributors now require full material disclosure documentation before contract execution.
India
BIS mandatory registration schemes block uncertified import streams while PLI scheme incentives reshape enterprise IT modernization budgets. Domestic testing partnerships unlock public-sector procurement channels previously closed to foreign vendors. Maharashtra and Karnataka data center clusters lead deployment of certified IP-based systems for remote management.
Taiwan
High-density hardware production capacity concentrates around Kaohsiung manufacturing bases serving East Asian distribution networks. Component supply volatility in copper and rare earth inputs creates margin pressure across cable assembly operations. Local fabricators dominate enterprise-grade switch production for regional hyperscale builds.
Poland
EU cohesion fund allocations modernize legacy SCADA environments through analog-to-digital console migration. Industrial automation retrofits in Silesian manufacturing corridors present white-space demand for cost-efficient digital switching. Extended temperature-range chassis protect console access in harsh factory floor deployments.
KVM Market Competitive Environment
Global majors compete with regional champions across certification capability and manufacturing scale. The vendor base organizes around three tiers: integrated server OEMs with embedded console modules, dedicated switch specialists with semiconductor design capabilities, and regional fabricators serving cost-sensitive industrial retrofits. Dominant competitive moves include strategic partnerships with domestic testing labs for regulatory compliance and portfolio diversification into subscription-based firmware licensing.
Among Taiwan-based fabricators, ATEN INTERNATIONAL Co., Ltd. and GIGA-BYTE Technology Co., Ltd. exemplify the manufacturing-scale archetype with captive production capacity. Vertiv Group Corp. represents the compliance-forward tier through localization partnerships with Indian BIS testing facilities. Dell Inc. anchors the integrated-server segment with motherboard-embedded console silicon standard across hyperscale builds.
| Leading Market Players |
|---|
| Vertiv Group Corp. |
| ATEN INTERNATIONAL Co., Ltd. |
| IEC. |
| PROSUM |
| Rextron International Inc. |
| Dell Inc. |
| GIGA-BYTE Technology Co., Ltd. |
| Shenzhen CKL Technology Co., Ltd. |
| Raritan Americas, Inc. |
| Others |
Value Chain & Pricing Dynamics
Copper futures volatility on the London Metal Exchange cascades through Taiwanese cable assembly operations into three distinct pricing tiers for console infrastructure buyers. German data center operators absorb REACH compliance premiums for halogen-free chassis materials while Indian procurement teams exploit PLI scheme offsets to compress landed costs on IP-based systems.
Pricing Analysis
Warranty bundling separates enterprise procurement tiers, with three-year firmware update subscriptions commanding premium positioning against bare-hardware transactional sales. Pricing stratifies across FIPS 140-2 certified government tiers, CE-marked commercial tiers, and uncertified economy tiers for industrial retrofits. Cost compression in entry-level hardware intensifies because Microsoft Remote Desktop substitution eliminates peripheral-switching demand in small-office environments. SME buyers exhibit highest price sensitivity, while defense contractors accept extended validation timelines for security-assured premiums.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Rotterdam, and Mumbai anchor hub-and-spoke fulfillment patterns for console hardware. Manufacturing concentrates in Taiwan, China, and Vietnam for PCB fabrication and cable assembly operations. Production draws from copper conductor stock, FPGA silicon from Xilinx and Altera supply channels, and rare earth magnet components for electromagnetic shielding. Single-source vulnerability in Taiwanese high-density switch fabrication creates exposure to geopolitical disruption. Distribution runs through server OEM direct channels, specialized AV integrators, and industrial automation distributors serving Eastern European manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwanese foundry capacity constraints for FPGA signal processors prop pricing premiums across enterprise-grade console deployments. Supply bottlenecks in advanced semiconductor packaging limit expansion of sub-millisecond latency product lines.
For Market Incumbents: Deploy firmware subscription licensing to capture recurring revenue streams and offset hardware margin compression from Chinese cost competitors. Deepen backward integration into FPGA semiconductor design to reduce dependence on Xilinx supply allocations. Strengthen BIS certification partnerships in India to defend channel position against localized testing requirements. For New Entrants and Emerging Players: Polish industrial automation retrofit buyers represent underserved demand with EU cohesion fund backing and limited incumbent presence. Eastern European manufacturing facilities modernizing legacy SCADA environments offer lowest competitive density for cost-efficient digital switching solutions. Pursue direct sales relationships with Silesian plant engineering departments bypassing established distribution hierarchies. For Investors and Strategic Acquirers: Distressed-cycle entries favor Taiwanese mid-cap fabricators with captive Kaohsiung production capacity and established East Asian distribution networks. Long-term viability hinges on semiconductor design capabilities becoming non-negotiable for hyperscale procurement qualification. Monitor FPGA allocation announcements from major foundries as inflection indicator for console hardware supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Testing Partnership Formation | BIS certification alliances unlock Indian public-sector procurement channels previously blocked to import streams. |
| FPGA Semiconductor Design Acquisition | In-house signal processor development eliminates latency penalties from third-party silicon sourcing in financial trading environments. |
| Subscription Firmware Licensing Launch | Three-year support contracts capture recurring revenue from healthcare and financial services cybersecurity update mandates. |
| Halogen-Free Material Reformulation | REACH compliance investment preserves German distributor relationships requiring full material disclosure documentation. |
| Edge Computing Micro Data Center Targeting | 5G infrastructure and smart city deployments create distributed console management requirements outside traditional hyperscale concentration. |
Study Parameters
Multi-period observation of hyperscaler capex disclosures, BIS certification registration databases, and EU cohesion fund allocation announcements anchored the trend analysis, supplemented by interviews with data center infrastructure directors, broadcast systems integrators, industrial automation procurement leads, and Taiwanese cable assembly plant managers. Secondary validation drew from FCC equipment authorization filings, ECHA REACH substance restriction updates, PLI scheme beneficiary lists, and server OEM embedded module specifications. Bottom-up port shipment aggregation triangulated against top-down data center buildout tracking across the analysis window.
Input-output matrices modeled product type, signal processing technology, application vertical, and end-user scale segmentation dimensions over the projection horizon. CAGRs derived from installed base replacement cycle analysis and remote management adoption curve fitting. Forecast inputs incorporated EU Green Deal carbon reduction timeline enforcement and 4K broadcast production standard migration patterns.
Revisions become necessary when Taiwanese foundry allocation disruptions, Indian BIS regulatory scope expansions, or software-based remote desktop substitution acceleration materialize outside baseline assumptions. Forecasts reflect documented parameter sets and scenario-weighted probability distributions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Data Center Substation Market