
 North America Containerized Data Center Market | 2026-2036
North America Containerized Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
North America Containerized Data Center Market Analytics
A widening capital-intensity divergence between integrated power specialists and IT hardware vendors is unwinding competitive parity across the North America containerized data center landscape. Schneider Electric SE leverages its end-to-end power and cooling portfolio to anchor large-scale deployments across utility-constrained sites. Vertiv Group sustains engineering density in thermal management and controls, competing aggressively for hyperscale edge contracts. Dell Technologies differentiates through server-storage integration within factory-built modules, reducing field assembly cycles.
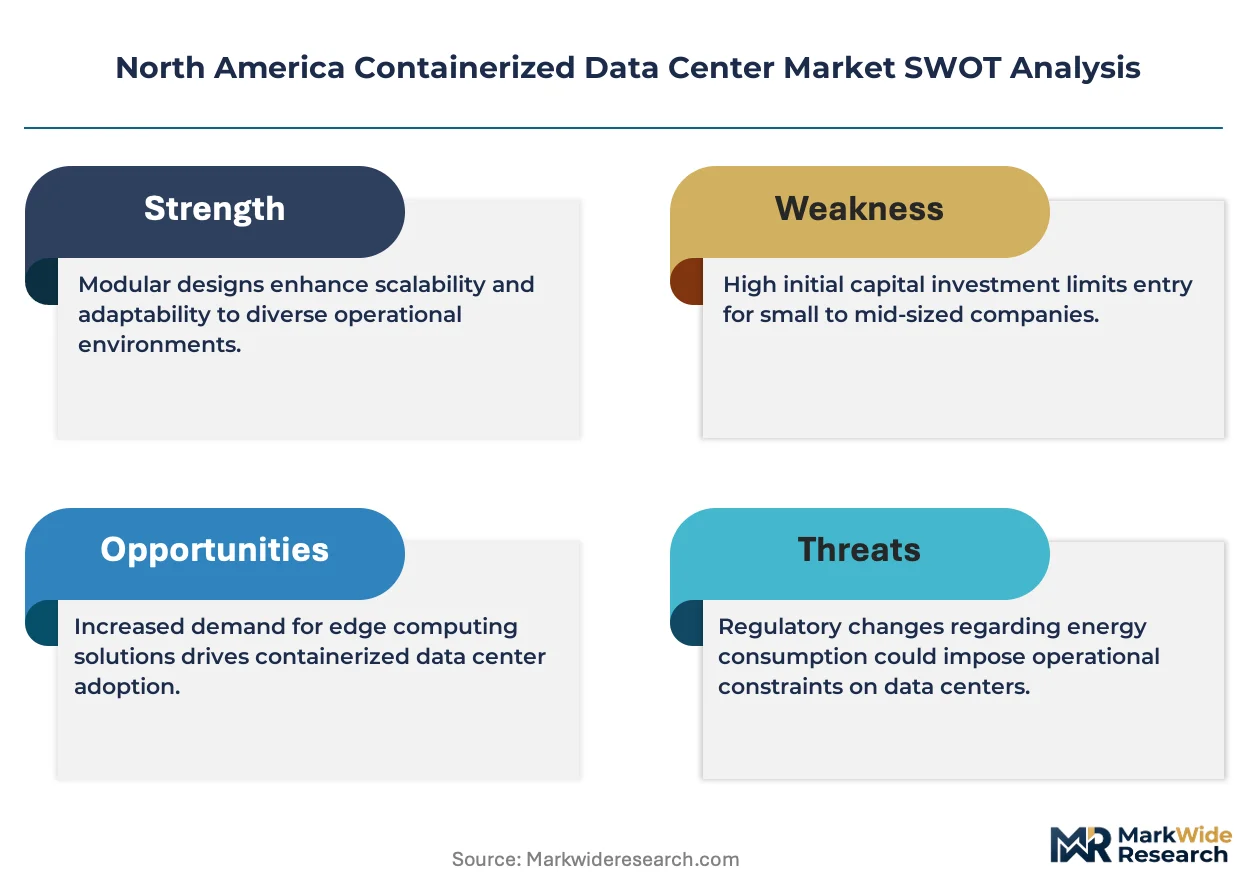
Containerized data centers enclose prefabricated IT, power, and cooling systems within standardized shipping-container footprints, typically delivering 100 kW to 1 MW per unit with PUE targets below 1.3 for efficient operations. Modular data centers and micro data centers lead current revenue contribution, reflecting enterprise demand for rapid-scaling infrastructure without traditional construction timelines. Edge computing deployments represent the fastest-growing deployment model, as telecommunications carriers and content distributors position compute closer to population centers. The 500 kW to 1 MW power rating segment captures concentrated margin pools, balancing density economics against utility interconnection complexity.
The U.S. Department of Energy and the Environmental Protection Agency shape equipment efficiency mandates through ENERGY STAR certification and emerging carbon intensity benchmarks for federal procurement. State regulators in California, Texas, and Virginia enforce distinct electrical code variations and renewable energy thresholds that complicate standardized product design. Enterprise buyers and infrastructure operators must monitor evolving grid interconnection rules and carbon disclosure obligations across multiple state jurisdictions.
Market Dynamics
Hyperscale cloud operators and telecommunications carriers are compressing deployment timelines from 18-24 months to under 90 days, forcing infrastructure vendors to reconfigure factory workflows around containerized delivery rather than field-integrated construction.
Growth Catalysts
- State Renewable Portfolio Standards:California's SB 100 mandates and Texas ERCOT grid incentives accelerate clean-powered modular deployments across utility-constrained corridors.
- 5G Network Densification:Telecommunications carriers require sub-10ms latency infrastructure, positioning containerized edge units within 50 miles of metropolitan centers.
- Liquid Cooling Adoption:Direct-to-chip and immersion thermal systems enable 50kW+ rack densities in standard 40-foot footprints, unlocking AI training workloads.
Market Restraints
- Transformer and Switchgear Lead Times:North American electrical equipment manufacturers currently quote 52-78 week delivery cycles for medium-voltage power distribution components.
- Interconnection Queue Backlogs:ERCOT, CAISO, and PJM interconnection studies now extend 36-48 months for new 1-10 MW load additions in prime data center counties.
- Skilled Electrical Trade Scarcity:IBEW-certified medium-voltage technicians command 40% wage premiums in Northern Virginia and Dallas-Fort Worth markets.
Strategic Opportunities
- Mexico Nearshoring Expansion:Querétaro and Monterrey industrial corridors offer 30-40% land cost arbitrage with NAFTA-compliant supply chain integration for US-bound deployments.
- Defense and Federal Edge:Department of Defense CONUS basing requirements and DISA tactical edge programs specify MIL-STD-810G hardened container specifications.
- Carbon Intensity Labeling:EPA ENERGY STAR and emerging SEC climate disclosure rules create procurement preference for PUE-certified sub-1.2 modular units.
Industry Challenges
- Multi-Jurisdictional Code Compliance:Containerized units must simultaneously satisfy NFPA 70 National Electrical Code, ICC modular building standards, and local fire marshal amendments across Texas, Virginia, and California.
- Legacy DCIM Integration:Enterprise facilities management platforms from established vendors lack native API connectivity to containerized power and cooling telemetry streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Containerized Data Center Market |
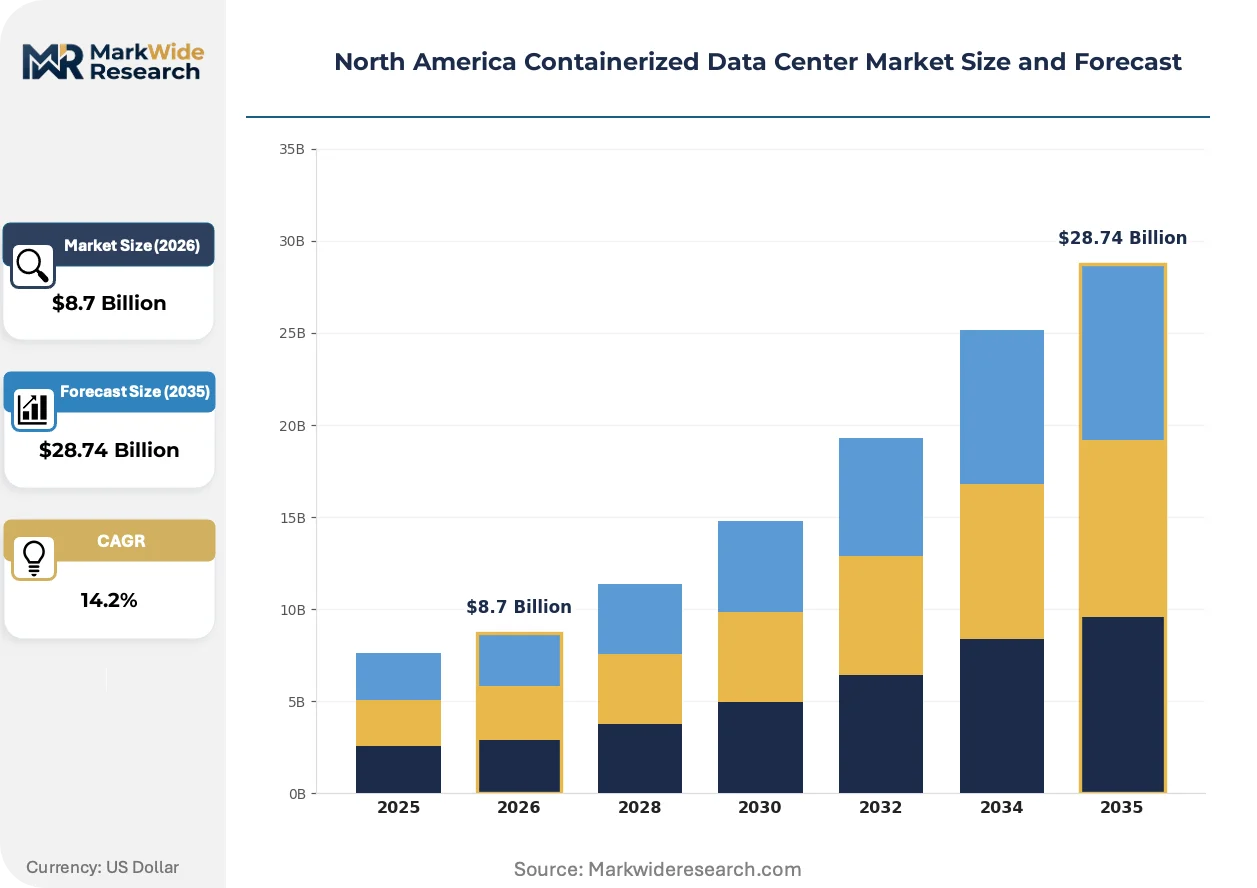
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Mobile Data Centers, Micro Data Centers, Hybrid Data Centers Deployment Model: On-Premises, Off-Premises, Edge Computing, Remote Locations End User: Telecommunications, IT Service Providers, Enterprises, Government Power Rating: Up to 100 kW, 100 to 500 kW, 500 kW to 1 MW, Above 1 MW |
| Companies Covered | Schneider Electric SE, Vertiv Group, IBM Corporation, Hewlett Packard Enterprise Company, Cisco Systems Inc., Dell Technologies, Huawei Technologies Co. Ltd., Eaton Corporation, Rittal GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Containerized Data Center Market Evolving Landscape
Modular infrastructure design is converging with semiconductor packaging roadmaps, compressing the traditional boundary between IT equipment and facility engineering into unified thermal and power envelopes.
Immersion cooling dielectric fluids are miniaturizing thermal management footprints from raised-floor plenums to rack-level tanks. Hyperscale operators now specify single-phase and two-phase immersion for 100kW+ GPU clusters. This compression is miniaturizing the mechanical plant into shipping-container dimensions, eliminating separate chiller yards and enabling parking-lot deployments.
EPA carbon intensity benchmarking and FERC Order 2222 distributed energy resource aggregation rules are reshaping power procurement for modular facilities. Industrial consequence includes mandatory hourly matching of renewable generation to IT load in California and emerging requirements in PJM territories. Colocation providers and enterprise self-builders in Northern Virginia now pre-specify battery energy storage and solar-ready electrical busses to maintain interconnection eligibility.
Telecommunications carriers are unbundling infrastructure ownership from network operations, shifting from capital purchase to managed service agreements with 5-7 year terms. This displacement concentrates buyer power among three national wireless operators and two cable MSOs, compressing vendor margins and elevating performance-based SLA penalties. The procurement transformation is most visible in Texas and Florida markets where hurricane resilience requirements add 15-20% premium pricing for hardened container specifications.
North America Containerized Data Center Market Segmentation
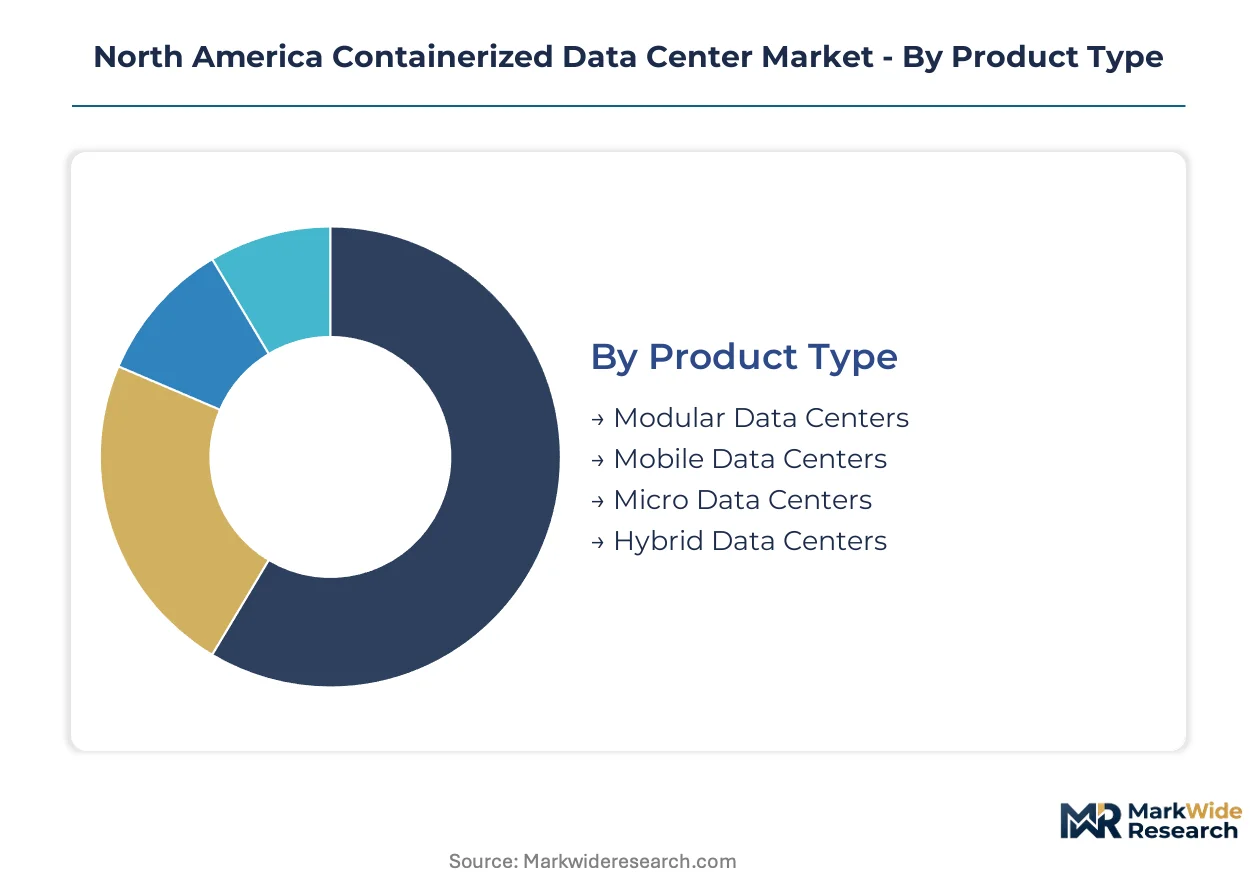
Containerized data center segmentation reveals distinct margin architectures across product formats, deployment contexts, and power envelopes. Procurement patterns diverge sharply between hyperscale cloud operators seeking density-optimized modules and federal buyers prioritizing hardened specifications. Understanding these segment boundaries enables vendors to align factory configurations with buyer willingness-to-pay.
Product Type:
Margin pools concentrate in factory-integrated formats that compress field assembly cycles and reduce skilled labor dependencies.
- Modular Data Centers:These prefabricated units integrate IT, power, and cooling systems within standardized 20-foot or 40-foot shipping containers, typically delivering 100 kW to 1 MW per unit. Demand concentrates across Northern Virginia and Texas data center corridors where land constraints and ERCOT grid interconnection backlogs favor rapid-deployment alternatives to traditional construction.
- Micro Data Centers:Compact sub-100 kW units designed for edge computing deployments within 50 miles of metropolitan centers. Telecommunications carriers in California and Florida specify these for 5G network densification, with hurricane resilience requirements adding 15-20% premium pricing for hardened specifications.
- Mobile Data Centers:Trailer-mounted or skid-based transportable units serving temporary capacity needs and disaster recovery scenarios.
- Hybrid Data Centers:Configurations combining containerized modules with traditional stick-built infrastructure for phased expansion.
Modular Data Centers hold installed capacity. Micro Data Centers is rotating up the share rankings.
Deployment Model:
Application context determines procurement authority structures and contract term flexibility across buyer segments.
- Edge Computing:Distributed compute nodes positioned for sub-10ms latency requirements. Telecommunications carriers in Texas and California unbundle infrastructure ownership from network operations, shifting toward managed service agreements with 5-7 year terms that concentrate buyer power among national wireless operators.
- On-Premises:Enterprise-controlled deployments on owned real estate. Financial services and healthcare organizations in Northern Virginia and Dallas-Fort Worth favor this model to maintain direct compliance with HIPAA and SEC climate disclosure obligations.
- Off-Premises:Colocation and hosting arrangements where third-party operators manage facility infrastructure.
- Remote Locations:Deployments in areas with limited grid connectivity, including mining operations and military forward operating bases.
On-Premises retains the largest deployment footprint. Edge Computing is expanding most quickly as carriers densify 5G infrastructure.
End User:
Customer type shapes specification complexity and sales cycle duration through distinct procurement protocols.
- Telecommunications:National wireless operators and cable MSOs drive volume demand for standardized edge units. The segment's shift from capital purchase to managed services compresses vendor margins while elevating performance-based SLA penalties.
- Government:Department of Defense CONUS basing requirements and DISA tactical edge programs specify MIL-STD-810G hardened container specifications with extended qualification timelines.
- IT Service Providers:Cloud and managed service providers procuring modular capacity for client-facing infrastructure.
- Enterprises:Corporate self-builders across manufacturing, healthcare, and financial services seeking rapid-scaling alternatives to traditional construction.
Telecommunications holds the dominant procurement volume. Government is climbing the fastest as defense edge programs accelerate.
Power Rating:
Density economics and utility interconnection complexity create nonlinear margin structures across power tiers.
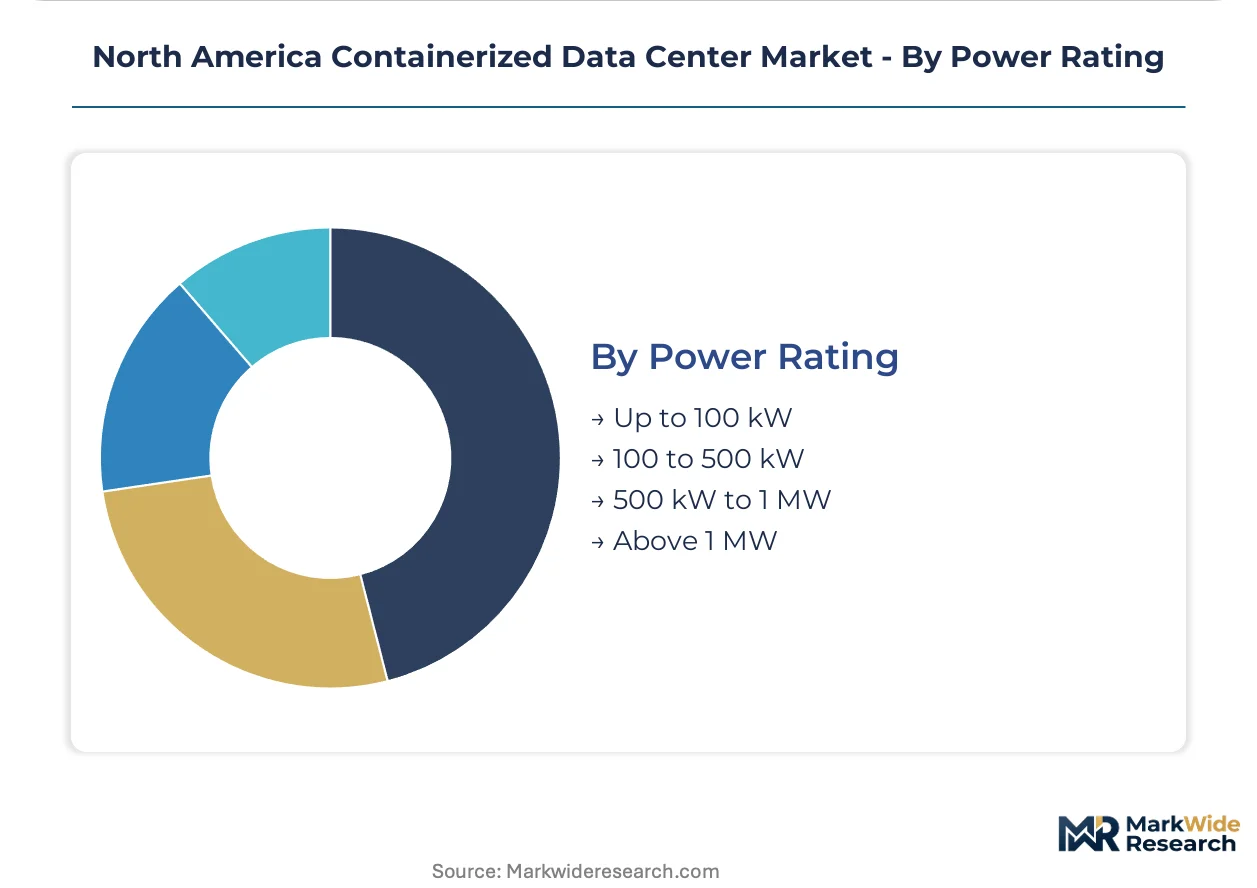
- 500 kW to 1 MW:The optimal balance between density economics and interconnection feasibility. California's SB 100 mandates and ERCOT grid incentives accelerate procurement in this segment, though PJM and CAISO interconnection studies now extend 36-48 months for new load additions.
- Above 1 MW:High-density units requiring medium-voltage infrastructure and extended transformer lead times. Northern Virginia deployments face 52-78 week delivery cycles for electrical equipment, constraining near-term growth.
- 100 to 500 kW:Mid-range units serving enterprise edge and regional colocation needs.
- Up to 100 kW:Entry-level micro data centers for distributed retail and branch office deployments.
500 kW to 1 MW captures the densest margin pools. Above 1 MW is gaining share fastest as AI training workloads drive rack density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Northern Virginia corridors where land scarcity and ERCOT interconnection backlogs compress deployment timelines, while Canadian markets command premiums for hydroelectric-powered modular specifications. Mexico's nearshoring corridors exploit 30-40% land cost arbitrage with NAFTA-compliant supply chain integration.
United States
Hyperscale cloud operators and telecommunications carriers drive procurement across Texas, Northern Virginia, and California data center corridors. The U.S. Department of Energy efficiency mandates and EPA ENERGY STAR certification reshape equipment specifications for federal procurement. Northern Virginia deployments face 52-78 week transformer lead times and 36-48 month PJM interconnection queue backlogs, forcing buyers toward pre-specified battery energy storage configurations.
Canada
Enterprise self-builders and colocation providers target Ontario and Quebec for hydroelectric-powered modular deployments with sub-1.2 PUE targets. Provincial clean energy standards and federal carbon disclosure obligations for publicly traded firms accelerate procurement of renewable-matched containerized infrastructure. Toronto and Montreal industrial corridors concentrate demand for rapid-deployment alternatives to traditional construction timelines.
Mexico
Querétaro and Monterrey industrial corridors attract US-bound containerized data center manufacturing with NAFTA-compliant supply chain integration and 30-40% land cost arbitrage. CFE grid interconnection rules and state-level industrial incentives complicate standardized product design for cross-border deployments. Manufacturing clusters in these corridors supply prefabricated modules to Texas and California utility-constrained sites.
North America Containerized Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America containerized data center landscape. The market structure consolidates around integrated power specialists, IT hardware vendors, and thermal management engineers competing for hyperscale edge contracts. Three strategic archetypes dominate: end-to-end infrastructure integrators, factory-built module specialists, and thermal management engineers. Competitive moves concentrate on strategic partnerships for utility-constrained site deployment and portfolio diversification into liquid cooling systems for AI training workloads.
Among integrated power and cooling specialists, Schneider Electric SE anchors large-scale deployments across utility-constrained sites with end-to-end infrastructure portfolios. Vertiv Group occupies a position within the thermal management engineering tier, competing aggressively for hyperscale edge contracts. Dell Technologies exemplifies the factory-built module specialist archetype, reducing field assembly cycles through server-storage integration within standardized shipping-container footprints.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group |
| IBM Corporation |
| Hewlett Packard Enterprise Company |
| Cisco Systems Inc. |
| Dell Technologies |
| Huawei Technologies Co. Ltd. |
| Eaton Corporation |
| Rittal GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Liquid cooling dielectric fluids replacing traditional raised-floor HVAC systems simultaneously concentrate supply geography in Taiwan and South Korea while compressing pricing economics for thermal management subsystems. This substitution dynamic redirects procurement power toward semiconductor packaging specialists and away from conventional mechanical plant vendors.
Pricing Analysis
Configured-to-order premiums for MIL-STD-810G hardened specifications run 15-20% above standard modular units in hurricane-exposed Texas and Florida markets. Three-tier pricing structure across hardened, efficiency-certified, and baseline configurations reflects California SB 100 compliance costs and ERCOT grid interconnection complexity. Price differentiation hinges on PUE certification tier and factory integration depth. Margins are tightening due to telecommunications carriers' shift toward 5-7 year managed service agreements that concentrate buyer power among three national wireless operators. Federal buyers show lowest price sensitivity given extended qualification timelines for DISA tactical edge programs.
Supply Chain Analysis
Mexico and China anchor prefabricated module fabrication with NAFTA-compliant and cost-optimized supply chain integration respectively. Taiwan and South Korea feed critical semiconductor content for power conversion and thermal management subsystems. Raw material dependencies center on electrical steel for transformers, lithium-ion cells for battery energy storage, and specialized dielectric fluids for immersion cooling. Single-source vulnerability concentrates in medium-voltage switchgear where North American manufacturers face extended order backlogs. Distribution runs through direct OEM channels for hyperscale contracts and systems integrators for federal and enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized data center procurement is shifting toward platform-based interoperability standards that mirror hyperscaler cloud ecosystems, compressing vendor differentiation around API-native telemetry integration rather than hardware specifications alone.
For Market Incumbents: Consolidate factory automation investments in Querétaro and Monterrey corridors to capture 30-40% land cost arbitrage against Texas manufacturing. Deepen backward integration into battery energy storage systems to maintain interconnection eligibility across PJM and CAISO queue backlogs. Lock in IBEW-certified electrical trade partnerships in Northern Virginia and Dallas-Fort Worth to defend against 40% wage premiums eroding field assembly margins. For New Entrants and Emerging Players: Managed service orchestration layers represent the most penetrable white-space where incumbents under-serve telecommunications carriers unbundling infrastructure ownership from network operations. Target California and Texas edge computing corridors with API-first DCIM platforms that bridge legacy facilities management systems to containerized power and cooling telemetry. Lead with outcome-based SLAs that absorb performance risk in exchange for 5-7 year contract terms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors thermal management engineering specialists with liquid cooling IP and established hyperscale relationships. Long-term viability across the projection horizon rests on positioning against AI training workload density requirements. Target acquisition archetypes include immersion cooling subsystem vendors and factory-automated module integrators with NAFTA-compliant Mexico manufacturing footprints. The signal to watch is FERC Order 2222 implementation pace shaping distributed energy resource aggregation economics for modular facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Licensing | Enables 50kW+ rack densities in standard 40-foot footprints for AI training workloads. |
| NAFTA-Compliant Manufacturing Expansion | Captures land cost arbitrage in Querétaro and Monterrey corridors serving US-bound deployments. |
| Battery Energy Storage Integration | Maintains CAISO and PJM interconnection eligibility amid 36-48 month queue backlogs. |
| API-Native DCIM Platform Development | Bridges legacy enterprise facilities management systems to containerized telemetry streams. |
| Federal Certification Fast-Track Program | Accelerates MIL-STD-810G qualification timelines for DISA tactical edge procurement. |
Research Methodology
Cross-validation between primary interviews with data center infrastructure executives and secondary validation through SEC hyperscaler capex disclosures anchors the qualitative findings. Stakeholder roles engaged include utility interconnection planners, telecommunications network engineering directors, federal procurement officers at DISA, colocation facility operators, and IBEW electrical trade representatives. Secondary sources span EIA grid interconnection databases, FERC Order 2222 docket filings, state renewable portfolio standard filings in California and Texas, and EPA ENERGY STAR certification records. Bottom-up unit economics triangulate against top-down corridor-level capacity buildout tracking.
Sensitivity analysis around transformer lead time assumptions and interconnection queue duration scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, deployment context, power rating tier, and end-user procurement authority structure. CAGRs derive from capacity-weighted average deployment timelines and factory utilization rates reported across vendor disclosures. Industry-specific forecast inputs center on ERCOT grid incentive program participation rates and California SB 100 hourly renewable matching compliance trajectories.
Forecasts assume regulatory continuity in FERC interconnection rules and state-level clean energy standards; material policy shifts would require re-modeling. Specific risk factors that could revise projections include abrupt changes to CFE grid interconnection rules affecting Mexico nearshoring economics and accelerated EPA carbon intensity benchmarking timelines. Recalibration cycles align with material shifts in utility queue processing rates and hyperscaler edge deployment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Underwater Data Center Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Indonesia Data Center Market