
 Cloud Network Infrastructure Market | 2026-2036
Cloud Network Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Network Infrastructure Market Analysis
Market Context
Enterprise procurement of cloud network infrastructure is shifting from single-vendor contracts toward multi-cloud sourcing arrangements. Amazon Web Services dominates hyperscale capacity deployment through its global fiber backbone and edge PoP expansion. Microsoft Azure leverages enterprise channel relationships to anchor hybrid cloud connectivity in regulated industries. Google Cloud specializes in AI-optimized networking fabrics that interconnect its tensor processing clusters with customer workloads.
Technical Definition and Segment Structure
Cloud network infrastructure encompasses the physical and virtualized systems—routers, switches, optical transport, SD-WAN controllers, and NFV orchestrators—that enable scalable, on-demand connectivity between distributed compute resources and end users. These systems operate at latencies below 10 milliseconds for edge nodes and support throughput exceeding 400 Gbps per optical wavelength. Infrastructure as a Service and Network as a Service segments command the largest revenue pools, while SD-WAN and cloud orchestration technologies are expanding fastest as enterprises disaggregate hardware from control planes. Hybrid Cloud deployments generate premium pricing due to complexity in stitching private data center fabrics with public cloud backbones.
Regulatory Framework and Outlook
FCC net neutrality rulings in the United States, EU GDPR data localization mandates, and China's MIIT cybersecurity multi-level protection scheme collectively determine where providers must site physical infrastructure and how traffic may traverse national boundaries. ISO 27001 and IEC 62443 certifications function as de facto market access requirements for providers serving energy and healthcare verticals. Stakeholders must monitor evolving spectrum allocation policies for fixed wireless access as a potential substitute for last-mile fiber in underserved markets.
Market Dynamics
Enterprise migration to distributed cloud architectures is compressing procurement cycles while fragmenting vendor relationships across multi-cloud environments. Financial services institutions now demand sub-10 millisecond latency guarantees that force infrastructure providers to rearchitect physical layer deployments.
Growth Catalysts
- EU AI Act compliance mandates:Data sovereignty requirements under the NIS2 Directive are compelling hyperscale providers to expand sovereign cloud zones across member states. This creates captive demand for EU-sited optical transport and edge PoP infrastructure.
- AI-optimized networking fabrics:Tensor processing cluster interconnects require specialized 400 Gbps+ wavelengths and low-latency east-west traffic patterns. Cloud providers are retrofitting backbone capacity to support GPU-to-GPU communication at scale.
- Frankfurt Rhine-Main concentration:Germany's dominance as Europe's hyperscale hub is pulling submarine cable landings, terrestrial fiber builds, and data center power allocations into the metropolitan region.
Market Restraints
- Optical component supply concentration:Coherent DSPs and high-speed transceivers depend on a limited supplier base concentrated in Taiwan and South Korea. Geopolitical friction threatens delivery timelines for 800 Gbps generation hardware.
- FCC net neutrality uncertainty:Shifting classification of broadband under Title II creates compliance ambiguity for traffic prioritization services. Providers face stranded investment risk in edge caching and quality-of-service features.
- Fixed wireless access substitution:CBRS and millimeter-wave deployments in underserved US markets threaten last-mile fiber economics. Rural enterprise connectivity may bypass wired infrastructure entirely.
Strategic Opportunities
- ISO 27001 certification arbitrage:Energy and healthcare verticals require IEC 62443-compliant infrastructure. Providers achieving both certifications command premium positioning in regulated procurement.
- India's data localization enforcement:RBI and TRAI mandates for financial data storage are forcing hyperscale expansion into Mumbai, Hyderabad, and Chennai. Greenfield data center construction creates optical transport pull-through.
- NFV-SD-WAN convergence:Disaggregated control planes meeting virtualized network functions enable multi-tenant edge platforms. Enterprise managed service providers are white-labeling these stacks for mid-market verticals.
Industry Challenges
- Optical transport engineering scarcity:Coherent optics design and DWDM network planning expertise concentrates among retiring telecom veterans. Training pipelines for 400 Gbps+ system integration lag deployment timelines.
- Hybrid cloud stitching complexity:Private data center MPLS fabrics require protocol translation to public cloud backbone BGP policies. Integration projects overrun schedules due to undocumented legacy configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Network Infrastructure Market |
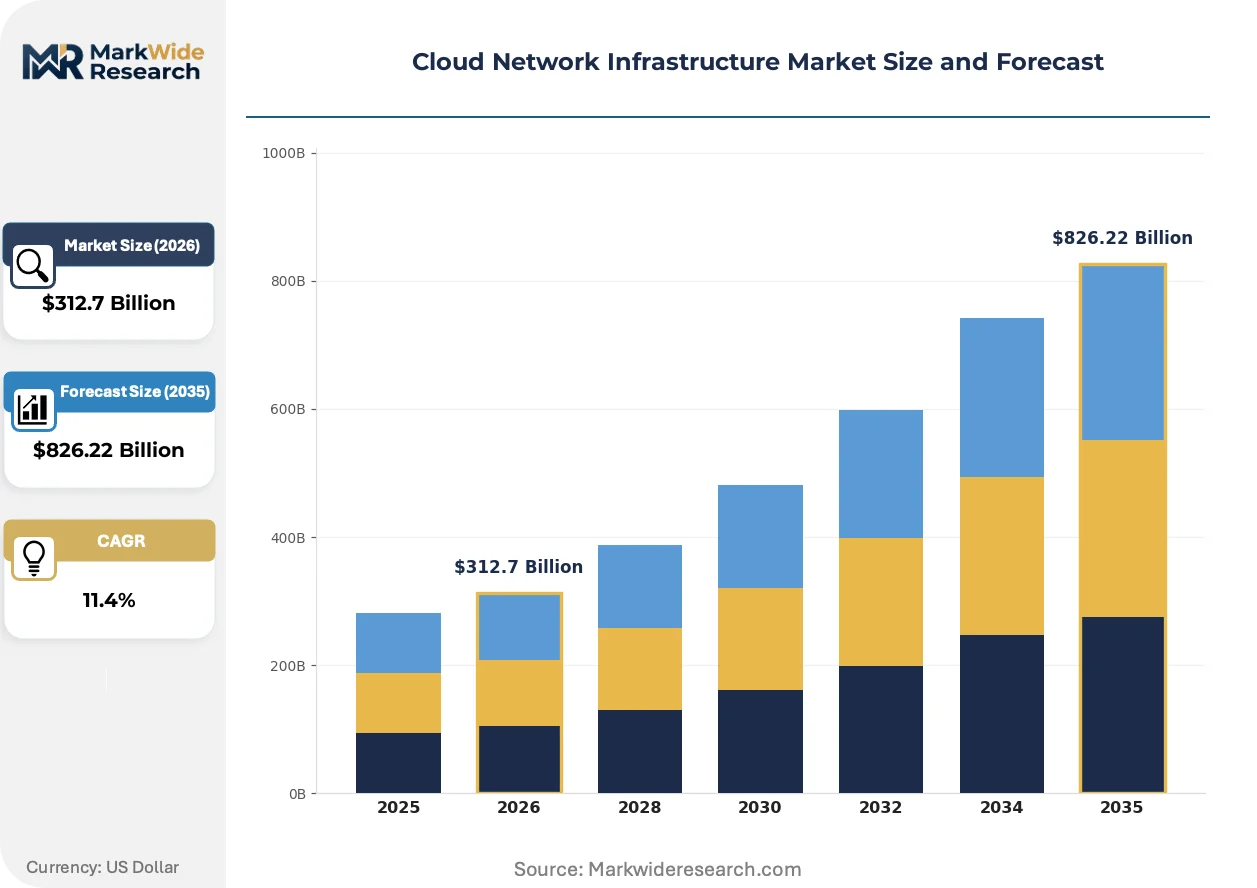
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Network as a Service Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: SD-WAN, NFV, Virtualization, Cloud Orchestration End User: SMEs, Large Enterprises, Telecommunication Providers, Managed Service Providers |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Cloud Infrastructure, Alibaba Cloud, IBM Cloud, Cisco Systems, Juniper Networks, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Network Infrastructure Market Emerging Trajectories
Silicon photonics integration is collapsing cost curves for high-speed optical interconnects while programmable fabrics enable real-time traffic engineering. These shifts are compressing hardware refresh cycles and forcing control plane software unification.
Silicon photonics co-packaging is electrifying transceiver economics by replacing discrete optical components with monolithic CMOS integration. Hyperscale data center operators are adopting 800 Gbps DR8 modules at twice the pace of previous generation ramps. This technology is electrifying vendor consolidation pressure as merchant silicon suppliers capture value from traditional optical component houses.
The EU AI Act's risk-based classification system is mandating algorithmic transparency and data lineage documentation for high-risk AI deployments. Cloud providers must now architect network telemetry and audit logging into substrate layers previously optimized for throughput alone. Financial services workloads in Frankfurt and Amsterdam are migrating to certified sovereign zones that pre-certify compliance with these documentation requirements.
Enterprise sourcing patterns are fragmenting across multi-cloud brokerage platforms that abstract provider-specific APIs. Mid-market manufacturers are abandoning direct AWS, Azure, or Google contracts for FinOps-managed consumption across three-plus environments. This behavior is most visible in Germany's Industrie 4.0 sector, where Mittelstand firms lack internal cloud architecture expertise and outsource orchestration to regional managed service providers.
Cloud Network Infrastructure Market Segmentation
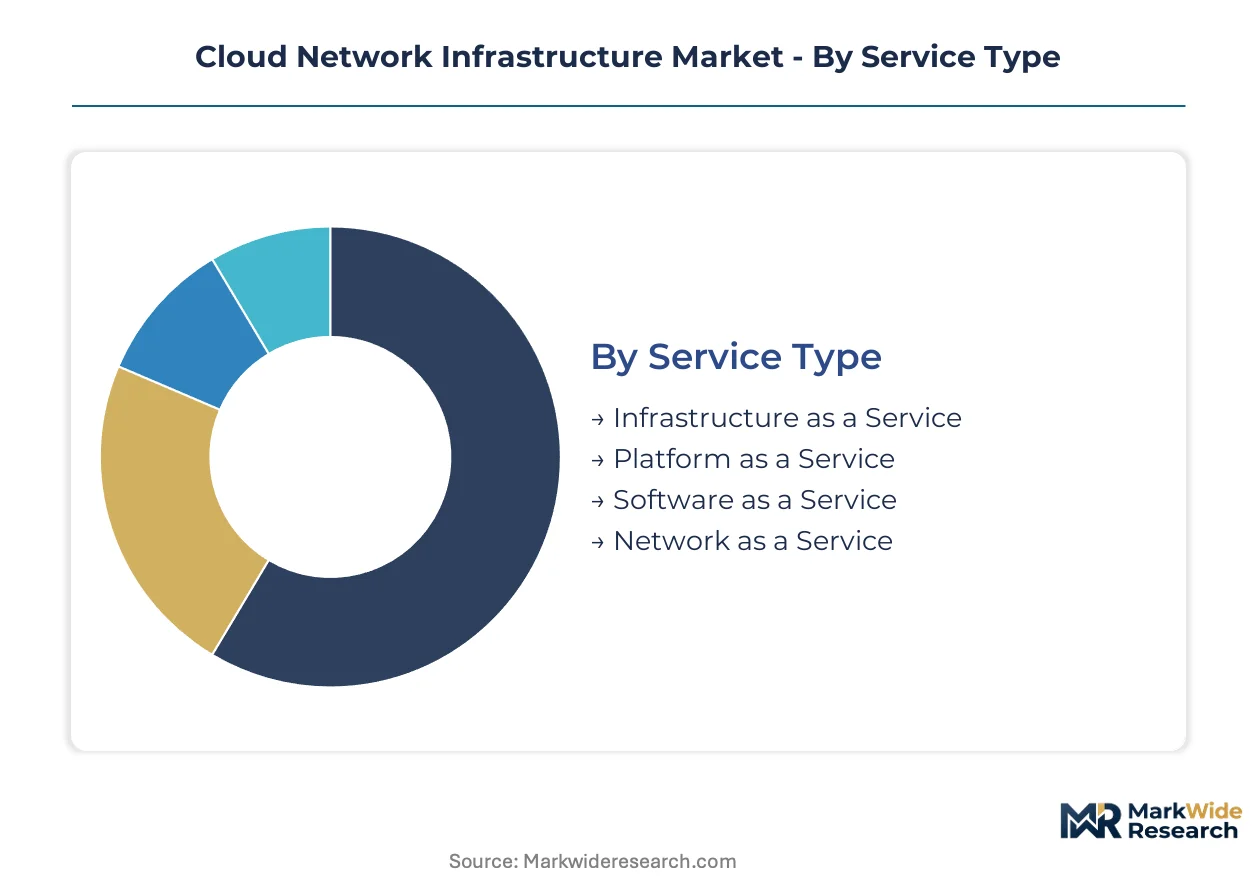
Cloud network infrastructure procurement patterns diverge sharply across service tiers, deployment complexity, and buyer technical sophistication. Understanding these fault lines reveals where margin pools concentrate and which technology transitions reshape vendor relationships.
Service Type:
Buyers differentiate primarily by capital efficiency requirements and internal engineering depth.
- Infrastructure as a Service:Bare-metal compute, storage, and networking resources delivered through programmable APIs. Financial services institutions in Frankfurt dominate consumption, driven by EU AI Act mandates for auditable substrate control.
- Network as a Service:Elastic connectivity provisioned via SD-WAN overlays and virtualized routing functions. Germany's Industrie 4.0 manufacturers are adopting this fastest to bypass capital-intensive MPLS refresh cycles.
- Platform as a Service:Managed middleware and runtime environments abstracting infrastructure complexity. Development teams favor this for containerized workload deployment without cluster management overhead.
- Software as a Service:Fully managed applications delivered through browser interfaces or REST endpoints. Procurement concentrates in mid-market verticals lacking dedicated cloud architecture teams.
Infrastructure as a Service leads volumes today; Network as a Service is expanding most quickly.
Deployment Model:
Regulatory jurisdiction and data gravity determine architectural choices more than cost optimization.
- Hybrid Cloud:Interconnected private data centers and public cloud zones with unified orchestration. Energy and healthcare verticals require this for IEC 62443-compliant workload placement across certified boundaries.
- Multi-Cloud:Deliberate distribution across AWS, Azure, and Google environments to avoid vendor lock-in. German Mittelstand firms are fragmenting sourcing through regional managed service brokers.
- Public Cloud:Shared infrastructure pools with tenant isolation through software-defined networking. Hyperscale providers compete here on optical backbone latency and edge PoP density.
- Private Cloud:Single-tenant infrastructure with dedicated physical layer resources. Sovereign cloud zones in EU member states are expanding this segment under NIS2 Directive data localization pressure.
Hybrid Cloud commands premium pricing; Multi-Cloud is climbing the fastest as procurement fragments.
Technology:
Control plane disaggregation separates hardware refresh cycles from software innovation velocity.
- SD-WAN:Software-defined overlays abstracting transport from application-aware path selection. Mid-market enterprises are displacing legacy MPLS to reduce branch connectivity costs.
- Cloud Orchestration:Kubernetes and proprietary control planes automating resource provisioning. AI training clusters require this for GPU-to-GPU traffic engineering at 400 Gbps scale.
- NFV:Virtualized network functions replacing purpose-built appliances with commodity compute. Telecommunication providers use this to collapse service chaining latency in core networks.
- Virtualization:Hypervisor abstraction enabling multi-tenant compute on shared hardware. This foundational layer underpins all higher-order cloud service delivery.
SD-WAN leads installed volumes today; Cloud Orchestration shows the steepest expansion trajectory.
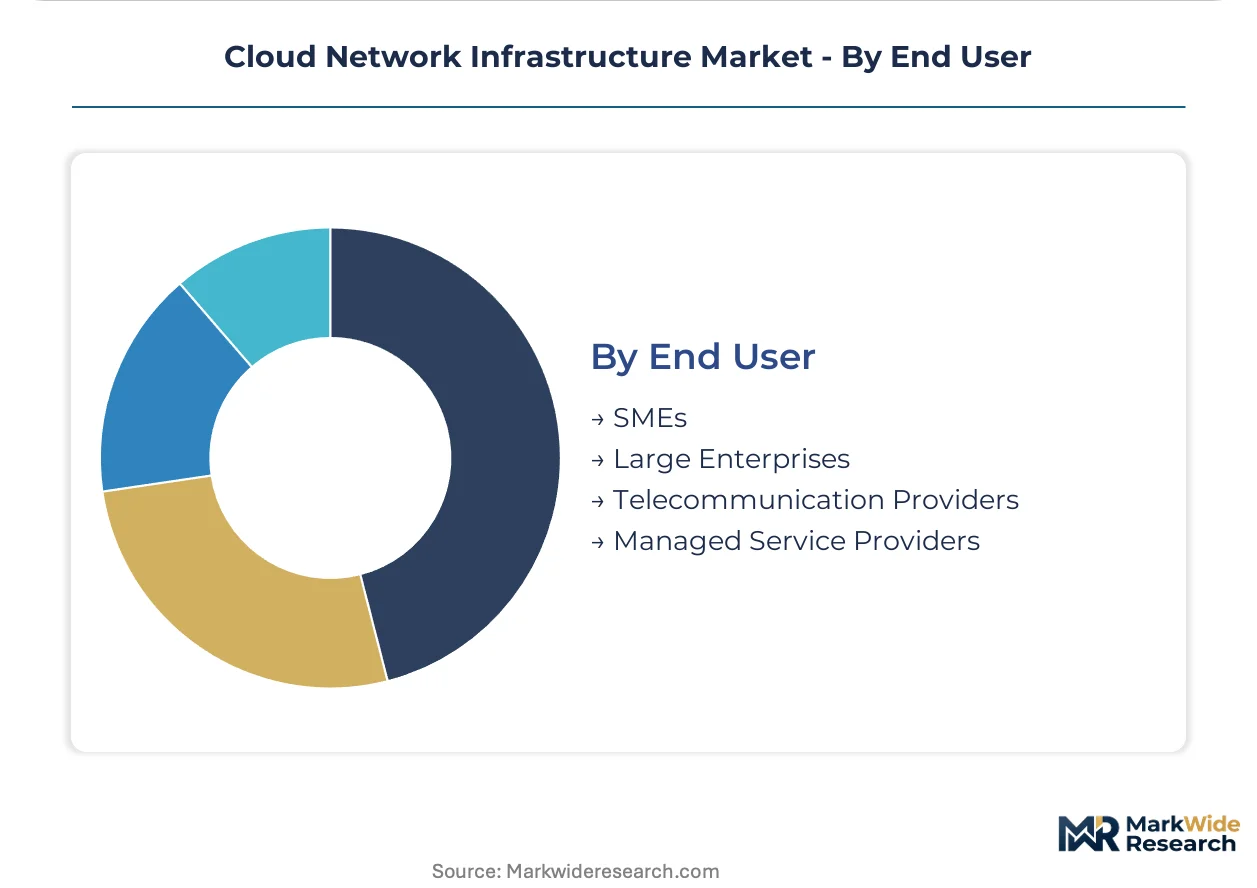
End User:
Technical sophistication and procurement scale create distinct buying behaviors across buyer categories.
- Large Enterprises:Dedicated cloud centers of excellence negotiating direct hyperscale contracts. These buyers demand sub-10 millisecond latency guarantees forcing physical layer rearchitecture.
- Managed Service Providers:Regional intermediaries white-labeling multi-tenant platforms for mid-market verticals. Germany's Rhine-Main corridor hosts the densest concentration of these intermediaries.
- SMEs:Resource-constrained organizations consuming through bundled service packages. FinOps-managed consumption patterns are displacing direct cloud contracts in this segment.
- Telecommunication Providers:Incumbent carriers retrofitting central office infrastructure for edge computing. These buyers drive coherent optical transport demand for 800 Gbps generation upgrades.
Large Enterprises dominate spending today; Managed Service Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Rhine-Main anchors European hyperscale capacity expansion, pulling submarine cable landings and terrestrial fiber builds into Germany's financial capital. Enterprise procurement concentrates in four national markets where regulatory pressure and data gravity reshape infrastructure deployment.
United States
Financial services institutions in New York and Chicago demand sub-10 millisecond latency guarantees for algorithmic trading workloads. FCC net neutrality rulings create compliance ambiguity for traffic prioritization services. Northern Virginia's Data Center Alley hosts the densest concentration of hyperscale facilities, with power allocation constraints now limiting new construction.
Germany
EU AI Act risk classifications force algorithmic transparency into network telemetry layers previously optimized for throughput alone. NIS2 Directive data localization mandates compel sovereign cloud zone expansion across member states. Frankfurt's metropolitan region concentrates submarine cable landings from 15+ transatlantic and intra-European systems.
India
RBI and TRAI mandates for financial data storage force hyperscale expansion into Mumbai, Hyderabad, and Chennai. The country's data localization enforcement creates captive demand for domestic optical transport infrastructure. Maharashtra's Mumbai-Pune corridor anchors greenfield data center construction with associated fiber pull-through.
China
MIIT cybersecurity multi-level protection schemes determine where providers must site physical infrastructure and how traffic traverses national boundaries. Dual carbon goals accelerate renewable-powered data center deployment in western provinces. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate state-affiliated cloud capacity.
United Kingdom
Post-Brexit data adequacy negotiations with the EU reshape cross-border traffic routing requirements for London-based financial institutions. Financial Conduct Authority operational resilience rules mandate geographic redundancy for critical trading infrastructure. Slough and Docklands data center campuses face power grid constraints limiting expansion.
Cloud Network Infrastructure Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sovereign cloud specialization and AI-optimized networking fabrics. Hyperscale providers dominate capacity deployment through global fiber backbones and edge PoP expansion. Three archetypes define competitive positioning: full-stack cloud operators, networking equipment specialists, and regional sovereign cloud builders. Dominant competitive moves include strategic partnerships for data center power allocation and technology licensing for silicon photonics integration.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify divergent strategic vectors. Amazon Web Services anchors market presence through global fiber backbone density and aggressive edge PoP expansion. Microsoft Azure occupies a position leveraging enterprise channel relationships to anchor hybrid cloud connectivity in regulated industries. Google Cloud represents the AI-optimized networking fabric specialization, interconnecting tensor processing clusters with customer workloads at scale.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Oracle Cloud Infrastructure |
| Alibaba Cloud |
| IBM Cloud |
| Cisco Systems |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 27001/IEC 62443-compliant infrastructure and uncertified commodity networking hardware manifests in 40-60% pricing spreads and dual-source supply strategies that segregate qualified component flows from generic procurement channels. This divergence forces hyperscale providers to maintain parallel supplier relationships: one tier for regulated verticals demanding audit trails, another for price-sensitive mid-market consumption.
Pricing Analysis
Input-cost pass-through from coherent DSP and high-speed transceiver shortages in Taiwan and South Korea is compressing margins on 800 Gbps generation hardware. Three-tier pricing structure across premium certified, standard enterprise, and economy connectivity tiers reflects ISO 27001 compliance premiums and latency guarantee enforceability. Pricing pressure stems from silicon photonics integration collapsing legacy optical component economics. Managed service providers exhibit highest price sensitivity, while financial services institutions in Frankfurt absorb premiums for sovereign zone guarantees.
Supply Chain Analysis
Certification gating through ISO 27001 and IEC 62443 audits restricts qualified supplier pools to established optical transport vendors with multi-year compliance track records. Manufacturing concentrates in Taiwan, South Korea, and China for coherent DSPs, with Germany and the United States hosting final system integration. Raw material dependencies include indium phosphide substrates, silicon photonics wafers, and rare-earth-doped fiber amplifiers. Single-source vulnerability around 400 Gbps+ transceiver supply threatens deployment timelines. Distribution runs through hyperscale direct procurement and telecommunications carrier channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-based classification system compounds infrastructure demand through mandated algorithmic transparency and data lineage documentation, creating captive procurement for certified sovereign cloud zones.
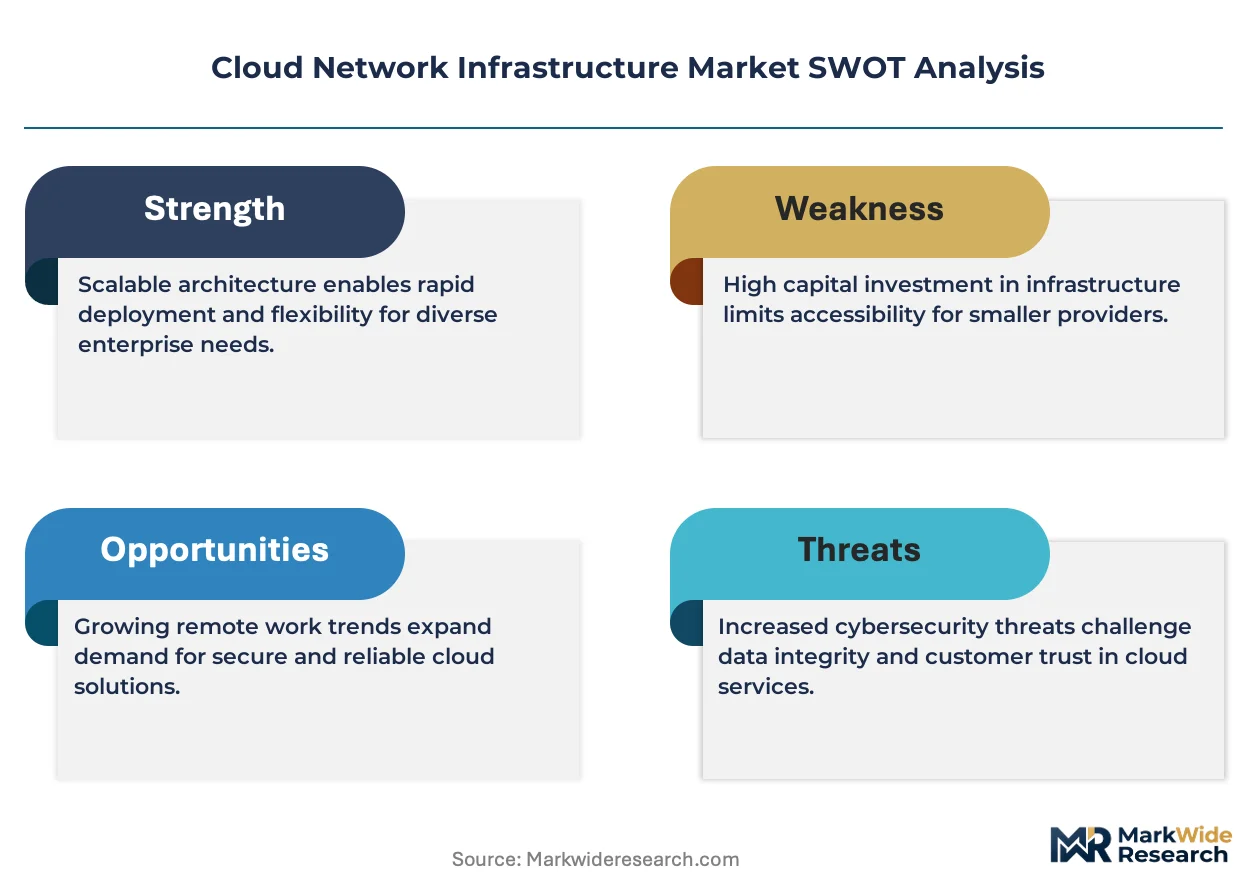
For Market Incumbents: Lock in optical transport engineering talent through acquisition of retiring telecom veteran expertise and structured knowledge transfer programs. Defend position against silicon photonics merchant silicon suppliers by deepening captive wafer supply from TSMC and Samsung Foundry. Prioritize IEC 62443 certification maintenance for energy and healthcare vertical retention. For New Entrants and Emerging Players: Mid-market manufacturers lacking internal cloud architecture expertise represent the most penetrable buyer archetype. White-label NFV-SD-WAN convergence platforms through Germany's Rhine-Main managed service provider ecosystem. Target FinOps-managed consumption brokerage as the go-to-market angle, displacing direct hyperscale contracts with abstraction layer value. For Investors and Strategic Acquirers: Consolidation pressure builds where optical component supply concentration intersects with sovereign cloud zone buildout requirements. Five-to-ten year viability favors vertically integrated players controlling silicon photonics design through system integration. Target acquisition archetype: regional sovereign cloud builders with NIS2 Directive pre-certification. The signal to watch is 800 Gbps transceiver delivery timeline extensions from Taiwanese suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Zone Expansion | NIS2 Directive compliance in Frankfurt and Amsterdam captures EU AI Act-mandated financial services workloads. |
| Silicon Photonics Integration | Co-packaged 800 Gbps DR8 modules from merchant suppliers displace discrete optical component vendors. |
| NFV-SD-WAN Convergence | Disaggregated control planes enable multi-tenant edge platforms for Germany's Industrie 4.0 Mittelstand firms. |
| Optical Transport Engineering Acquisition | Retiring telecom veteran expertise addresses 400 Gbps+ system integration pipeline gaps. |
| Hybrid Cloud Stitching Services | Protocol translation between private MPLS fabrics and public cloud BGP policies resolves integration project overruns. |
Methodological Framework
Multiple input streams — hyperscaler capex disclosures, telecommunications carrier procurement records, and optical component supplier delivery data — were reconciled across primary interviews with cloud infrastructure architects, data center procurement directors, and network engineering leads. Secondary validation drew from SEC 10-K filings, TRAI spectrum allocation reports, and EU regulatory impact assessments. Bottom-up triangulation across deployment model segmentation and top-down cross-reference against aggregate infrastructure investment flows anchored volume estimates.
Historical hyperscaler fiber backbone expansion patterns were cross-referenced against panel input from Frankfurt-based managed service providers and Mumbai data center developers. Segmentation dimensions modeled include service type, deployment complexity tier, technology generation, and regulatory jurisdiction cluster. CAGRs were derived from slope analysis of capital commitment trajectories and capacity absorption rates. AI training cluster interconnect demand and NIS2 Directive compliance timelines served as industry-specific forecast inputs across the projection horizon.
Inputs from hyperscaler facility planning teams and submarine cable consortium filings were available through the study window; gaps in proprietary optical transport equipment cost structures introduce uncertainty bands around 800 Gbps generation penetration assumptions. Forecasts reflect documented deployment schedules and regulatory milestone enforcement patterns. Supply chain disruption from Taiwan Strait geopolitical friction or FCC net neutrality reclassification could materially revise trajectory. A model refresh is warranted upon material change in EU AI Act certification timeline enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Data Center in Japan Market