
 France Data Center Construction Market | 2026-2036
France Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Construction Market Insights
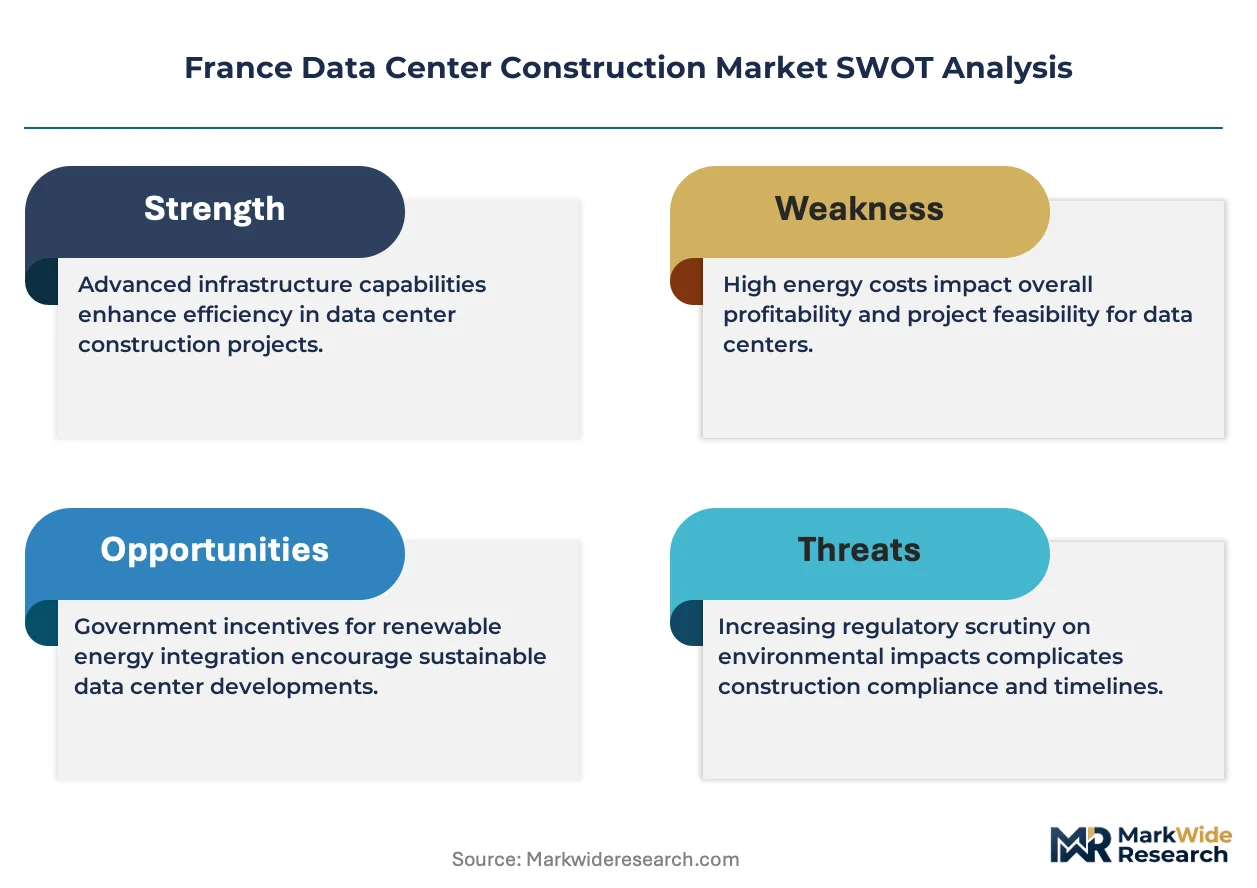
ISO 50001 energy management certification is unwinding the competitive landscape for contractors bidding on hyperscale projects. Digital Realty leverages its European engineering playbook to sustain repeatability across its Paris campus developments. DATA4 Group anchors its positioning through in-house design-build capabilities that compress delivery timelines for cloud tenants. Equinix competes on interconnection density rather than pure megawatt scale, differentiating its offering for financial services clients requiring low-latency cross-connects.
France data center construction encompasses the civil, mechanical, electrical, and structural engineering required to create facilities housing IT infrastructure, with specifications typically demanding N+1 redundancy in power distribution and PUE targets below 1.3 for new hyperscale builds. Hyperscale data centers dominate capital deployment as cloud service providers absorb the majority of new supply coming online near Paris and Marseille. Edge data centers represent the fastest-growing construction type as latency-sensitive applications require distributed presence beyond the Ile-de-France core, though these projects carry higher per-megawatt civil costs due to smaller scale and remote site logistics. Modular data centers are gaining traction for rapid deployment scenarios where prefabricated power and cooling modules slash on-site construction duration.
France's RE2020 building code and the EU Energy Efficiency Directive shape design standards, mandating renewable energy integration and thermal performance disclosures that filter which engineering firms qualify for public-sector and large private tenders. ANSM and CNIL oversight adds data sovereignty and cybersecurity compliance layers that influence physical security system specifications and site selection criteria. Stakeholders must weigh power grid interconnection queues against sustainability commitments when sequencing project pipelines, as EDF's nuclear baseload capacity offers carbon advantages that regulatory frameworks increasingly monetize through green financing instruments.
Market Dynamics
France's RE2020 building code and the EU Energy Efficiency Directive are compressing project timelines as contractors must integrate renewable energy systems and thermal performance disclosures into hyperscale builds before breaking ground.
Growth Catalysts
- Hyperscale Cloud Expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are absorbing the majority of new supply coming online near Paris and Marseille, driving sustained capital deployment into purpose-built facilities.
- RE2020 Energy Mandates:France's building code requires renewable energy integration and PUE targets below 1.3 for new hyperscale construction, filtering qualified engineering firms into premium tender pools.
- Edge Computing Latency Requirements:Distributed presence beyond the Ile-de-France core is accelerating construction of smaller-footprint facilities for latency-sensitive applications in autonomous systems and industrial IoT.
Market Restraints
- Land Scarcity in Ile-de-France:Greenfield development faces severe constraints as available parcels near adequate grid interconnection are exhausted, pushing projects to secondary corridors with inferior fiber latency profiles.
- Copper and Electrical Steel Volatility:Raw material input costs for busbar systems and transformer cores fluctuate with commodity markets, compressing fixed-price contract margins for electrical contractors.
- Nuclear Baseload Dependency:EDF's reactor maintenance schedules and interconnection queue backlogs create sequencing uncertainty for projects banking on carbon-free power claims for green financing eligibility.
Strategic Opportunities
- Modular Prefabrication:Factory-built power and cooling modules slash on-site construction duration, enabling rapid deployment scenarios for cloud tenants with compressed move-in deadlines.
- Marseille Submarine Cable Hub:The Mediterranean landing point for transcontinental fiber routes offers untapped development potential for latency-arbitrage facilities serving African and Middle Eastern markets.
- Green Bond Financing Instruments:Regulatory frameworks increasingly monetize nuclear carbon advantages through sustainability-linked debt structures that reward sub-1.2 PUE performance with rate reductions.
Industry Challenges
- ISO 50001 Certification Bottlenecks:Energy management system auditors face capacity constraints, delaying contractor qualification for public-sector and large private tenders requiring documented continuous improvement protocols.
- Grid Interconnection Synchronization:Sequencing project pipelines requires precise coordination with RTE's transmission upgrade schedules, where misalignment strands completed facilities without operational power.
Report Scope
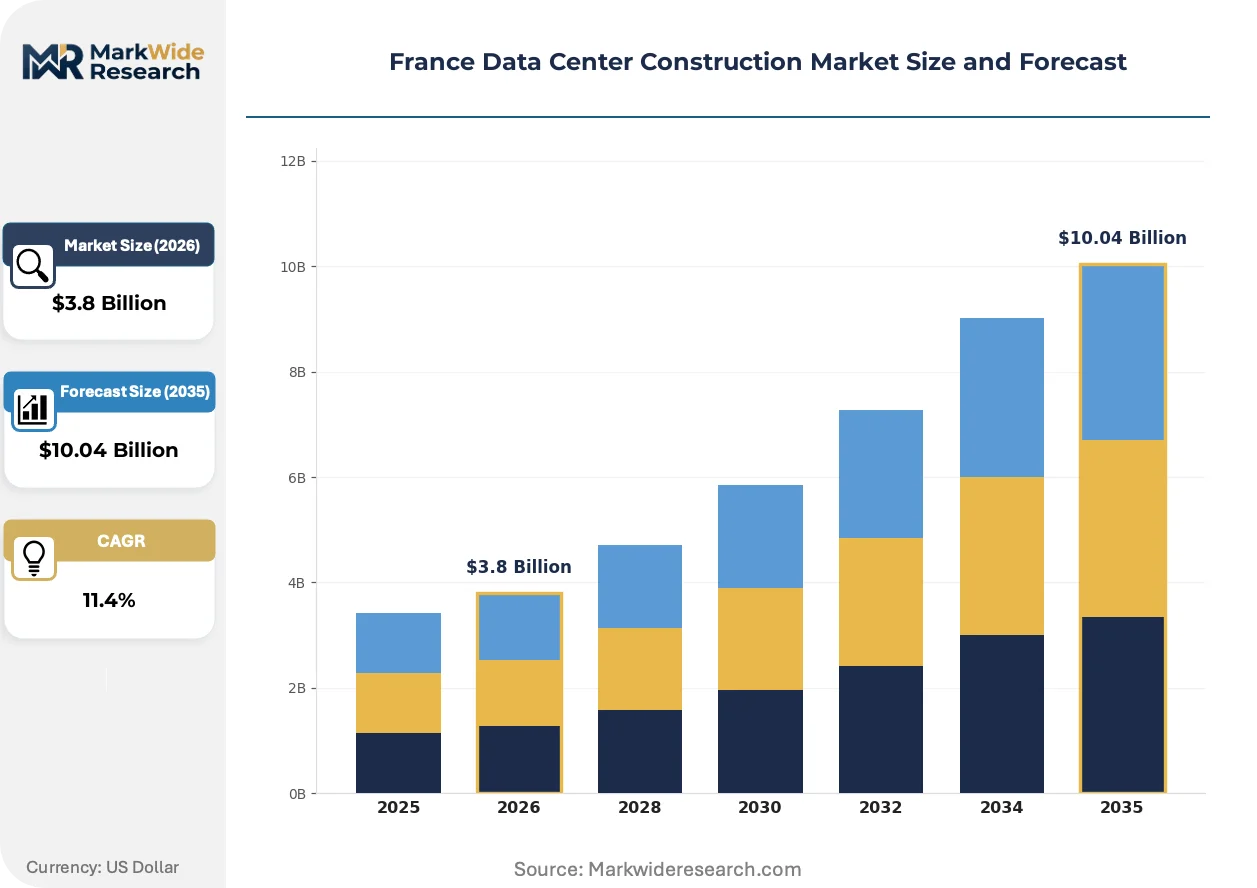
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Construction Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Hyperscale Data Centers, Edge Data Centers, Colocation Centers Technology: Cooling Solutions, Power Infrastructure, Fire Prevention Systems, Security Systems End User: Cloud Service Providers, Enterprises, Government Organizations, Telecommunication Companies Construction Type: New Construction, Retrofit, Expansion, Renovation |
| Companies Covered | Digital Realty, Equinix, DATA4 Group, CloudHQ, CyrusOne, Penta Infra, Telehouse, OPCore, AECOM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Construction Market Trends and Innovations
Liquid cooling infrastructure is reshaping mechanical system specifications as heat densities from AI training clusters exceed traditional air-handling capacity. Engineering firms are retooling their Paris playbooks around thermal management innovations that were marginal five years ago.
Direct-to-chip liquid cooling is supplanting raised-floor air distribution in hyperscale halls housing GPU-intensive workloads. Cloud service providers are specifying immersion and cold-plate systems for new builds exceeding 50kW per rack. This technology is compressing mechanical plant footprints by eliminating perimeter CRAC units and enabling higher ceiling densities.
France's CNIL data sovereignty oversight is hardening physical security specifications for facilities processing sensitive personal data. ANSM cybersecurity compliance layers now mandate biometric access controls and air-gapped monitoring networks for health data hosting contracts. Financial services clients in the La Défense corridor are accelerating compliance investments ahead of anticipated EU AI Act infrastructure requirements.
Build-to-suit development models are displacing speculative construction as cloud tenants demand bespoke power densities and fiber diversity commitments before ground-breaking. Colocation providers are absorbing pre-construction design risk to secure ten-year lease anchors. This shift concentrates project initiation authority with hyperscale procurement teams rather than developer balance sheets.
France Data Center Construction Market Segmentation
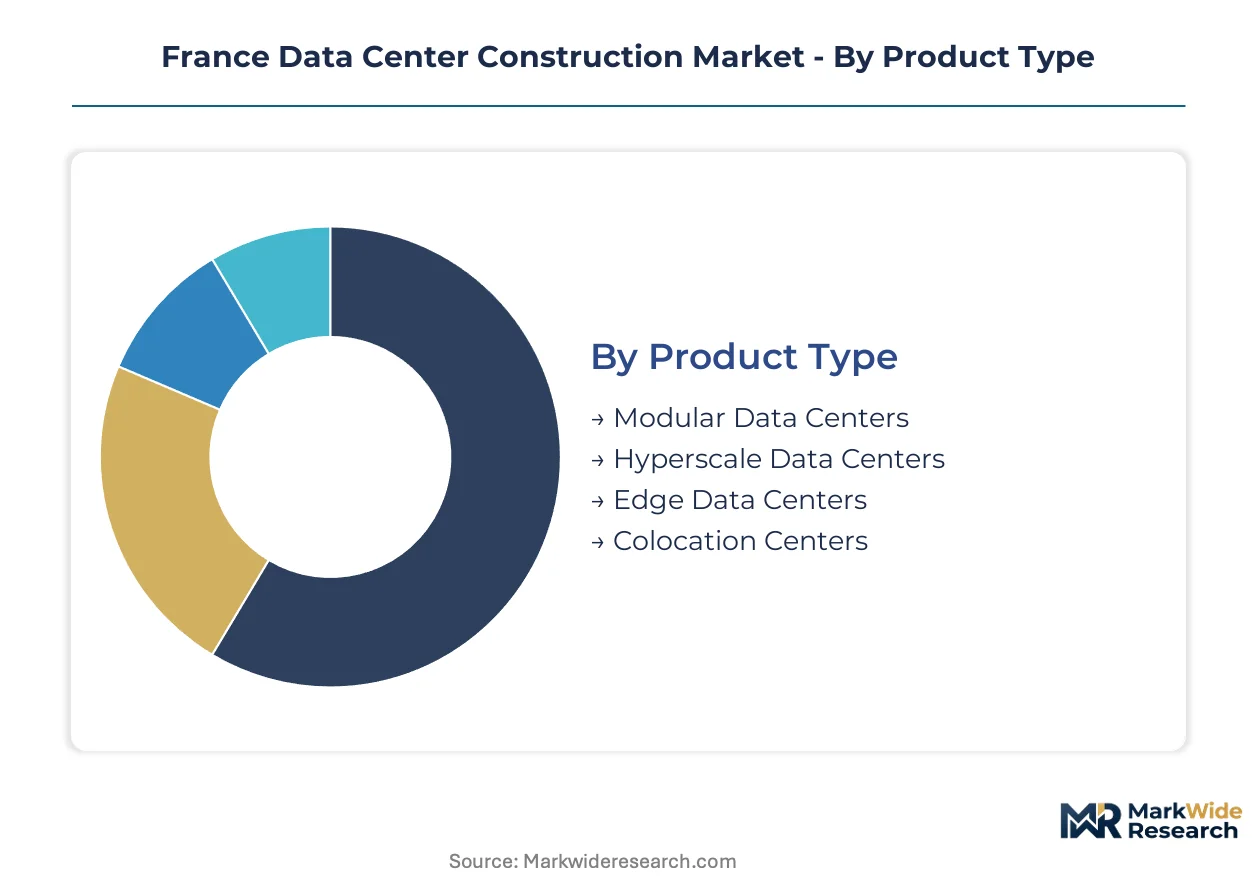
Segmentation in the France data center construction market reveals how capital flows through distinct technical specifications, regulatory compliance layers, and procurement channels. Each dimension shapes contractor qualification requirements and margin structures differently across the Ile-de-France corridor and secondary development zones.
Product Type:
Channel mix varies sharply by scale: hyperscale projects flow through direct engineering-procurement-construction contracts with cloud tenants, while edge and colocation assets distribute through developer balance sheets and institutional capital partners.
- Hyperscale Data Centers:Purpose-built facilities exceeding 15 megawatts with N+1 redundancy and sub-1.3 PUE targets. Demand concentrates in Greater Paris where Amazon Web Services, Microsoft Azure, and Google Cloud are absorbing available grid interconnection capacity ahead of RE2020 compliance deadlines.
- Edge Data Centers:Distributed footprint facilities under 5 megawatts positioned for sub-10 millisecond latency. Expansion is accelerating in Lyon, Marseille, and Lille corridors for autonomous systems and industrial IoT workloads, though per-megawatt civil costs run higher due to remote logistics and smaller scale.
- Modular Data Centers:Factory-built power and cooling modules that compress on-site construction duration. Prefabrication is gaining traction for rapid deployment scenarios where cloud tenants face compressed move-in deadlines.
- Colocation Centers:Multi-tenant facilities with standardized power densities and cross-connect fabrics. Build-to-suit development models are displacing speculative construction as operators absorb pre-construction design risk to secure ten-year lease anchors.
Hyperscale Data Centers dominate installed base. Edge Data Centers are where expansion concentrates most steeply.
Technology:
Cost tier stratification separates premium liquid-cooling mechanical systems from standardized air-handling units, with security and fire systems occupying mid-tier procurement budgets.
- Cooling Solutions:Direct-to-chip liquid cooling and immersion systems for GPU-intensive AI training clusters exceeding 50kW per rack. Mechanical plant footprints compress as perimeter CRAC units eliminate, enabling higher ceiling densities in Paris campus developments.
- Power Infrastructure:Busbar distribution, switchgear, and transformer systems with nuclear baseload integration. Copper and electrical steel volatility compresses fixed-price contract margins for electrical contractors bidding hyperscale tenders.
- Fire Prevention Systems:Clean agent suppression and early warning smoke detection mandated by insurer requirements and local safety codes.
- Security Systems:Biometric access controls and air-gapped monitoring networks hardened by CNIL data sovereignty oversight and ANSM cybersecurity compliance for health data hosting contracts.
Power Infrastructure commands the largest share of capital expenditure. Cooling Solutions is where technology substitution is accelerating fastest.
End User:
Customer type determines procurement rhythm: cloud service providers drive continuous pipeline activity, while enterprise and government demand pulses with budget cycles and tender schedules.
- Cloud Service Providers:Hyperscale operators specifying bespoke power densities and fiber diversity commitments before ground-breaking. Procurement teams now initiate projects rather than developer balance sheets, concentrating authority with Amazon Web Services, Microsoft Azure, and Google Cloud infrastructure groups.
- Telecommunication Companies:Orange, Free, and Bouygues Telecom deploying edge assets for 5G core network functions and content delivery. Latency requirements push distributed presence beyond the Ile-de-France core into secondary corridors.
- Enterprises:Financial services clients in La Défense corridor accelerating compliance investments ahead of anticipated EU AI Act infrastructure requirements.
- Government Organizations:Public-sector tenders filtering qualified engineering firms through ISO 50001 energy management certification and RE2020 thermal performance disclosure mandates.
Cloud Service Providers dominate current construction volume. Government Organizations are where qualification barriers are tightening most aggressively.
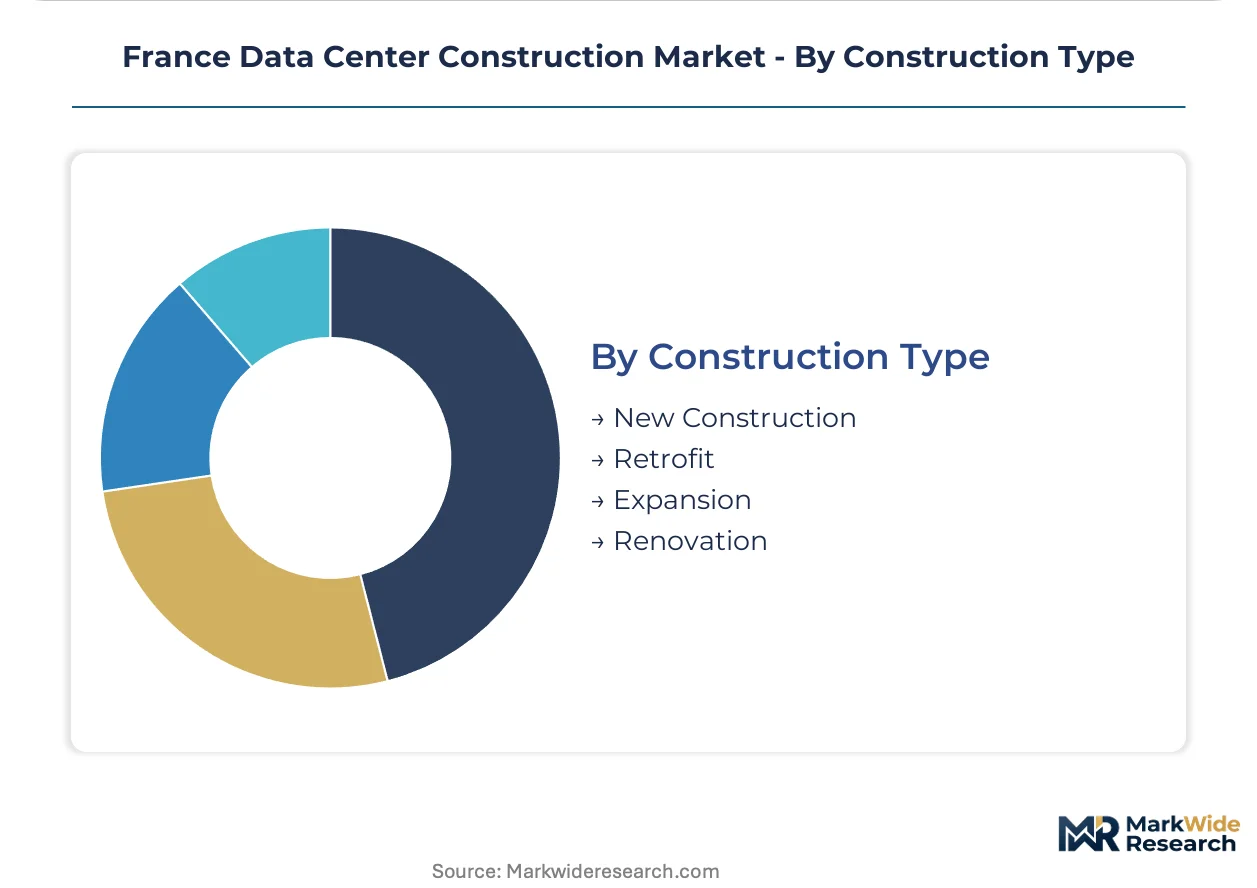
Construction Type:
Margin structure varies by maturity: new construction commands premium engineering fees, while retrofit and renovation compete on cost efficiency and speed.
- New Construction:Greenfield hyperscale builds facing severe land scarcity constraints in Ile-de-France as available parcels near adequate grid interconnection exhaust. Projects push to secondary corridors with inferior fiber latency profiles.
- Expansion:Campus additions leveraging existing substations and fiber meet-me rooms. Digital Realty and DATA4 Group repeat engineering playbooks across Paris developments to sustain delivery velocity.
- Retrofit:Mechanical system upgrades integrating liquid cooling into legacy air-handling facilities. Engineering firms retool specifications around thermal management innovations that were marginal five years ago.
- Renovation:Structural and electrical refresh of aging facilities to meet current PUE and redundancy standards.
New Construction holds the largest project pipeline. Expansion is where repeatability advantages concentrate for established contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's high-voltage transmission grid and submarine cable landing stations at Marseille anchor its data center geography. These infrastructure assets channel investment toward two distinct development corridors with divergent power and connectivity profiles.
Île-de-France
Greater Paris absorbs the majority of hyperscale cloud demand from Amazon Web Services, Microsoft Azure, and Google Cloud. RE2020 building codes and ANSM cybersecurity mandates filter qualified engineering firms into premium tender pools for facilities requiring sub-1.3 PUE targets. Land scarcity near adequate RTE grid interconnection is pushing projects to peripheral zones in Seine-et-Marne and Essonne with inferior fiber latency profiles.
Provence-Alpes-Côte d'Azur
Marseille's position as the Mediterranean hub for transcontinental submarine cables creates latency-arbitrage opportunities for African and Middle Eastern market access. Edge computing deployments for autonomous systems and industrial IoT are accelerating across the Aix-Marseille-Provence metropolis. CNIL data sovereignty oversight hardens physical security specifications for facilities processing cross-border personal data flows.
Auvergne-Rhône-Alpes
Lyon's strategic location between Paris and Marseille corridors supports distributed cloud infrastructure for latency-sensitive financial services and manufacturing workloads. The region's hydroelectric capacity from EDF's alpine generation assets offers carbon-free power advantages for green financing eligibility. Engineering firms are adapting Paris campus playbooks to secondary market construction with compressed delivery timelines.
Hauts-de-France
The Lille metropolitan area is emerging as a northern edge node for low-latency connectivity to London and Benelux markets. 5G core network functions from Orange and Bouygues Telecom are driving smaller-footprint facility construction with higher per-megawatt civil costs due to remote logistics. ISO 50001 certification bottlenecks are delaying contractor qualification for public-sector tenders in this corridor.
France Data Center Construction Market Competitive Landscape
Listed leaders compete with private specialists across capital deployment and delivery velocity. The market structure concentrates around three tiers: global colocation platforms with European engineering playbooks, regional developers with in-house design-build capabilities, and specialized contractors competing on ISO 50001 qualification and liquid cooling expertise. Strategic moves center on build-to-suit pre-construction risk absorption and modular prefabrication partnerships that compress on-site duration.
Among global platform operators, Digital Realty and Equinix exemplify contrasting positioning archetypes—repeatable campus development versus interconnection density differentiation. DATA4 Group anchors the regional specialist tier with integrated design-build capabilities. These three entities represent the dominant competitive vectors shaping tender dynamics across the Ile-de-France corridor and secondary development zones.
| Leading Market Players |
|---|
| Digital Realty |
| Equinix |
| DATA4 Group |
| CloudHQ |
| CyrusOne |
| Penta Infra |
| Telehouse |
| OPCore |
| AECOM |
| Others |
Pricing and Supply Chain Analysis
Long-term engineering-procurement-construction contracts lock in copper busbar and electrical steel supply access while fixing mechanical plant pricing visibility for hyperscale cloud tenants facing RE2020 compliance deadlines. This contract structure concentrates procurement leverage with Amazon Web Services, Microsoft Azure, and Google Cloud infrastructure teams who sequence pipeline commitments against RTE grid interconnection queues.
Pricing Analysis
Volume-discount tiering structures separate hyperscale direct EPC contracts from colocation developer balance sheets and edge facility institutional capital partnerships. Price differentiation rests on ISO 50001 certification status and liquid cooling technical capability, with premium engineering firms commanding 15-20% fee spreads over uncertified competitors. Cost compression in electrical contracting is intensifying because copper and electrical steel commodity volatility erodes fixed-price margin buffers. Cloud service providers exhibit lowest price sensitivity due to ten-year lease anchors, while edge computing developers face acute capital efficiency pressure from higher per-megawatt civil costs in remote corridors.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing hubs through Marseille and Le Havre ports constrain transformer and switchgear delivery schedules for Paris campus developments. Supply concentration centers on Germany for precision mechanical components, China for electrical steel and copper processing, and South Korea for advanced cooling system fabrication. Raw material dependencies span copper ore, electrical-grade steel laminations, and specialized refrigerants for liquid cooling infrastructure. Single-source vulnerability in semiconductor-controlled power electronics creates qualification bottlenecks for contractors bidding ANSM cybersecurity-mandated facilities. Distribution runs through direct manufacturer-to-site logistics for hyperscale projects, with modular prefabrication compressing on-site assembly duration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's data center construction market is approaching a platform-economics inflection where interconnection density and energy management certification become the interoperable currencies for tenant retention and financing access.
For Market Incumbents: Fortify campus development repeatability by embedding liquid cooling retrofit capabilities into Paris engineering playbooks before AI training cluster demand accelerates. Absorb pre-construction design risk through build-to-suit commitments that lock in ten-year lease anchors against emerging modular prefabrication specialists. Vertical integration into in-house electrical contracting mitigates copper price volatility exposure. For New Entrants and Emerging Players: Differentiate on Marseille submarine cable latency arbitrage for African and Middle Eastern market access, where transcontinental fiber landing points remain underdeveloped relative to Paris corridor saturation. Target edge computing deployments in Lyon and Lille corridors where 5G core network functions and industrial IoT workloads outpace established contractor capacity. Lead with rapid modular deployment timelines that compress move-in deadlines for cloud tenants facing RE2020 compliance windows. For Investors and Strategic Acquirers: Capital is best deployed toward engineering firms with ISO 50001 certification and proven liquid cooling integration track records, as these capabilities filter tender qualification for public-sector and hyperscale private contracts. Long-term viability hinges on positioning for nuclear baseload carbon advantage monetization through green bond eligibility. Watch RTE transmission upgrade queue alignment as the signal for project pipeline acceleration or stranded capacity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Partnership | Factory-built power modules slash on-site construction duration for cloud tenants facing compressed RE2020 deadlines. |
| Liquid Cooling Infrastructure Investment | Direct-to-chip thermal systems capture GPU-intensive AI training cluster demand exceeding 50kW per rack specifications. |
| ISO 50001 Certification Program | Energy management documentation qualifies contractors for premium tender pools in public-sector hyperscale procurement. |
| Marseille Cable Landing Expansion | Transcontinental fiber hub positioning unlocks latency-arbitrage facilities serving African and Middle Eastern markets. |
| Build-to-Suit Risk Absorption | Pre-construction design commitments secure ten-year lease anchors from Amazon Web Services, Microsoft Azure, and Google Cloud. |
Research Methodology
Initial hypotheses were tested against primary input from data center engineering directors, EPC contractor procurement leads, cloud tenant infrastructure planners, and RTE grid interconnection officers, then refined through secondary validation against SEC hyperscaler capex disclosures, EDF nuclear generation schedules, ANSM cybersecurity compliance filings, and RE2020 thermal performance databases. Bottom-up project pipeline aggregation across Ile-de-France, Provence-Alpes-Côte d'Azur, Auvergne-Rhône-Alpes, and Hauts-de-France corridors was triangulated with top-down capital deployment estimates from institutional investor filings.
Variance-decomposition across the projection horizon isolates growth contributions from hyperscale cloud expansion, edge computing latency requirements, and modular prefabrication adoption. Segmentation dimensions span facility scale tier, cooling technology type, end-user procurement rhythm, and construction delivery model. CAGRs derive from installed base evolution and pipeline conversion rates, with nuclear baseload availability and copper commodity trajectories as sensitivity inputs.
Forecasts assume regulatory continuity in France's RE2020 building code, EU Energy Efficiency Directive implementation, and CNIL data sovereignty enforcement; material policy shifts in PUE thresholds or cybersecurity physical specifications would require re-modeling. Recalibration cycles align with material shifts in RTE transmission upgrade schedules, EDF reactor maintenance programs, and hyperscale cloud procurement team authority concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Rugged Servers Market