
 Italy Data Center Rack Market | 2026-2036
Italy Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Rack Market Insights
Italy is reconfiguring its data center infrastructure map as Milan's Lombardy corridor attracts hyperscale investments from cloud operators and colocation specialists. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale rack deployments across northern Italy. Rittal GmbH & Co. KG sustains manufacturing proximity advantages through its German-Italian supply chain network. Vertiv Group Corp. differentiates on thermal management integration within high-density rack enclosures.
Data center racks are standardized structural frames designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA width specifications and supporting static loads from 1,000 to 3,000 pounds per cabinet. These enclosures organize cable routing, enable airflow management, and provide physical security for mission-critical IT hardware operating in controlled environments. Enclosed racks command premium positioning due to integrated cooling channels and electromagnetic shielding requirements from financial services clients. Edge data center deployments represent the fastest-growing deployment category as telecom providers push compute closer to population centers. Wall-mount racks occupy a mature niche serving branch offices and industrial control rooms where floor space constraints dominate procurement criteria.
Italy's AgID (Agenzia per l'Italia Digitale) mandates public-sector data residency and security certifications that shape rack-level access control and audit trail specifications. CE marking under EU machinery directives governs structural load ratings and electrical safety for rack systems deployed across Italian facilities. BIS-equivalent conformity assessments for telecommunications infrastructure ensure interoperability with national broadband expansion programs. Stakeholders must monitor how Italy's transposition of EU energy efficiency regulations into building codes for data centers will alter cooling-integrated rack specifications and power density thresholds.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles across Italy's data center rack market, forcing manufacturers to reconfigure supply chains around Milan's fiber corridor while AgID mandates reshape security specifications at the enclosure level.
Growth Catalysts
- PNRR Digital Infrastructure Allocation:Italy's National Recovery and Resilience Plan directs public capital toward data center modernization, creating rack procurement pipelines for government cloud facilities.
- Hyperscale Clustering in Lombardy:Cloud providers concentrate rack deployments around Milan's interconnection hubs, generating density economies that attract secondary colocation investment.
- Edge Computing Rollout:Telecom operators deploy wall-mount and compact rack systems in provincial population centers to reduce latency for industrial IoT and autonomous systems.
Market Restraints
- Steel and Aluminum Input Volatility:Rack enclosure manufacturing depends on commodity metal pricing subject to EU carbon border adjustment mechanisms and energy-intensive production cost swings.
- German Supply Chain Concentration:Critical power distribution and cooling components route through Rhine-Ruhr manufacturing clusters, exposing Italian integrators to cross-border logistics friction.
- CE Marking Complexity:EU machinery directive compliance for integrated cooling and power systems extends certification timelines beyond standard enclosure approvals.
Strategic Opportunities
- Southern Italy Underpenetration:Campania and Sicily lack hyperscale presence, creating first-mover positioning for edge-focused rack configurations serving latency-sensitive applications.
- Liquid Cooling Convergence:Direct-to-chip thermal management integration with high-density rack enclosures addresses power density thresholds exceeding 30kW per cabinet.
- AgID Security Certification Fast-Track:Pre-certified rack access control and audit trail modules capture public-sector procurement where data residency mandates apply.
Industry Challenges
- Thermal Engineering Talent Scarcity:Integrated cooling-electrical rack design requires cross-functional expertise in short supply across Italian technical institutes.
- Legacy Facility Retrofit Complexity:Aging Milan colocation sites impose spatial constraints on modern aisle-containment rack dimensions and power feed configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Rack Market |
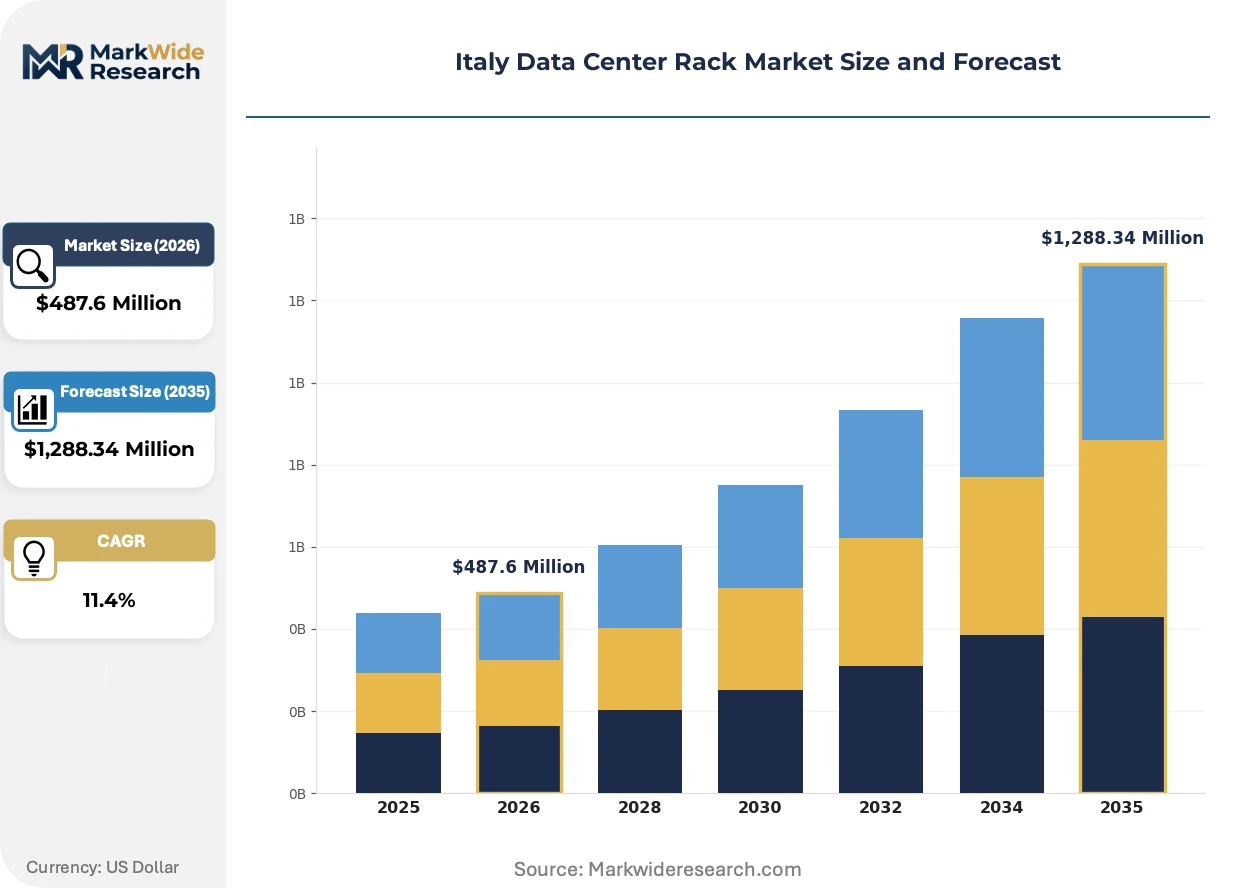
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mount Racks, Compact Racks End User: IT Services, Telecom Providers, Government Agencies, Cloud Providers Deployment: On-Premises, Colocated Facilities, Edge Data Centers, Hybrid Solutions Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Eaton Corporation, Black Box Corporation, Rittal GmbH & Co. KG, Schneider Electric SE, Vertiv Group Corp., Hewlett Packard Enterprise, Dell Technologies, Tecnosteel S.r.l., ITRack S.r.l., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Rack Market Trends and Innovations
Modular thermal architecture is displacing fixed-configuration rack designs across Italian facilities, with manufacturers racing to integrate liquid cooling manifolds and intelligent power distribution before efficiency regulations tighten.
Direct liquid cooling manifolds embedded at the rack level circulate coolant to server cold plates, eliminating dependency on perimeter CRAC units. Hyperscale operators in Milan's Lombardy corridor are specifying these systems for AI training clusters exceeding 50kW per cabinet. Conventional air-cooled aisle containment is rendering obsolete for high-density deployments where heat rejection requirements exceed mechanical infrastructure capacity.
Italy's transposition of EU energy efficiency directives into national building codes for data centers mandates PUE reporting and cooling efficiency thresholds. Rack-integrated metering and environmental sensors become compliance infrastructure rather than operational luxuries. Financial services colocation providers in Rome face the steepest retrofit obligations under AgID security overlays combined with energy performance mandates.
Hyperscale operators now specify rack systems through direct manufacturer engagement, bypassing traditional distribution channels for large-scale deployments. Systems integrators and value-added resellers lose volume to factory-direct procurement above 500-unit thresholds. This channel compression concentrates in northern Italy where cloud provider procurement teams maintain local technical staff for specification oversight.
Italy Data Center Rack Market Segmentation
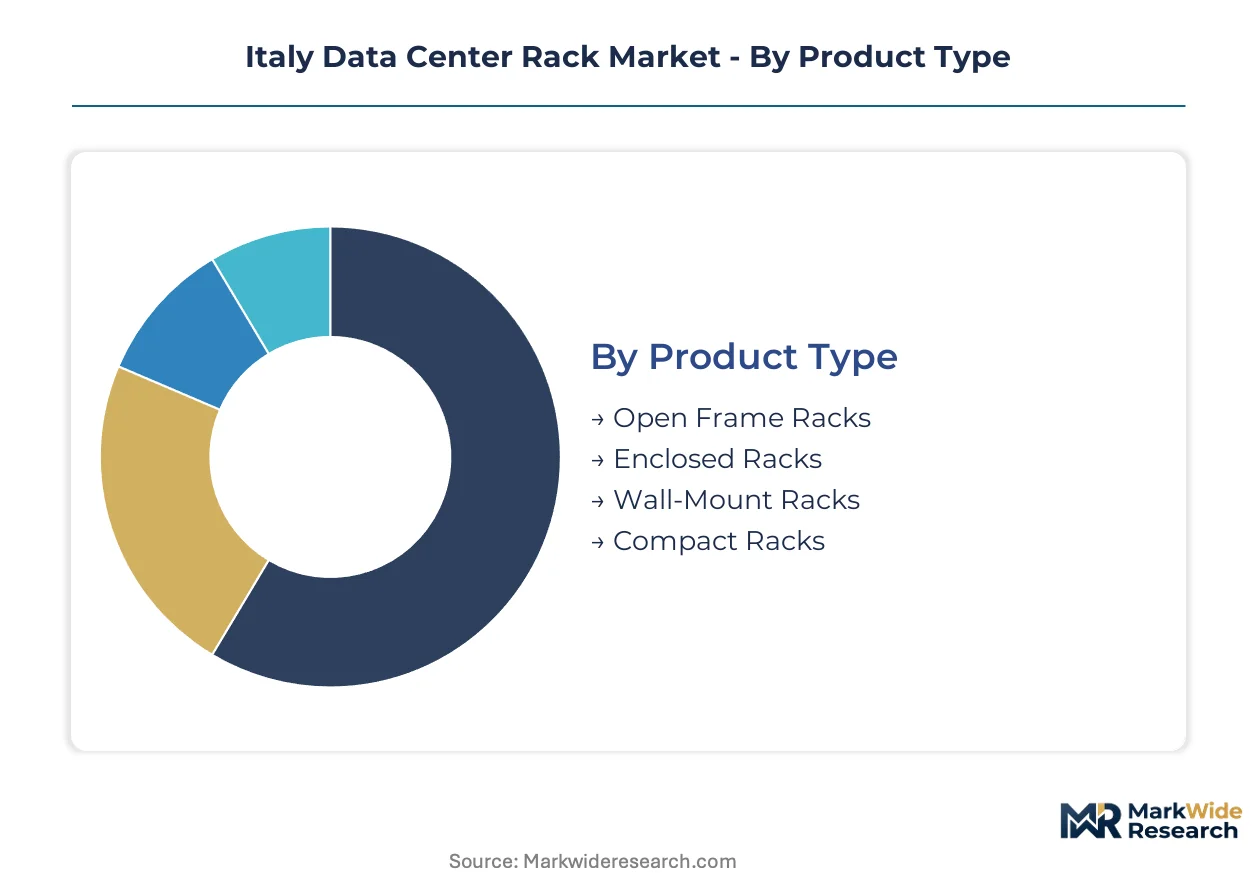
Segmentation in Italy's data center rack market reveals divergent service intensity requirements across enclosure types and deployment contexts. Rack configuration choices directly determine maintenance protocols, spare parts stocking, and field engineering coverage models throughout Lombardy's hyperscale corridor and southern Italy's emerging edge nodes.
Product Type:
After-sales service intensity varies dramatically by enclosure architecture, with integrated cooling and power systems demanding specialized technical response capabilities that pure structural frames do not require.
- Enclosed Racks:These fully enclosed cabinets incorporate integrated cable management, electromagnetic shielding, and climate control channels. Financial services colocation providers in Milan specify these for AgID-mandated audit trail compliance, driving premium service contracts for access control module replacement and environmental sensor calibration.
- Open Frame Racks:Four-post structural frames without side panels or doors optimize airflow for standard density deployments below 15kW per cabinet. Hyperscale operators in Lombardy deploy these for cost-sensitive storage tier infrastructure where thermal margins permit passive cooling designs.
- Wall-Mount Racks:Compact enclosures designed for vertical installation in constrained spaces serve telecom edge sites across Campania and Sicily.
- Compact Racks:Reduced-depth cabinets accommodate shallow equipment footprints in retrofitted Milan colocation facilities with legacy spatial constraints.
By volume, Open Frame Racks leads. By growth pace, Enclosed Racks is ahead.
End User:
Procurement sophistication and lifecycle service expectations diverge sharply across customer categories, with public-sector mandates imposing certification burdens that commercial buyers avoid.
- Cloud Providers:Hyperscale operators in Milan's fiber corridor procure through direct manufacturer engagement above 500-unit thresholds, bypassing distribution channels and negotiating factory-embedded commissioning support. Their rack specifications drive liquid cooling integration and intelligent power distribution adoption.
- Government Agencies:AgID-mandated data residency requirements and security certifications shape access control and audit trail specifications at the enclosure level. Public cloud facilities under Italy's PNRR allocate capital toward pre-certified rack systems with documented chain-of-custody protocols.
- IT Services:Systems integrators serving mid-market enterprises balance standardization against customization demands, with service revenue tied to multi-vendor interoperability support.
- Telecom Providers:Edge computing rollout across provincial population centers drives demand for compact, wall-mount configurations with remote monitoring capabilities.
Cloud Providers dominates procurement value. Government Agencies shows steepest expansion trajectory under PNRR capital allocation.
Deployment:
Facility ownership structure determines rack specification authority and service contract negotiation leverage, with colocation tenants ceding infrastructure decisions to operator standards.
- Colocated Facilities:Multi-tenant datacenter operators in Lombardy standardize rack footprints to maximize floor plate efficiency, limiting tenant customization while offering managed power and cross-connect services. These facilities concentrate Italy's hyperscale rack deployments.
- Edge Data Centers:Telecom-operated micro facilities in southern Italy's underpenetrated markets deploy compact and wall-mount racks for latency-sensitive industrial IoT applications, with service models emphasizing remote diagnostics over on-site engineering.
- On-Premises:Enterprise-owned facilities in Rome's financial services cluster face AgID security overlays combined with energy performance mandates, driving retrofit demand for metered, sensor-integrated enclosures.
- Hybrid Solutions:Split workloads across owned and colocated infrastructure create rack procurement complexity, with enterprises managing specification divergence between legacy on-premises standards and colocation operator requirements.
Colocated Facilities commands installed base. Edge Data Centers gains share fastest as TIM and Vodafone push compute toward population centers.
Power Rating:
Thermal engineering requirements escalate non-linearly with power density, with ultra-high-density deployments demanding liquid cooling integration that transforms rack from passive enclosure to active thermal management system.
- High Power:Cabinets rated 20-30kW accommodate dense compute configurations with aisle containment and in-row cooling. Milan's AI training clusters specify these for GPU-intensive workloads approaching mechanical infrastructure limits.
- Ultra High Power:Direct-to-chip liquid cooling manifolds embedded at rack level circulate coolant to server cold plates, eliminating perimeter CRAC dependency. Hyperscale operators specify these for cabinets exceeding 50kW, rendering conventional air-cooled designs obsolete for frontier AI deployments.
- Medium Power:Standard 10-20kW configurations serve mainstream enterprise virtualization with traditional hot-aisle containment.
- Low Power:Sub-10kW ratings persist in storage-dense and networking applications where compute thermal load remains modest.
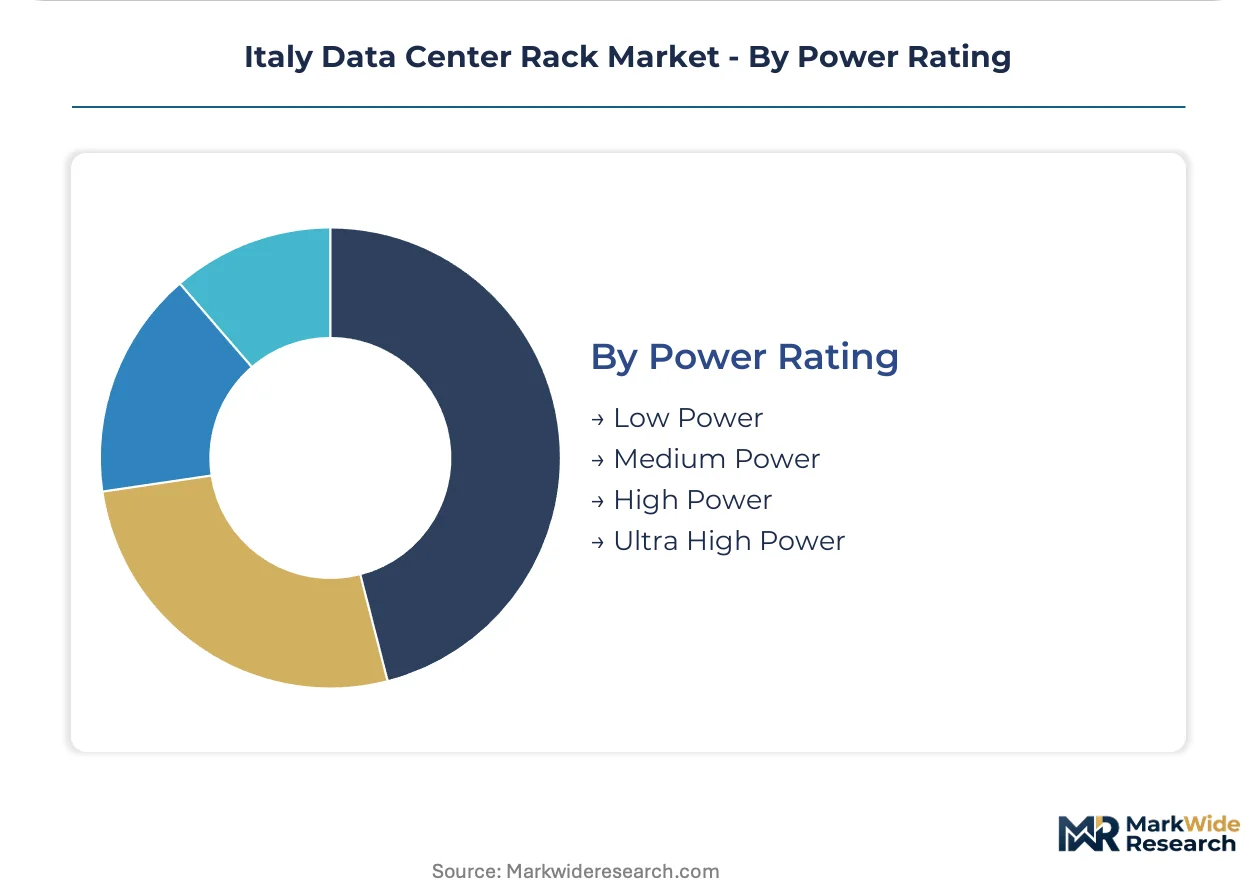
Medium Power leads shipment volume. Ultra High Power posts the steepest growth curve as AI training infrastructure expands across Lombardy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rack manufacturing clusters concentrate in Germany's Rhine-Ruhr corridor and northern Italy's industrial belt, with cross-border component flows shaping procurement economics across European data center buildouts.
Lombardy
Milan's fiber-rich corridor attracts hyperscale cloud operators compressing rack procurement cycles for AI training infrastructure. AgID data residency mandates shape security specifications at enclosure level for public cloud facilities. The region hosts Italy's densest concentration of colocation facilities, with rack deployments clustering around interconnection hubs in the metropolitan area.
Piedmont
Turin's automotive-to-tech industrial transition generates edge computing demand for compact rack configurations serving industrial IoT applications. CE marking requirements under EU machinery directives govern structural load ratings for rack systems deployed across regional facilities. The Alpine logistics corridor connects Piedmont fabricators to German component suppliers with reduced transit friction.
Lazio
Rome's financial services cluster faces steep retrofit obligations under combined AgID security overlays and energy performance mandates. Italy's PNRR directs public capital toward government cloud facilities in the capital region, creating certified rack procurement pipelines. Aging colocation sites impose spatial constraints on modern aisle-containment dimensions.
Campania
Naples anchors southern Italy's emerging edge node architecture with telecom-operated micro facilities deploying wall-mount configurations. TIM and Vodafone push compute toward provincial population centers to reduce latency for autonomous systems. Underpenetration relative to northern markets creates first-mover positioning for compact rack specialists.
Sicily
Catania and Palermo lack hyperscale presence, driving demand for remote-monitored edge enclosures rather than high-density cabinets. EU energy efficiency directive transposition into national building codes mandates PUE reporting for new data center construction. Submarine cable landings position the island for future interconnection-driven expansion.
Italy Data Center Rack Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying power distribution and thermal management modules to rack assemblers. The vendor base stratifies across three tiers: multinational electrical conglomerates with integrated portfolios, mid-cap metal fabrication specialists, and regional systems integrators. Two strategic archetypes dominate—full-stack platform vendors bundling power, cooling, and enclosure, and pure-play rack fabricators sourcing electromechanical subsystems. Competitive moves concentrate on factory-direct procurement relationships with hyperscale operators and pre-certification of security modules for public-sector pipelines.
Among Germany-based fabricators, Rittal GmbH & Co. KG exemplifies the integrated electromechanical archetype, leveraging Rhine-Ruhr manufacturing proximity to anchor cross-border supply chains into northern Italy. Schneider Electric SE represents the full-stack platform model, with Vertiv Group Corp. occupying a position emphasizing thermal management integration. Italian specialists including Tecnosteel S.r.l. and ITRack S.r.l. sit within the regional fabrication tier, serving domestic retrofit and edge deployment markets where customization requirements exceed multinational standard product ranges.
| Leading Market Players |
|---|
| Eaton Corporation |
| Black Box Corporation |
| Rittal GmbH & Co. KG |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Tecnosteel S.r.l. |
| ITRack S.r.l. |
| Others |
Pricing and Supply Chain Analysis
EU carbon border adjustment mechanisms on steel and aluminum imports compress margin structures across Italian rack manufacturing tiers while simultaneously forcing supply chain reconfiguration toward lower-carbon sourcing corridors. This regulatory chokepoint widens pricing spreads between CE-marked premium enclosures and uncertified economy alternatives while accelerating German-Italian cross-border logistics investment.
Pricing Analysis
CE marking under EU machinery directives dictates the pricing tier structure across Italian data center rack procurement, separating AgID-certified enclosures with integrated audit trails from standard open-frame configurations. Price differentiation hinges on certification grade for public-sector eligibility and volume scale for hyperscale direct procurement. Cost compression in economy-tier open-frame racks is intensifying because cloud providers consolidate procurement above 500-unit thresholds. Government agencies exhibit lowest price sensitivity due to mandated security specifications, while mid-market IT services buyers face acute budget constraints driving standardization demands.
Supply Chain Analysis
Extended payment terms from Rhine-Ruhr component suppliers now stretch Italian integrators' working capital cycles as steel and aluminum commodity volatility escalates. Manufacturing concentration in Germany, Poland, and northern Italy feeds rack assembly lines with power distribution units and cooling manifolds. Raw material dependencies on galvanized steel, aluminum extrusions, and copper busbars expose margins to EU carbon border levies. Single-source vulnerability concentrates in precision cooling componentry routed through German industrial clusters. Distribution runs through factory-direct channels for hyperscale volumes above 500 units, with regional integrators capturing sub-scale retrofit and edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against modular liquid cooling systems displacing conventional air-cooled rack architectures as AI training clusters exceed 50kW per cabinet thermal thresholds. Substitution pressure from integrated thermal-electrical platforms threatens pure-play enclosure fabricators lacking cooling engineering capabilities.
For Market Incumbents: Pre-empt liquid cooling convergence by acquiring thermal engineering talent or partnering with direct-to-chip manifold specialists before hyperscale operators bypass rack vendors entirely. Anchor factory-direct relationships with Milan-based cloud procurement teams through embedded commissioning support. Certification investment in pre-qualified AgID security modules captures PNRR-funded public cloud pipelines where data residency mandates apply.
For New Entrants and Emerging Players: Southern Italy's Campania and Sicily edge nodes offer first-mover positioning for compact wall-mount configurations serving telecom-operated micro facilities with remote monitoring capabilities. Target latency-sensitive industrial IoT applications in provincial population centers where TIM and Vodafone push compute infrastructure. Pursue white-label manufacturing partnerships with German component suppliers to bypass capital-intensive electromechanical development cycles.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack platform vendors with integrated power-cooling-enclosure portfolios over pure-play metal fabricators. Acquisition targets should demonstrate liquid cooling integration capabilities or AgID pre-certification assets. Long-term viability over the next decade hinges on thermal engineering expertise scarcity. Monitor hyperscale direct procurement announcements as inflection indicators for distributor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration | Direct-to-chip manifold partnerships address AI training clusters exceeding 50kW per cabinet in Lombardy. |
| AgID Pre-Certification | Pre-qualified security modules capture PNRR-funded government cloud procurement pipelines. |
| Southern Edge Expansion | Campania and Sicily micro-facilities target latency-sensitive industrial IoT applications. |
| Factory-Direct Channel | Bypassing distribution above 500-unit thresholds secures hyperscale procurement relationships. |
| Thermal Engineering Acquisition | Cross-functional expertise scarcity in Italian technical institutes drives talent consolidation. |
Research Methodology
Desk research of EU machinery directive filings, AgID procurement databases, and hyperscaler capex disclosures preceded structured interviews with data center engineering directors, colocation facility operators, thermal management specialists, and public-sector IT procurement officers. Primary fieldwork with Milan-based cloud providers and Rome financial services colocation tenants validated secondary estimates of rack deployment volumes and specification trends. Bottom-up triangulation across regional installation data and top-down cross-checks against PNRR capital allocation schedules anchored market sizing.
Assumptions held fixed include CE marking compliance timelines, AgID data residency mandate enforcement, and Rhine-Ruhr supply corridor stability, while steel commodity pricing and hyperscale procurement cycle compression were modeled as variable sensitivities. Segmentation dimensions spanned enclosure architecture, end-user category, deployment ownership structure, and power density tier. CAGRs were derived from installation volume trajectories cross-referenced against efficiency regulation phase-in schedules and AI infrastructure buildout announcements. Thermal engineering labor supply constraints and legacy facility retrofit complexity served as industry-specific forecast modifiers.
Practitioners should monitor EU carbon border adjustment implementation severity and hyperscale direct procurement threshold shifts for early signals of margin structure change. Forecasts reflect documented assumptions regarding PNRR disbursement pacing and German supply chain continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Data Center Equipment Market